
 US Fuel Cell Bikes Market | 2026-2036
US Fuel Cell Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
US Fuel Cell Bikes Market Insights
Carbon fiber frame construction is realigning weight-to-power economics across the US fuel cell bikes landscape. Toyota Motor Corporation leverages its hydrogen fuel cell intellectual property to anchor premium positioning in early-adopter channels. Hyundai Motor competes through sustained R&D intensity on compact fuel cell stack miniaturization. Intelligent Energy Limited specializes in air-cooled fuel cell module design, differentiating its powertrain architecture for two-wheeler applications.
US fuel cell bikes integrate proton exchange membrane fuel cells with onboard hydrogen storage to generate electric propulsion, typically achieving 60-100 miles of range per 700 bar fill. These vehicles serve last-mile logistics and commuter mobility where zero-emission operation and rapid refueling outperform battery-electric alternatives. Pedal assist configurations lead unit shipments due to favorable classification under federal e-bike regulations and broader consumer familiarity with hybrid propulsion. The delivery services end user segment represents the fastest-growing demand pool, as fleet operators prioritize route uptime over purchase price. Above 750Wh battery capacity configurations command margin concentration despite smaller volumes, reflecting the premium attached to extended-range hydrogen-electric architectures.
The Department of Transportation's alternative fuel corridor program directs hydrogen infrastructure investment toward interstate-adjacent depots, shaping fleet operator route planning and purchase timing. California Air Resources Board ZEV mandates and the Inflation Reduction Act's clean hydrogen production credits jointly compress total cost of ownership for commercial adopters. The National Highway Traffic Safety Administration's evolving light electric vehicle standards will determine whether throttle-controlled variants retain roadway access or face reclassification. Stakeholders must monitor state-level hydrogen hub award disbursements and NHTSA rulemaking timelines to calibrate product portfolio and distribution investments.
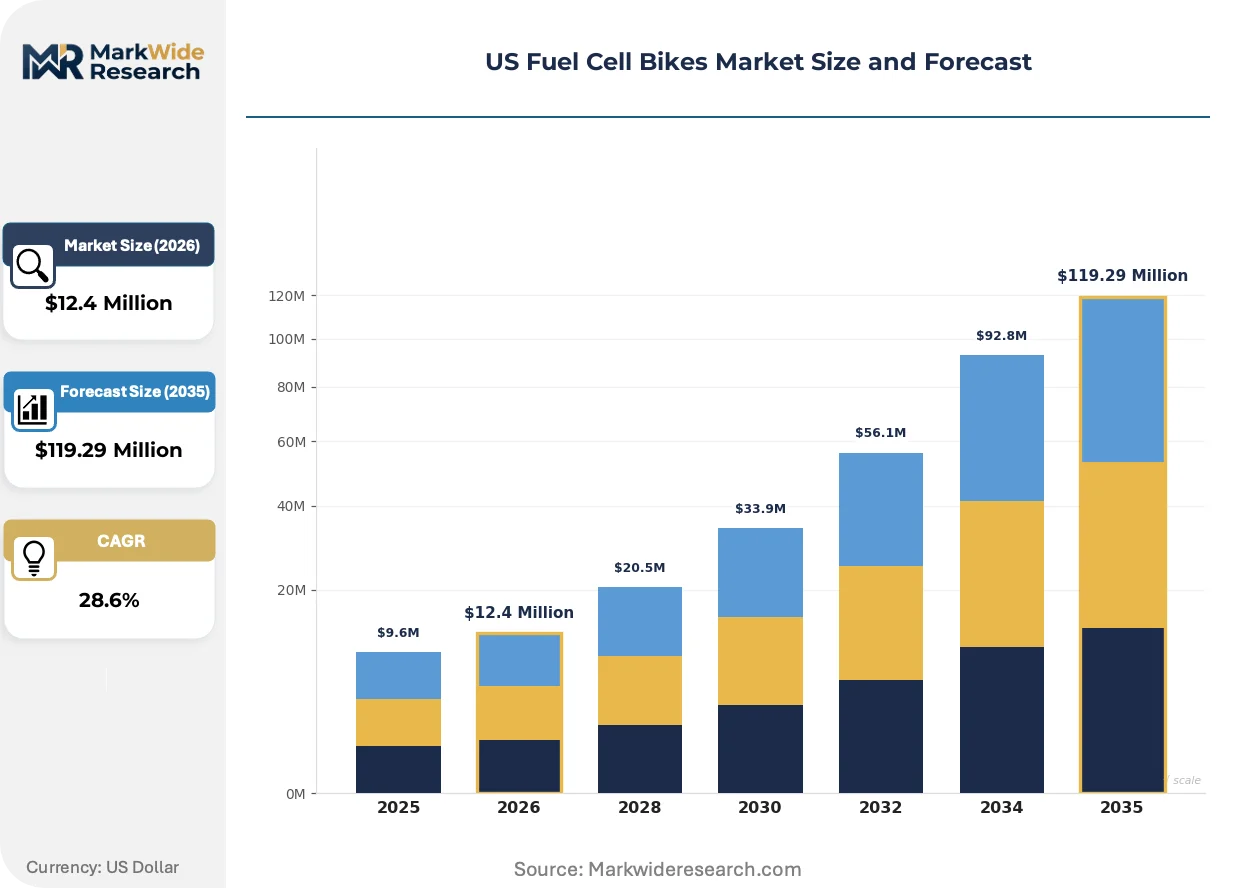
Market Dynamics
California's ZEV program and the Department of Transportation's alternative fuel corridor designations are compressing total cost of ownership for commercial fleet operators while redirecting hydrogen infrastructure investment toward interstate-adjacent depots.
Growth Catalysts
- Inflation Reduction Act clean hydrogen production credits:Federal tax incentives stack with California state rebates, reducing capital outlay for fleet purchasers deploying hydrogen-electric two-wheelers in last-mile logistics.
- Carbon fiber frame construction:Advanced composite materials are cutting powertrain weight ratios, extending range per 700 bar fill and improving vehicle handling characteristics for urban delivery routes.
- Last-mile delivery services:E-commerce fulfillment networks prioritize route uptime and rapid refueling over battery-electric charging downtime, creating pull-through demand from national courier operators.
Market Restraints
- Hydrogen fueling station scarcity:Infrastructure clusters along California coastal metropolitan corridors leave interior and mountain states with refueling deserts, constraining geographic expansion for fleet operators.
- 700 bar compressed hydrogen storage costs:Carbon fiber-wrapped tank manufacturing requires specialized filament winding equipment and aerospace-grade materials, inflating bill-of-materials relative to lithium-ion battery packs.
- Federal e-bike classification ambiguity:National Highway Traffic Safety Administration standards for throttle-controlled variants remain unsettled, creating reclassification risk that deters multi-state fleet standardization.
Strategic Opportunities
- Texas and Arizona hydrogen hub development:Department of Energy regional clean hydrogen hub awards will extend fueling infrastructure into Southwestern interstate corridors, opening new fleet deployment territories beyond California.
- Air-cooled fuel cell module convergence:Integration of Intelligent Energy's compact stack architecture with existing electric bike frame geometries enables faster OEM platform adaptation without liquid cooling complexity.
- Pedal-assist regulatory pathway:Federal e-bike classification under 750W thresholds preserves roadway access and avoids motorcycle licensing requirements, simplifying consumer market entry.
Industry Challenges
- Hydrogen systems engineering talent scarcity:Specialized expertise in high-pressure containment, fuel cell membrane hydration management, and safety system integration remains concentrated among automotive suppliers, constraining bike-specific product development teams.
- California Air Resources Board certification timelines:ZEV compliance testing for novel powertrain configurations extends 18-24 months, delaying revenue recognition for manufacturers launching new platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fuel Cell Bikes Market |
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $119.29 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal Assist, Throttle Controlled, Folding, Cargo End User: Commuters, Recreational Users, Delivery Services, Fleet Operators Battery Capacity: Below 250Wh, 250-500Wh, 500-750Wh, Above 750Wh Sales Channel: Online Retail, Specialty Stores, Direct Sales, Distribution Partners |
| Companies Covered | Honda Motor, Hyundai Motor, Toyota Motor Corporation, Segway Inc., Xiaomi Inc., Kawasaki Heavy Industries, Pragma Industries, Azure Bikes, Intelligent Energy Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fuel Cell Bikes Market Trends and Innovations
Proton exchange membrane fuel cell miniaturization and onboard hydrogen storage advances are redefining powertrain packaging constraints. Fleet procurement criteria increasingly favor rapid refueling architectures over energy density metrics.
Compact fuel cell stack architectures are integrating liquid-cooled and air-cooled thermal management systems into standard bicycle frame triangles. Last-mile logistics operators in California coastal corridors are adopting these configurations fastest, drawn by sub-five-minute refueling cycles. The technology is integrating route planning software with real-time hydrogen station availability data, compressing fleet dispatch optimization timelines.
NHTSA light electric vehicle standards revision is forcing manufacturers to recertify throttle-controlled variants under emerging low-speed vehicle or motorcycle classifications. California fleet operators face uncertainty over access to bicycle lane infrastructure if reclassification proceeds. Commercial buyers are responding by accelerating pedal-assist platform procurement before regulatory thresholds shift.
Fleet procurement departments are consolidating vendor relationships around integrated hydrogen-electric service contracts. Third-party logistics providers are displacing direct equipment purchases with per-mile leasing arrangements that bundle fuel, maintenance, and vehicle replacement. This restructuring is most visible among national courier networks operating across California's hydrogen corridor network.
US Fuel Cell Bikes Market Segmentation
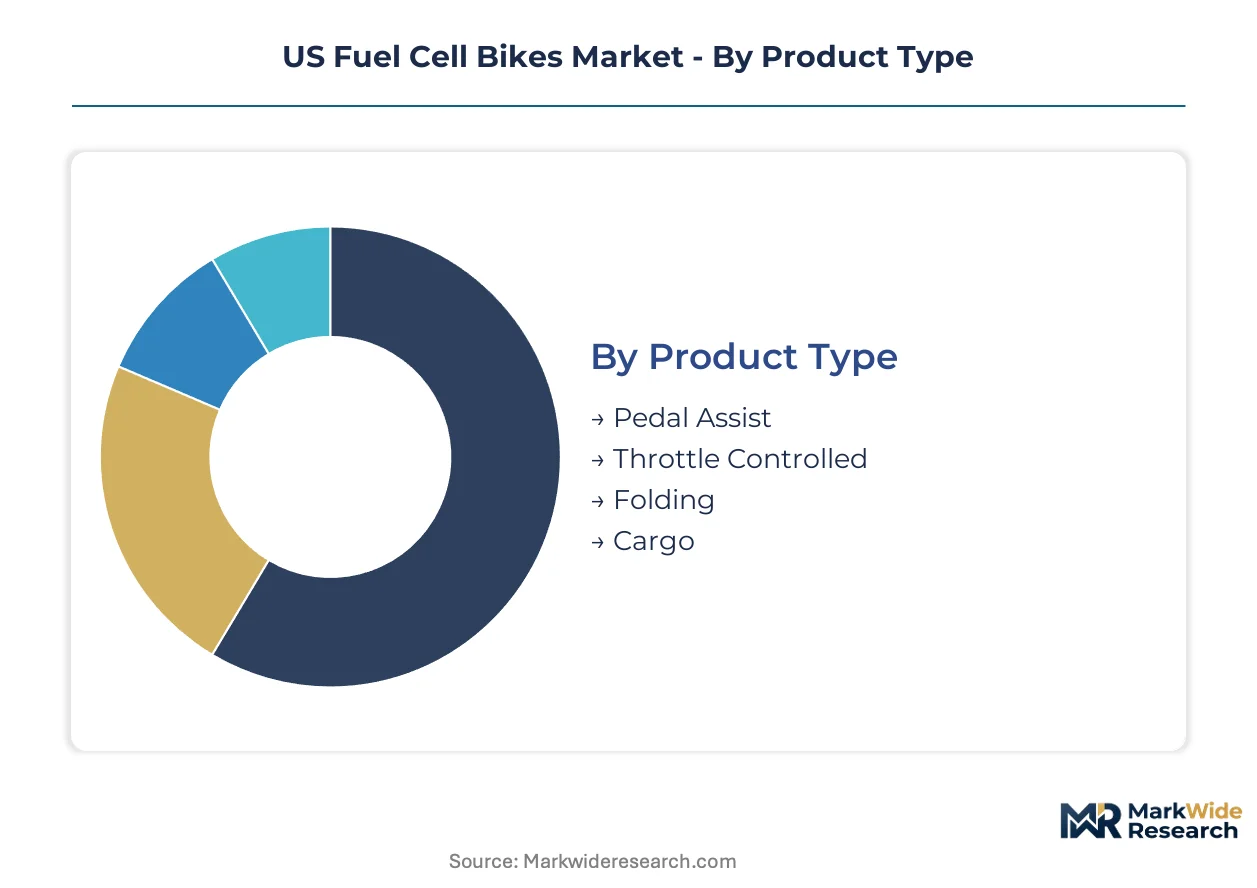
Segmentation in the US fuel cell bikes market reveals divergent engineering priorities between consumer mobility and commercial logistics applications. Product architecture, powertrain sizing, and distribution pathways all bifurcate sharply based on end-use intensity and regulatory classification constraints.
Product Type:
Supply concentration in frame manufacturing and fuel cell stack integration favors platforms that leverage existing bicycle component ecosystems.
- Pedal Assist:Combines human propulsion with hydrogen-electric boost under 750W federal thresholds, preserving bicycle lane access and avoiding motorcycle licensing. California commuter corridors and urban delivery fleets concentrate demand here due to regulatory clarity and infrastructure compatibility.
- Throttle Controlled:Delivers power-on-demand without pedaling requirements, attracting last-mile operators prioritizing route consistency over rider exertion. NHTSA reclassification risk looms as the agency weighs low-speed vehicle standards, compressing procurement timelines among risk-averse fleet managers.
- Folding:Compact frame geometries target multi-modal commuters integrating rail or bus segments with hydrogen-powered cycling.
- Cargo:Extended wheelbases and reinforced frames accommodate commercial payloads for grocery and parcel delivery applications.
Today's leader: Pedal Assist. Tomorrow's challenger: Throttle Controlled.
End User:
Cost tier differentiation separates recreational purchasers focused on acquisition price from commercial buyers optimizing total cost of ownership across depreciation and fuel.
- Delivery Services:National courier networks and regional logistics providers prioritize sub-five-minute refueling cycles over battery-electric charging downtime. California's hydrogen corridor density enables route planning confidence that interior states cannot yet match.
- Fleet Operators:Consolidated procurement departments negotiate integrated service contracts bundling vehicles, hydrogen supply, and maintenance. Per-mile leasing structures are displacing direct capital expenditure across last-mile networks.
- Commuters:Individual purchasers respond to state-level rebates and federal clean vehicle credits, with concentration in coastal metropolitan areas.
- Recreational Users:Early adopters drawn to zero-emission technology and novel propulsion systems, typically in higher-income demographics.
Volume concentrates with Delivery Services. Margin expansion tracks Fleet Operators.
Battery Capacity:
Application intensity dictates powertrain mass and hydrogen storage integration complexity.
- Above 750Wh:Extended-range architectures pair high-capacity buffer batteries with optimized fuel cell output curves, commanding premium positioning among commercial route operators. California fleet procurement criteria increasingly specify this tier for all-day duty cycles without midday refueling.
- 500-750Wh:Balanced configurations serving mixed-use commuters and light commercial applications where weight reduction competes with range assurance.
- 250-500Wh:Compact powertrains prioritizing frame integration simplicity and cost minimization for price-sensitive consumer segments.
- Below 250Wh:Minimal battery buffers suitable for pedal-dominant recreational use with supplemental electric assist.
Commercial specifications cluster above 750Wh. Consumer entry points concentrate below 500Wh.
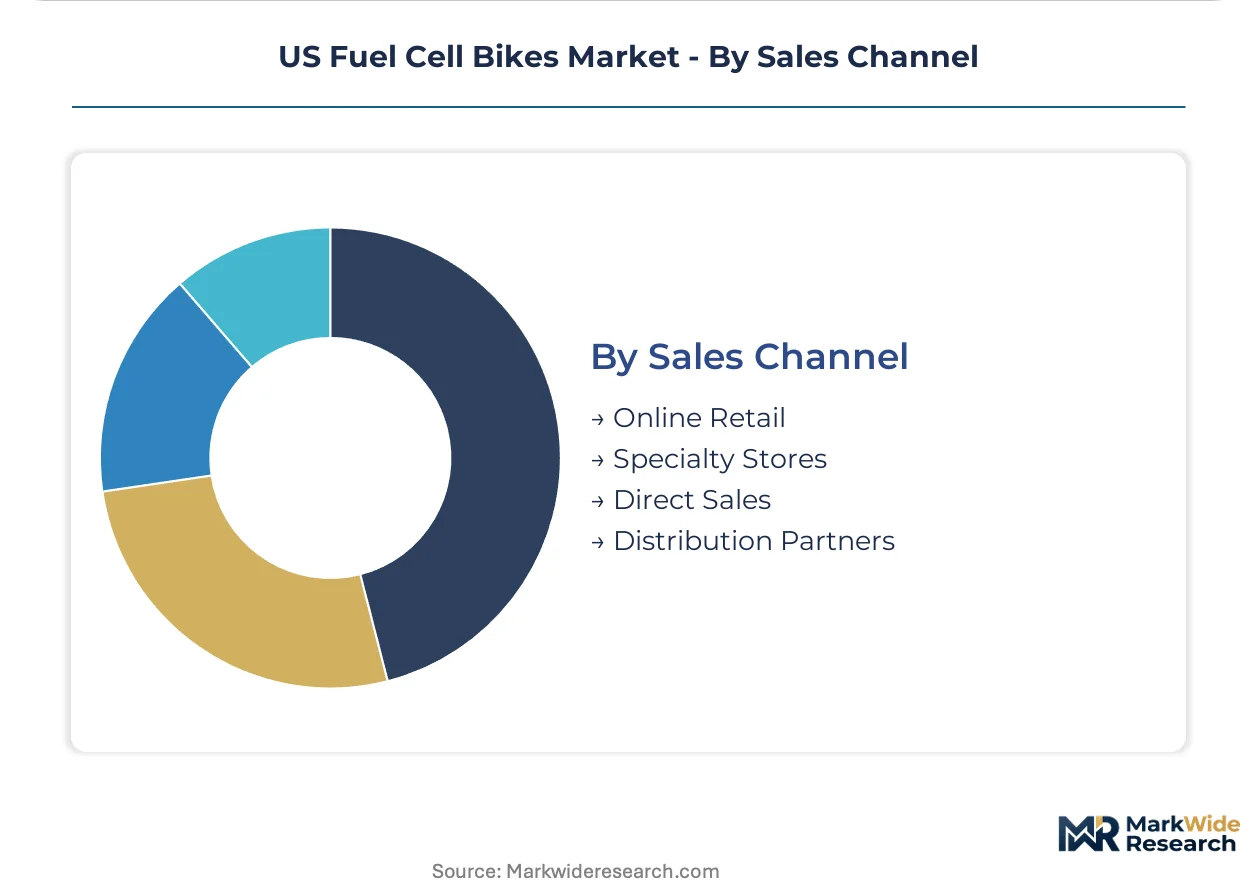
Sales Channel:
Customer type fragmentation drives channel strategy divergence between high-touch commercial relationships and scalable consumer access.
- Direct Sales:Manufacturers cultivate fleet operator relationships through dedicated account teams, offering customized service contracts and hydrogen supply integration. This channel captures the highest lifetime value per customer in the California corridor market.
- Distribution Partners:Regional logistics specialists extend geographic reach into emerging hydrogen hub territories beyond California, Arizona, and Texas.
- Specialty Stores:Local dealers provide test ride access and maintenance support for consumer segments prioritizing hands-on evaluation.
- Online Retail:Direct-to-consumer platforms serve early adopters comfortable with remote specification and self-directed assembly.
Revenue concentration favors Direct Sales. Geographic expansion depends on Distribution Partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's coastal metropolitan corridors anchor hydrogen fuel cell bike deployment through dense hydrogen station clustering and stacked state-federal incentive programs.
California
Los Angeles and San Francisco Bay Area logistics fleets drive commercial adoption through route-optimized depot placement near hydrogen corridors. California Air Resources Board ZEV mandates compress total cost of ownership for delivery operators. The state's hydrogen hub awards channel infrastructure investment toward interstate-adjacent fueling points in Oakland and Long Beach port complexes.
Texas
Dallas-Fort Worth and Houston last-mile networks are emerging as early adopters ahead of Department of Energy regional clean hydrogen hub disbursements. Texas state fleet procurement guidelines increasingly reference zero-emission two-wheeler specifications. Hydrogen infrastructure development concentrates along I-35 and I-10 corridors connecting San Antonio to Austin metro logistics zones.
Arizona
Phoenix metropolitan delivery services test fuel cell bike viability in extreme heat conditions where battery-electric range degrades. Arizona Commerce Authority clean transportation grants offset capital costs for pilot fleet deployments. Tucson and Flagstaff hydrogen station planning aligns with interstate freight corridor expansion timelines.
Pacific Northwest
Seattle and Portland urban mobility programs integrate fuel cell bikes into multi-modal transit networks. Washington State Department of Transportation alternative fuel corridor designations prioritize I-5 hydrogen infrastructure sequencing. Oregon Department of Environmental Quality zero-emission vehicle rebates stack with federal IRA credits for individual purchasers.
Northeast Corridor
New York City and Boston metropolitan areas represent latent demand pending hydrogen infrastructure buildout. State-level clean vehicle incentive programs in Massachusetts and New York await federal hydrogen hub awards to unlock fleet-scale deployment. Newark and Philadelphia logistics operators monitor California regulatory outcomes to time entry decisions.
US Fuel Cell Bikes Market Competitive Landscape
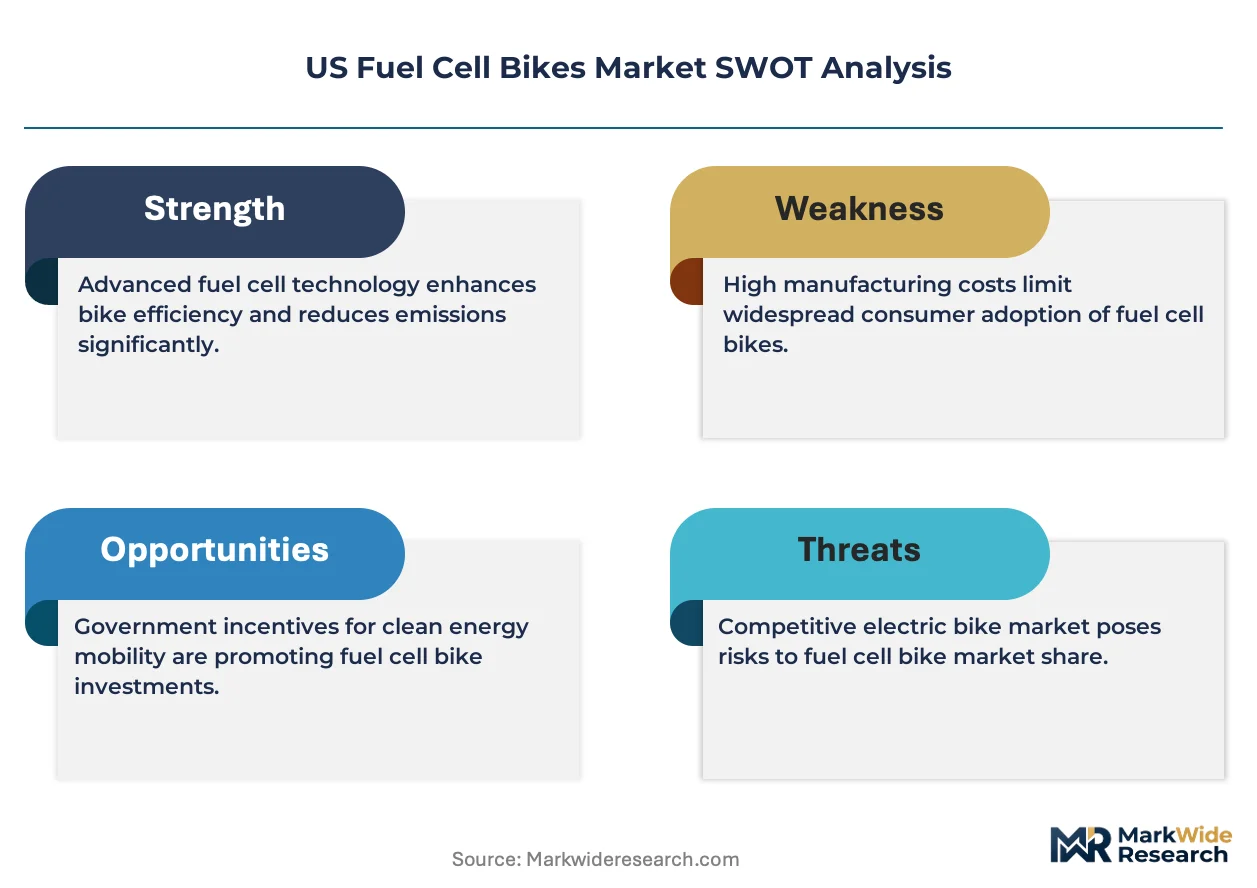
Global automotive majors compete with regional two-wheeler specialists across fuel cell stack miniaturization and frame integration capabilities. Market structure shows tiered concentration with premium positioning held by automotive-derived entrants and mid-market segments served by dedicated bike fabricators. Strategic archetypes include automotive technology licensors, air-cooled fuel cell module specialists, and integrated vehicle-fuel service providers. Dominant competitive moves center on strategic partnerships with hydrogen infrastructure operators and portfolio diversification into integrated leasing arrangements.
Within the automotive technology licensor tier, Toyota Motor Corporation and Hyundai Motor occupy positions leveraging existing hydrogen fuel cell intellectual property portfolios for premium two-wheeler applications. Honda Motor represents the diversified industrial conglomerate archetype with cross-sector fuel cell experience. Among dedicated fuel cell specialists, Intelligent Energy Limited anchors the air-cooled module segment with compact stack architectures purpose-built for bicycle frame integration. Segway Inc. exemplifies the micro-mobility platform specialist extending electric vehicle expertise into hydrogen-electric variants.
| Leading Market Players |
|---|
| Honda Motor |
| Hyundai Motor |
| Toyota Motor Corporation |
| Segway Inc. |
| Xiaomi Inc. |
| Kawasaki Heavy Industries |
| Pragma Industries |
| Azure Bikes |
| Intelligent Energy Limited |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation across fuel cell bike architectures manifests in divergent supply chain footprints, with carbon fiber-wrapped 700 bar tank sourcing anchoring premium tier cost structures while commodity frame fabrication serves volume segments. California fleet operators absorb hydrogen-electric premiums through stacked IRA credits and CARB rebates, compressing effective procurement spreads between tiers.
Pricing Analysis
Input-cost pass-through from aerospace-grade carbon fiber filament and platinum-group catalyst loadings intensifies pricing pressure at the premium tier, where 750Wh-plus configurations absorb material volatility through long-term hydrogen service contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by battery buffer capacity and fuel cell stack thermal management sophistication. Fleet operators negotiating per-mile leasing arrangements exhibit lowest price sensitivity, while individual commuter purchasers in non-incentive states drive economy tier volume. Cost compression in standard configurations stems from air-cooled fuel cell module convergence reducing liquid cooling subsystem complexity.
Supply Chain Analysis
Workforce availability constraints in South Korea and Japan constrain fuel cell stack membrane electrode assembly capacity, pushing manufacturers toward Taiwanese electronics manufacturing services for power electronics integration. Carbon fiber-wrapped pressure vessel fabrication draws from Japanese and German aerospace supplier networks, while frame welding and final assembly concentrate in Mexico and Vietnam. Single-source vulnerability in proton exchange membrane supply from Belgian and US specialty chemical producers threatens production continuity. Distribution runs through direct fleet sales teams in California corridor markets and regional logistics specialists in emerging hydrogen hub territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand architecture, with NHTSA light electric vehicle standards revision representing the pivotal milestone determining throttle-controlled variant roadway access and fleet procurement timing.
For Market Incumbents: Cement hydrogen infrastructure partnerships along Department of Energy regional clean hydrogen hub corridors before Texas and Arizona station networks mature. Secure captive supply of carbon fiber-wrapped pressure vessels through backward integration or long-term offtake agreements to defend margin position against emerging air-cooled stack competitors. Prioritize CARB certification pipeline investment to compress 18-24 month ZEV compliance timelines.
For New Entrants and Emerging Players: Air-cooled fuel cell module miniaturization offers technology-first wedge positioning against liquid-cooled incumbents burdened by thermal management complexity. Target Texas interstate-adjacent logistics depots ahead of hydrogen hub disbursement completion, where fleet operator route planning confidence remains unformed. Pursue pedal-assist platform entry under 750W federal thresholds to bypass NHTSA reclassification uncertainty.
For Investors and Strategic Acquirers: Consolidation pressure builds where air-cooled fuel cell engineering talent concentrates among automotive supplier alumni and dedicated stack specialists. Long-term viability hinges on integrated vehicle-fuel service contract economics displacing direct equipment purchases across national courier networks. Target acquisition archetype: regional two-wheeler fabricators with existing California distribution relationships and unencumbered CARB certification pathways. Watch NHTSA rulemaking publication as inflection signal for throttle-controlled variant market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Infrastructure Partnership | Locks in fleet operator route planning confidence ahead of Texas and Arizona hub completion. |
| Air-Cooled Stack Platform Launch | Accelerates OEM adoption timelines by eliminating liquid cooling subsystem integration complexity. |
| Per-Mile Leasing Structure | Aligns revenue recognition with fleet operator uptime priorities and hydrogen consumption patterns. |
| CARB Certification Fast-Track | Compresses 18-24 month ZEV compliance timelines to capture California fleet procurement windows. |
| Carbon Fiber Vessel Backward Integration | Secures aerospace-grade pressure containment supply against filament winding equipment scarcity. |
Research Methodology
Multiple input streams — fleet operator procurement interviews, fuel cell engineering specialist consultations, and hydrogen infrastructure developer assessments — were reconciled against secondary validation from Department of Energy hydrogen hub award documentation, NHTSA regulatory dockets, and California Air Resources Board certification records. Primary fieldwork engaged platform engineering directors at automotive-derived entrants, supply chain managers at carbon fiber pressure vessel fabricators, and logistics procurement leads at national courier networks. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Cross-referencing historical adoption curves in California hydrogen corridor markets against expert panel input on Texas and Arizona infrastructure buildout timelines anchored the projection framework. Segmentation dimensions modeled include propulsion architecture, battery capacity tier, end-use intensity, and regulatory classification pathway. CAGRs derived from logistic diffusion curve fitting calibrated to fleet operator procurement cycle data and state-level incentive program disbursement schedules. Fuel cell stack cost reduction trajectories and hydrogen station density projections served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHTSA reclassification rulings, Department of Energy hydrogen hub execution delays, and carbon fiber composite supply constraints. Forecasts reflect documented assumptions regarding IRA credit continuity and CARB ZEV mandate stringency trajectories. Material deviation in NHTSA rulemaking publication timing or hydrogen infrastructure capital deployment rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market