
 Germany Solar E-Bike Market | 2026-2036
Germany Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Solar E-Bike Market Insights
Specialty retail networks across southern Germany is fragmenting as direct-to-consumer platforms and brand-owned showrooms capture premium buyers. Riese & Müller GmbH leverages its engineering heritage to dominate high-performance cargo configurations. CUBE Bikes sustains broad portfolio coverage across price tiers through scalable manufacturing in Bavaria. Kalkhoff Werke GmbH anchors its position in urban commuter segments with integrated solar panel rack systems.
A solar e-bike combines photovoltaic cells mounted on frames or accessories with electric pedal-assist drivetrains, typically operating at 250W nominal power with 25 km/h speed cutoff under EU pedelec classification; the solar array extends range by regenerating battery charge during daylight exposure. Commuter e-bikes lead volume due to daily charging predictability among workplace-parked fleets, while cargo e-bikes command margin concentration from commercial buyers seeking diesel replacement in urban logistics. Solid-state battery technology attracts R&D investment for energy density gains that reduce panel surface requirements.
KBA type-approval requirements intersect with EU CE marking and Germany's StVZO road traffic regulations to mandate lighting, braking, and electromagnetic compatibility standards that shape product development cycles. The Federal Ministry for Economic Affairs and Climate Action funds solar mobility pilots through regional development programs, directing procurement preferences toward certified domestic assemblies. Stakeholders must monitor KBA consultation papers on solar auxiliary power classification, as reclassification would reshape insurance and roadway access rules.
Market Dynamics
KBA consultation papers on solar auxiliary power reclassification are reshaping product development timelines and insurance underwriting assumptions across German manufacturers.
Growth Catalysts
- StVZO lighting mandates:Federal road traffic regulations mandate integrated lighting systems that solar arrays now power independently, eliminating separate battery drains for commuter fleets.
- Municipal last-mile logistics:Bavarian city councils are expanding solar-assisted cargo e-bike procurement for parcel delivery networks, creating predictable fleet replacement cycles.
- Perovskite cell efficiency gains:Laboratory breakthroughs in thin-film photovoltaic chemistry are reducing panel surface area requirements without sacrificing charge rates.
Market Restraints
- Lithium-ion cell price volatility:Raw material sourcing constraints for battery cathodes are compressing margin structures for mid-tier assemblers in Saxony.
- CE marking complexity:Electromagnetic compatibility testing under EU directives adds 4-6 month certification delays for frame-integrated solar configurations.
- Conventional pedelec substitution:Standard plug-in e-bikes without solar augmentation retain price advantages that slow consumer conversion in northern Länder with lower insolation.
Strategic Opportunities
- Baden-Württemberg charging corridors:Solar canopy installations along Rhine Valley cycling routes create captive demand for compatible onboard panel systems.
- Federal solar mobility pilots:BMWi regional development programs direct procurement preferences toward certified domestic assemblies with photovoltaic integration.
- Solid-state battery convergence:Higher energy density cells from German automotive suppliers are enabling smaller panel footprints that preserve frame aesthetics.
Industry Challenges
- Photovoltaic integration engineering:Frame stress analysis for panel mounting requires specialized mechanical design talent scarce in traditional bicycle manufacturing regions.
- KBA type-approval timelines:Safety certification for novel solar rack configurations extends product launch windows beyond traditional e-bike development cycles.
- Supply chain reconfiguration:Dual sourcing of photovoltaic cells from Asian suppliers and European assemblers creates inventory coordination complexity for just-in-time production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Solar E-Bike Market |
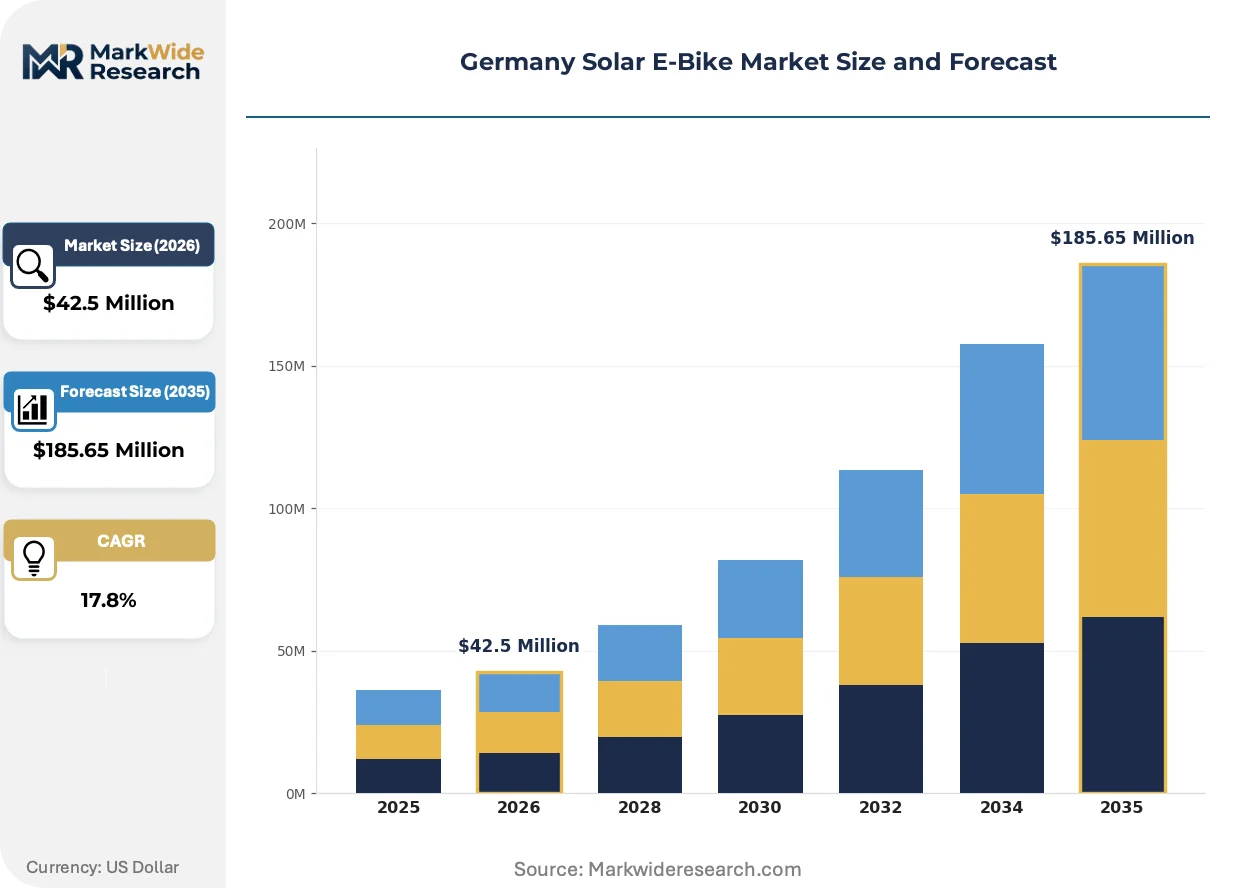
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $185.65 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commuter E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Technology: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Urban Commuters, Recreational Riders, Delivery Services, Fleet Operators |
| Companies Covered | Riese & Müller GmbH, CUBE Bikes, Kalkhoff Werke GmbH, Prophete In Moving GmbH, Winora Staiger GmbH, KTM Fahrrad GmbH, Canyon Bicycles GmbH, Cartrend GmbH, MHW Bike-House GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Solar E-Bike Market Trends and Innovations
Solar e-bike architecture is converging with automotive battery management systems and building-integrated photovoltaics, creating new technical standards that transcend traditional cycling industry boundaries.
Perovskite tandem solar cells are rendering obsolete the rigid silicon panels that previously dominated frame-mounted applications. Urban commuter OEMs in Stuttgart and Munich are adopting flexible thin-film laminates that conform to curved top tubes. This technology compression is rendering obsolete the aftermarket panel accessory market as factory-integrated solutions capture premium positioning.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-based thermal management alternatives in battery enclosures. German assemblers must redesign cooling architectures to maintain cell longevity under solar charging heat loads. Cargo e-bike configurations with extended duty cycles face the steepest engineering adaptation requirements.
Fleet procurement managers in municipal logistics are consolidating vendor relationships around certified service networks rather than product specifications. Direct-to-consumer platforms are losing ground to brand-owned showrooms that offer photovoltaic diagnostic capabilities. This concentration is most visible in Bavaria, where workplace charging infrastructure investments correlate with multi-unit fleet orders.
Germany Solar E-Bike Market Segmentation
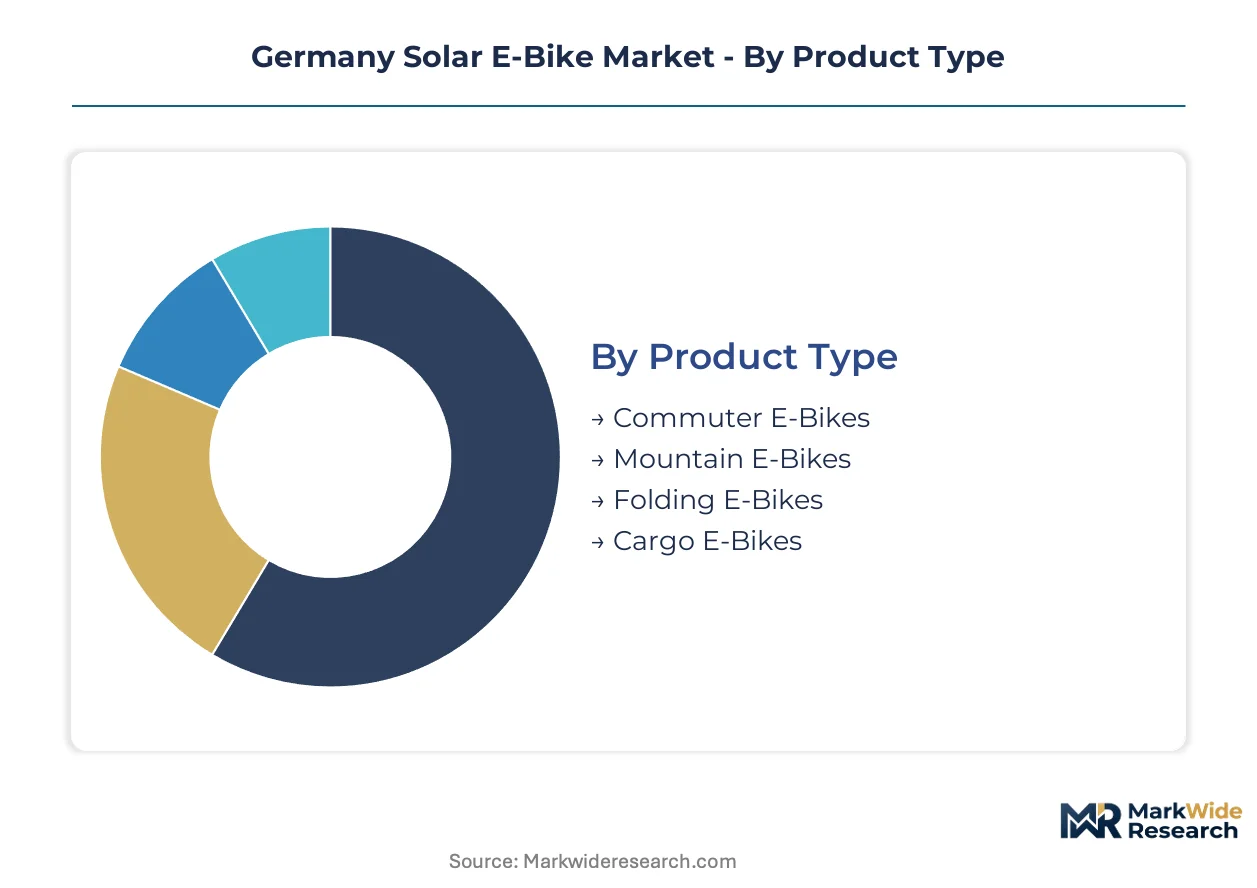
Solar e-bike market segmentation reveals how photovoltaic integration reshapes purchasing patterns across mobility use cases. Product architecture and battery chemistry create distinct performance tiers that align with specific rider profiles and charging infrastructure access.
Product Type:
Mature commuter configurations dominate volume, while emerging cargo formats capture commercial fleet investment.
- Commuter E-Bikes:Frame-integrated solar panels extend daily range for workplace-parked fleets across Bavarian cycling corridors. Urban commuters in Stuttgart and Munich generate predictable demand through employer-subsidized procurement programs.
- Cargo E-Bikes:Extended wheelbase designs accommodate larger photovoltaic arrays for last-mile logistics operators. Baden-Württemberg municipal parcel contracts are standardizing solar-assisted cargo specifications for diesel replacement.
- Mountain E-Bikes:Ruggedized panel mounting systems withstand off-road vibration while preserving frame geometry.
- Folding E-Bikes:Compact solar rack systems target multimodal commuters connecting to regional rail networks.
Commuter e-bikes handle the majority of throughput; cargo e-bikes are gaining share fastest among commercial buyers.
Battery Technology:
Cost tier stratification separates premium solid-state investment from commoditized lithium-ion volume.
- Lithium-Ion:Dominant cell chemistry pairs with mid-tier solar charge controllers across price-sensitive segments. Saxony-based assemblers source cylindrical formats from automotive supplier networks to reduce cathode material exposure.
- Solid-State:Higher energy density reduces panel surface requirements while preserving frame aesthetics. German automotive battery partnerships are accelerating pilot production for premium cargo configurations.
- Nickel-Metal Hydride:Legacy chemistry persists in entry-level commuter models with lower solar charge rates.
- Lead-Acid:Minimal market presence limited to retrofit kits for conventional pedelec conversions.
Lithium-ion chemistry handles the majority of throughput; solid-state formats are expanding most quickly in commercial segments.
Distribution Channel:
Customer type determines channel preference, with fleet procurement diverging sharply from individual purchase behavior.
- Specialty Stores:Technical consultation for photovoltaic diagnostics and panel maintenance drives repeat commercial relationships. Bavarian workplace charging infrastructure investments correlate with multi-unit fleet orders through certified service networks.
- Direct Sales:Brand-owned showrooms in Munich and Stuttgart capture premium buyers seeking factory-integrated solar configurations. Riese & Müller leverages engineering heritage to dominate high-performance cargo sales through controlled retail.
- Online Retail:Price transparency benefits entry-level commuter segments with standardized solar accessory compatibility.
- Supermarkets:Limited presence confined to seasonal promotional inventory without photovoltaic support services.
Specialty stores handle the majority of throughput; direct sales channels are climbing the fastest in premium positioning.
End User:
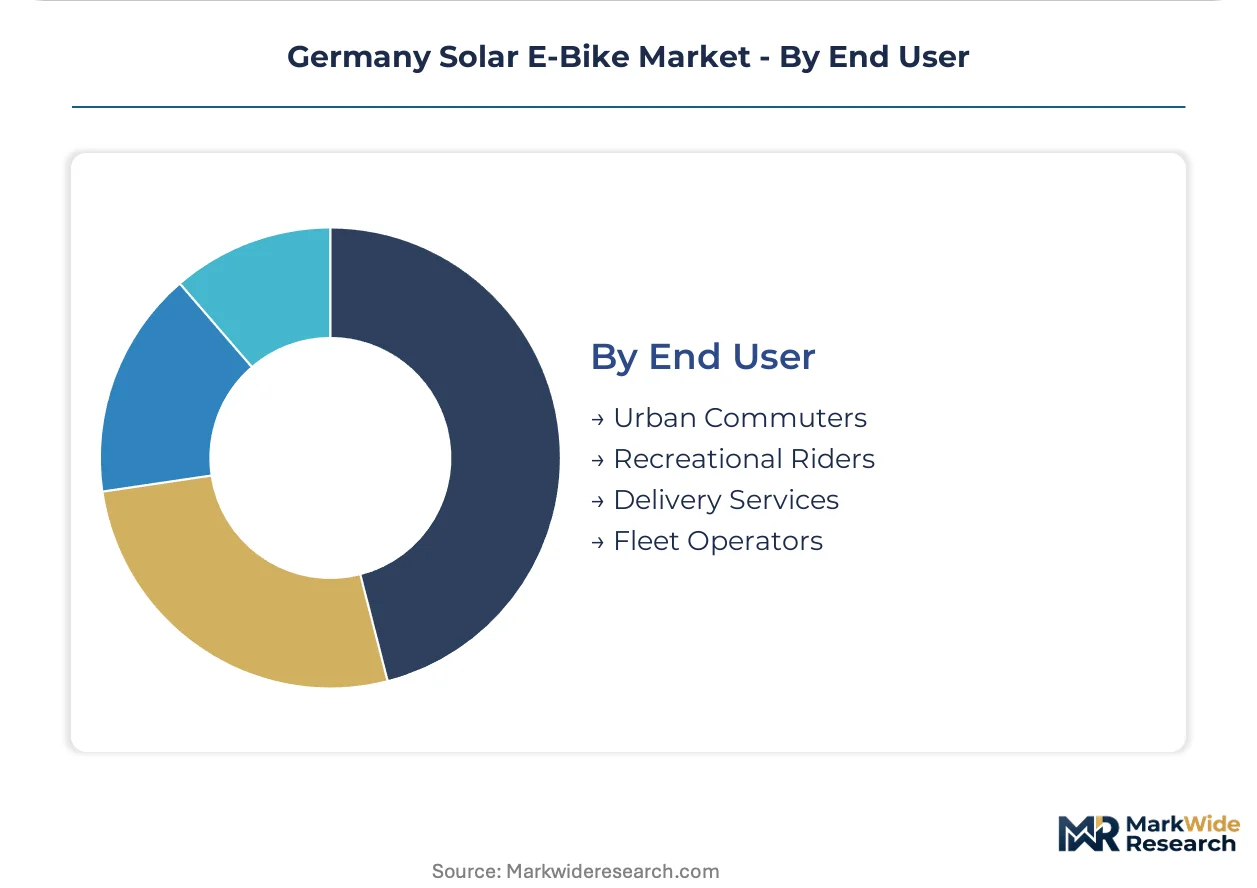
Application focus separates daily mobility predictability from intermittent recreational usage patterns.
- Urban Commuters:Workplace parking enables consistent solar exposure that maximizes photovoltaic return on investment. KBA type-approval compliance requirements shape insurance underwriting for daily-use configurations.
- Delivery Services:Route predictability allows solar charge planning that reduces grid dependency for fleet operators. Municipal last-mile logistics contracts in Bavarian cities are creating predictable replacement cycles.
- Fleet Operators:Consolidated procurement around certified service networks transcends product specifications for maintenance reliability.
- Recreational Riders:Variable usage patterns reduce solar charging predictability compared to commuter applications.
Urban commuters handle the majority of throughput; delivery services are expanding most quickly on commercial fleet conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria commands premium pricing power through workplace charging infrastructure density, while northern Länder with lower insolation struggle to justify solar panel premiums against conventional pedelec alternatives.
Bavaria
Munich-Stuttgart corridor employers subsidize solar e-bike procurement through corporate mobility budgets. KBA type-approval compliance shapes insurance underwriting for daily-use commuter configurations. Ingolstadt and Nuremberg manufacturing clusters produce frame-integrated solar rack systems for municipal fleet contracts.
Baden-Württemberg
Rhine Valley solar canopy installations generate captive demand for compatible onboard panel systems. Federal Ministry for Economic Affairs and Climate Action regional development programs direct procurement toward certified domestic assemblies. Stuttgart engineering consultancies specialize in photovoltaic diagnostic capabilities for brand-owned showrooms.
North Rhine-Westphalia
Ruhr industrial conversion zones pilot solar-assisted cargo fleets for last-mile logistics operators. StVZO road traffic regulations mandate integrated lighting systems that solar arrays power independently. Cologne-Düsseldorf workplace parking infrastructure enables consistent solar exposure for employer-subsidized programs.
Lower Saxony
Hanover municipal procurement standardizes solar-assisted specifications for parcel delivery network replacement cycles. CE marking electromagnetic compatibility testing creates certification delays for frame-integrated configurations. Wolfsburg automotive supplier partnerships accelerate solid-state battery pilot production for premium cargo segments.
Hesse
Frankfurt financial district commuter demand concentrates in employer-subsidized leasing programs with photovoltaic integration. KBA consultation papers on solar auxiliary power reclassification create regulatory uncertainty for product development timelines. Darmstadt research institutes advance perovskite thin-film chemistry for curved frame applications.
Germany Solar E-Bike Market Competitive Landscape
Engineering-heritage specialists and scalable-volume assemblers split the market between premium positioning and mid-tier coverage. The vendor base concentrates in southern German manufacturing regions with automotive supplier proximity. Three archetypes dominate: heritage engineering houses, diversified cycle conglomerates, and component-integrated specialists. Competitive moves center on direct-to-consumer showroom expansion and photovoltaic diagnostic service network certification.
Within the heritage engineering tier, Riese & Müller GmbH and Kalkhoff Werke GmbH exemplify premium positioning through controlled retail channels and frame-integrated solar rack specialization. CUBE Bikes occupies a scale-driven position leveraging Bavarian manufacturing infrastructure for portfolio breadth across price tiers. These three entities anchor the competitive structure while smaller specialists compete on aftermarket panel accessories and retrofit kit compatibility.
| Leading Market Players |
|---|
| Riese & Müller GmbH |
| CUBE Bikes |
| Kalkhoff Werke GmbH |
| Prophete In Moving GmbH |
| Winora Staiger GmbH |
| KTM Fahrrad GmbH |
| Canyon Bicycles GmbH |
| Cartrend GmbH |
| MHW Bike-House GmbH |
| Others |
Pricing and Supply Chain Analysis
Rhine Valley freight corridors linking Bavarian assembly plants to North Sea ports transmit lithium-ion cathode cost volatility directly into frame-integrated solar e-bike pricing, compressing mid-tier assembler margins while premium heritage brands exploit certification scarcity to sustain configured-to-order premiums.
Pricing Analysis
The customization-premium spread separates Riese & Müller configured-to-order cargo configurations from CUBE Bikes volume-tier commuter models. Pricing stratifies across premium heritage certification, integrated solar rack complexity, and after-sales photovoltaic diagnostic bundling. Cost compression in mid-tier lithium-ion commuter segments intensifies because cathode material sourcing constraints from automotive supplier networks squeeze Saxony-based assemblers. Fleet procurement managers exhibit lowest price sensitivity; individual recreational buyers in northern Länder with lower insolation demonstrate highest elasticity to solar panel premiums.
Supply Chain Analysis
Extended payment terms from photovoltaic cell suppliers in China and Taiwan strain working capital for Bavarian frame-integrated solar rack assemblers. Manufacturing draws from German automotive battery partnerships for solid-state pilot production, Chinese thin-film laminate suppliers for perovskite chemistry, and domestic aluminum forging for stress-tested frame mounts. Single-source vulnerability concentrates in Asian photovoltaic cell supply, with EU F-Gas Regulation thermal management redesigns adding compliance friction. Distribution runs through certified specialty retail networks with photovoltaic diagnostic capabilities rather than direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a regulatory entrenchment moat: KBA type-approval requirements for solar auxiliary power classification create switching costs that lock in certified domestic assemblers and marginalize unapproved imports.
For Market Incumbents: Build certification moats by accelerating KBA consultation paper compliance investments ahead of potential solar auxiliary power reclassification. Secure backward integration into solid-state battery partnerships with Wolfsburg automotive suppliers to reduce cathode material exposure. Channel control through brand-owned Stuttgart and Munich showrooms with photovoltaic diagnostic capabilities defends against direct-to-consumer platform erosion. For New Entrants and Emerging Players: Establish a beachhead in northern Länder retrofit kit compatibility, where lower insolation reduces incumbent solar-integrated product appeal. Target workplace charging infrastructure procurement programs in Cologne-Düsseldorf corridor employers seeking fleet standardization without heritage brand premiums. Go-to-market leverage rests on aftermarket panel accessory technical support partnerships with existing conventional pedelec service networks. For Investors and Strategic Acquirers: Component-integrated specialists with captive photovoltaic diagnostic software capabilities present asymmetric upside if KBA reclassification mandates factory-integrated solutions. Long-term viability hinges on regulatory entrenchment durability rather than technology differentiation alone. Perovskite tandem cell efficiency breakthroughs in Darmstadt research institutes signal inflection timing for thin-film laminate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| KBA Certification Pre-Positioning | Early compliance with draft solar auxiliary power standards secures roadway access before reclassification locks out competitors. |
| Solid-State Battery Partnership | Automotive supplier alliances in Wolfsburg and Stuttgart reduce panel surface requirements while preserving frame geometry. |
| Photovoltaic Diagnostic Service Network | Certified maintenance capabilities in Bavarian workplace charging clusters capture multi-unit fleet procurement consolidation. |
| Perovskite Thin-Film Integration | Darmstadt research institute licensing enables curved frame applications that obsolete rigid silicon aftermarket accessories. |
| Rhine Valley Solar Canopy Alignment | Compatible onboard panel systems for Baden-Württemberg cycling infrastructure generate captive corridor demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the German solar e-bike value chain: KBA regulatory affairs specialists, municipal fleet procurement managers in Bavarian cities, photovoltaic diagnostic service technicians, frame-integrated solar rack mechanical engineers, and workplace charging infrastructure planners. Secondary validation drew from KBA type-approval documentation, Federal Ministry for Economic Affairs and Climate Action regional development program disclosures, StVZO road traffic regulation amendments, EU F-Gas Regulation phase-down schedules, and CE marking electromagnetic compatibility testing protocols. Bottom-up assembly volume estimates triangulated against top-down mobility budget expenditure flows from employer-subsidized procurement programs.
Calibration against historical KBA registration data for solar-assisted pedelec categories anchored growth trajectory assumptions across the analysis window. Segmentation modeling spanned product architecture, battery chemistry tier, distribution channel control, and end-use application predictability. CAGRs derived from logistic diffusion curves fitted to municipal fleet replacement cycle visibility and workplace charging infrastructure investment pipelines. Perovskite cell efficiency laboratory benchmarks and solid-state battery automotive supplier partnership timelines informed technology adoption pacing.
Sensitivities concentrate around KBA consultation paper finalization timing, lithium-ion cathode material sourcing disruptions, and perovskite manufacturing scale-up feasibility. Forecasts reflect documented assumptions on regulatory stability, insolation-adjusted solar charge rate economics, and fleet procurement consolidation velocity. Macroeconomic contraction in employer mobility budgets, abrupt KBA solar auxiliary power reclassification, or breakthrough solid-state battery energy density gains would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Electric Vehicle Power Control Unit Market