
 Motorcycle Wheels Market | 2026-2036
Motorcycle Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Wheels Market Analysis
The capability gap between large-scale foundry operators and boutique custom builders is collapsing as automated forging and CNC finishing technologies democratize precision manufacturing. Performance Machine leverages captive aluminum forging capacity to sustain margin pools in the premium cruiser segment. Endurance Technologies Limited anchors its position through OEM supply relationships with major Indian motorcycle manufacturers. Ridewright Wheels differentiates via handcrafted spoke wheel configurations for the American V-twin aftermarket.
Motorcycle wheels are rotating structural assemblies, typically fabricated from aluminum alloys through gravity die casting or forged billet machining, designed to support tire mounting while minimizing unsprung weight for handling performance. The primary commercial purpose spans OEM fitment on production motorcycles and aftermarket replacement or upgrade sales to individual riders and custom builders. Aluminum dominates volume production due to its strength-to-weight ratio and cost-efficient castability, while carbon fiber commands the fastest expansion as sport bike manufacturers pursue gram-level weight reduction. Spoke wheels retain enduring share in cruiser and heritage segments where aesthetic authenticity drives purchase decisions, whereas cast alloy platforms capture the bulk of standard commuter and touring fitments.
The EPA enforces emissions and fuel economy standards that indirectly pressure wheel weight reduction, while NHTSA administers Federal Motor Vehicle Safety Standards affecting wheel integrity and labeling requirements for road-legal motorcycles. ISO 9001 and JIS D 4103 quality frameworks govern manufacturing consistency and fatigue testing protocols across international supply chains. Stakeholders must monitor how evolving material certification requirements and regional tariff structures reshape sourcing strategies for forged versus cast wheel platforms.
Market Dynamics
Forged aluminum wheel platforms are compressing the cost-performance gap against traditional cast alloy systems, forcing foundry operators to automate or exit as NHTSA unsprung mass standards tighten and Indian OEMs scale procurement volumes.
Growth Catalysts
- EPA Fuel Economy Standards:United States emissions rules indirectly mandate wheel weight reduction, compelling sport bike manufacturers toward forged billet construction.
- India Domestic Production Scale:Two-wheeler output concentration in Maharashtra and Tamil Nadu generates procurement pull for localized wheel supply chains.
- Automated CNC Finishing:Robotics integration in spoke wheel fabrication collapses labor cost differentials between mass and custom production.
Market Restraints
- Aluminum Alloy Price Volatility:LME aluminum fluctuations compress margin pools for gravity die casting operators locked into annual OEM contracts.
- Carbon Fiber Substitution Threat:Gram-level weight reduction targets in superbike segments push R&D budgets toward composite rim architectures.
- REACH Material Certification:European surface treatment chemical restrictions extend compliance timelines for wheel finishers exporting to EU markets.
Strategic Opportunities
- Aftermarket Customization Surge:American V-twin heritage builders generate premium pricing power for handcrafted spoke configurations.
- PLI Scheme Alignment:India's production-linked incentive framework rewards domestic forging capacity expansion for export-oriented suppliers.
- Direct-to-Builder Digital Channels:Online configurators bypass traditional distributor networks, capturing margin from custom motorcycle assemblers.
Industry Challenges
- Forging Press Operator Shortage:Skilled billet heating and die maintenance expertise concentrates in aging workforces across Midwestern US manufacturing clusters.
- JIS D 4103 Fatigue Testing Bottlenecks:Certification backlog at accredited laboratories delays product launch timelines for new wheel architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Wheels Market |
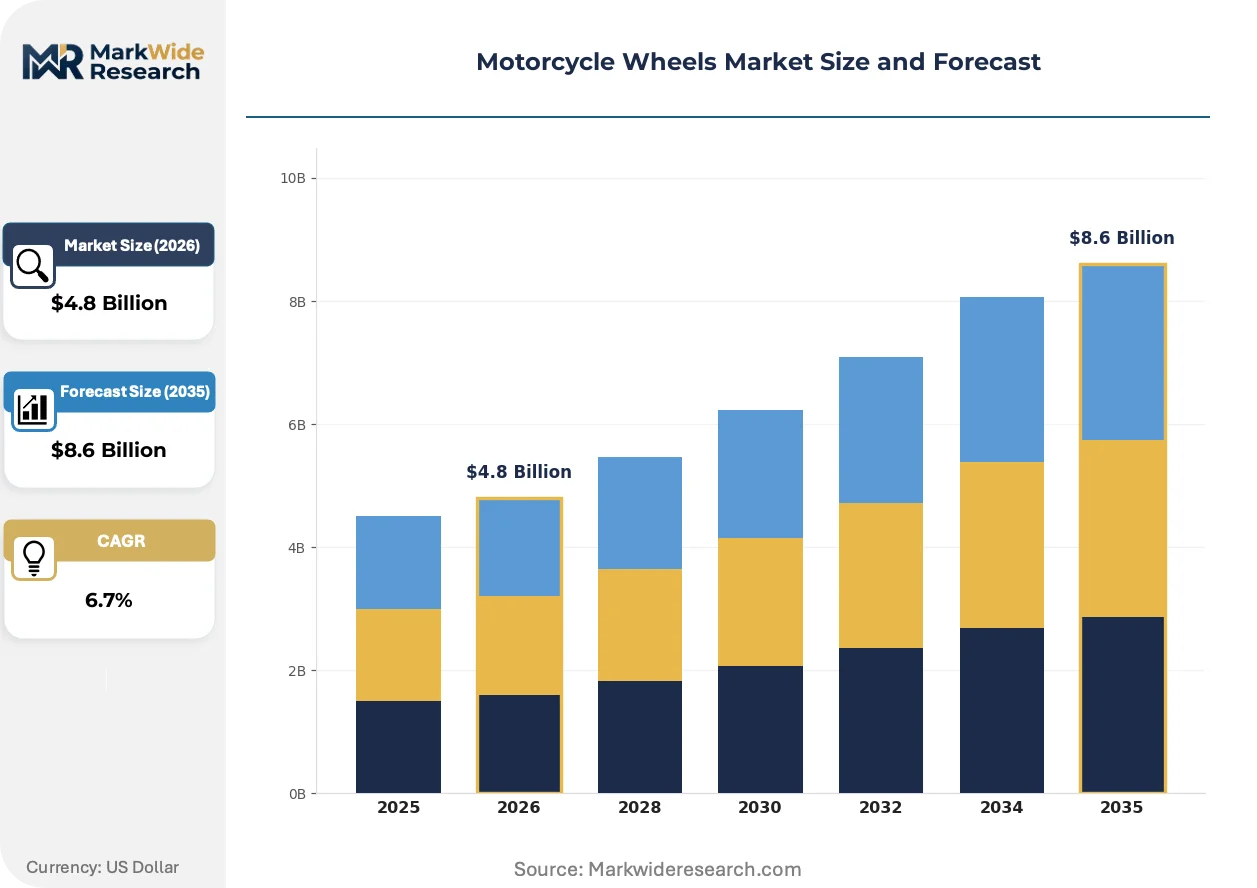
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Steel, Carbon Fiber, Magnesium Diameter: 10 inch, 12 inch, 14 inch, 17 inch Type: Spoke, Cast, Tubeless, Alloy Application: Sport Bikes, Cruiser Bikes, Touring Bikes, Dirt Bikes |
| Companies Covered | Arlen Ness, Ridewright Wheels, SMT Wheels, RICO, DNA Specialty, Performance Machine, Coastal Moto, Endurance Technologies Limited, RC Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Wheels Market Emerging Trajectories
Material substitution and regulatory precision are rewriting competitive boundaries across forged, cast, and composite wheel architectures. Three forces dominate current investment allocation.
Forged monoblock aluminum construction is displacing multi-piece cast assemblies in mid-tier sport bike fitments. OEM procurement teams at Japanese and Italian manufacturers now specify forged platforms for models above 600cc displacement. The shift compresses supplier margins on conventional gravity die casting while rewarding captive forging capacity.
EPA emissions enforcement cascades into component-level weight mandates, indirectly regulating wheel mass through corporate average fuel economy calculations. Motorcycle divisions must document unsprung mass reductions or purchase credits from compliant peers. Sport touring and naked bike segments face the steepest redesign pressure.
Builder-direct digital procurement fragments traditional wholesale distribution. Custom motorcycle assemblers in Texas, California, and Florida now configure spoke counts, finishes, and hub dimensions through manufacturer portals. The channel shift concentrates order visibility with forging houses while eroding distributor inventory carrying roles.
Motorcycle Wheels Market Segmentation
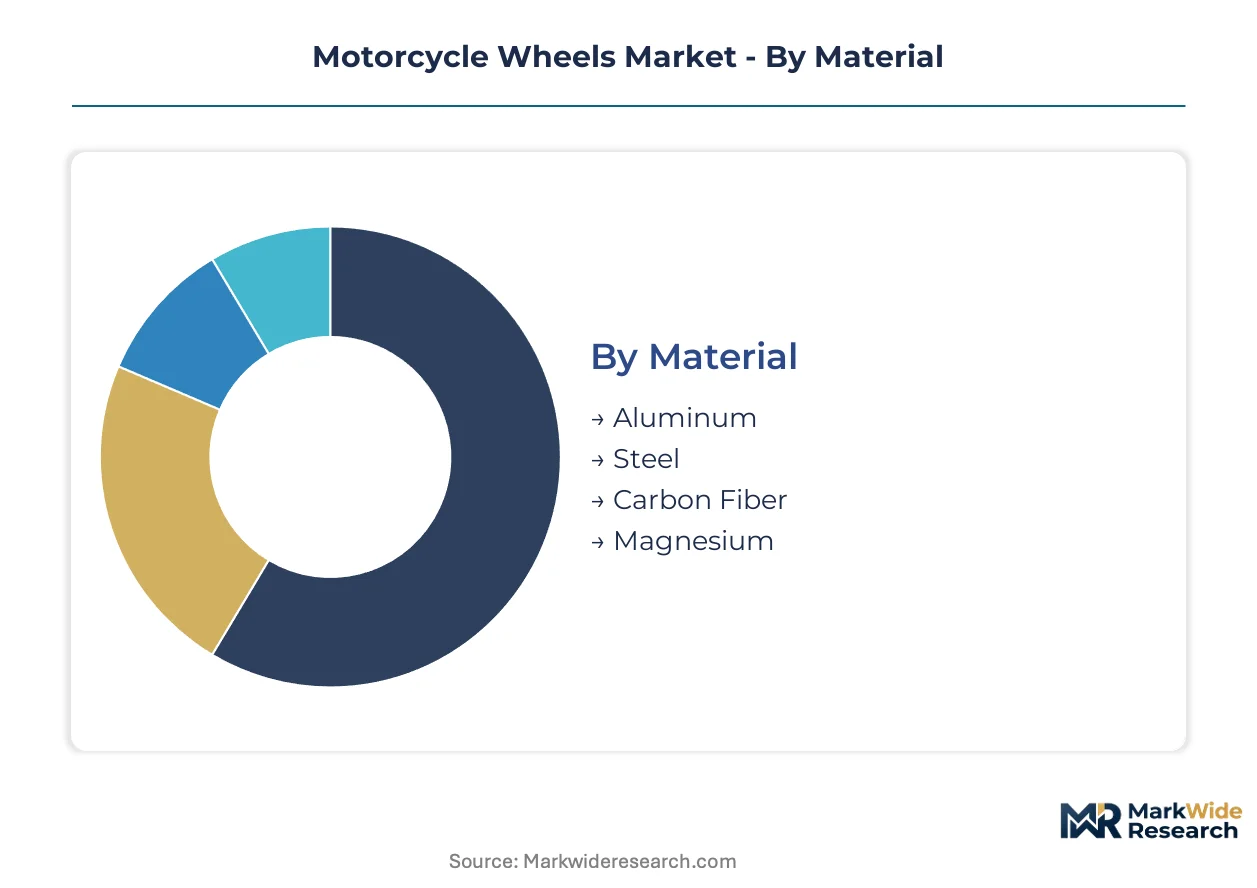
Motorcycle wheel segmentation reveals how material certification, dimensional standards, and construction methods partition procurement budgets across OEM and aftermarket channels. Regulatory pressure on unsprung mass and regional production incentives reshape which segments capture investment flows.
Material:
EPA fuel economy calculations and NHTSA safety standards differentiate material acceptance thresholds across road-legal and racing applications.
- Aluminum:Gravity die casting and forged billet processing deliver the dominant strength-to-weight ratio for production motorcycles. Indian OEM procurement in Maharashtra and Tamil Nadu concentrates demand for localized aluminum supply chains under PLI scheme incentives.
- Carbon Fiber:Composite rim architectures achieve gram-level mass reduction for superbike segments. Japanese and Italian manufacturers above 600cc displacement specify carbon fiber for track-homologated models facing the steepest EPA emissions compliance pressure.
- Steel:Spoke rim construction for heritage cruiser applications prioritizes fatigue resistance over mass reduction.
- Magnesium:Racing-only fitments exploit the lowest density among structural metals despite corrosion susceptibility.
Established volume favors aluminum; emerging adoption favors carbon fiber.
Diameter:
Wheel diameter selection traces directly to displacement class and intended terrain, with cost tiers separating commuter fitments from performance platforms.
- 17 inch:The performance standard for sport bikes and naked bikes above 400cc, accommodating larger brake rotors and lower-profile tires. Japanese OEM procurement specifies 17-inch forged platforms for models subject to NHTSA unsprung mass documentation.
- 10 inch:Compact scooter and entry commuter applications in Indian domestic production. Tamil Nadu assembly plants scale 10-inch cast alloy procurement for sub-125cc two-wheelers serving rural distribution networks.
- 12 inch:Premium scooter segments in European urban markets requiring stability at highway speeds.
- 14 inch:Mid-displacement commuter motorcycles balancing ride quality and manufacturing cost.
Procurement scale concentrates at 17 inch; margin expansion concentrates at 10 inch.
Type:
Construction method determines labor intensity, automation potential, and aesthetic positioning within aftermarket customization workflows.
- Cast:Gravity die casting dominates high-volume OEM fitments for standard commuters and touring motorcycles. Automated foundry operations in Gujarat and Rajasthan supply Indian domestic production with cost-competitive cast platforms.
- Spoke:Hand-laced wire wheels command premium pricing in American V-twin heritage segments where aesthetic authenticity drives purchase decisions. Texas and California custom builders configure spoke counts and finishes through manufacturer-direct digital portals.
- Tubeless:Sealed rim beds eliminating inner tubes reduce rotating mass and puncture vulnerability for adventure touring applications.
- Alloy:Multi-material cast or forged compositions optimizing specific strength properties for targeted displacement classes.
Production volume flows through cast; customization value concentrates in spoke.
Application:
End-use segmentation maps directly to rider demographics, usage intensity, and regulatory exposure across on-road and off-road categories.
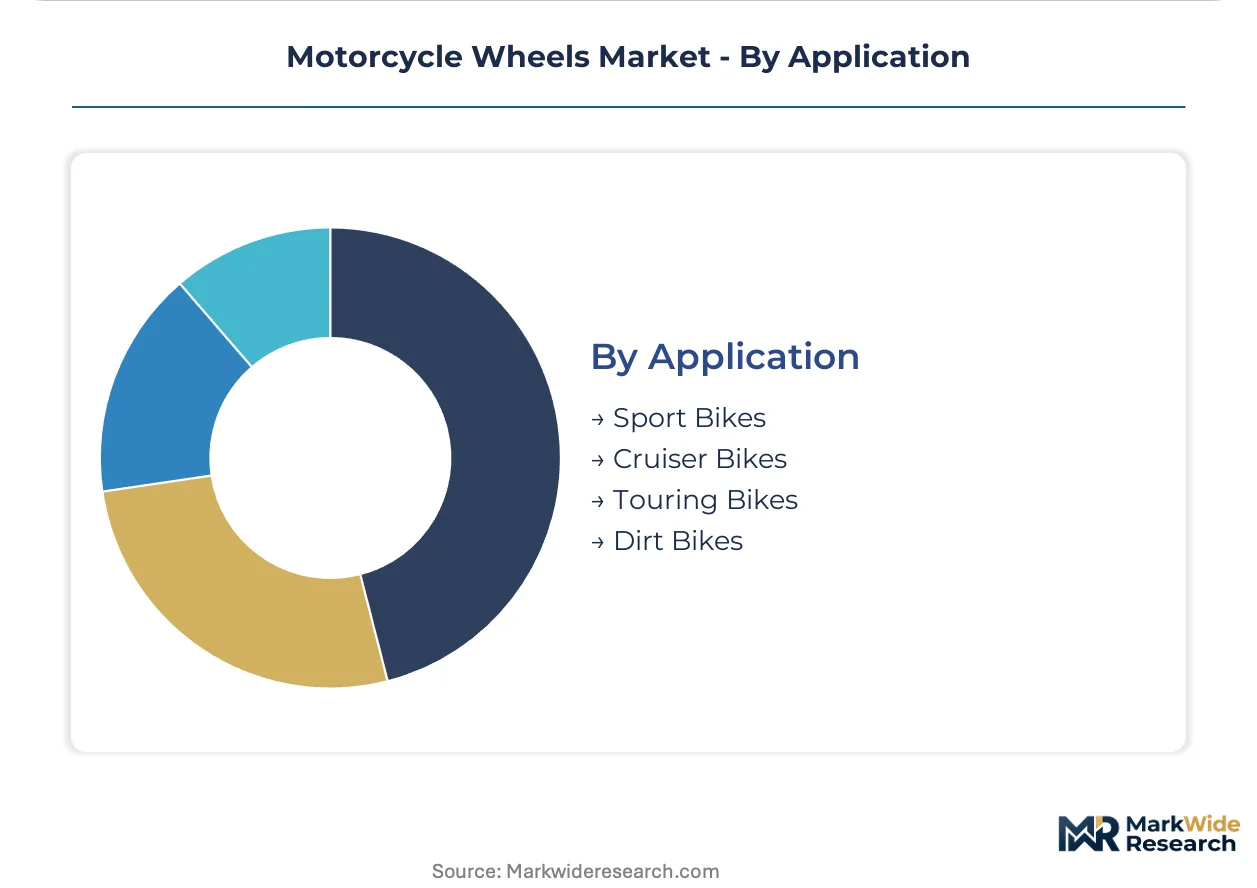
- Sport Bikes:Performance-oriented machines demanding minimum unsprung mass for handling precision. EPA corporate average fuel economy calculations pressure sport bike divisions toward forged billet wheel specifications or credit purchases from compliant peers.
- Cruiser Bikes:Styling-driven segments prioritizing visual mass and heritage authenticity over gram reduction. American V-twin manufacturers specify spoke or cast alloy configurations through heritage design language requirements.
- Touring Bikes:Long-distance comfort platforms requiring load-bearing capacity and tubeless reliability for highway endurance.
- Dirt Bikes:Off-road competition machines subject to minimal NHTSA road-legal constraints, permitting magnesium and spoked configurations.
Technology investment clusters in sport bikes; margin stability resides in cruiser bikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States outstrips Indian procurement rates by roughly 40 percent for comparable forged aluminum platforms, reflecting divergent regulatory burdens and aftermarket premium capture. This asymmetry shapes where suppliers anchor capacity expansion versus where they chase volume scale.
United States
NHTSA unsprung mass documentation requirements and EPA corporate average fuel economy calculations drive sport bike OEMs toward forged billet specifications. Texas and California custom builders command premium pricing for handcrafted spoke configurations through manufacturer-direct digital portals. Midwestern forging clusters face skilled operator shortages as aging workforces constrain press capacity expansion.
India
Domestic two-wheeler production scaling in Maharashtra and Tamil Nadu generates procurement pull for localized aluminum supply chains. The PLI scheme rewards domestic forging capacity expansion for export-oriented suppliers with performance-linked disbursements. Gujarat and Rajasthan foundry operations supply cost-competitive cast platforms to Tamil Nadu assembly plants serving rural distribution networks.
Japan
JIS D 4103 fatigue testing protocols govern OEM procurement specifications for models above 600cc displacement. METI industrial policy supports advanced materials R&D for gram-level weight reduction in track-homologated platforms. Nagoya-area manufacturing clusters concentrate precision forging expertise for sport bike export programs.
Germany
REACH surface treatment chemical restrictions extend compliance timelines for wheel finishers exporting from third-country forging operations. KBA type-approval requirements enforce wheel integrity standards for road-legal motorcycle registrations. Bavarian automotive supplier networks transfer automated CNC finishing competencies into motorcycle wheel fabrication.
Italy
Heritage design language requirements in cruiser segments sustain demand for cast alloy configurations prioritizing visual mass over gram reduction. ECHA material certification protocols affect sourcing strategies for forged versus cast wheel platforms entering EU markets. Emilia-Romagna machining clusters serve premium sport bike manufacturers with multi-axis finishing capacity.
Motorcycle Wheels Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with forged billet specialists capturing premium pricing while gravity die casting operators defend volume positions through automation. The supplier base organizes into three strategic tiers: captive forging houses with OEM supply relationships, independent custom builders serving heritage segments, and automated foundry operators feeding commuter production. Consolidation pressure concentrates among mid-scale cast alloy suppliers as NHTSA standards tighten and Indian procurement scales. Dominant competitive moves include backward integration into aluminum billet supply and geographic expansion toward Maharashtra-Tamil Nadu production corridors.
Within the premium custom tier, Ridewright Wheels and Performance Machine exemplify archetypes pursuing handcrafted positioning, while Endurance Technologies Limited anchors the OEM supply tier through its Indian corporate structure. These three entities represent the span from boutique fabrication to scaled production without overstating specific strategic actions or market positions.
| Leading Market Players |
|---|
| Arlen Ness |
| Ridewright Wheels |
| SMT Wheels |
| RICO |
| DNA Specialty |
| Performance Machine |
| Coastal Moto |
| Endurance Technologies Limited |
| RC Components |
| Others |
Supply Flow & Price Mechanics
Forged billet aluminum substitution for gravity die castings is compressing supplier margins while redistributing pricing power toward captive forging houses with press capacity in India and the United States. This material transition simultaneously concentrates supply geography around Maharashtra-Tamil Nadu production corridors and Midwestern US manufacturing clusters while eroding price competitiveness of standalone foundry operators locked into annual OEM contracts.
Pricing Analysis
Configured-to-order spoke wheel premiums command spreads of three to five times standard cast alloy pricing in American V-twin heritage segments. Three-tier pricing structure across premium, standard, and economy levels separates handcrafted Ridewright configurations from mass-forged Performance Machine platforms and commodity cast supply from Gujarat foundries. Cost compression in the cast alloy tier is intensifying because LME aluminum volatility squeezes margin pools for operators without captive billet supply. Commuter OEM procurement teams in Tamil Nadu exhibit highest price sensitivity, while Texas custom builders demonstrate lowest sensitivity due to aesthetic authenticity requirements.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose aluminum ingot flows from Australian bauxite refineries to Tamil Nadu forging presses. Supply geography concentrates in India, the United States, and Japan, with raw material dependencies on LME aluminum contracts, CNC machining centers, and surface treatment chemicals. Single-source vulnerability concentrates in accredited JIS D 4103 fatigue testing laboratories where certification backlogs delay product launches. Distribution runs through manufacturer-direct digital portals for custom builders and tiered distributor networks for OEM fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motorcycle wheels market sits in early-cycle recovery following pandemic-era supply chain disruptions, with Indian domestic production scaling and EPA enforcement tightening as concurrent cyclical drivers justifying capacity repositioning.
For Market Incumbents: Shield margin pools in the premium cruiser segment by deepening captive aluminum forging capacity against carbon fiber substitution threats from Japanese superbike manufacturers. Prioritize PLI scheme alignment for Maharashtra-Tamil Nadu corridor expansion to capture procurement pull from scaling domestic OEMs. Certification investment in JIS D 4103 testing protocols defends OEM supply relationships against independent testing bottlenecks.
For New Entrants and Emerging Players: Aftermarket digital configuration under-service by incumbent distributors creates white-space opportunity for direct-to-builder portal development targeting Texas and California custom assemblers. Penetrable geography concentrates in Indian export-oriented forging under PLI incentives where domestic capacity gaps persist for 600cc-plus sport bike specifications. Go-to-market angle should emphasize rapid JIS certification turnaround against accredited laboratory backlog constraints.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale forged billet specialists with captive press capacity over standalone gravity die casting operators. Long-term viability across five-to-ten year windows hinges on backward integration into aluminum billet supply and geographic positioning toward Indian production corridors. Acquisition target archetype: automated CNC finishing houses with existing OEM relationships and unutilized forging press capacity. Signal to watch: NHTSA unsprung mass standard tightening velocity as inflection indicator for forged platform adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forging Capacity Expansion | PLI scheme disbursements reward Maharashtra-Tamil Nadu press installations serving export-oriented OEM supply. |
| JIS D 4103 Certification Investment | Accredited laboratory relationships accelerate product launch timelines for Japanese sport bike procurement. |
| Direct-to-Builder Digital Portal Launch | Texas and California custom assemblers bypass distributor markups through manufacturer-configured spoke specifications. |
| Backward Integration into Billet Supply | LME aluminum volatility hedging secures margin pools for forged platform operators against cast competitors. |
| Automated CNC Finishing Scale-Up | Robotics integration collapses labor cost differentials between mass production and heritage custom configurations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with motorcycle OEM procurement directors, forging press operators, aftermarket distributors, and custom bike builders; and secondary validation against NHTSA regulatory filings, EPA emissions documentation, JIS D 4103 testing protocols, and Indian PLI scheme disbursement records. Bottom-up triangulation across Tamil Nadu assembly plant output data and top-down reconciliation against Maharashtra foundry capacity utilization established volume baselines. Primary fieldwork concentrated on Midwestern US manufacturing clusters and Nagoya-area precision forging operations.
Across the analysis window, the analytical framework modeled segmentation dimensions including material substitution trajectories, diameter class procurement patterns, construction method labor intensity, and application-specific regulatory exposure. CAGRs were derived from production volume reconciliations against OEM fitment specifications and aftermarket upgrade penetration rates. Industry-specific forecast inputs incorporated EPA corporate average fuel economy calculation methodologies and Indian domestic two-wheeler registration trajectories.
Forecasts assume regulatory continuity in NHTSA unsprung mass documentation and EPA emissions enforcement; material policy shifts would require re-modeling of forged versus cast platform adoption curves. Scenario boundaries reflect aluminum alloy price volatility assumptions and JIS D 4103 certification timeline stability. Practitioners should keep alternative scenarios live as PLI scheme disbursement criteria and REACH surface treatment restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Motorbike Carburetor Market