
 Motorcycle Accessories Market | 2026-2036
Motorcycle Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Accessories Market Outlook
Connected-helmet telemetry and integrated rider-assistance electronics is reconfiguring how motorcycle accessories integrate with vehicle systems and mobile platforms. Brembo S.p.A. leverages its braking-system expertise to anchor premium aftermarket positioning across European and North American markets. Garmin Ltd. competes through GPS and communication devices that extend rider safety and navigation functionality. Alpinestars USA Inc. specializes in protective apparel with advanced impact-absorption materials for track and street segments.
Motorcycle accessories encompass protective equipment, luggage systems, performance components, and electronic devices designed to enhance rider safety, vehicle utility, or aesthetic customization, typically manufactured from aramid fibers, thermoplastic polymers, or aluminum alloys to meet impact-resistance and weight specifications. Helmets represent the most regulated product category with stringent penetration and retention testing protocols, while jackets and gloves incorporating CE-certified armor are capturing margin pools as riders prioritize protective specifications over basic styling. The distribution channel dimension shows online retailers gaining transaction volume through fitment tools and video reviews, though specialty stores retain advantage in custom builds and professional installation services where tactile assessment dominates purchase decisions.
Federal Motor Vehicle Safety Standard No. 218 from NHTSA governs helmet performance in the United States, while ECE R22.06 in Europe mandates rotational-impact testing that is reshaping design priorities among manufacturers. India's BIS certification requirements for two-wheeler components create compliance thresholds that filter import access and shape domestic production scale. Stakeholders must monitor how evolving safety standards across these jurisdictions influence material substitution timelines and certification cost structures.
Market Dynamics
ECE R22.06's rotational-impact testing mandate is compressing design cycles for helmet manufacturers while simultaneously elevating material specifications across the protective gear supply base. This regulatory inflection point is reshaping competitive positioning by favoring suppliers with captive R&D and integrated testing capabilities over pure assemblers.
Growth Catalysts
- Connected-helmet telemetry:Integrated rider-assistance electronics are pulling demand from recreational riders in Germany and the United States who prioritize safety data logging and emergency notification systems.
- ECE R22.06:Europe's tightened certification standards are forcing material upgrades to advanced aramid composites and dual-density EPS liners, creating replacement demand across the installed base of non-compliant inventory.
- India's commuter expansion:Two-wheeler ownership broadening beyond urban centers into tier-2 and tier-3 cities is concentrating volume demand for affordable protective apparel and basic luggage systems.
Market Restraints
- Aramid fiber supply concentration:DuPont and Teijin control over seventy percent of global para-aramid capacity, exposing manufacturers to input cost volatility and allocation risk during demand surges.
- Technical limitation in rotational testing:Current oblique-impact simulation equipment lacks standardized correlation between laboratory results and real-world traumatic brain injury outcomes, creating certification uncertainty.
- Substitution threat from ride-hailing:Urban mobility shifts toward scooter-sharing platforms in Paris and Milan are reducing individual ownership rates among younger demographic cohorts.
Strategic Opportunities
- Underpenetrated Brazil:ANVISA's pending harmonization with ECE standards creates a regulatory tailwind for pre-certified European and Asian suppliers to establish local assembly partnerships.
- Technology convergence:Integration of heads-up display optics with carbon-fiber shell manufacturing is opening premium price tiers for track-day enthusiasts seeking real-time telemetry overlay.
- Direct-to-rider subscription:Helmet replacement programs tied to mileage or impact sensors represent a channel innovation bypassing traditional retail markups in the United States and United Kingdom.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous pursuit of DOT, ECE, and BIS approvals stretches product development cycles and strains testing laboratory capacity.
- Legacy inventory obsolescence:Pre-R22.06 helmet stocks require discount liquidation or geographic redirection to markets without rotational-impact mandates, compressing margin recovery.
- Integration complexity with OEM CAN bus systems:Aftermarket electronics manufacturers face proprietary protocol barriers when connecting rider-assistance devices to BMW, Ducati, and Kawasaki vehicle networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Accessories Market |
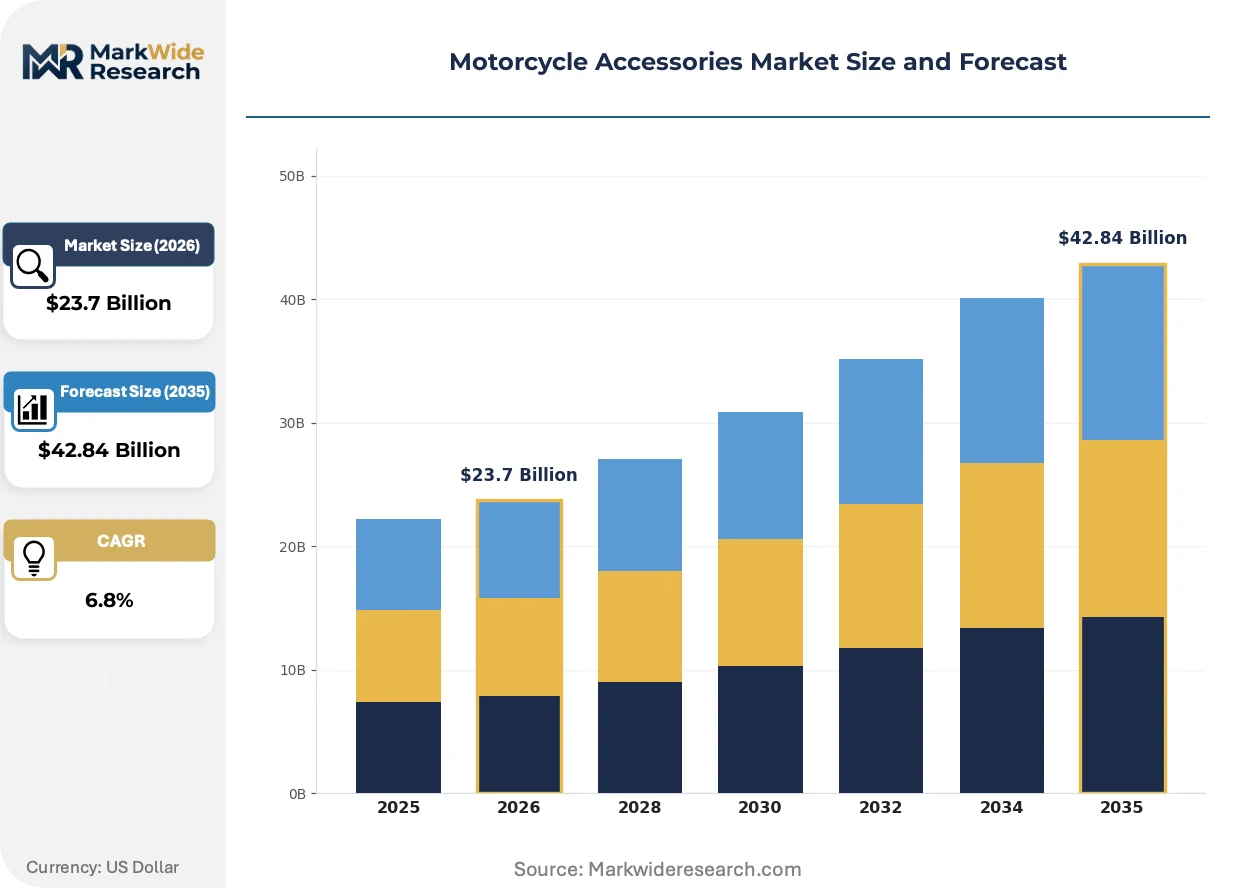
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Gloves, Jackets, Luggage End User: Recreational Riders, Commuters, Off-Road Enthusiasts, Professional Racers Installation: DIY, Professional Installer, Aftermarket, Custom Builds Distribution Channel: Online Retailers, Specialty Stores, Motorcycle Dealerships, Events |
| Companies Covered | TVS Motor Company, Brembo S.p.A., Harley-Davidson, Inc., Garmin Ltd., GIVI S.P.A., Yamaha Motor Co., Ltd., Alpinestars USA Inc., FOX Head Inc., Hero MotoCorp Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Accessories Market Strategic Shifts
Material science advances and embedded sensor miniaturization are converging to redefine what constitutes protective equipment. The boundary between passive safety gear and active vehicle systems is dissolving.
Multi-directional impact protection system (MIPS) technology reduces rotational forces transmitted to the brain during angled impacts. Track-day riders and road-touring enthusiasts in Sweden and Australia are adopting MIPS-equipped helmets at accelerating rates. Traditional fixed-liner designs are rendering obsolete for premium segments above three hundred dollars.
REACH's restriction on per- and polyfluoroalkyl substances (PFAS) is eliminating water-repellent treatments from textile manufacturing processes. European apparel suppliers are reformulating DWR coatings or switching to alternative membrane technologies like electrospun nanofibers. The protective jacket segment faces the steepest compliance cost escalation due to fabric surface-area exposure requirements.
Video-enabled purchasing is displacing tactile assessment for standardized replacement items. Riders in the United Kingdom and Canada now rely on fitment algorithms and user-generated review content for helmet sizing decisions. Specialty retailers retain advantage only in custom builds and professional installation where hands-on expertise remains non-substitutable.
Motorcycle Accessories Market Segmentation
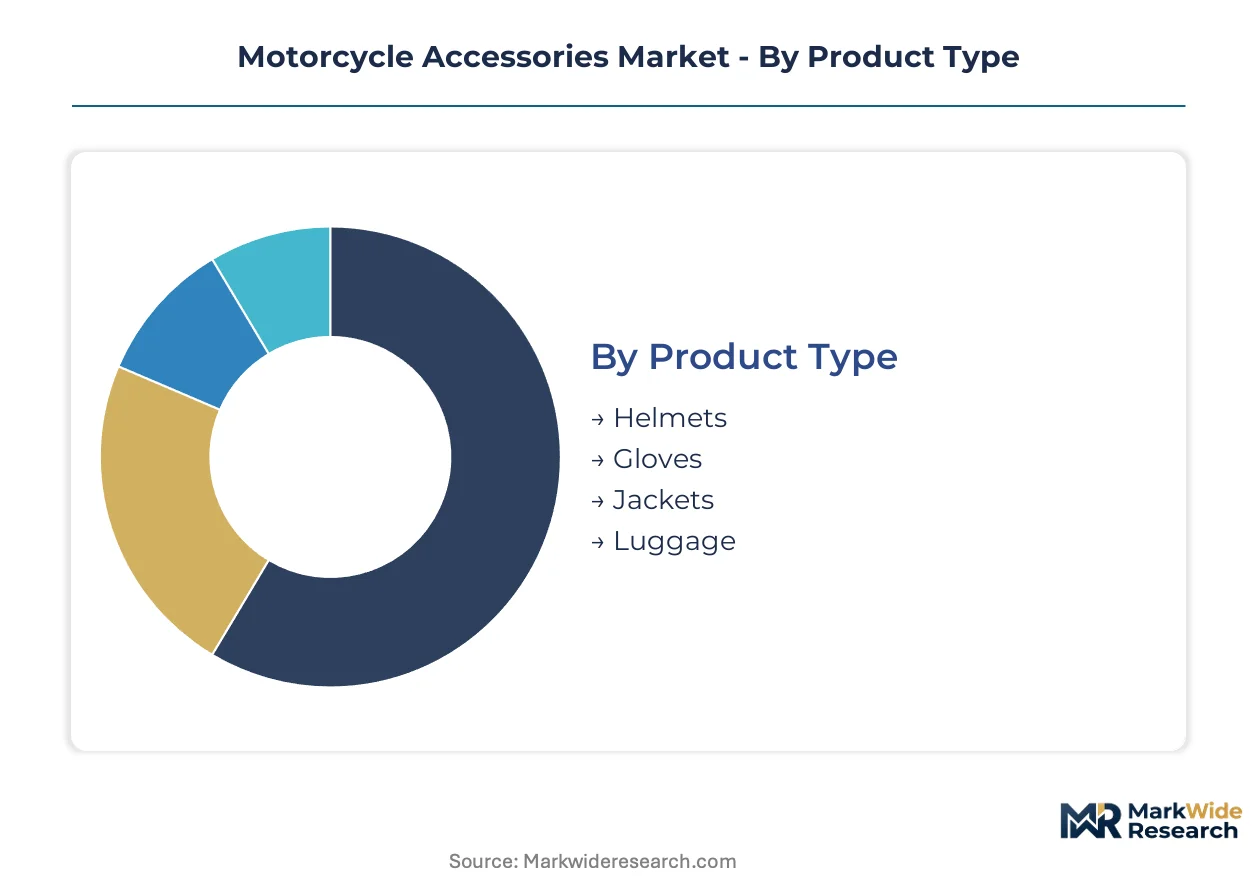
Motorcycle accessories segmentation reveals divergent margin structures across protective equipment versus lifestyle categories. Material certification requirements and installation complexity create distinct competitive dynamics within each slice.
Product Type:
Mature segments coexist with emerging material technologies across the protective equipment spectrum.
- Helmets:Full-face and modular designs incorporate dual-density EPS liners and carbon-fiber composites to meet ECE R22.06 rotational-impact mandates. Demand concentrates in Germany and France where regulatory enforcement eliminates non-compliant inventory from retail channels.
- Jackets:CE-certified armor integration with aramid fiber reinforcement dominates premium positioning for track-day and touring riders in Sweden and Australia. REACH PFAS restrictions are forcing DWR coating reformulation across European textile suppliers.
- Gloves:Leather and synthetic palm constructions with knuckle protection serve street and off-road segments.
- Luggage:Hard-shell panniers and tank bags manufactured from aluminum alloys and thermoplastic polymers address touring utility requirements.
Helmets handle the majority of throughput; jackets are climbing the fastest on share as armor certification becomes a purchase prerequisite.
End User:
Application intensity separates occasional purchasers from equipment replacement cycles measured in months rather than years.
- Recreational Riders:Weekend touring enthusiasts in the United States and United Kingdom prioritize connected-helmet telemetry and integrated communication systems. Garmin GPS units and Bluetooth intercoms anchor their accessory spending patterns.
- Commuters:Daily urban riders in India's tier-2 and tier-3 cities concentrate volume demand for affordable protective apparel and basic luggage systems as two-wheeler ownership broadens beyond metropolitan centers.
- Off-Road Enthusiasts:Trail and enduro riders require impact-resistant body armor and hydration-compatible gear for extended terrain exposure.
- Professional Racers:Track-day competitors demand FIM-homologated equipment with real-time biometric monitoring and heads-up display integration.
Commuters generate the highest transaction frequency; professional racers command the steepest price premiums per unit.
Installation:
Technical barrier determines whether value capture stays with manufacturers or shifts to service providers.
- DIY:Bolt-on accessories and standardized replacement items suit riders comfortable with basic mechanical work. Video-enabled purchasing and fitment algorithms now displace tactile assessment for helmets and gloves in Canada and the United Kingdom.
- Professional Installer:Brake system upgrades and suspension modifications require certified technician involvement to preserve warranty coverage and safety performance.
- Aftermarket:Dealer-installed accessories leverage existing service relationships for warranty-aligned equipment additions.
- Custom Builds:Fabrication-intensive projects demand hands-on expertise for one-off luggage racks, exhaust systems, and lighting modifications. Specialty retailers retain advantage here where tactile assessment dominates purchase decisions.
DIY absorbs the greatest unit volume; custom builds extract the highest margin per transaction.
Distribution Channel:
Channel economics split between scale efficiency and relationship-based value capture.
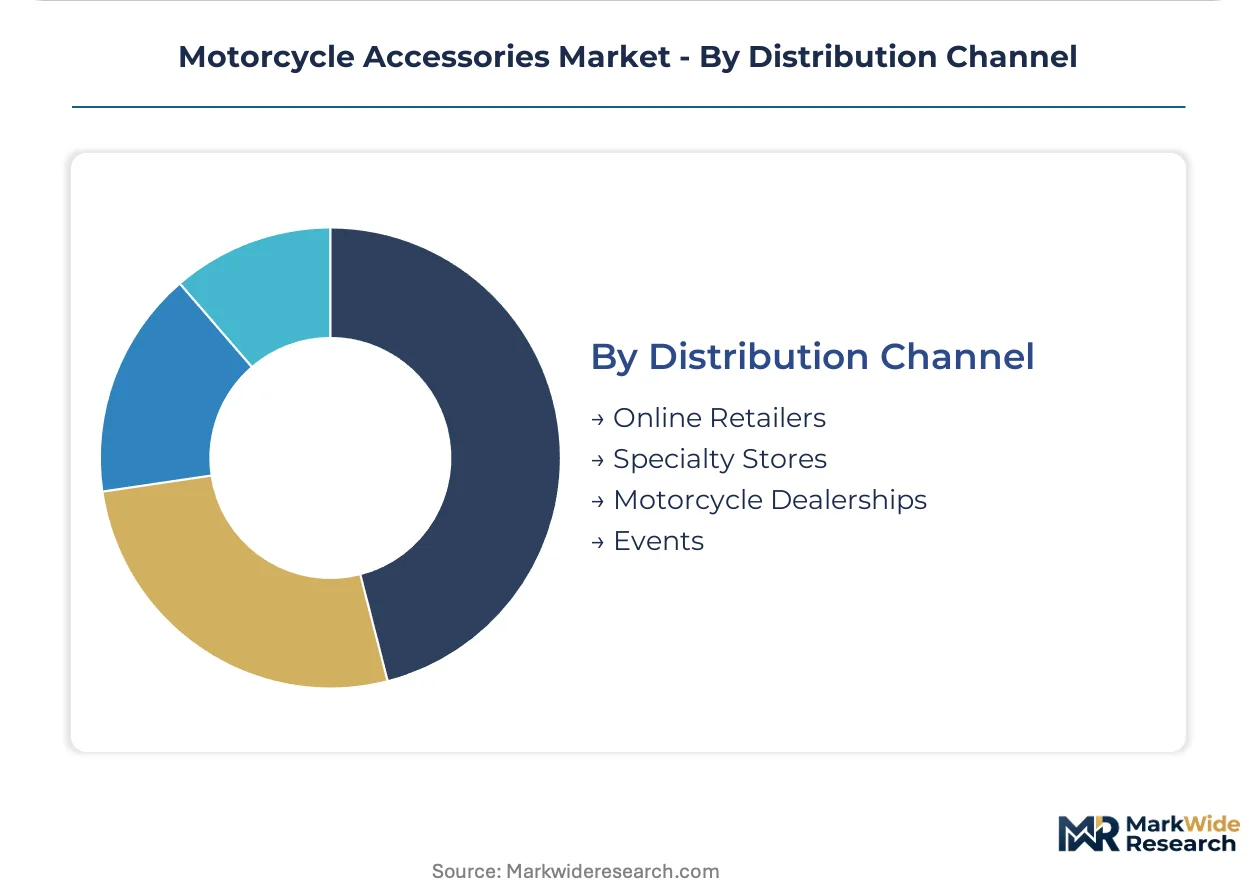
- Online Retailers:Amazon and RevZilla aggregate transaction volume through fitment tools, video reviews, and subscription replacement programs. United States and United Kingdom riders increasingly rely on user-generated content for helmet sizing decisions.
- Specialty Stores:Independent shops in Milan and Paris retain advantage in custom builds and professional installation where hands-on expertise remains non-substitutable.
- Motorcycle Dealerships:OEM-aligned channels bundle accessories with new vehicle sales and warranty service packages.
- Events:Track days, rallies, and trade shows enable direct manufacturer-to-rider engagement for premium brand launches and limited-edition releases.
Online retailers are expanding most quickly; specialty stores defend margin through technical services unavailable through digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational riders in Germany and the United States anchor premium equipment spending, while India's commuter base drives volume throughput. Regulatory divergence across ECE, DOT, and BIS jurisdictions fragments certification requirements. Manufacturing clusters concentrate in northern Italy, southern Germany, and Gujarat.
Germany
ECE R22.06 enforcement eliminates non-compliant helmet inventory from retail channels, pulling replacement demand from safety-conscious touring enthusiasts. KBA homologation requirements for vehicle-linked accessories create compliance barriers for aftermarket electronics suppliers. Bavaria's industrial corridor hosts specialized carbon-fiber shell manufacturers serving premium helmet brands.
United States
NHTSA's Federal Motor Vehicle Safety Standard No. 218 governs helmet penetration and retention testing for the recreational rider segment. Garmin GPS units and Bluetooth intercoms anchor accessory spending patterns among weekend touring enthusiasts. Southern California's custom build shops retain advantage in professional installation where tactile assessment dominates purchase decisions.
India
BIS certification requirements for two-wheeler components filter import access and shape domestic production scale as ownership broadens into tier-2 and tier-3 cities. The PLI scheme for automotive components incentivizes local assembly of protective apparel. Gujarat's manufacturing belt concentrates affordable helmet production for the expanding commuter base.
Italy
REACH's PFAS restrictions force DWR coating reformulation across textile suppliers serving the premium protective jacket segment. Milan's specialty retailers defend margin through custom builds and hands-on expertise unavailable through digital channels. The northern industrial cluster integrates aramid fiber processing with CE-certified armor manufacturing for track-day equipment.
Japan
METI standards for connected-vehicle systems influence integration protocols for helmet telemetry and rider-assistance electronics. Kanto-based electronics manufacturers supply miniaturized sensors for heads-up display optics in premium carbon-fiber helmets. Tokyo's dealer networks bundle accessories with new vehicle sales and warranty service packages.
Motorcycle Accessories Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. Brembo S.p.A. and Garmin Ltd. anchor premium positioning through braking-system expertise and GPS navigation respectively. Alpinestars USA Inc. occupies the protective apparel specialization tier. Competitive moves concentrate on technology licensing for connected-helmet integration and geographic expansion into underpenetrated certification jurisdictions.
Within the premium-tier vector, Brembo S.p.A. and Garmin Ltd. exemplify technology-anchored positioning, while Alpinestars USA Inc. represents apparel specialization. These entities sit within a competitive structure where European and North American players leverage regulatory pre-certification to access emerging markets. Italian and German manufacturers occupy positions tied to ECE harmonization advantages. The competitive dynamic rewards integrated R&D capabilities over pure assembly as rotational-impact testing mandates compress design cycles.
| Leading Market Players |
|---|
| TVS Motor Company |
| Brembo S.p.A. |
| Harley-Davidson, Inc. |
| Garmin Ltd. |
| GIVI S.P.A. |
| Yamaha Motor Co., Ltd. |
| Alpinestars USA Inc. |
| FOX Head Inc. |
| Hero MotoCorp Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gujarat's helmet assembly corridor is compressing supplier margins and triggering aggressive pricing postures for entry-level commuter gear. DuPont and Teijin's grip on para-aramid fiber allocation forces protective apparel manufacturers to absorb input volatility or push cost escalation downstream.
Pricing Analysis
Cost-plus contracts with aramid fiber indexation dominate raw material procurement for premium helmet and jacket manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates MIPS-equipped carbon-fiber helmets from basic ABS-shell commuter models from non-certified regional alternatives. Price differentiation hinges on ECE R22.06 certification grade and volume scale, with bulk fleet orders for India's tier-2 cities commanding steep discounts. Pricing pressure stems from legacy pre-R22.06 inventory liquidation in European channels. Commuters in India's expanding tier-3 markets exhibit highest price sensitivity; professional racers seeking FIM-homologated heads-up display integration show least.
Supply Chain Analysis
Contract manufacturing concentrates among Taiwanese electronics foundries supplying helmet telemetry sensors and Italian carbon-fiber shell fabricators serving premium brands. Geographic supply concentration centers on China for thermoplastic polymer injection molding, India for textile cut-and-sew operations, and Germany for precision EPS liner production. Raw material dependencies include para-aramid fibers from DuPont and Teijin, dual-density EPS formulations from BASF and SABIC, and carbon-fiber prepregs from Toray Industries. Single-source vulnerability in aramid fiber allocation exposes manufacturers to allocation rationing during demand surges. Distribution runs through online retailers aggregating volume with fitment algorithms, specialty stores defending margin through custom build expertise, and OEM dealerships bundling with warranty packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECE R22.06's rotational-impact mandate constitutes a high-growth disruption, forcing material upgrades and replacement demand across Europe's installed base while compressing design cycles for unprepared suppliers.
For Market Incumbents: Pre-empt margin erosion by securing captive aramid fiber supply through backward integration into Teijin or DuPont distribution partnerships, and accelerate MIPS technology licensing to Asian contract manufacturers before certification mandates spread beyond Europe. Legacy inventory obsolescence in pre-R22.06 helmets represents the primary threat; channel control through direct-to-rider subscription replacement programs offers defensive leverage.
For New Entrants and Emerging Players: Build out local assembly partnerships in Brazil ahead of ANVISA's ECE harmonization, targeting the underpenetrated premium protective apparel segment where European suppliers lack established distribution. India's tier-2 commuter expansion offers volume white-space for affordable CE-certified armor integration. Go-to-market execution should prioritize video-enabled purchasing platforms with algorithmic fitment tools to bypass specialty retail gatekeepers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected-helmet electronics sub-segments as sensor miniaturization and heads-up display integration demand specialized R&D infrastructure. Long-term viability favors vertically integrated players controlling both carbon-fiber shell manufacturing and telemetry firmware development. Acquisition target archetype: mid-cap MIPS technology licensors with established ECE pre-certification and dormant Asian distribution relationships. Signal to watch: BIS adoption of rotational-impact testing protocols, which would replicate Europe's replacement demand dynamic in India's volume market.
| Strategic Initiative | Industry Significance |
|---|---|
| ECE R22.06 Pre-Certification Investment | Unlocks access to Brazil's ANVISA-harmonized market ahead of competitors. |
| Aramid Fiber Supply Agreement | Secures allocation priority from DuPont and Teijin during demand surges. |
| Direct-to-Rider Subscription Launch | Bypasses retail markups through mileage-based helmet replacement programs. |
| MIPS Technology Licensing | Captures premium positioning as fixed-liner designs become obsolete. |
| Connected-Helmet Platform Integration | Overcomes proprietary CAN bus barriers with BMW, Ducati, and Kawasaki. |
Study Parameters
Cross-validation between regulatory filing analysis and distributor procurement data anchors the qualitative findings in this study. Primary interviews with helmet R&D directors, aftermarket category buyers at RevZilla and Amazon, specialty retail owners in Milan and Paris, and BIS certification consultants were synthesized with secondary validation from ECE R22.06 technical documentation, NHTSA FMVSS 218 enforcement records, and India PLI scheme disclosure filings. Bottom-up demand modeling across commuter, recreational, and professional racer segments was triangulated against top-down production capacity estimates from Gujarat and Bavaria manufacturing clusters.
Calibration against historical certification cycle timing and material substitution elasticities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user application intensity, installation technical barrier, and distribution channel economics, with additional granularity on certification jurisdiction tier. CAGRs were derived from regression analysis of replacement demand elasticities and ownership penetration curves. Industry-specific forecast inputs incorporated ECE R22.06 compliance deadlines and India's two-wheeler ownership broadening patterns.
Stress conditions across aramid fiber supply disruption, BIS regulatory acceleration, and ride-hailing substitution in European urban centers were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification harmonization timelines and material cost trajectories. Specific risk factors that could revise projections include REACH PFAS restriction expansion to Asian textile suppliers and proprietary CAN bus protocol barriers intensifying for aftermarket electronics integration. Quarterly review of BIS testing protocol announcements and ANVISA harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Electric Motorsport Market