
 Japan Motorcycle ADAS Market | 2026-2036
Japan Motorcycle ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Motorcycle ADAS Market Insights
Japan's carbon neutrality commitments under the Green Growth Strategy is shifting procurement priorities across mobility sectors. Honda Motor Co., Ltd. leverages its integrated powertrain and electronics divisions to control development timelines for motorcycle-specific ADAS modules. Yamaha Motor Co., Ltd. competes through dedicated R&D investment in compact radar architectures suited to lightweight vehicle platforms. Denso Corporation anchors the supplier tier with manufacturing scale that sustains cost competitiveness for domestic OEM programs.
Motorcycle advanced driver assistance systems integrate multi-modal sensor fusion—combining millimeter-wave radar, monocular cameras, and inertial measurement units—to detect threats across blind spots, forward collision zones, and lane boundaries, with primary purpose of reducing fatalities among powered two-wheeler operators who face disproportionate road death risk. Camera systems and radar sensors dominate the technology stack, with radar sustaining premium pricing due to all-weather reliability requirements in Japan's humid subtropical climate zones. Collision avoidance and emergency braking applications capture the steepest adoption curves as insurers and fleet operators demand measurable incident reduction.
METI's connected mobility framework, JIS standards for vehicle-to-everything communication, and the National Police Agency's traffic safety targets collectively shape product certification pathways and OEM compliance obligations. PMDA-aligned functional safety expectations for automotive-grade electronics extend to motorcycle platforms, raising barriers for non-certified component suppliers. Stakeholders must monitor how METI's next-phase spectrum allocations for V2X communication reshape sensor interoperability requirements and supplier qualification protocols.
Market Dynamics
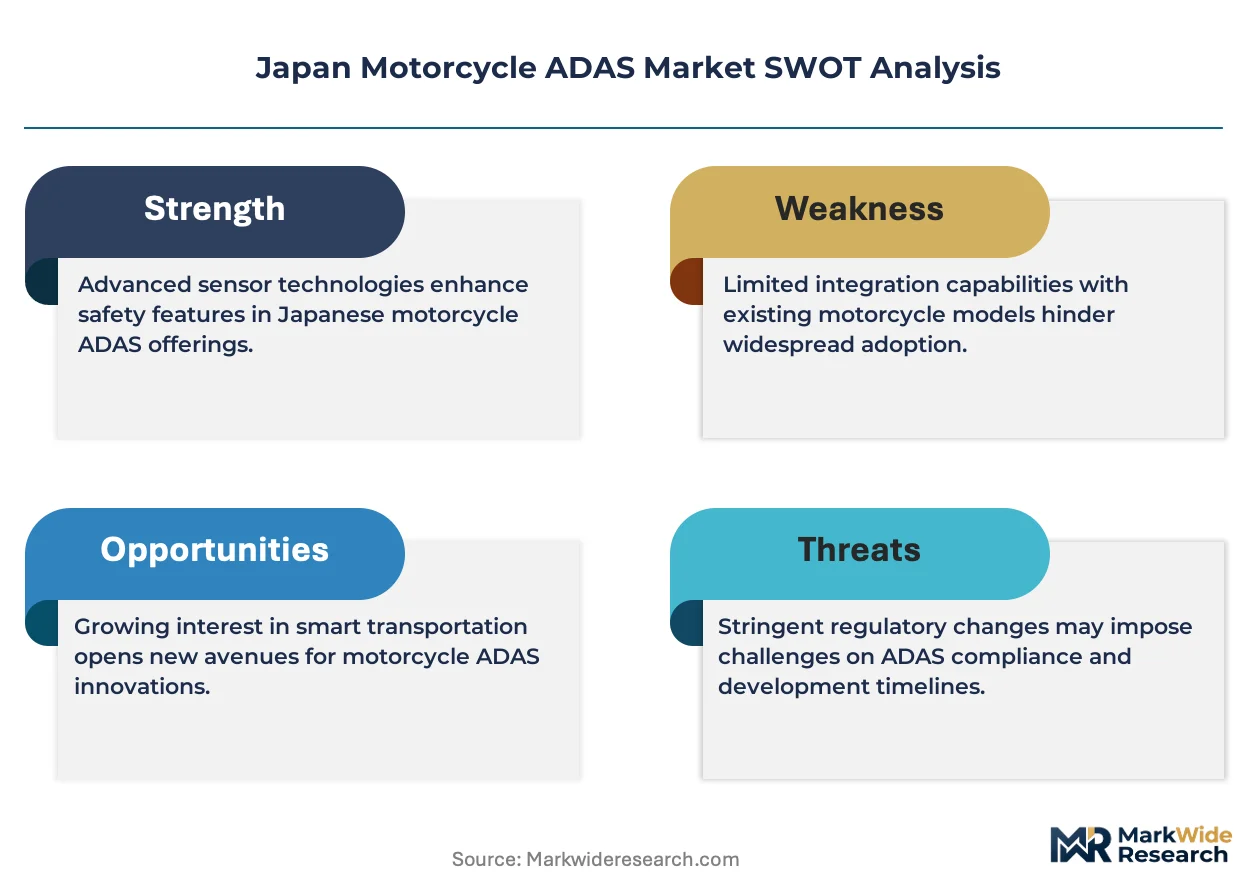
METI's connected vehicle framework is forcing sensor interoperability requirements onto motorcycle platforms faster than supply chains can absorb, compressing development timelines for domestic OEMs while elevating functional safety certification to gatekeeper status for component qualification.
Growth Catalysts
- Fleet operator safety mandates:Commercial delivery services in Tokyo and Osaka corridors prioritize measurable incident reduction, creating volume pull for collision avoidance systems.
- METI spectrum allocation:Japan's Ministry of Economy, Trade and Industry is reallocating dedicated V2X frequency bands, accelerating vehicle-to-infrastructure communication module deployment.
- Radar reliability premiums:Humid subtropical climate conditions across Kyushu and Shikoku sustain pricing power for all-weather millimeter-wave sensors over camera-only alternatives.
Market Restraints
- PMDA functional safety certification costs:Automotive-grade electronics validation for motorcycle platforms requires 18-24 month qualification cycles that exclude non-certified suppliers.
- Sensor package miniaturization limits:Compact radar architectures face thermal management constraints on sub-250cc vehicle frames, restricting addressable unit volumes.
- Domestic OEM supply concentration:Tier 1 manufacturing scale concentrates with Denso Corporation, creating single-source dependency risk for multi-sensor fusion modules.
Strategic Opportunities
- Kansai region fleet penetration:Osaka's commercial logistics density remains underpenetrated relative to Kanto, offering white space for telematics-integrated ADAS bundles.
- JIS V2X standard convergence:Vehicle-to-everything communication mandates create regulatory tailwind for sensor suppliers achieving early interoperability certification.
- Camera-radar fusion architectures:Convergence of monocular vision and millimeter-wave processing is opening mid-tier pricing segments previously served by single-modality systems.
Industry Challenges
- Embedded systems firmware talent scarcity:Functional safety engineering expertise for ISO 26262-aligned motorcycle applications concentrates with automotive suppliers, constraining OEM hiring pipelines.
- Legacy powertrain integration friction:Internal combustion engine control units lack standardized CAN bus protocols for ADAS sensor data ingestion, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Motorcycle ADAS Market |
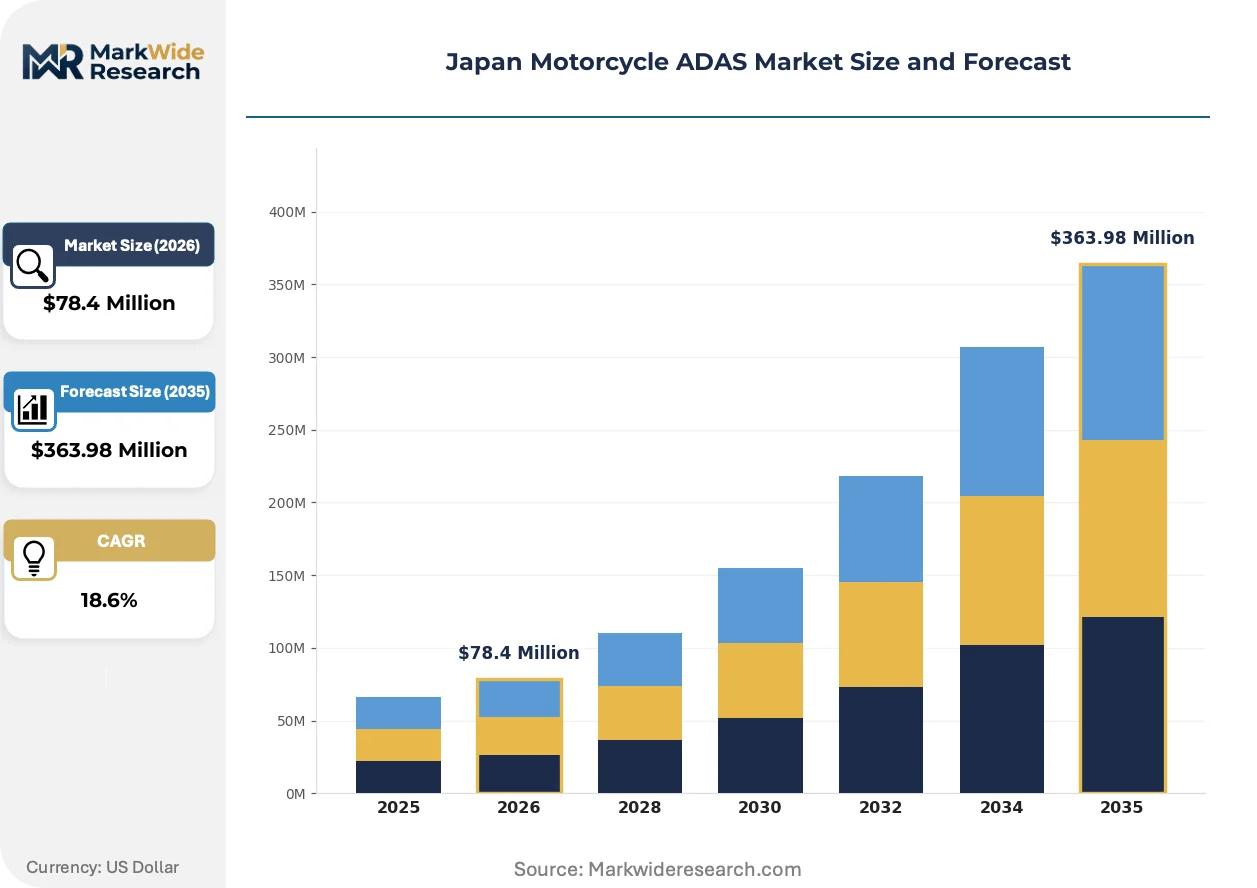
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $363.98 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
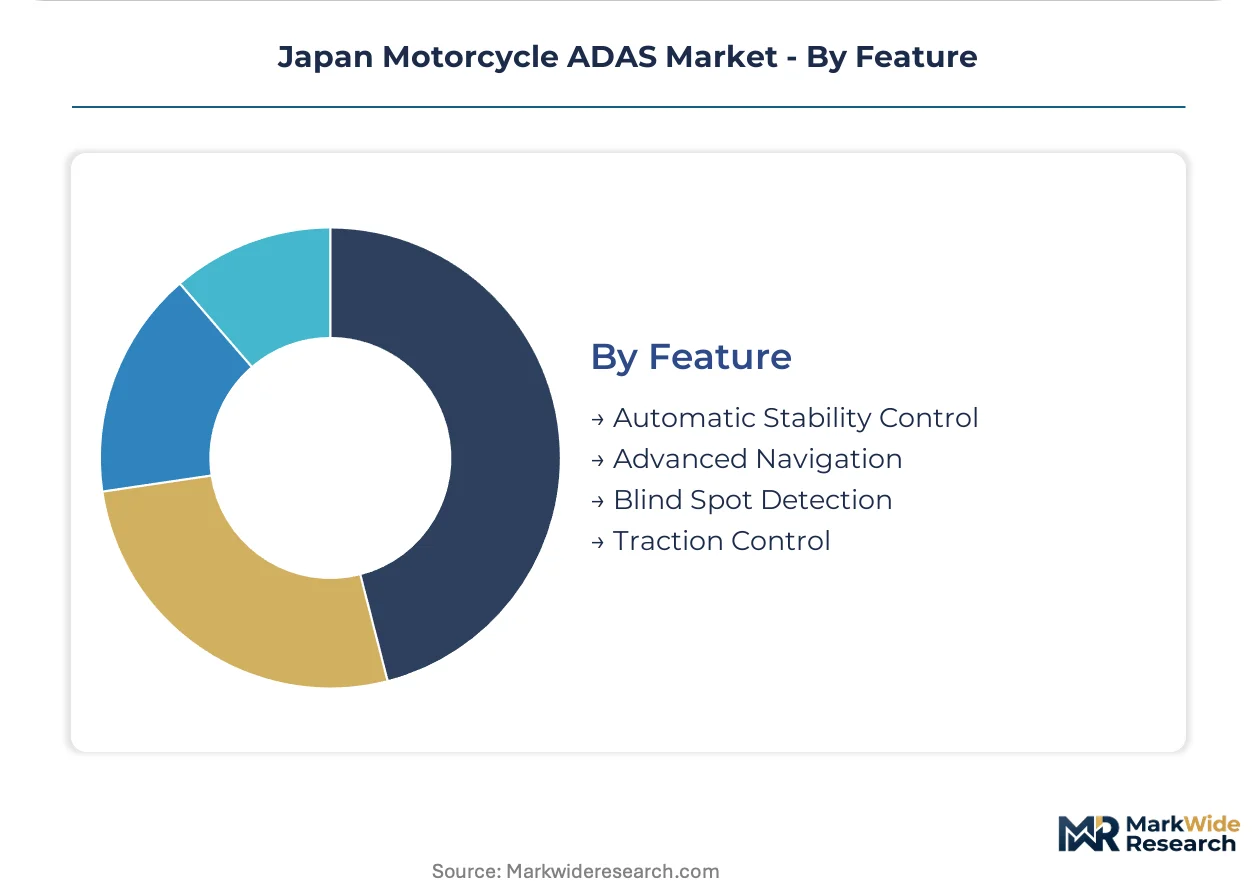
| Segmentation | Technology: Camera Systems, Radar Sensors, LiDAR, Ultrasonic Sensors Application: Collision Avoidance, Adaptive Cruise Control, Lane Departure Warning, Emergency Braking End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Riders Feature: Automatic Stability Control, Advanced Navigation, Blind Spot Detection, Traction Control |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Kawasaki Heavy Industries, Ltd., Suzuki Motor Corporation, Denso Corporation, Robert Bosch GmbH, Continental AG, Nissin Kogyo Co., Ltd., Hitachi Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Motorcycle ADAS Market Trends and Innovations
Multi-modal sensor fusion is compressing the technology stack from discrete components toward integrated perception platforms, with regulatory pressure and climate durability requirements dictating which modalities survive at each price tier.
Millimeter-wave radar is integrating inertial measurement unit data to maintain threat detection through monocular camera occlusion events. Fleet operators in Tokyo's elevated expressway corridors adopt these fused systems fastest, citing insurer premium reductions. The technology is integrating blind-spot monitoring and emergency braking into single hardware packages, collapsing supplier bill-of-materials complexity.
METI's JIS standards for vehicle-to-everything communication are mandating dedicated short-range communication modules on new motorcycle platforms by 2027. This regulatory pressure is redirecting R&D spending from standalone sensor development toward connectivity-integrated architectures. Kanto region OEMs are responding fastest, embedding V2X transceivers within existing radar housing to minimize aerodynamic disruption.
Commercial buyer concentration is consolidating procurement authority toward fleet safety managers who demand incident-reduction guarantees rather than equipment specifications. This behavioral shift is displacing dealer-channel accessory sales with direct OEM fleet contracts. The transformation is most visible in last-mile delivery verticals, where operators negotiate enterprise pricing tied to telematics-validated safety outcomes.
Japan Motorcycle ADAS Market Segmentation
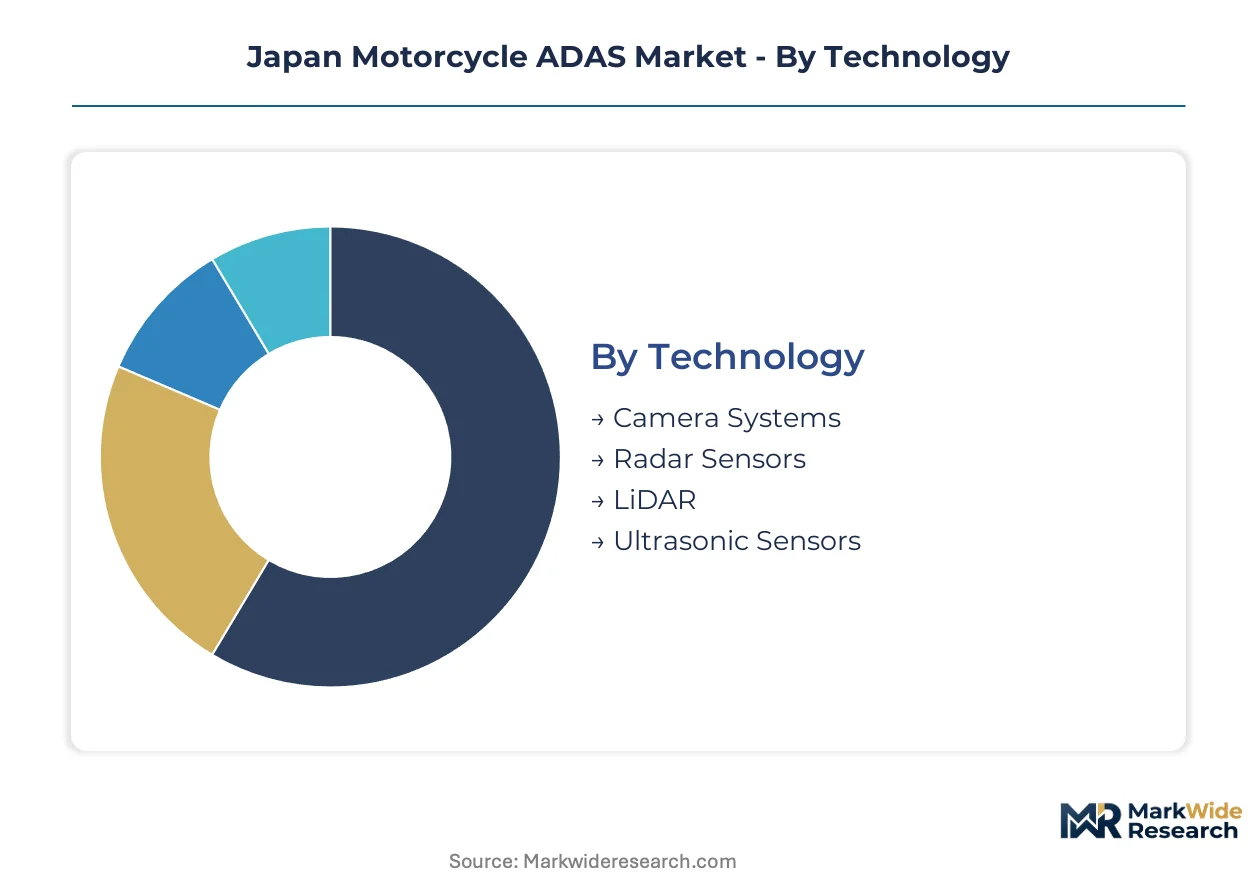
Motorcycle ADAS segmentation in Japan reflects divergent cost-performance tradeoffs across vehicle classes. Technology modality and application intensity vary sharply between premium touring models and sub-250cc urban commuters. Fleet procurement patterns are compressing these traditional tier boundaries through volume-driven standardization.
Technology:
Volume deployment concentrates on single-modality solutions, while premium platforms absorb multi-sensor fusion architectures. Cost tier separation between camera-dominant and radar-integrated systems is narrowing in Kanto fleet contracts.
- Camera Systems:Monocular vision processors deliver lane-keeping and traffic sign recognition at lowest bill-of-materials cost. Tokyo's dense urban corridors drive concentration here, though humid subtropical conditions in Kyushu limit all-weather reliability and sustain demand for sensor redundancy.
- Radar Sensors:Millimeter-wave architectures provide velocity measurement and occlusion penetration for collision avoidance. Pricing premiums persist in Shikoku and coastal regions where precipitation frequency degrades camera performance, with METI's connected vehicle timeline accelerating 77GHz module qualification.
- LiDAR:Solid-state scanning units remain prototyping-stage for motorcycle platforms due to packaging volume constraints.
- Ultrasonic Sensors:Low-frequency proximity detection dominates parking-assist applications on maxi-scooters and three-wheeled vehicles.
Mature deployment sits with Camera Systems. Newer deployment is concentrated in Radar Sensors.
Application:
Commercial buyer mandates are reshaping application priority rankings. Insurer premium reduction programs validate specific safety outcomes rather than equipment lists.
- Collision Avoidance:Forward-looking threat detection combining radar ranging with camera classification. Osaka logistics corridors show steepest fleet adoption as delivery operators negotiate incident-rate guarantees with underwriters.
- Emergency Braking:Autonomous deceleration algorithms calibrated for two-wheeler dynamics and road surface variability. Kanto region OEMs integrate these systems fastest due to National Police Agency traffic safety target alignment.
- Adaptive Cruise Control:Velocity-maintaining functionality primarily deployed on 400cc+ touring motorcycles for highway corridor operation.
- Lane Departure Warning:Haptic and visual alerts for unintended drift, concentrated in premium commuter segments.
Volume concentration favors Collision Avoidance. Margin expansion concentrates in Emergency Braking.
End User:
Procurement authority is migrating from dealer networks to enterprise safety managers. Direct OEM-fleet contracting is displacing accessory-channel sales in commercial verticals.
- Fleet Operators:Commercial delivery services with measurable incident reduction mandates. Tokyo and Osaka corridors represent primary volume pull, with telematics-validated outcomes driving contract terms.
- OEMs:Factory-integrated ADAS modules on new vehicle platforms. Honda and Yamaha control development timelines through captive electronics divisions, compressing supplier qualification windows.
- Aftermarket Providers:Retrofit installations for existing vehicle parc, constrained by PMDA functional safety certification barriers.
- Individual Riders:Dealer-channel accessory purchases, losing share to OEM-embedded solutions as standard equipment penetration rises.
Contract value concentrates with Fleet Operators. Installation complexity limits Aftermarket Providers.
Feature:
Feature bundling is collapsing discrete functions into integrated perception platforms. JIS V2X standards are redirecting development toward connectivity-embedded architectures.
- Blind Spot Detection:Rearward-looking radar or camera monitoring of adjacent lane occupancy. Elevated expressway corridors in Kanto drive fastest adoption, with sensor integration into mirror housings minimizing aerodynamic disruption.
- Automatic Stability Control:Inertial measurement unit feedback to powertrain and braking systems. Premium touring motorcycles deploy these systems as differentiation features.
- Traction Control:Wheel slip mitigation through ignition timing and throttle intervention, standard on performance-oriented platforms.
- Advanced Navigation:Head-up display integration with hazard alerting, concentrated in 650cc+ vehicle classes.
Regulatory tailwind favors Blind Spot Detection. Technology maturity concentrates in Automatic Stability Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Kanto corridor concentrates Japan's motorcycle ADAS deployment, with dense urban expressways and elevated road networks creating the highest incident-risk environments for two-wheeler commuters and commercial delivery fleets.
Kanto/Tokyo
Commercial delivery density and elevated expressway corridors drive collision avoidance system demand. METI's connected vehicle framework mandates V2X module integration by 2027. Fleet operators in Tokyo's 23 wards negotiate enterprise contracts tied to telematics-validated safety outcomes.
Kansai/Osaka
Logistics corridors connecting Osaka, Kobe, and Kyoto generate underpenetrated fleet volume relative to Kanto. National Police Agency traffic safety targets align with emergency braking adoption. Commercial operators in the Hanshin Industrial Region prioritize incident-rate guarantees with insurers.
Chubu/Nagoya
Automotive supplier concentration around Toyota City accelerates radar module manufacturing scale. PMDA functional safety certification requirements elevate barriers for non-certified component suppliers. Tier 1 electronics fabricators in Aichi Prefecture control multi-sensor fusion development timelines.
Kyushu
Humid subtropical climate conditions sustain pricing premiums for all-weather millimeter-wave radar over camera-only alternatives. Precipitation frequency degrades monocular vision performance in Fukuoka's coastal corridors. Shikoku-facing ports see concentrated demand for sensor redundancy.
Hokkaido
Extended winter conditions and road surface variability create specialized traction control demand. Cold-weather battery performance constraints affect ADAS module reliability. Sapporo's urban delivery networks represent a niche testing ground for climate-hardened sensor architectures.
Japan Motorcycle ADAS Market Competitive Landscape
The competitive structure tilts toward integrated OEM electronics divisions over independent component suppliers. Domestic motorcycle manufacturers leverage captive powertrain and sensor development capabilities, compressing supplier qualification windows. Two archetypes dominate: vertically integrated OEM electronics divisions and Tier 1 automotive suppliers with motorcycle-adjacent portfolios. Competitive moves center on strategic partnerships for V2X interoperability certification and portfolio diversification into camera-radar fusion architectures.
Among Japan-based integrated manufacturers, Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., and Denso Corporation occupy distinct competitive positions. Honda exemplifies the captive electronics archetype through consolidated powertrain and ADAS module development. Yamaha represents dedicated R&D investment in compact sensor architectures suited to lightweight platforms. Denso anchors the supplier tier with manufacturing scale sustaining cost competitiveness for domestic OEM programs.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Kawasaki Heavy Industries, Ltd. |
| Suzuki Motor Corporation |
| Denso Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Nissin Kogyo Co., Ltd. |
| Hitachi Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive electronics divisions at Honda and Yamaha function as vertically integrated profit centers, insulating tier-one pricing from external margin compression while METI certification timelines extend supplier qualification windows. This ownership pattern concentrates pricing power with OEMs who internalize sensor fusion development, forcing independent suppliers to absorb functional safety validation costs or exit the motorcycle ADAS tier.
Pricing Analysis
Outcome-based pricing tied to telematics-validated incident reduction anchors fleet contract negotiations in Tokyo and Osaka corridors. Three-tier pricing structure across premium radar-fusion, standard camera-dominant, and economy single-sensor tiers reflects PMDA certification grade and volume scale. Pricing pressure stems from commercial buyer consolidation toward enterprise safety managers who demand guaranteed loss ratios. Fleet operators exhibit highest price sensitivity; premium touring OEMs show lowest sensitivity due to feature-differentiation requirements.
Supply Chain Analysis
Functional safety engineering talent scarcity in Aichi and Kanagawa prefectures constrains radar module manufacturing scale, compressing output timelines for Denso and Hitachi production facilities. Japan, Germany, and Taiwan anchor millimeter-wave component fabrication, drawing from silicon germanide substrates, automotive-grade PCBs, and precision-machined antenna housings. Single-source vulnerability concentrates with Denso Corporation's multi-sensor fusion module dominance. Distribution runs through captive OEM channels and direct fleet contracting, bypassing traditional aftermarket wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PMDA certification capacity acts as the binding constraint, with eighteen-month qualification queues propping pricing premiums for certified suppliers while excluding uncertified competitors from fleet procurement shortlists.
For Market Incumbents: Acquire compact radar architecture IP from distressed European automotive suppliers to fill thermal management gaps in sub-250cc platforms. Consolidate V2X interoperability certification ahead of METI's 2027 mandate to lock out non-compliant component vendors. Denso's manufacturing scale and Honda's captive electronics division exemplify defensive positioning against emerging LiDAR entrants. For New Entrants and Emerging Players: METI's JIS V2X standard convergence in Japan opens a window for telematics-integrated ADAS bundles targeting Kansai fleet operators. White space concentrates in Osaka logistics corridors where incident-rate guarantees remain unpenetrated relative to Tokyo. Camera-radar fusion architectures at mid-tier price points offer the most penetrable entry vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor Tier 2 automotive electronics fabricators in Chubu with dormant motorcycle ADAS qualification. Long-term viability hinges on five-to-ten year OEM platform integration timelines. Watch for METI spectrum allocation announcements as inflection indicators for V2X module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| V2X Interoperability Certification | METI's 2027 mandate locks in supplier qualification protocols for connected motorcycle platforms. |
| Camera-Radar Fusion Platform | Integrated perception architectures collapse bill-of-materials complexity for Kanto fleet contracts. |
| Thermal Management R&D Investment | Compact radar packaging for sub-250cc frames expands addressable unit volumes in urban commuter segments. |
| Direct Fleet Contracting Channel | Enterprise safety manager relationships displace dealer-channel accessory sales in commercial verticals. |
| Functional Safety Talent Acquisition | ISO 26262-aligned firmware expertise concentrates hiring pipelines with automotive-grade electronics suppliers. |
Research Methodology
Multi-period observation of METI regulatory filings, PMDA certification timelines, and fleet procurement contract structures anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet safety managers at commercial delivery operators, and aftermarket distribution heads. Secondary validation drew from JIS standard publication records, National Police Agency traffic safety statistics, vehicle production databases, and customs trade data for radar component imports. Bottom-up segment sizing and top-down market triangulation cross-checked volume and value estimates.
Input-output matrices modeled technology modality, application intensity, vehicle class tier, and regional fleet penetration across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic mobility indicators and regulatory milestone timing. Forecast inputs incorporated METI spectrum allocation schedules, PMDA certification queue lengths, and commercial insurance premium reduction program validation criteria.
The model assumes a particular technology adoption path; alternative pathways for solid-state LiDAR miniaturization would alter the outlook for radar-dominant architectures. Forecasts reflect documented assumptions about V2X module integration timelines and fleet operator procurement centralization. Material deviation in METI regulatory enforcement or PMDA certification capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Australia E- Bike Market