
 Motorcycle Fuel Hoses Market | 2026-2036
Motorcycle Fuel Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Fuel Hoses Market Foresight
SAE J30 R9 certification is reorganizing competitive access in motorcycle fuel hoses, filtering out suppliers lacking fuel permeation resistance below 15 g/m²/day. Continental AG leverages captive rubber compounding to lock in compound consistency for premium OEM programs. Gates Corporation anchors North American aftermarket distribution through dealer-direct channels. Sumitomo Riko specializes in thin-wall multilayer constructions for Japanese sportbike platforms.
Motorcycle fuel hoses are flexible tubular conduits engineered from fluorocarbon, nitrile, or thermoplastic elastomer layers to transport gasoline, ethanol blends, or diesel under pressures typically below 10 bar while resisting permeation, ozone, and aromatic swelling. Wall thickness, braid reinforcement pattern, and inner liner fluorination grade determine compatibility with modern biofuel formulations and engine bay thermal cycling. Rubber hoses retain dominant OEM share due to cost-scaled extrusion and established bonding to barbed fittings, though Teflon hoses capture the fastest-growing tier in performance and racing segments where chemical inertness commands premium positioning. Stainless steel braided variants occupy a narrow but high-margin niche in custom and cruiser builds where abrasion resistance and aesthetic finish justify elevated unit economics.
EPA emissions enforcement and CARB permeation caps in the United States, REACH chemical restrictions in Europe, and BIS automotive rubber standards in India collectively dictate material substitution timelines and testing burden for hose manufacturers seeking multi-regional approval. OEMs now require pre-certified sub-assemblies, pushing tier-two extruders toward third-party validation or partnership with established brands. Stakeholders must track regulatory divergence on ethanol blend limits and perfluorinated compound restrictions to avoid stranded inventory in key motorcycle-producing regions.
Market Dynamics
SAE J30 R9 certification mandates are compressing supplier margins while forcing compound reformulation across nitrile and fluorocarbon elastomer supply chains, fundamentally restructuring competitive access in motorcycle fuel hose manufacturing.
Growth Catalysts
- EPA and CARB permeation caps:United States emissions enforcement mandates sub-15 g/m²/day fuel vapor transmission rates, compelling OEMs to source certified multilayer hose constructions and accelerating material upgrade cycles across domestic motorcycle production.
- Ethanol blend expansion:E15 and higher biofuel formulations in key motorcycle markets degrade conventional nitrile rubber, creating replacement demand for fluorinated inner liners and aromatic-resistant compound systems in both factory-fit and aftermarket channels.
- India aftermarket concentration:Two-wheeler fleet expansion and extended vehicle lifespans in Indian urban centers concentrate demand for replacement fuel hoses, with BIS automotive rubber standards driving quality tiering among domestic extruders.
Market Restraints
- Fluorocarbon raw material volatility:Perfluoroelastomer feedstock costs fluctuate with specialty chemical supply constraints, compressing margins for SAE J30 R9 certified hose producers unable to pass through compound cost increases.
- Testing burden concentration:Pre-certified sub-assembly requirements from tier-one OEMs strand tier-two extruders without third-party validation partnerships, creating supply-side bottlenecks in emerging manufacturing regions.
- Thermoplastic substitution pressure:Teflon and thermoplastic elastomer alternatives capture performance segment share, threatening volume-scale rubber hose economics despite higher unit costs in racing and custom applications.
Strategic Opportunities
- Vietnam aftermarket expansion:Motorcycle fleet growth and repair shop density in Vietnamese urban corridors create white space for ethanol-compatible replacement hose distribution through independent service networks.
- Thin-wall multilayer convergence:Integration of fluorinated barriers with aramid reinforcement and thermoplastic outers enables weight reduction for sportbike OEMs seeking thermal cycling performance in compact engine bays.
- Dealer-direct channel innovation:North American aftermarket distributors bypass traditional jobber networks, capturing margin through direct-to-service-bay logistics and same-day availability guarantees for certified hose SKUs.
Industry Challenges
- SAE J30 R9 certification timeline compression:Extended fuel permeation testing protocols and compound validation cycles delay product launches, requiring captive laboratory investment or outsourced validation partnerships that strain mid-cap extruder cash flows.
- REACH chemical restriction alignment:European perfluorinated compound phase-out timelines diverge from EPA ethanol blend mandates, forcing dual-compound inventory strategies that complicate multi-regional supply chain configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Fuel Hoses Market |
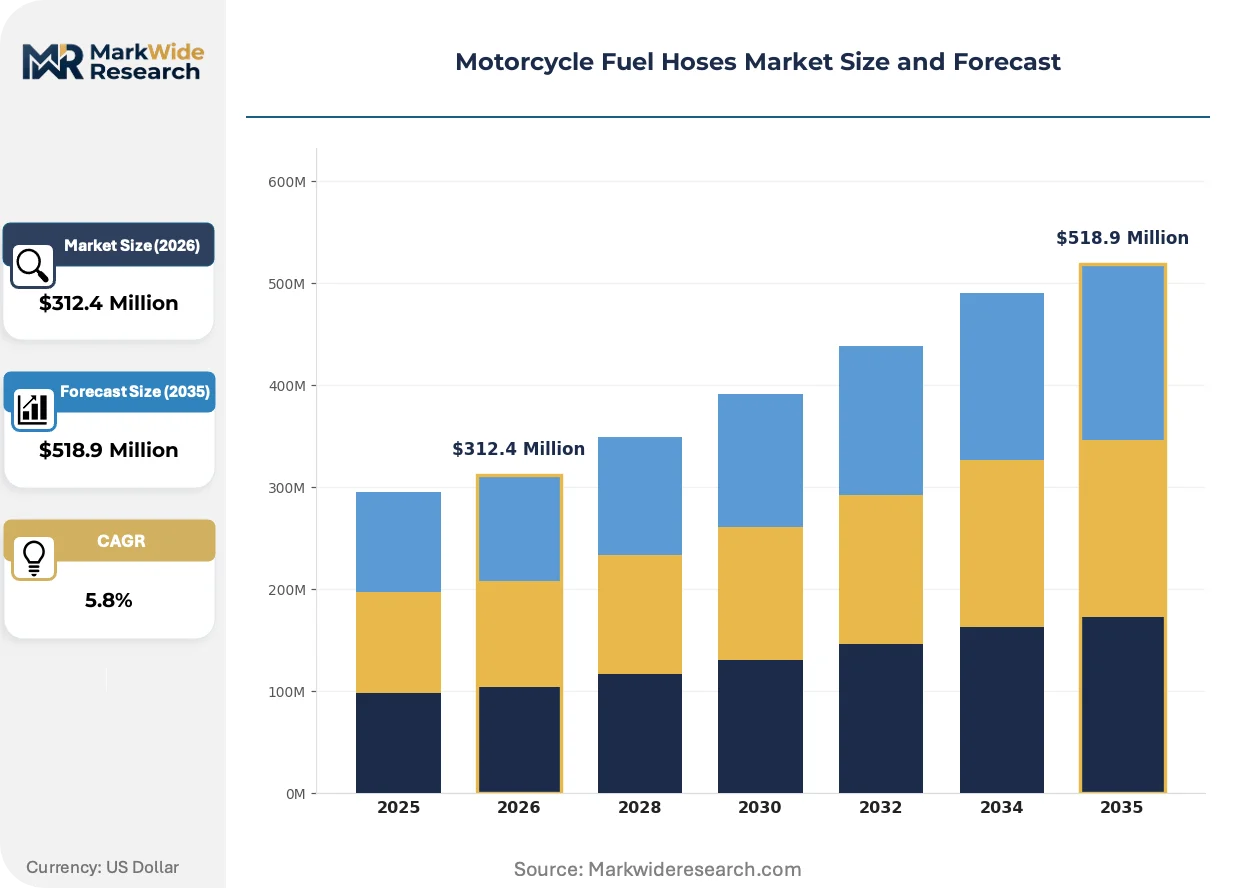
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Hoses, Stainless Steel Hoses, PVC Hoses, Teflon Hoses Diameter: 6 mm, 8 mm, 10 mm, 12 mm End User: OEMs, Aftermarket Providers, Dealerships, Repair Shops Application: Fuel Systems, Lubrication Systems, Cooling Systems, Others |
| Companies Covered | Continental AG, Gates Corporation, Sumitomo Riko, Parker Hannifin Corporation, Manuli Hydraulics, Hutchinson SA, Codan Rubber, Eaton Corporation, Goodridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Fuel Hoses Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape motorcycle fuel hose construction, with fluorination depth, braid architecture, and thermal barrier integration becoming primary differentiation vectors.
Fluorinated ethylene propylene inner liners are displacing conventional nitrile rubber in premium OEM programs. Japanese sportbike manufacturers specify sub-millimeter fluorocarbon barriers to meet SAE J30 R9 permeation thresholds without diameter expansion. This construction is displacing thicker-walled rubber alternatives in factory-fit applications where packaging constraints dominate design trade-offs.
REACH chemical restrictions in Europe are accelerating perfluorinated compound substitution timelines. ECHA regulatory pressure forces reformulation of traditional FKM compounds toward lower-fluorine alternatives or hybrid thermoplastic barriers. Aftermarket suppliers serving EU member states face stranded inventory risk if compound transitions lag restriction implementation dates.
Service-interval compression in commercial motorcycle fleets is shifting procurement toward preventive replacement schedules. Fleet operators in Indian logistics corridors now specify hose change intervals aligned with oil service cycles, displacing failure-driven aftermarket demand with contracted volume commitments to authorized distributor networks.
Motorcycle Fuel Hoses Market Segmentation
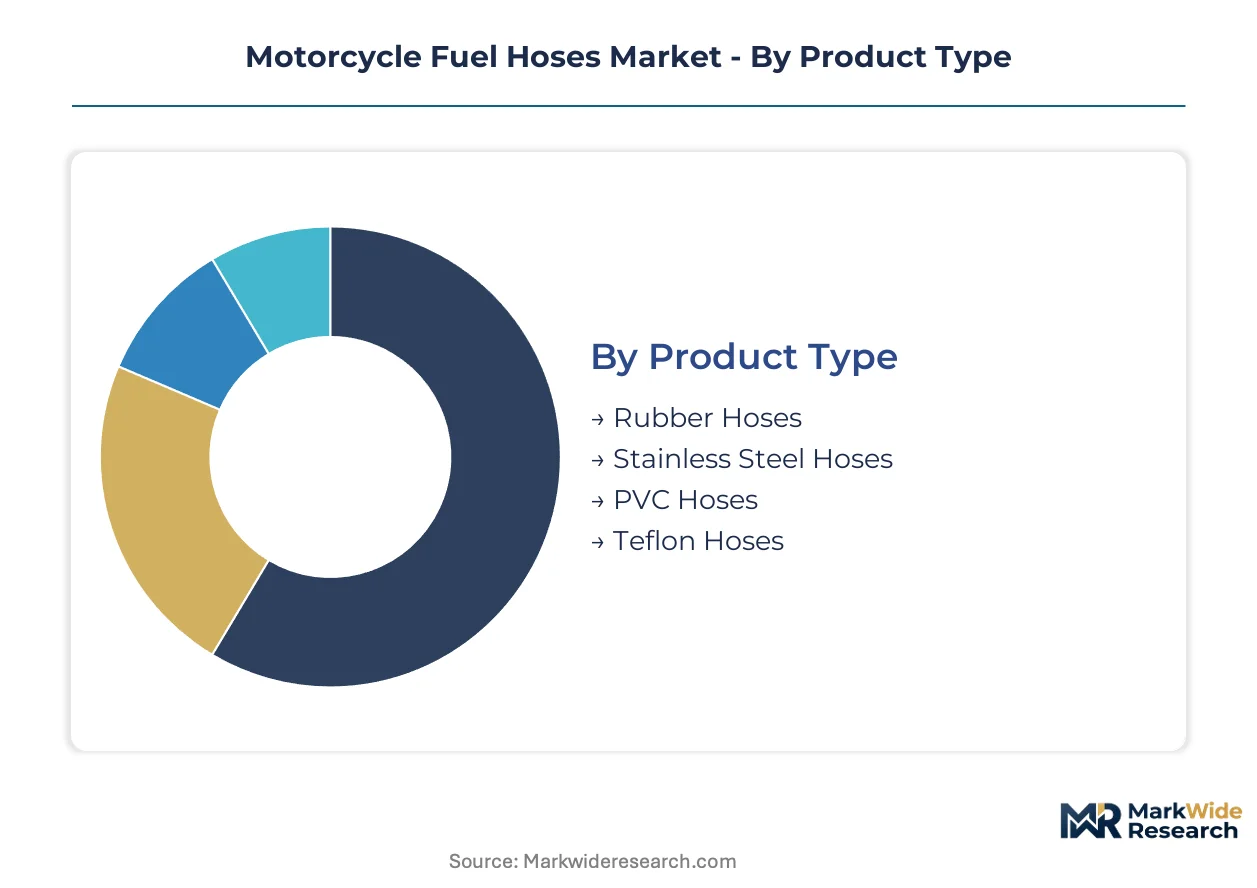
Motorcycle fuel hose segmentation reflects divergent material science capabilities and regulatory compliance tiers across manufacturing channels. Product type and diameter specifications determine permeation resistance thresholds, while end-user and application splits reveal where SAE J30 R9 certification concentrates economic value.
Product Type:
Fluorocarbon and thermoplastic alternatives are displacing conventional rubber constructions in segments where ethanol compatibility commands premium positioning.
- Rubber Hoses:Nitrile and fluorocarbon elastomer extrusions dominate factory-fit volume through cost-scaled production and established barbed-fitting integration. Indian OEM programs and Vietnamese aftermarket channels concentrate demand for SAE J30 R9 certified rubber constructions as BIS standards tighten quality tiering.
- Teflon Hoses:Polytetrafluoroethylene inner liners deliver chemical inertness for E15+ ethanol blends and aromatic resistance in performance motorcycle builds. Japanese sportbike manufacturers specify thin-wall PTFE constructions for thermal cycling endurance in compact engine bays.
- Stainless Steel Hoses:Braided 304-grade outer reinforcement targets custom cruiser segments where abrasion resistance and aesthetic finish justify elevated unit economics.
- PVC Hoses:Thermoplastic constructions serve economy-tier replacement demand in price-sensitive emerging markets lacking stringent permeation enforcement.
Rubber hoses anchor the volume base while Teflon constructions gain share at the steepest rate.
Diameter:
Engine displacement and fuel injection pressure specifications dictate diameter selection across sportbike, commuter, and cruiser platforms.
- 6 mm:Thin-wall constructions serve sub-150cc commuter motorcycles with carbureted fuel systems and low-pressure delivery requirements.
- 8 mm:Mid-range diameter dominates 150-250cc production motorcycle volume across Indian and Southeast Asian manufacturing.
- 10 mm:Large-bore fuel injection systems in performance motorcycles and commercial fleet applications specify this diameter for flow rate optimization.
- 12 mm:Heavy-duty cruiser and touring motorcycle platforms with high-displacement engines utilize maximum-diameter hoses for pump-fed delivery systems.
Eight-millimeter specifications capture the highest shipment volumes across mass-market production, while ten-millimeter demand expands most quickly in fuel-injected performance segments.
End User:
Certification requirements and procurement scale separate factory-fit programs from fragmented aftermarket channels.
- OEMs:Factory-fit programs demand pre-certified sub-assemblies with validated compound consistency and permeation documentation. Tier-one motorcycle manufacturers in Japan and India source directly from established extruders with captive laboratory capabilities.
- Aftermarket Providers:Independent distributors and private-label suppliers serve replacement demand through dealer-direct and jobber networks, with ethanol-compatible SKUs commanding quality tier premiums.
- Dealerships:Authorized service networks procure certified hose assemblies for warranty-compliant repairs, particularly in North American markets with EPA enforcement visibility.
- Repair Shops:Independent mechanics in Vietnamese and Indian urban corridors drive volume for economy-tier replacements, with fleet operators shifting toward preventive replacement contracts.
OEM procurement concentrates value in certified premium tiers, while repair shop volume is expanding fastest through fleet service-interval compression.
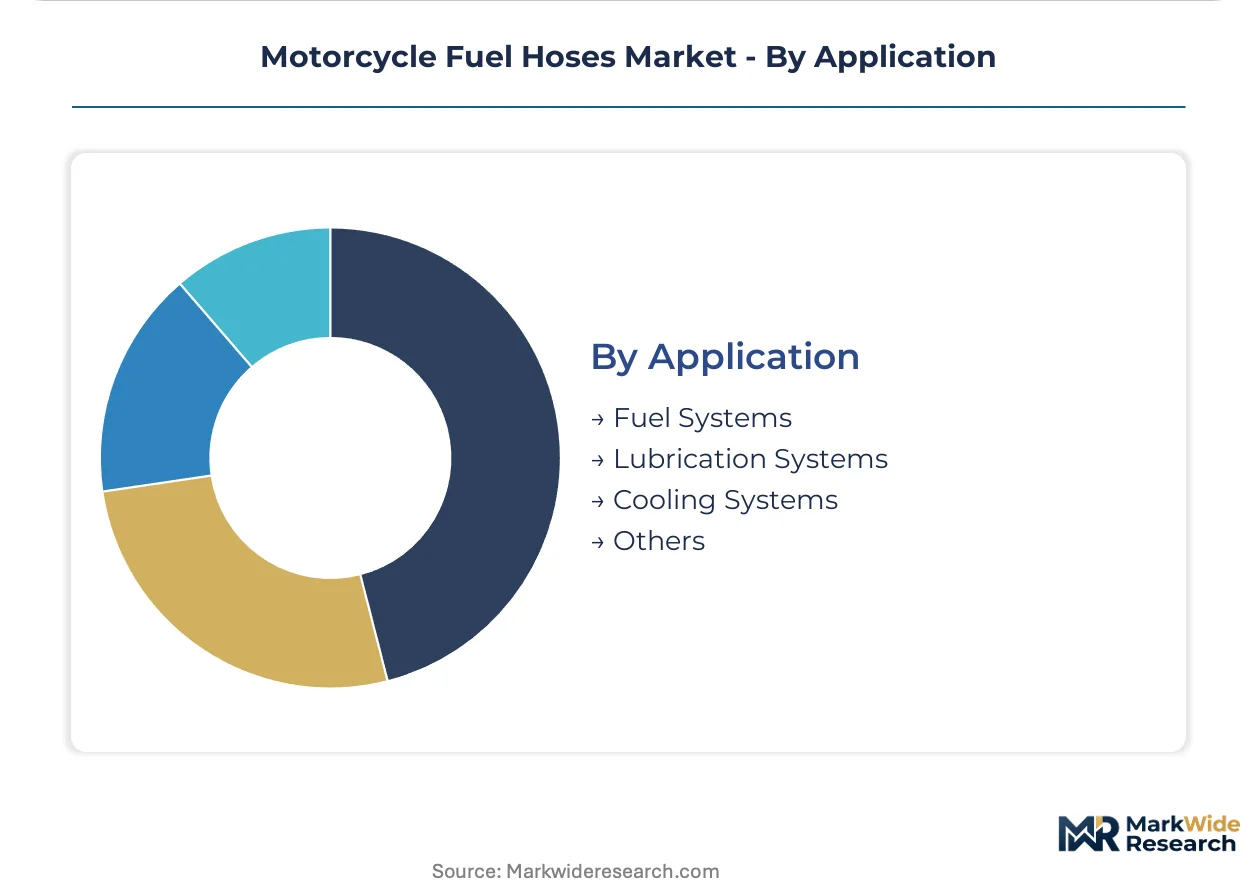
Application:
Thermal cycling exposure and fluid compatibility separate fuel system specifications from auxiliary hose applications.
- Fuel Systems:Gasoline and ethanol blend delivery demands multilayer constructions with fluorinated barriers meeting sub-15 g/m²/day permeation thresholds. CARB and EPA enforcement in the United States mandates SAE J30 R9 certification for factory-fit and replacement applications.
- Lubrication Systems:Engine oil and transmission fluid hoses utilize nitrile rubber without fluorination, serving lower permeation requirements in crankcase ventilation and oil cooler circuits.
- Cooling Systems:Ethylene glycol and water mixture compatibility drives EPDM or silicone hose specifications for radiator and heater circuit applications.
- Others:Vacuum lines, breather hoses, and auxiliary fluid conduits employ simplified single-layer constructions with minimal regulatory testing burden.
Fuel system applications concentrate regulatory compliance investment, while cooling system specifications follow the steepest substitution trajectory toward integrated thermal management modules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA and CARB permeation caps in the United States, REACH chemical restrictions in Europe, and BIS automotive rubber standards in India are forcing material substitutions across motorcycle fuel hose manufacturing corridors. These regulatory frameworks now dictate where certified production concentrates and which extruders capture multi-regional approval.
United States
CARB's sub-15 g/m²/day fuel vapor transmission mandate drives OEM sourcing toward SAE J30 R9 certified multilayer constructions. EPA enforcement visibility pushes authorized service networks toward pre-certified hose assemblies for warranty-compliant repairs. California's regulatory stringency radiates eastward, influencing Midwest manufacturing clusters supplying domestic motorcycle assembly plants.
Germany
ECHA regulatory pressure on perfluorinated compounds accelerates FKM reformulation toward lower-fluorine alternatives or hybrid thermoplastic barriers. Continental AG's captive rubber compounding capabilities anchor premium OEM program supply from Baden-Württemberg and Lower Saxony production facilities. Aftermarket suppliers face stranded inventory risk if compound transitions lag restriction implementation dates across EU member states.
India
BIS automotive rubber standards tighten quality tiering among domestic extruders serving two-wheeler fleet expansion in Mumbai, Delhi, and Bangalore urban corridors. Extended vehicle lifespans concentrate replacement demand for certified rubber constructions. Fleet operators in logistics corridors now specify preventive hose change intervals aligned with oil service cycles.
Japan
METI industrial standards and JIS certification requirements shape thin-wall multilayer specifications for sportbike manufacturers. Sumitomo Riko specializes in fluorinated barrier constructions meeting sub-millimeter packaging constraints for compact engine bays. Tokyo and Osaka metropolitan manufacturing clusters supply directly to tier-one motorcycle OEMs with validated compound consistency documentation.
Vietnam
Motorcycle fleet growth in Ho Chi Minh City and Hanoi urban corridors creates white space for ethanol-compatible replacement hose distribution. Independent repair shop density drives volume for economy-tier products lacking stringent permeation enforcement. Aftermarket expansion through independent service networks captures demand from aging vehicle populations.
Motorcycle Fuel Hoses Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive polymer compounding capabilities and specialized rubber extruders serving regional aftermarket channels. The competitive structure tiers across three archetypes: integrated material-science conglomerates controlling upstream elastomer supply, mid-cap extruders with third-party validation partnerships, and regional fabricators competing on price in less regulated corridors. Dominant competitive moves include backward integration into specialty rubber compounding and geographic expansion through dealer-direct distribution networks bypassing traditional jobber intermediaries.
Among diversified industrial conglomerates, Continental AG and Gates Corporation exemplify scale-driven positions anchored by material science capabilities and North American aftermarket distribution infrastructure respectively. Parker Hannifin Corporation occupies a position within the precision-engineering tier. Sumitomo Riko represents the thin-wall specialization archetype serving Japanese sportbike OEM requirements. These named entities serve as anchors for understanding how competitive positioning stratifies across certification tiers, geographic reach, and compound control rather than as exhaustive market coverage.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Sumitomo Riko |
| Parker Hannifin Corporation |
| Manuli Hydraulics |
| Hutchinson SA |
| Codan Rubber |
| Eaton Corporation |
| Goodridge |
| Others |
Supply & Pricing Matrix
Captive rubber compounding at scale anchors cost structures for SAE J30 R9 certified hose producers, concentrating margin control among integrated manufacturers while tier-two extruders face price floors dictated by third-party validation fees and fluorocarbon feedstock volatility. This scale asymmetry compresses returns for non-integrated suppliers serving Indian and Vietnamese aftermarket channels where BIS standards and informal repair networks create divergent quality tiers.
Pricing Analysis
Certification level creates the primary spread between premium SAE J30 R9 constructions and economy-tier PVC alternatives. Three-tier pricing structure across certified multilayer, standard rubber, and economy thermoplastic levels reflects compound cost, permeation testing burden, and OEM validation status. Cost compression in standard rubber tiers intensifies because fluorocarbon feedstock volatility outpaces pass-through capacity. Fleet operators in Indian logistics corridors exhibit highest price sensitivity, while Japanese sportbike OEMs prioritize sub-millimeter thin-wall performance over unit cost.
Supply Chain Analysis
Specialty fluorocarbon resin availability from German and Japanese chemical manufacturers anchors certified hose production capacity. Raw material flows draw from perfluoroelastomer feedstock, aramid fiber reinforcement, and nitrile rubber base compounds. Single-source vulnerability concentrates in fluorinated liner supply where REACH chemical restrictions threaten compound continuity. Distribution runs through dealer-direct channels in North America and independent service networks in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Replacement demand cycles in motorcycle fuel hoses track vehicle fleet aging and ethanol mandate implementation, positioning the market for cyclical uplift as E15 expansion accelerates material upgrade requirements across major producing regions.
For Market Incumbents: Shield certified compound formulations through backward integration into captive rubber compounding, locking in consistency for premium OEM programs. Defend channel position by acquiring third-party validation partnerships that tier-two extruders cannot replicate, while monitoring thermoplastic substitution threats in performance segments.
For New Entrants and Emerging Players: Dealer-direct logistics gaps in Vietnamese urban corridors offer white-space entry where incumbent distribution remains jobber-dependent. Target ethanol-compatible SKU availability for independent repair shops lacking same-day certified hose access. Build market presence through preventive replacement contracts with Indian fleet operators before expanding to OEM validation partnerships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thin-wall multilayer specialists with validated fluorinated barrier capabilities over commodity rubber extruders. Five-to-ten-year viability hinges on REACH alignment and EPA ethanol blend trajectory. Watch ECHA perfluorinated compound phase-out timelines as inflection signal for compound transition winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorocarbon Compounding | Captive supply of SAE J30 R9 certified compounds locks in OEM program access against feedstock volatility. |
| Dealer-Direct Channel Expansion | Bypassing jobber networks in North America captures margin through same-day availability guarantees. |
| Thin-Wall Multilayer R&D Investment | Sub-millimeter fluorinated barriers meet Japanese sportbike packaging constraints without diameter expansion. |
| Third-Party Validation Partnership | Pre-certified sub-assembly status enables tier-two extruder participation in OEM sourcing pools. |
| REACH-Compliant Compound Transition | Lower-fluorine FKM alternatives or hybrid thermoplastic barriers prevent stranded inventory in EU markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM procurement managers, aftermarket distributor executives, tier-one extruder plant managers, and regulatory compliance officers at compound manufacturers. Secondary validation drew from EPA enforcement disclosures, ECHA restriction timelines, BIS automotive rubber standards documentation, and SAE J30 certification registries. Bottom-up shipment data from regional manufacturing clusters was triangulated against top-down OEM program sourcing estimates.
Across the analysis window, the forecast framework modeled volume and value outputs through segmentation by material construction, diameter specification, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement rates against fleet age distributions and ethanol blend expansion schedules. Industry-specific inputs included permeation testing protocol timelines, compound reformulation cycles, and channel inventory turnover patterns.
Forecasts assume regulatory continuity in EPA, CARB, and REACH enforcement regimes; material policy shifts would require re-modeling of compound substitution timelines and certification burden trajectories. Practitioners should keep alternative scenarios live as ECHA perfluorinated compound restrictions and EPA ethanol blend mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market