
 Motorcycle Rider Assistance System Market | 2026-2036
Motorcycle Rider Assistance System Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Rider Assistance System Market Analytics
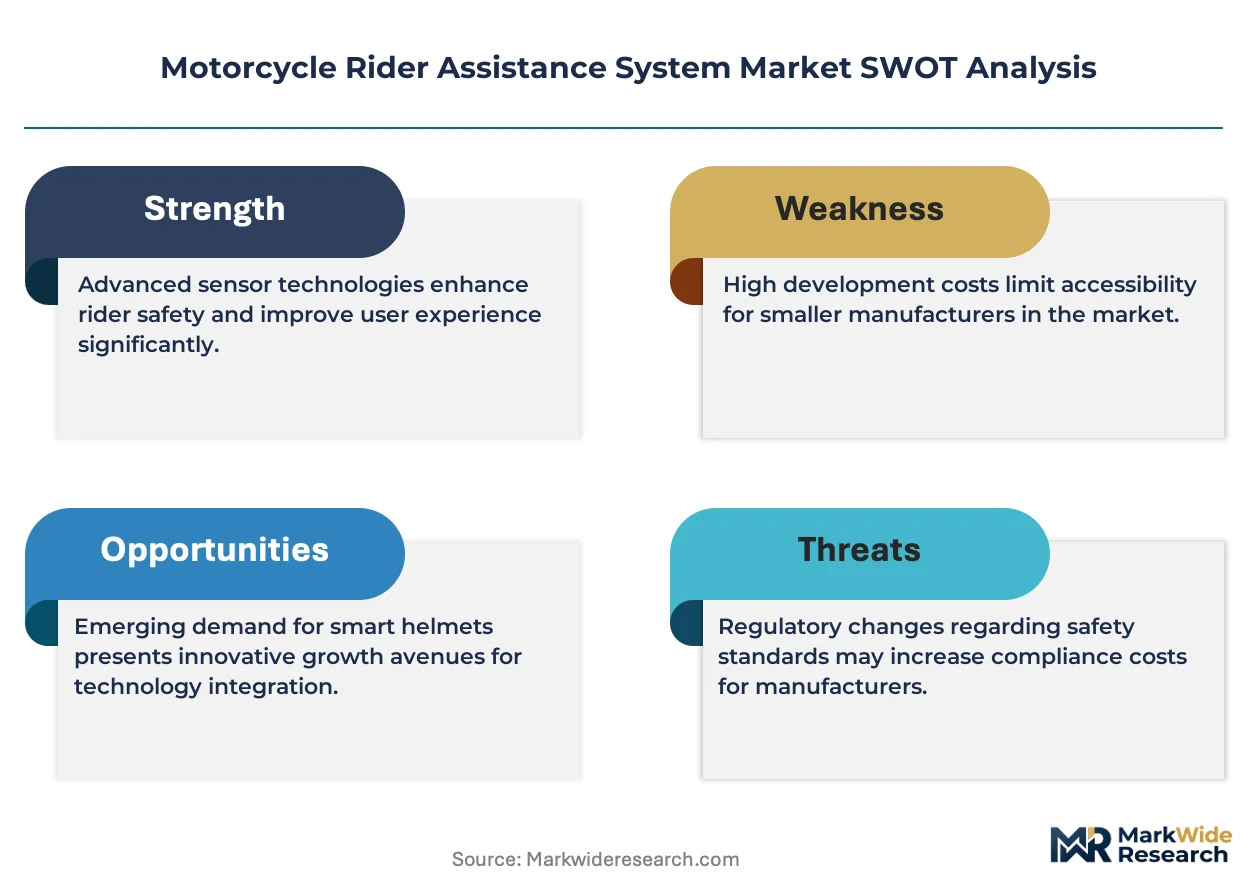
Modular bundling of radar-assisted adaptive cruise control with camera-based collision avoidance is pivoting how OEMs configure safety packages across sport and touring segments. Robert Bosch GmbH leverages its cross-vehicle sensor platform to anchor motorcycle-specific radar development. Continental AG competes through integrated V2X communication modules that extend from automotive into two-wheeler applications. ZF Friedrichshafen AG specializes in compact LiDAR units designed for limited motorcycle fairing space.
A motorcycle rider assistance system comprises sensor arrays, electronic control units, and actuator interfaces that process real-time environmental data to automate or augment braking, throttle, and stability interventions; typical radar units operate at 77 GHz with detection ranges of 150-200 meters for forward collision scenarios. Camera-based systems currently dominate OEM fitment due to lower unit cost and mature image-processing pipelines, while radar systems represent the fastest-growing technology segment as all-weather reliability becomes a purchasing criterion for fleet operators. Aftermarket installation channels occupy a shrinking margin pool as integrated OEM systems become standard on mid-displacement motorcycles.
The European Union's General Safety Regulation and UNECE R79 steering equipment standards shape product certification timelines for adaptive cruise control and lane-keeping assistance in member states. NHTSA in the United States and Japan's METI coordinate through bilateral regulatory dialogues on motorcycle-specific advanced driver assistance system equivalency, reducing redundant homologation costs for suppliers. Stakeholders must monitor whether emerging brake-assistance mandates in major motorcycle markets will accelerate sensor fusion requirements or fragment technology roadmaps across regulatory jurisdictions.
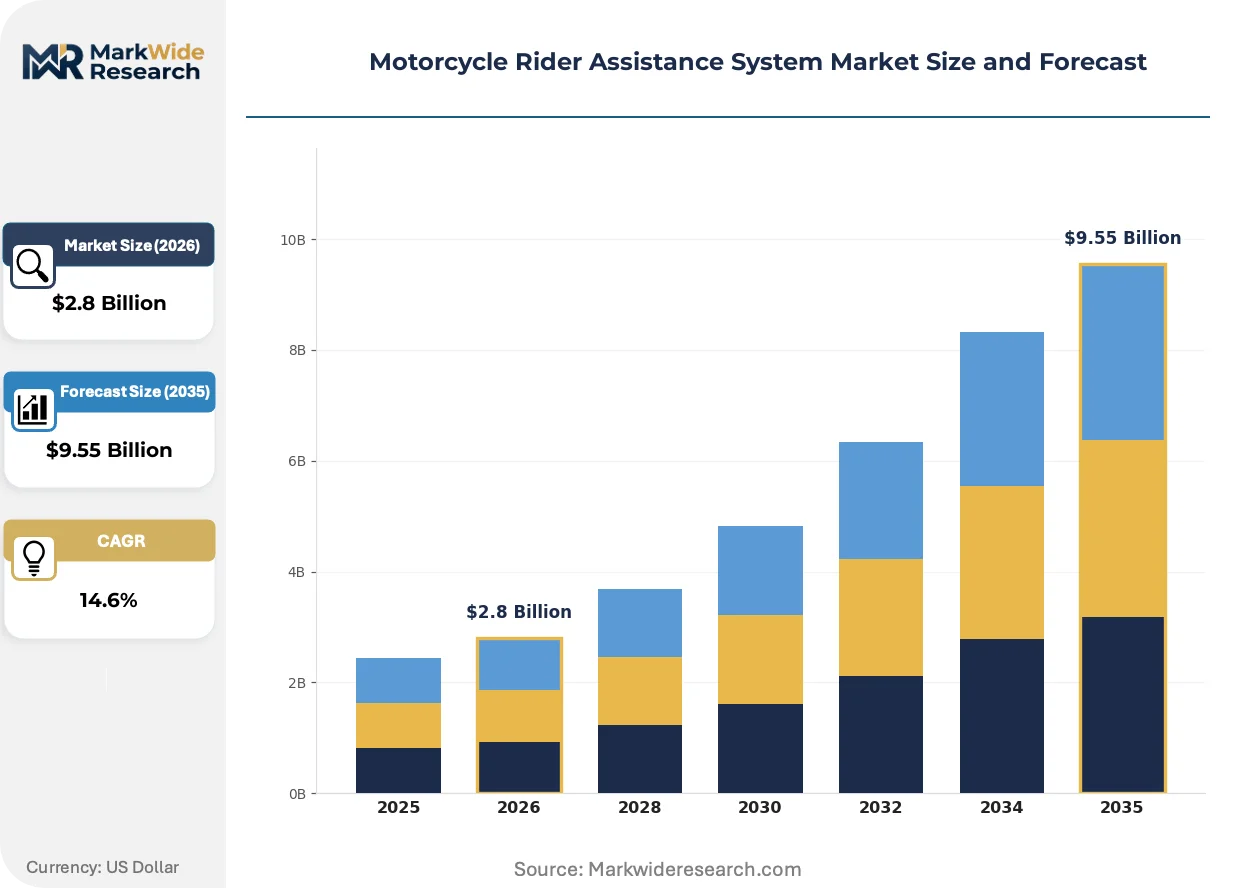
Market Dynamics
Sensor fusion architectures are compressing development cycles as OEMs integrate radar, camera, and LiDAR inputs through unified electronic control units, forcing tier-one suppliers to reconfigure hardware-software boundaries.
Growth Catalysts
- EU General Safety Regulation:Mandates for advanced rider assistance systems on new motorcycle models are compelling OEMs to pre-integrate radar and camera suites during platform design phases rather than post-hoc retrofitting.
- Fleet operator risk management:Commercial motorcycle fleets in Germany and Japan are specifying all-weather radar systems as procurement criteria to reduce insurance premiums and liability exposure.
- 77 GHz radar maturation:Automotive-scale production of millimeter-wave radar modules is driving unit cost reductions that transfer directly to motorcycle-specific compact form factors.
Market Restraints
- LiDAR thermal management:Compact motorcycle fairings limit heat dissipation capacity for solid-state LiDAR units, constraining continuous operation in high-ambient-temperature environments.
- Semiconductor foundry concentration:Advanced driver assistance system chipsets depend on Taiwan-based fabrication capacity, exposing supply continuity to geopolitical friction.
- UNECE homologation timelines:Protracted certification cycles for adaptive cruise control and lane-keeping assistance delay revenue recognition for suppliers by 18-24 months post-development completion.
Strategic Opportunities
- India two-wheeler electrification:Domestic OEMs integrating rider assistance systems into electric motorcycle platforms can establish safety differentiation before regulatory mandates crystallize.
- V2X roadside infrastructure:Cooperative intelligent transport system deployments in Japan and Germany create demand for motorcycle-specific communication modules that broadcast position and intent to surrounding vehicles.
- Sensor-as-a-service models:Subscription-based over-the-air feature activation for adaptive cruise control and collision warning allows OEMs to monetize hardware pre-installation through software unlocking.
Industry Challenges
- Embedded systems firmware integration:Motorcycle ECU architectures lack standardized middleware layers, forcing suppliers to develop bespoke software stacks for each OEM platform.
- Functional safety engineer scarcity:ISO 26262 certification expertise for automotive-grade systems commands premium compensation, constraining supplier scaling.
- Windshield distortion compensation:Camera-based systems require calibration algorithms that correct for optical aberrations introduced by curved motorcycle windshields, adding validation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Rider Assistance System Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Collision Avoidance, Blind Spot Detection, Traction Control Technology: Radar Systems, LiDAR, Camera-Based Systems, V2X Communication Installation: Aftermarket, OEM, Integrated Systems, Standalone Units End User: Private Owners, Fleet Operators, Motorcycle Manufacturers, Leasing Companies |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, BMW Motorrad, Denso Corporation, Garmin Ltd., Honda Motor Co. Ltd., Ducati Motor Holding S.p.A., KTM AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Rider Assistance System Market Evolving Landscape
Hardware abstraction layers are decoupling sensor hardware from application software, enabling OEMs to swap radar or camera suppliers without redesigning electronic control unit architectures.
Radar-camera sensor fusion is modularizing across premium touring motorcycles, allowing manufacturers like BMW Motorrad and KTM to offer adaptive cruise control as a factory-installed option while preserving upgrade pathways for collision avoidance expansion. Fleet purchasers in Germany are specifying fused-sensor configurations to satisfy insurer risk assessment protocols. The technology is modularizing supplier relationships as tier-ones compete to provide reference designs that OEMs customize through software rather than hardware differentiation.
Japan's METI has established bilateral equivalency protocols with NHTSA on motorcycle advanced driver assistance system certification, reducing redundant homologation costs for suppliers serving both markets. The industrial consequence is accelerated product launch timelines for radar-based adaptive cruise control systems. Japanese OEMs are responding by pre-certifying platforms for simultaneous US and domestic market entry.
Aftermarket installation channels are contracting as integrated OEM systems become standard equipment on mid-displacement motorcycles above 500cc. Independent service providers in the United States are pivoting toward calibration and diagnostic services rather than hardware sales. This behavioral shift is most visible in California and Texas, where dealer network expansion for European and Japanese brands has compressed independent mechanic margins on safety system installations.
Motorcycle Rider Assistance System Market Segmentation
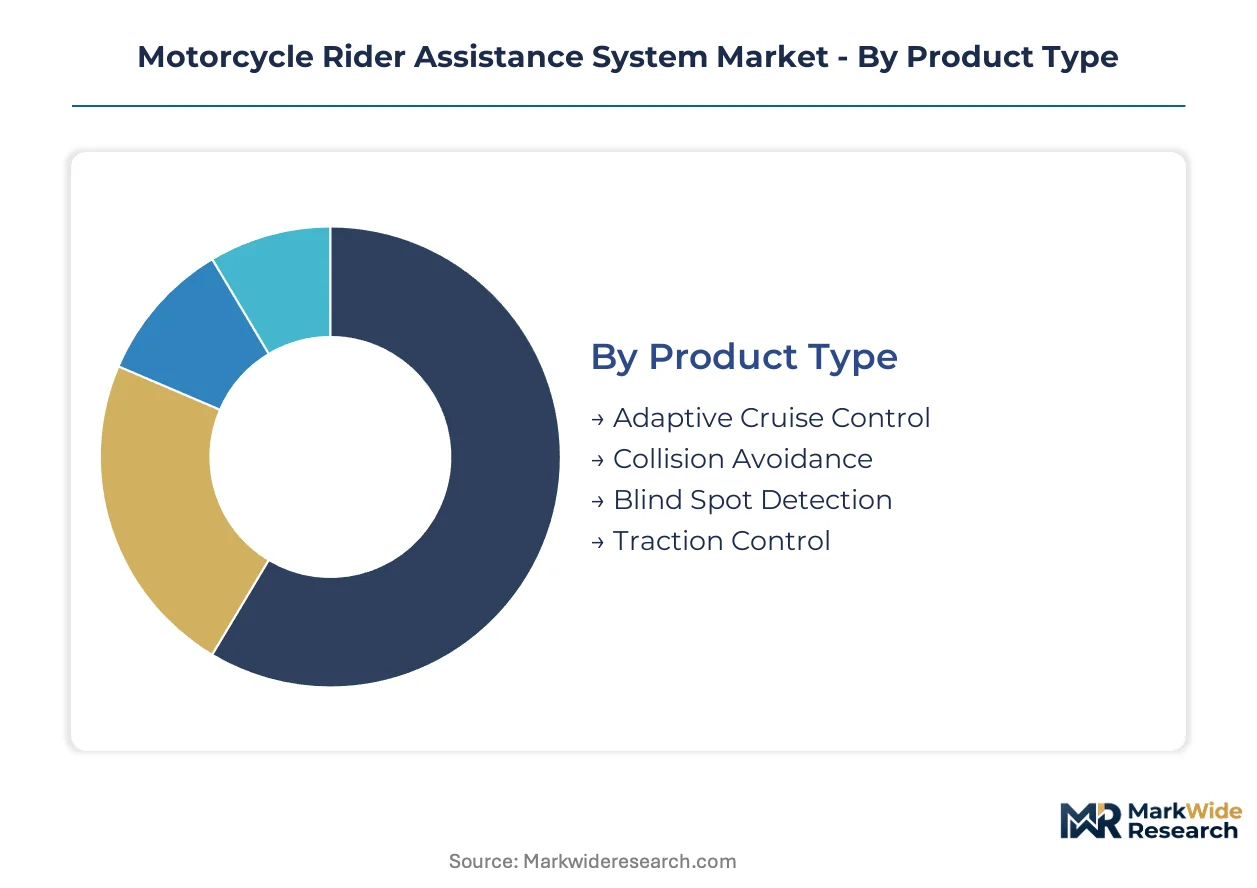
Segmentation in motorcycle rider assistance systems reveals how OEMs bundle hardware and software across price tiers and use cases. Supplier strategies diverge sharply between premium factory integration and aftermarket retrofit channels.
Product Type:
Supply concentration in forward-facing safety modules has concentrated tier-one engineering resources on collision prevention and speed management functions.
- Adaptive Cruise Control:Radar-assisted throttle and braking modulation maintains set following distances to preceding vehicles. German fleet operators specify this as mandatory equipment for touring motorcycles used in commercial dispatch services, reducing rear-end collision liability exposure.
- Collision Avoidance:Sensor fusion architectures process camera and radar inputs to trigger autonomous emergency braking when closing speeds exceed calibrated thresholds. Japanese OEMs pre-integrate these systems into flagship sport-touring platforms bound for domestic and US markets under METI-NHTSA equivalency protocols.
- Blind Spot Detection:Rear-mounted radar units monitor adjacent lane occupancy with 50-meter range specifications.
- Traction Control:Wheel-speed differential algorithms modulate engine output to prevent rear-wheel slip on variable road surfaces.
Adaptive Cruise Control absorbs the bulk of installed capacity; Collision Avoidance is expanding most quickly.
Technology:
Cost tier differentiation separates mature camera pipelines from emerging all-weather radar and V2X modules requiring fresh semiconductor supply chains.
- Radar Systems:77 GHz millimeter-wave units deliver 150-200 meter detection range through precipitation and darkness. Automotive-scale production at Robert Bosch GmbH and Continental AG is compressing unit costs for motorcycle-specific compact form factors.
- Camera-Based Systems:CMOS image sensors with HDR processing dominate OEM fitment due to mature supply chains and lower bill-of-materials cost. Windshield distortion compensation algorithms add validation burden for curved motorcycle fairings.
- LiDAR:Solid-state units face thermal management constraints in compact motorcycle enclosures.
- V2X Communication:DSRC and C-V2X modules broadcast position and intent data to surrounding vehicles and roadside infrastructure.
Camera-Based Systems anchor current production volumes; Radar Systems are climbing the fastest as fleet procurement criteria harden.
Installation:
Customer type fragmentation splits between factory-integrated safety suites and independent service provider retrofit channels.
- OEM:Pre-integrated radar and camera suites installed during platform design phases capture the majority of value capture as EU General Safety Regulation mandates eliminate post-hoc retrofitting economics. BMW Motorrad and KTM offer adaptive cruise control as factory options with software-upgradeable collision avoidance pathways.
- Integrated Systems:Unified electronic control units fuse multiple sensor inputs through standardized middleware, reducing bespoke software development for each OEM platform.
- Aftermarket:Independent installation channels contract as mid-displacement motorcycles above 500cc standardize factory safety equipment.
- Standalone Units:Single-function retrofit devices occupy shrinking margin pools in California and Texas dealer networks.
OEM installation commands the dominant share of unit economics; Integrated Systems are gaining share fastest as sensor fusion architectures modularize.
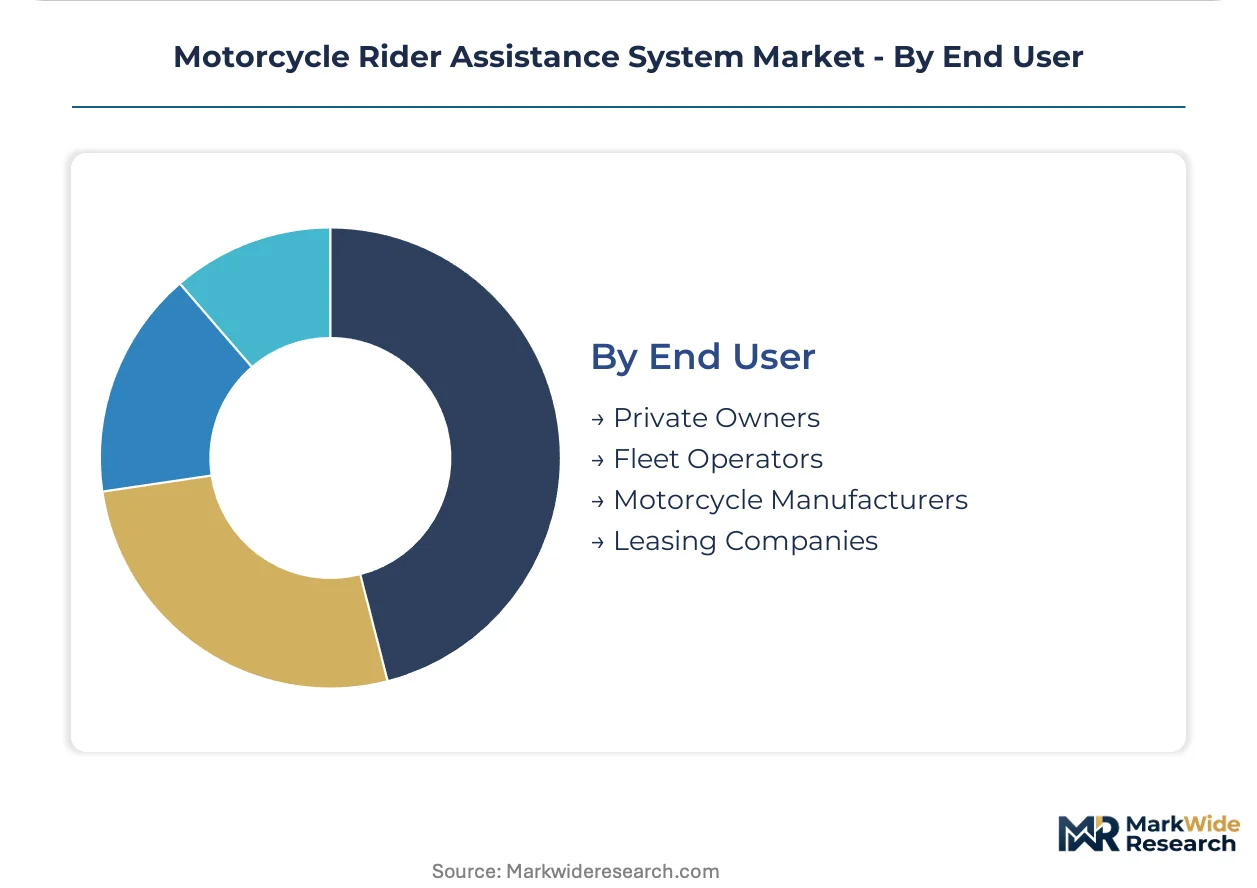
End User:
Application concentration in commercial risk management is reshaping procurement specifications away from consumer preference toward insurer-mandated equipment lists.
- Fleet Operators:Commercial motorcycle dispatch and delivery services in Germany and Japan specify all-weather radar systems to satisfy insurer risk assessment protocols and reduce premium exposure. Procurement contracts increasingly require ISO 26262 functional safety certification as a gate condition.
- Motorcycle Manufacturers:OEM platform engineering teams pre-certify safety systems for simultaneous multi-market entry under bilateral regulatory equivalency agreements.
- Private Owners:Individual purchasers in premium segments demonstrate willingness to pay for factory-installed safety technology.
- Leasing Companies:Asset managers specify residual value protection through standardized safety equipment across fleet rotations.
Fleet Operators concentrate near-term demand volume; Motorcycle Manufacturers are scaling integration fastest as regulatory mandates crystallize across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of motorcycle rider assistance systems concentrates in Germany and Japan, while consumption spreads across Germany, the United States, and Japan where regulatory mandates and fleet procurement converge. Component fabrication clusters in southern Germany and Aichi Prefecture supply radar and camera modules to assembly plants worldwide. Market entry timelines vary by jurisdiction as bilateral equivalency agreements compress homologation cycles in some corridors while prolonging them in others.
United States
Fleet operators in California and Texas specify radar-assisted adaptive cruise control to satisfy insurer risk protocols and reduce liability exposure. NHTSA coordinates certification equivalency with Japan's METI through bilateral dialogues on motorcycle advanced driver assistance systems. The Southwest corridor hosts calibration service providers pivoting from aftermarket hardware sales to diagnostic and maintenance operations as factory-integrated systems become standard.
Germany
Commercial motorcycle dispatch services mandate all-weather radar systems to qualify for reduced insurance premiums under fleet risk management programs. The EU General Safety Regulation compels OEMs to pre-integrate safety suites during platform design rather than retrofitting post-production. Bavaria anchors radar module development with engineering centers in Stuttgart and Ingolstadt supplying sensor platforms across European motorcycle assembly networks.
Japan
Domestic OEMs pre-certify platforms for simultaneous US and domestic market entry under METI-NHTSA equivalency protocols. METI establishes bilateral certification standards that reduce redundant homologation costs for suppliers serving both jurisdictions. Aichi Prefecture concentrates camera and radar production with tier-one suppliers feeding assembly plants in the Kanto and Kansai industrial belts.
India
Domestic OEMs integrate rider assistance systems into electric motorcycle platforms to establish safety differentiation before regulatory mandates crystallize. The country's national automotive regulator evaluates draft standards for advanced rider assistance systems on two-wheelers above 125cc. Tamil Nadu and Karnataka host emerging engineering centers where suppliers develop compact sensor packages for tropical climate operation and cost-sensitive procurement.
South Korea
Component suppliers leverage automotive-scale semiconductor fabrication to produce compact radar modules for motorcycle-specific form factors. The national automotive technology regulator coordinates with UNECE working groups on harmonized standards for adaptive cruise control certification. The Seoul Capital Area concentrates ECU development laboratories serving both domestic motorcycle OEMs and export markets requiring ISO 26262 functional safety certification.
Motorcycle Rider Assistance System Market Competitive Landscape
The competitive structure tilts toward diversified automotive suppliers with cross-vehicle sensor platforms rather than motorcycle-specialized pure-plays. Tier-one automotive electronics conglomerates dominate radar and camera module supply, while motorcycle OEMs retain system integration and software calibration functions. Two strategic archetypes prevail: diversified automotive suppliers repurposing passenger vehicle sensor architectures, and integrated motorcycle manufacturers controlling end-to-end safety suite deployment. Competitive moves concentrate on sensor fusion partnerships and middleware standardization efforts that reduce bespoke software development burdens.
Within the diversified automotive supplier tier, Robert Bosch GmbH and Continental AG exemplify platform leverage strategies, while ZF Friedrichshafen AG occupies a position among component specialists developing compact form-factor solutions. These Germany-based entities represent the archetype of automotive-scale suppliers extending sensor and control module portfolios into two-wheeler applications through unified electronic control unit architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| BMW Motorrad |
| Denso Corporation |
| Garmin Ltd. |
| Honda Motor Co. Ltd. |
| Ducati Motor Holding S.p.A. |
| KTM AG |
| Others |
Value Network & Pricing Analysis
Automotive-grade silicon wafer pricing indices cascade through motorcycle radar module production, compressing margins at tier-two component suppliers while OEMs capture value through software-tiered feature activation. This commodity-cost transmission splits the market into certification-grade premium tiers and volume-standard economy configurations.
Pricing Analysis
Margin tightening in mid-displacement motorcycle segments reflects 77 GHz radar chipset cost-down pressure from automotive-scale production. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified fusion systems from single-sensor camera modules and basic aftermarket retrofit kits. Fleet operators in Germany demonstrate lowest price sensitivity due to insurer-mandated equipment specifications, while private owners in India exhibit highest elasticity as electrification platforms compete on total cost of ownership.
Supply Chain Analysis
Functional safety engineer scarcity in southern Germany and Aichi Prefecture constrains ECU firmware development capacity for integrated sensor platforms. Semiconductor fabrication draws from Taiwan-based foundries, automotive-grade radar modules rest on Bosch and Continental production networks, and LiDAR thermal management components hinge on South Korean packaging specialists. Single-source vulnerability in millimeter-wave radar chipsets exposes continuity risks. Distribution runs through OEM pre-integration channels with shrinking aftermarket hardware pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sensor fusion middleware and V2X communication stacks is accelerating as tier-one suppliers and OEMs race to control software-defined feature roadmaps. This upstream control over electronic control unit architectures determines margin capture in subscription-based safety feature monetization.
For Market Incumbents:Hedge against semiconductor foundry concentration by diversifying radar chipset sourcing across multiple fabrication geographies. Secure captive capacity for 77 GHz module production through joint development agreements with automotive-scale suppliers. Defensive consolidation around ISO 26262 certification expertise protects against functional safety engineer scarcity that constrains competitor scaling.
For New Entrants and Emerging Players:Direct-to-fleet digital procurement platforms in Germany and Japan bypass entrenched OEM-dealer networks for commercial motorcycle dispatch operators. White-space concentration sits in India electric motorcycle safety pre-integration before regulatory mandates crystallize. Calibration-as-a-service offerings for dealer networks in California and Texas exploit contracting aftermarket hardware margins.
For Investors and Strategic Acquirers:The window for entry favors sensor fusion middleware specialists with automotive-grade functional safety credentials and existing OEM platform relationships. Long-term viability centers on software-defined vehicle architecture convergence across two-wheeler and passenger car applications. Watch for METI-NHTSA equivalency protocol expansion to additional jurisdictions as inflection signal for accelerated homologation cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Middleware Development | Hardware abstraction layers enable OEM supplier swaps without ECU redesign, reducing bespoke software burdens. |
| V2X Communication Module Integration | DSRC and C-V2X units broadcast motorcycle position data to cooperative intelligent transport infrastructure in Japan and Germany. |
| ISO 26262 Certification Investment | Functional safety credentials gate fleet procurement contracts and reduce liability exposure for commercial operators. |
| Subscription Feature Activation Platform | Over-the-air unlocking of adaptive cruise control monetizes pre-installed hardware through recurring software revenue. |
| Tropical Climate Sensor Packaging | Compact radar and camera enclosures engineered for high-ambient-temperature operation open India and Southeast Asia volume. |
Research Methodology
Independent corroboration across tier-one supplier engineering directors, OEM platform integration teams, and fleet procurement managers underwrites the qualitative findings. Primary fieldwork encompassed radar module specialists at Robert Bosch GmbH and Continental AG, motorcycle safety system architects at BMW Motorrad and KTM, and commercial dispatch operators in Germany and Japan. Secondary validation drew from UNECE R79 steering equipment documentation, EU General Safety Regulation implementation timelines, NHTSA-METI bilateral equivalency protocols, and semiconductor foundry capacity disclosures. Bottom-up unit economics triangulated against top-down regulatory mandate penetration models.
Rate-of-change decomposition separated technology adoption velocity from regulatory compliance timelines and fleet replacement cycles across the projection horizon. Segmentation dimensions encompassed product type, sensor technology, installation channel, and end-user archetype with regional regulatory cluster overlay. CAGRs derived from installed base growth, content-per-vehicle expansion, and software-tiered monetization trajectory. Forecast inputs included 77 GHz radar cost curves, EU mandate phase-in schedules, and V2X roadside infrastructure deployment commitments.
The model holds under stable regulatory equivalence agreements and automotive semiconductor supply continuity; deviation in Taiwan foundry capacity access or UNECE homologation timeline extension would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Netherlands E-Bike Market