
 GPS Bike Computers Market | 2026-2036
GPS Bike Computers Market Size, Share, and Industry Trends Forecast 2026-2036
GPS Bike Computers Market Outlook
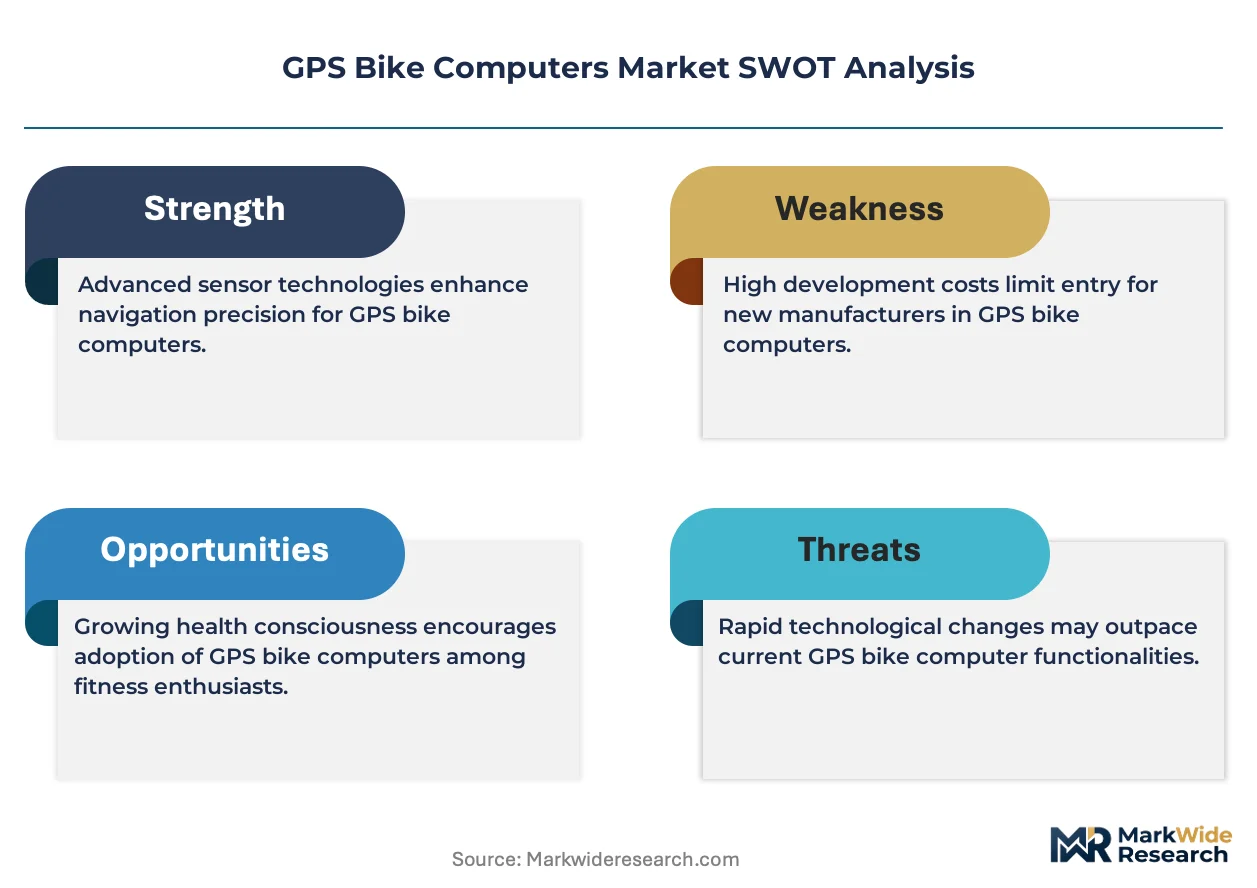
CE marking under the EU Radio Equipment Directive is unwinding market access for smaller import brands. Garmin Ltd. leverages in-house GNSS chipset development to sustain pricing power across European and North American channels. Wahoo Fitness anchors its position through deep trainer ecosystem integration that locks users into recurring software subscriptions. Bryton Inc. competes aggressively on hardware specification density at mid-tier price points.
GPS bike computers are handlebar-mounted navigation and telemetry devices that combine multi-constellation satellite receivers with wireless sensor pairing to deliver real-time position, speed, power, and elevation data to cyclists. Manufacturing centers on ruggedized waterproof housings with transflective displays readable in direct sunlight, plus lithium-ion power management for multi-hour battery endurance. Wearable devices and integrated systems capture diverging margin pools, with wrist-mounted units appealing to triathletes who demand swim-bike-run continuity while stem-integrated systems command premium pricing from road racers who refuse aerodynamic penalty. Bluetooth and ANT+ connectivity standards split the sensor pairing landscape, with ANT+ retaining dominance among power meter and smart trainer interfaces due to its lower protocol overhead.
FCC Part 15 certification gates US market entry for any device emitting radio signals above specified power thresholds, while CE marking under the EU Radio Equipment Directive and RED cybersecurity requirements impose parallel compliance burdens on manufacturers selling into European markets. Japan's MIC radio law adds a third certification track that delays product launches by four to six months for brands lacking Tokyo-based testing partnerships. Stakeholders must monitor whether emerging national cybersecurity labeling regimes expand from smartphones into fitness electronics, as this would fragment compliance costs across formerly harmonized radio standards.
Market Dynamics
Multi-constellation GNSS chipset commoditization is compressing hardware margins while forcing differentiation through software ecosystems and sensor integration depth.
Growth Catalysts
- EU cycling infrastructure mandates:Germany's federal transport investment programs and Dutch cycling highway networks generate dense addressable markets for navigation hardware.
- Power meter sensor proliferation:Strain-gauge crank and pedal systems from Stages Cycling and Favero Electronics create installed bases demanding compatible head units.
- Smart trainer ecosystem lock-in:Zwift, TrainerRoad, and Wahoo X subscription services drive hardware refresh cycles among indoor training enthusiasts.
Market Restraints
- Lithium-ion cell cost volatility:Cathode material price swings and Chinese cell production concentration squeeze battery margin predictability.
- CE marking compliance burden:EU Radio Equipment Directive cybersecurity requirements and RED delegated acts impose testing costs that disadvantage smaller import brands.
- Smartphone substitution threat:Handlebar phone mounts with Bluetooth sensor bridging apps capture price-sensitive recreational riders.
Strategic Opportunities
- India sport tourism expansion:Himalayan ultra-endurance events and Western Ghats gran fondo circuits create first-mover positioning for ruggedized navigation hardware.
- Gravel and bikepacking segment emergence:Off-pavement route planning and multi-day navigation demands favor devices with extended battery life and offline mapping.
- Japan MIC radio law partnership structures:Tokyo-based testing laboratory relationships compress certification timelines for brands targeting the domestic audax and randonneuring community.
Industry Challenges
- Firmware engineering talent scarcity:Embedded systems developers with GNSS signal processing and low-power optimization expertise command premium compensation.
- Multi-certification timeline compression:Parallel FCC Part 15, CE marking, and Japan MIC tracks delay product launches by 4-6 months without established testing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Bike Computers Market |
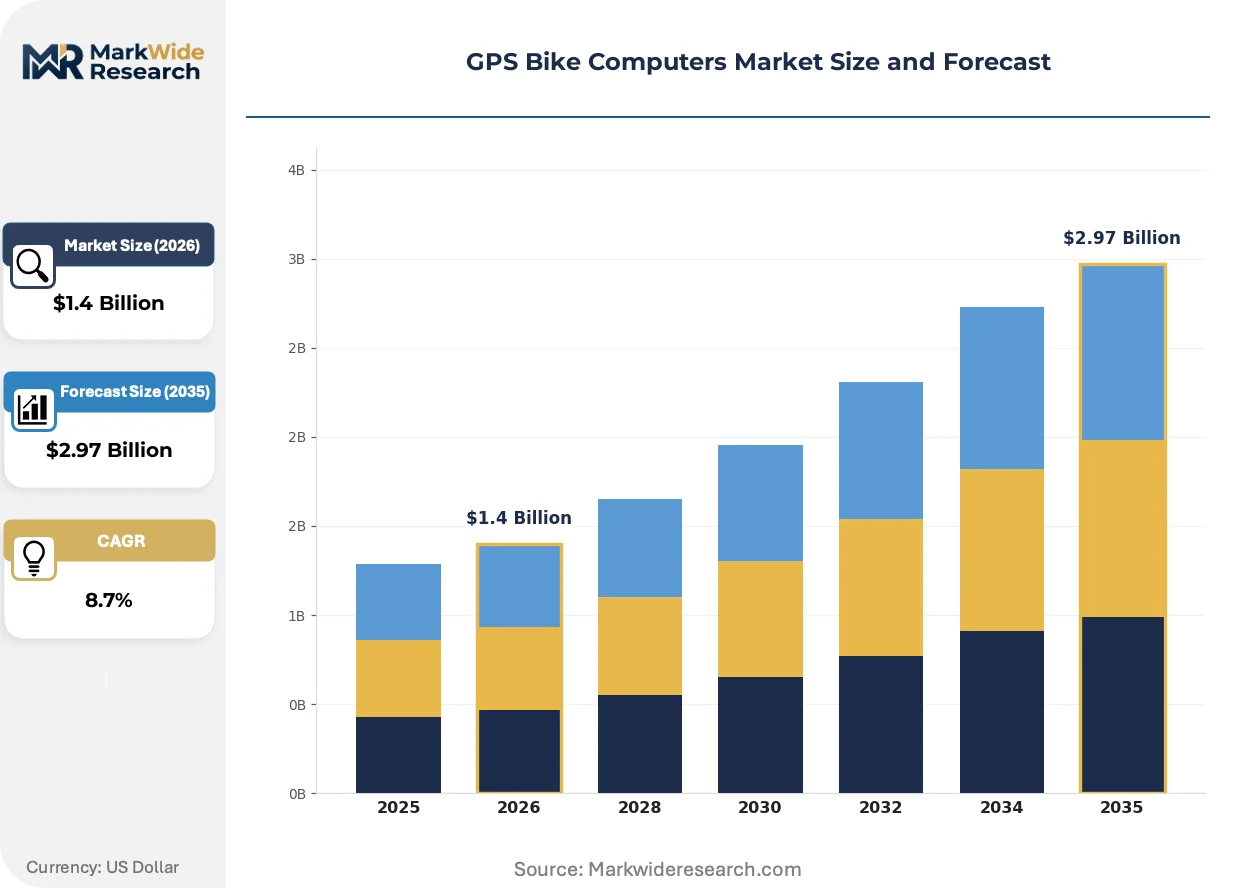
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Handheld Units, Integrated Systems, Smartphone Attachments Connectivity: Bluetooth, ANT+, Wi-Fi, USB End User: Cycling Enthusiasts, Professional Athletes, Recreational Riders, Tourists Features: Navigation, Performance Metrics, Route Planning, Live Tracking |
| Companies Covered | Garmin Ltd., Wahoo Fitness, SIGMA-ELEKTRO GmbH, CATEYE Co., Ltd., Bryton Inc., Hammerhead Technologies, Pioneer Electronics (USA) Inc., Lezyne USA, Inc., Polar Electro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Bike Computers Market Strategic Shifts
Solar harvesting displays and AI-generated route engines are redefining hardware-software boundaries. Three developments merit particular attention.
Transflective solar-boosted display technology is fragmenting the premium tier. These photovoltaic-integrated screens extend runtime by 40-60% in direct sunlight conditions. Competitive cyclists and bikepacking tourers in Arizona, Australia, and Spain's interior are adopting units that eliminate mid-ride charging anxiety. The technology is fragmenting vendor R&D roadmaps between solar-integrated flagship lines and conventional lithium-dependent mid-tier products.
EU Cybersecurity Act labeling requirements are expanding from smartphones into connected fitness devices. The European Commission's proposed hardware security certification would mandate vulnerability disclosure timelines and firmware update guarantees. Premium GPS computer manufacturers selling through German, Dutch, and Belgian channels face the steepest compliance preparation. Several brands are pre-positioning encrypted over-the-air update architectures ahead of formal mandate implementation.
Subscription-unbundled hardware purchasing is gaining traction among amateur endurance athletes. Buyers increasingly reject mandatory software bundling, demanding head units with full functionality absent recurring payments. Direct-to-consumer channels and specialty retailers in Denmark, Norway, and Switzerland report stronger attachment rates for hardware-only SKUs. This pattern is compressing vendor lifetime value calculations and forcing ecosystem monetization toward optional feature tiers rather than base functionality paywalls.
GPS Bike Computers Market Segmentation
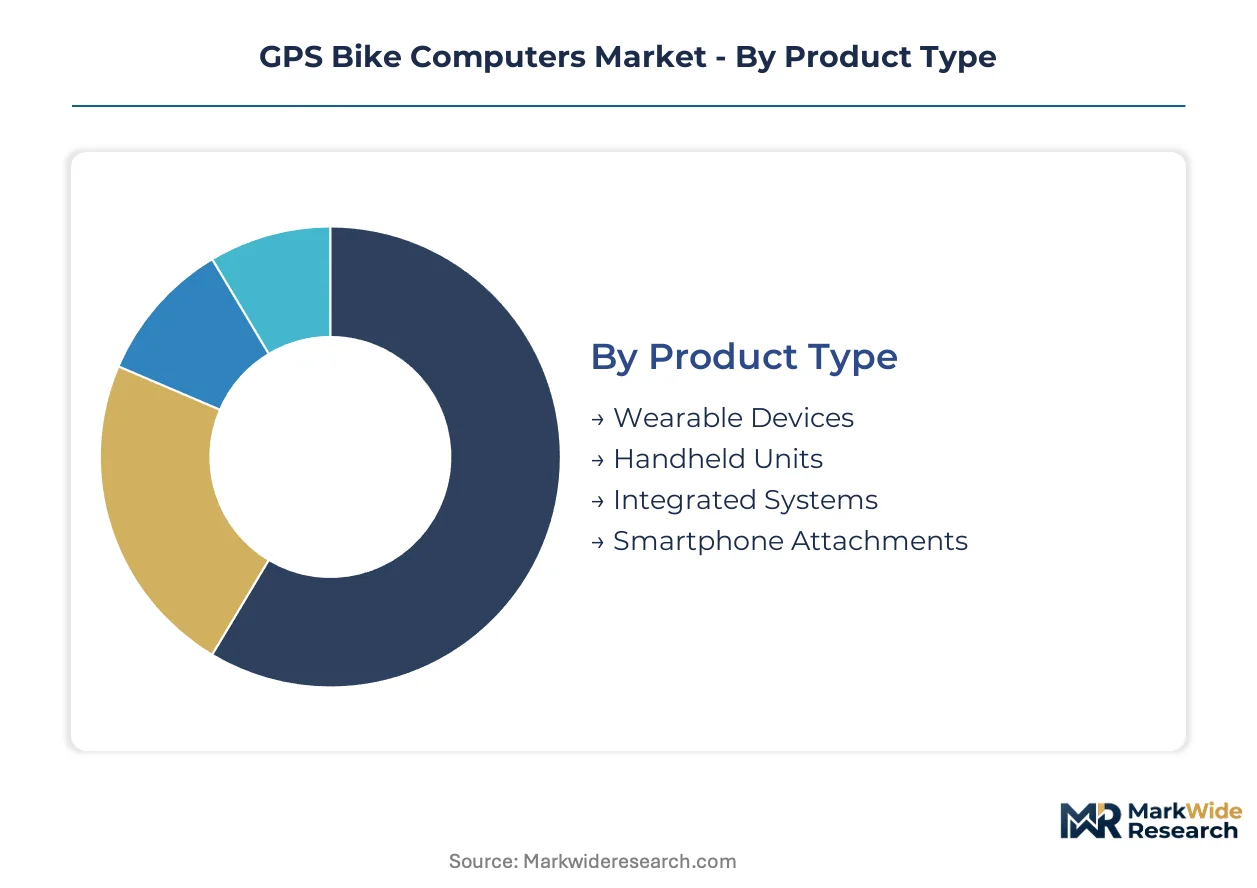
Segmentation in GPS bike computers reveals how hardware specifications, wireless protocols, and user workflows create distinct margin pools. Manufacturers configure certification pathways and distribution channels around these divisions rather than treating the market as uniform.
Product Type:
FCC Part 15 certification intensity varies sharply across form factors, with integrated systems facing the most complex antenna compliance testing and wearable devices benefiting from modular pre-certified modules.
- Wearable Devices:Wrist-mounted units with transflective displays and multi-sport firmware appeal to triathletes who demand swim-bike-run continuity. Demand concentrates in Switzerland and Denmark among amateur endurance athletes who reject handlebar clutter. Solar harvesting variants extend runtime 40-60% in direct sunlight, commanding premium positioning in Arizona and Australia's interior.
- Integrated Systems:Stem-mounted or frame-integrated hardware with aerodynamic housings and proprietary antenna architectures target road racers who refuse drag penalties. German cycling teams and Dutch sport tourists drive volume through specialty retail channels that bundle installation services.
- Handheld Units:Ruggedized devices with glove-friendly interfaces serve bikepacking tourers navigating off-pavement routes in Spain's interior and the Himalayan ultra-endurance circuit.
- Smartphone Attachments:Handlebar mounts with sensor bridging apps capture price-sensitive recreational riders in India and Southeast Asia, though Bluetooth latency limits power meter compatibility.
Established volume favors integrated systems; emerging adoption favors wearable devices.
Connectivity:
Protocol selection determines sensor ecosystem compatibility and certification cost structures, with ANT+ retaining efficiency advantages for power meter interfaces despite Bluetooth's smartphone ubiquity.
- ANT+:Low-overhead wireless protocol purpose-built for fitness sensors dominates power meter and smart trainer pairings. Strain-gauge crank systems from Stages Cycling create installed bases demanding compatible head units across German and Belgian channels.
- Bluetooth:Universal smartphone compatibility enables firmware updates and live tracking services, though higher protocol overhead drains battery faster than ANT+ equivalents. Recreational riders in price-sensitive segments prioritize this standard.
- Wi-Fi:High-bandwidth connectivity supports automatic ride uploads and over-the-air map updates, typically reserved for premium tiers with larger battery capacities.
- USB:Wired data transfer and charging persists in entry-level units and as fallback for firmware recovery, particularly in markets with unreliable wireless infrastructure.
Protocol loyalty fragments by user type: competitive cyclists cluster around ANT+; recreational riders default to Bluetooth.
End User:
Customer workflow intensity shapes feature bundling and pricing architecture, with professional athletes demanding unbundled hardware and amateurs accepting subscription-tied ecosystems.
- Professional Athletes:UCI-registered cyclists and national team members require CE-marked devices with encrypted firmware and anti-tamper guarantees for competition eligibility. German Bundesliga cycling teams drive refresh cycles through sponsor-mandated equipment standards.
- Cycling Enthusiasts:Amateur endurance athletes with structured training programs represent the core revenue base, increasingly rejecting mandatory software subscriptions in favor of hardware-only purchasing through Danish and Norwegian direct-to-consumer channels.
- Recreational Riders:Weekend cyclists prioritize ease of use over specification density, often substituting smartphone mounts for dedicated hardware.
- Tourists:Sport tourism participants in gran fondo circuits and organized tours demand offline mapping and extended battery life for multi-day navigation.
Revenue concentration sits with cycling enthusiasts; steepest expansion trajectory belongs to professional athletes facing tightening equipment regulations.
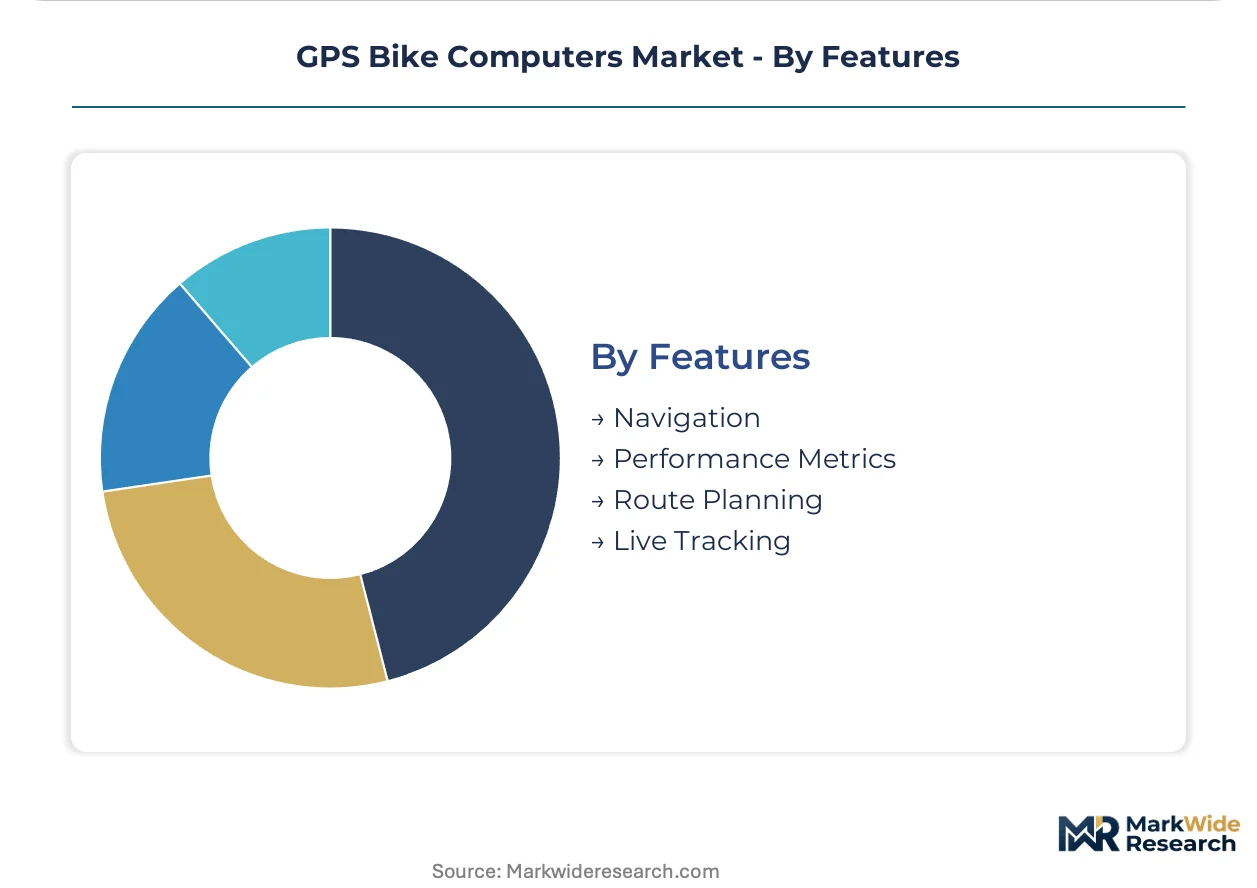
Features:
Software capability tiers now differentiate hardware more than raw specifications, with AI-generated route engines and live tracking services creating recurring revenue opportunities.
- Navigation:Multi-constellation GNSS with offline map storage addresses connectivity gaps in remote terrain. Bikepacking segments in the Western Ghats and Arizona desert prioritize this capability.
- Performance Metrics:Power, cadence, and physiological data integration requires deep sensor ecosystem partnerships. Wahoo Fitness locks users through trainer software integration that rewards proprietary hardware pairing.
- Route Planning:Cloud-based route engines with surface-type classification and elevation profiling attract gravel segment riders exploring off-pavement networks.
- Live Tracking:Real-time location sharing for safety and social validation demands cellular or paired-smartphone connectivity, with EU Cybersecurity Act labeling requirements imposing new compliance burdens on data transmission features.
Margin sustainability favors performance metrics; differentiation potential concentrates in route planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's federal cycling infrastructure investment programs and the Netherlands' cycling highway networks generate dense addressable markets for premium navigation hardware. National regulations on radio equipment certification and cybersecurity labeling reshape competitive access across major demand centers.
Germany
Bundesliga cycling teams and amateur endurance athletes drive hardware refresh cycles through sponsor-mandated equipment standards. KBA transport regulations and EU Radio Equipment Directive CE marking requirements filter market access for import brands. Bavaria and Baden-Württemberg host specialty retail clusters serving gran fondo participants and sport tourists.
United States
Competitive cycling teams in Arizona and Colorado create concentrated demand for solar-harvesting display technology. FCC Part 15 rules for unlicensed radio transmitters govern ANT+ and Bluetooth certification requirements. The Pacific Northwest and Rocky Mountain regions anchor outdoor recreation retail channels for ruggedized navigation hardware.
Japan
The domestic audax and randonneuring community demands extended-battery devices for ultra-endurance events. METI oversees MIC radio law certification that delays product launches by four to six months without Tokyo-based testing partnerships. Kanto and Kansai regions concentrate specialty distributors serving competitive amateur cyclists.
Australia
Interior desert cycling and coastal endurance events favor solar-boosted display technology for runtime extension. The country's national communications regulator administers radio equipment compliance parallel to European and North American frameworks. Victoria and New South Wales host gran fondo circuits generating seasonal hardware demand spikes.
India
Himalayan ultra-endurance events and Western Ghats gran fondo circuits create first-mover positioning opportunities for ruggedized navigation hardware. BIS certification requirements and DGFT import regulations shape market entry pathways for foreign brands. Maharashtra and Karnataka anchor emerging sport tourism infrastructure investment.
GPS Bike Computers Market Competitive Environment
Player mix skews toward vertically integrated specialists with in-house GNSS chipset development and ecosystem-locked subscription platforms. Market structure concentrates around three archetypes: integrated hardware-software vendors, specification-dense mid-tier challengers, and trainer-ecosystem anchors. Dominant competitive moves include deep software integration investments and geographic certification partnership structures.
Within the integrated hardware-software tier, Garmin Ltd. and Wahoo Fitness exemplify divergent ecosystem strategies. Garmin's in-house GNSS development sustains pricing power across European and North American channels, while Wahoo anchors position through trainer software integration locking users into recurring subscriptions. Bryton Inc. occupies the specification-dense mid-tier, competing aggressively on hardware metrics at price points below premium leaders. SIGMA-ELEKTRO GmbH represents the European specialist archetype with regional certification depth.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Wahoo Fitness |
| SIGMA-ELEKTRO GmbH |
| CATEYE Co., Ltd. |
| Bryton Inc. |
| Hammerhead Technologies |
| Pioneer Electronics (USA) Inc. |
| Lezyne USA, Inc. |
| Polar Electro |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with Taiwanese GNSS foundries lock in both chipset supply access and unit cost visibility for premium tier manufacturers navigating FCC Part 15 and CE marking compliance timelines. These contractual structures insulate vertically integrated vendors from lithium-ion cell price volatility while compressing margin buffers for mid-tier brands dependent on spot-market component procurement.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with CE-marked units under EU Radio Equipment Directive cybersecurity mandates commanding substantial premiums over uncertified import alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity of software subscriptions and sensor ecosystem depth. Cost compression in mid-tier hardware is intensifying because multi-constellation GNSS chipset commoditization erodes specification-based differentiation. Recreational riders in India and Southeast Asia exhibit highest price sensitivity, while German competitive cycling teams show lowest sensitivity due to sponsor-mandated equipment standards.
Supply Chain Analysis
Just-in-time inventory strategies dominate among brands assembling in Taiwan and China, though strategic stockpiling of lithium-ion cells from South Korean suppliers buffers against cathode material price swings. Manufacturing concentrates in Taiwan for GNSS chipsets, China for display modules and battery cells, and Germany for precision sensor calibration. Raw material dependencies include rare earth elements for antenna substrates, cobalt and nickel for power cells, and specialized glass for transflective displays. Single-source vulnerability in Taiwanese GNSS foundry capacity represents the dominant structural risk. Distribution runs through specialty cycling retail channels in Germany and the Netherlands, direct-to-consumer platforms in Scandinavia, and outdoor recreation chains in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent GPS bike computer manufacturers face sustained substitution pressure from smartphone handlebar mounts with Bluetooth sensor bridging capabilities that capture price-sensitive recreational riders. Defense requires ecosystem deepening and certification moat reinforcement.
For Market Incumbents: Secure exclusive sensor ecosystem partnerships with power meter manufacturers like Stages Cycling and Favero Electronics to lock in ANT+ protocol loyalty among competitive cyclists. Deepen in-house GNSS chipset development to sustain pricing power against specification-dense mid-tier challengers. Invest in encrypted over-the-air update architectures ahead of EU Cybersecurity Act labeling expansion into fitness electronics. For New Entrants and Emerging Players: Offline mapping service gaps in gravel and bikepacking segments present white-space entry points where incumbents under-serve multi-day navigation demands. Target India's Himalayan ultra-endurance circuit and Western Ghats gran fondo infrastructure as first-mover geographies with limited established brand presence. Pursue Tokyo-based testing laboratory partnerships to compress Japan MIC radio law certification timelines for audax and randonneuring community access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among trainer-ecosystem-locked vendors with software subscription attach rates above hardware-only competitors. Long-term viability favors vertically integrated specialists with captive GNSS development and deep certification expertise across FCC, CE, and MIC frameworks. Acquisition target archetypes include mid-tier challengers with specification density advantages but lacking ecosystem depth. Watch for EU Cybersecurity Act mandate implementation timelines as inflection indicator for compliance cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Solar Harvesting Display Integration | Photovoltaic-integrated transflective screens extend runtime 40-60% in Arizona and Australian desert conditions. |
| Tokyo Testing Laboratory Partnership | MIC radio law certification relationships compress Japan market entry timelines by four to six months. |
| Encrypted Over-the-Air Architecture | Cybersecurity-compliant firmware update systems pre-position vendors ahead of EU hardware security mandates. |
| Direct-to-Consumer Channel Expansion | Hardware-only SKU distribution through Danish and Norwegian platforms captures subscription-rejecting amateur endurance athletes. |
| Power Meter Ecosystem Lock-in | Deep ANT+ integration with Stages Cycling and Favero Electronics creates installed base dependency for head unit replacement cycles. |
Study Parameters
Cross-validation between regulatory filing analysis and component supply chain intelligence anchors the qualitative findings in this GPS bike computer market assessment. Primary interviews with product managers at GNSS chipset developers, regulatory affairs leads navigating FCC Part 15 and CE marking pathways, specialty cycling retail buyers in Germany and the Netherlands, and firmware engineering directors with low-power optimization expertise combined with secondary validation from FCC equipment authorization databases, EU Radio Equipment Directive notified body filings, METI MIC certification records, and customs trade data for lithium-ion cell and display module flows. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across wearable, integrated, handheld, and smartphone attachment form factors.
Sensitivity analysis around GNSS chipset cost trajectories, lithium-ion cell price volatility scenarios, and smartphone substitution elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity protocol, end user workflow intensity, and feature bundling architecture alongside geographic regulatory cluster differentiation. CAGRs derived from fitted growth curves incorporating EU cycling infrastructure investment trajectories, power meter sensor installed base expansion, and smart trainer ecosystem penetration rates. Industry-specific forecast inputs encompassed solar harvesting display adoption curves and EU Cybersecurity Act implementation probability assessments.
Underlying assumptions cover sustained lithium-ion cell supply from South Korean and Chinese manufacturers, stable multi-constellation GNSS signal availability, and gradual EU cybersecurity labeling expansion into fitness electronics, with deviation risk concentrated in cathode material price spikes and accelerated smartphone sensor bridging app performance improvements. Revision becomes warranted when smartphone power meter latency performance crosses usability thresholds for competitive cycling applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Motorcycle Headlight Market