
 300cc Motorcycle Market | 2026-2036
300cc Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
300cc Motorcycle Market Analysis
Market Context
Euro 5 emission standards is consolidating the competitive landscape by forcing smaller manufacturers to absorb costly catalytic converter and fuel injection upgrades. Honda leverages its integrated powertrain manufacturing to sustain margin resilience under tighter emission budgets. KTM competes through Austrian-engineered performance positioning that commands premium pricing. CFMOTO anchors its expansion on Chinese domestic scale and aggressive export pricing into Southeast Asian markets.
Technical Definition and Segment Structure
The 300cc motorcycle designates a two-wheeled motor vehicle with engine displacement between 250cc and 350cc, typically producing 25-40 horsepower through single or parallel-twin cylinder configurations with liquid or air cooling, designed for urban commuting, light touring, and entry-level sport riding where power-to-weight ratios balance fuel efficiency against acceleration needs. Sport Bike and Dirt Bike product categories dominate volume in emerging markets where younger riders prioritize performance aesthetics and off-road capability, while Cruiser variants occupy mature premium segments in North America and Western Europe with higher per-unit margins. Electric fuel type variants within the 300cc-equivalent power band represent the fastest-growing structural pocket, though petrol configurations still control over ninety percent of current production throughput.
Regulatory Frame and Outlook
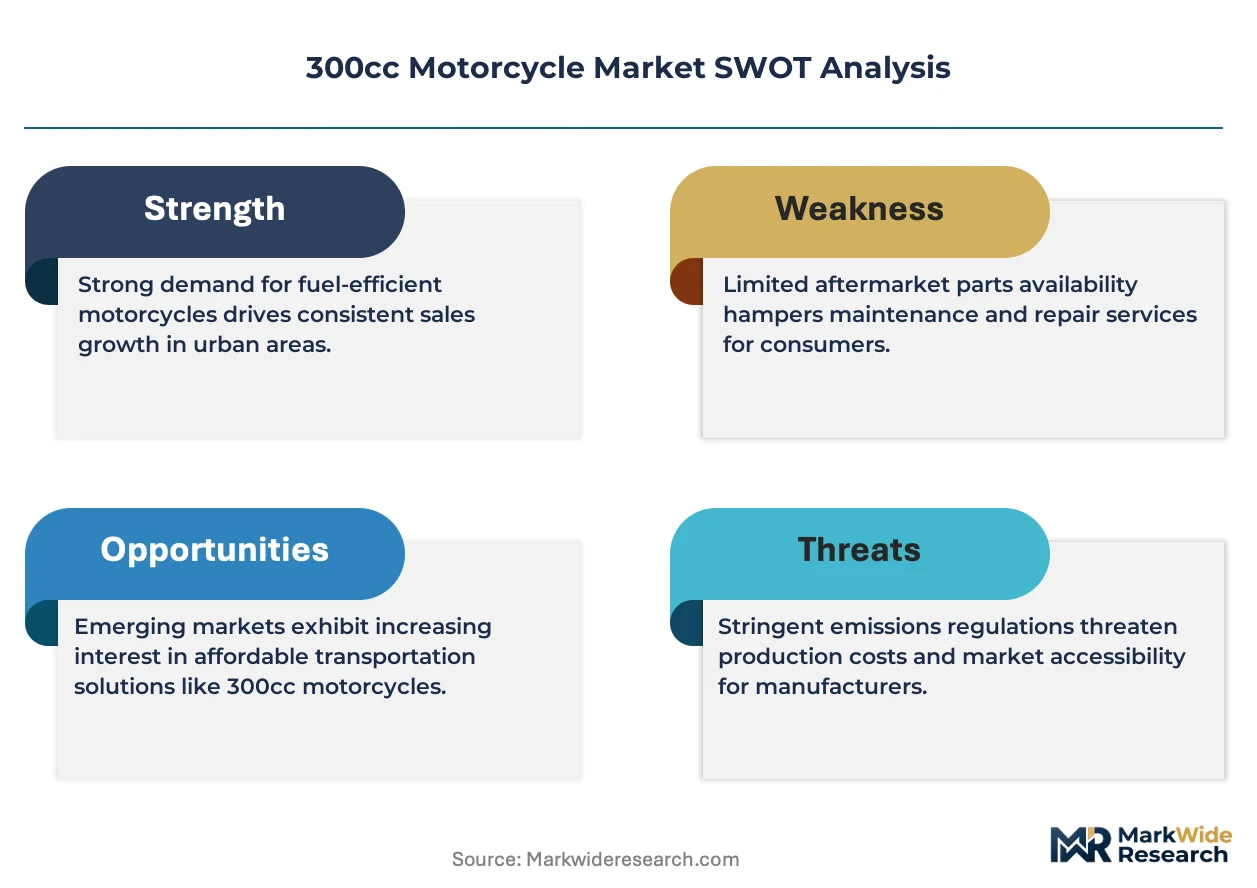
The EPA in the United States, Euro 5 regulators in Europe, and India's BIS together shape emission compliance timelines, safety testing protocols, and homologation barriers that determine which manufacturers can access major national markets. These frameworks directly influence engine architecture decisions, catalytic system investments, and model availability calendars across OEM portfolios. Stakeholders must monitor pending Euro 6 pre-announcements and India's evolving PLI scheme for electric vehicle components to anticipate which powertrain technologies will retain market access over the next decade.
Market Dynamics
Euro 5 emission compliance is compressing engine architecture choices across the 300cc segment, forcing manufacturers to absorb catalytic converter costs while preserving power-to-weight ratios that define commuter appeal in Southeast Asian cities.
Growth Catalysts
- Urban congestion premium:Southeast Asian commuters in Jakarta, Bangkok, and Ho Chi Minh City are trading up from 125cc scooters to 300cc motorcycles that cut through gridlock with superior torque delivery.
- India's PLI scheme for electric components:The incentive structure is drawing component suppliers toward domestic manufacturing of motors and battery packs for 300cc-equivalent electric variants.
- Parallel-twin liquid cooling:This configuration is displacing air-cooled singles in premium commuter segments by delivering sustained highway performance without thermal degradation.
Market Restraints
- Catalytic converter palladium dependency:Euro 5 mandates have tied exhaust system costs to volatile precious metal markets, squeezing margin on entry-priced models.
- Indonesian component concentration:Southeast Asian assembly plants rely heavily on Indonesian-sourced forgings and castings, creating vulnerability to archipelago logistics disruptions.
- Electric range anxiety:300cc-equivalent electric motorcycles face persistent buyer skepticism about highway-range adequacy versus petrol alternatives.
Strategic Opportunities
- Vietnam's underserved central provinces:Da Nang and Hue represent white-space markets where 300cc adoption lags behind Hanoi and Saigon despite comparable income levels.
- Battery-swapping infrastructure:Gogoro-style networks are emerging as a channel innovation that eliminates home-charging barriers for apartment-dwelling urban buyers.
- Thai excise tax restructuring:The revised CO2-based levy favors sub-150g/km motorcycles, creating a regulatory tailwind for efficient 300cc designs.
Industry Challenges
- Homologation timeline compression:Euro 5 certification cycles have stretched from 18 to 28 months, delaying model-year launches and freezing R&D budgets.
- Power electronics integration:Electric variant development demands scarce firmware engineers capable of blending motor control with vehicle dynamics algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 300cc Motorcycle Market |
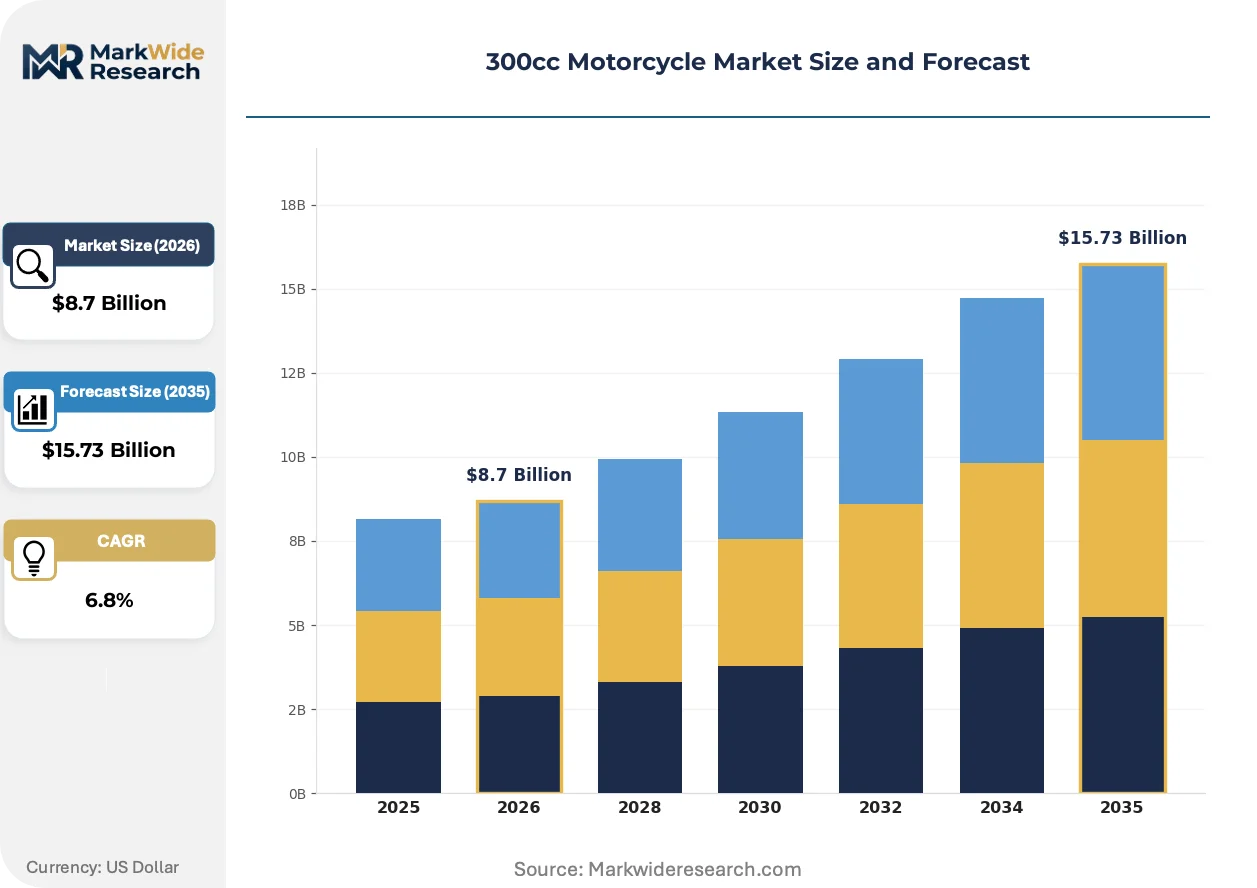
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport Bike, Cruiser, Touring Bike, Dirt Bike End User: Personal Use, Commercial Use, Rental Services, Racing Fuel Type: Petrol, Electric, Hybrid, CNG Distribution Channel: Dealerships, Online Retailers, Auctions, Direct Sales |
| Companies Covered | Benelli, CFMOTO, Honda, Voge, Zontes, KTM, Rieju, QJMOTOR, Husqvarna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
300cc Motorcycle Market Emerging Trajectories
Powertrain electrification and connected-vehicle architectures are rewriting the engineering priorities that once governed 300cc development, shifting investment from mechanical refinement to software-defined performance mapping.
Integrated starter-generator systems are consolidating starting, charging, and mild-hybrid assist functions into single compact units. Southeast Asian OEMs are adopting these modules fastest to meet stop-start traffic demands without weight penalties. The technology is consolidating accessory electrical architectures and reducing component count by thirty percent versus conventional setups.
India's BIS is tightening noise and emission testing protocols for 2025 model-year certification, extending laboratory test cycles to capture real-driving-condition variability. Domestic manufacturers must retool dyno facilities and revalidate entire engine families. The sport-bike segment faces the steepest compliance cost escalation due to higher specific-output engines.
Subscription-based ownership models are emerging in Malaysian and Indonesian cities, replacing traditional installment purchase with monthly fees covering bike, insurance, and maintenance. Younger riders in Kuala Lumpur and Jakarta are accepting these arrangements to access premium 300cc hardware without down-payment burdens. Dealership networks are responding by converting floor space to service bays and digital onboarding terminals.
300cc Motorcycle Market Segmentation
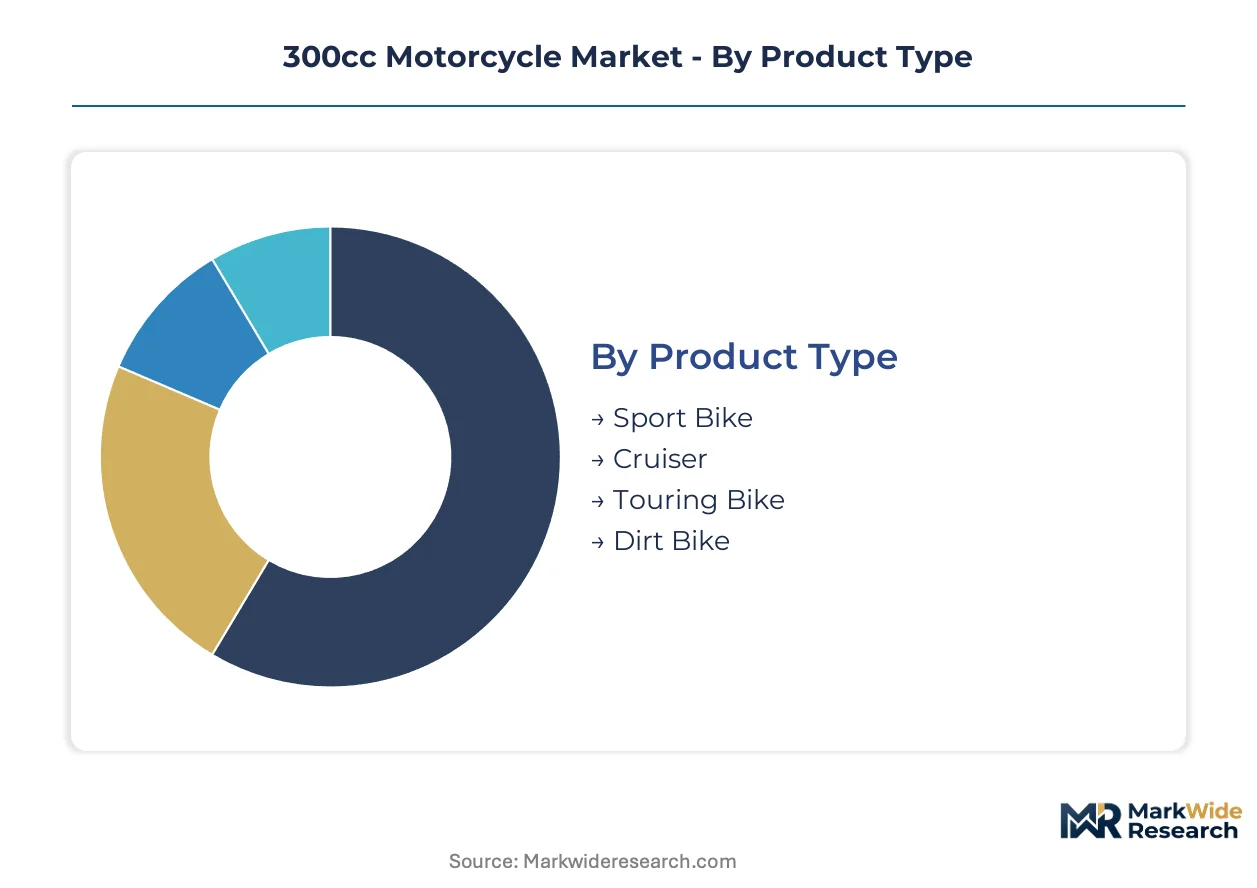
Segmentation in the 300cc motorcycle market reveals how engineering trade-offs align with distinct use cases and buyer economics. Each category reflects divergent cost structures, regulatory exposure, and channel access requirements that shape manufacturer portfolio decisions.
Product Type:
Supply concentration in frame fabrication and engine casting favors platforms that share components across high-volume variants.
- Sport Bike:Aggressive ergonomics and high-revving parallel-twin engines define this segment. Demand clusters among younger riders in Indonesia and Vietnam where styling commands premium pricing over pure commuter utility. Euro 5 compliance costs hit hardest here due to high specific-output powertrains requiring sophisticated catalytic systems.
- Dirt Bike:Long-travel suspension and high-ground-clearance frames accommodate off-road terrain. Thai and Malaysian buyers drive volume for weekend trail riding and agricultural access where paved roads remain sparse. Emission regulations exempt many off-road configurations, preserving simpler carbureted architectures in certain markets.
- Cruiser:Low-slung seating and torque-biased V-twin engines target mature riders in North American and Western European markets.
- Touring Bike:Wind protection and luggage capacity suit extended highway journeys, with demand concentrated in Japan and South Korea.
Sport Bike absorbs the bulk of installed capacity; Dirt Bike is expanding most quickly.
End User:
Customer type determines financing structures, insurance costs, and service interval expectations that ripple back to manufacturing specifications.
- Personal Use:Individual ownership dominates volume across all geographies. Indian buyers prioritize fuel efficiency and low maintenance costs, while Southeast Asian commuters emphasize maneuverability in dense urban traffic. Financing penetration varies sharply by market, from cash-dominant Vietnam to highly leveraged Malaysian purchases.
- Commercial Use:Fleet operators and delivery services demand durability and standardized maintenance protocols. Indonesian logistics companies and Indian food-delivery platforms are consolidating procurement around specific 300cc models with proven uptime records. Bulk purchasing power compresses margins but guarantees production volume.
- Rental Services:Short-term hire operators in tourist corridors require crash-resistant bodywork and simplified rider interfaces.
- Racing:Homologation requirements for entry-level competition classes drive limited-production variants with upgraded suspension and engine management.
Personal Use captures the majority of unit shipments; Commercial Use is climbing the fastest as platform economies professionalize two-wheel logistics.
Fuel Type:
Powertrain architecture choices reflect divergent infrastructure maturity and total cost-of-ownership calculations across buyer segments.
- Petrol:Internal combustion engines with port or direct fuel injection retain dominance due to refueling infrastructure density. Indian and Southeast Asian markets depend on this configuration for highway range and cold-start reliability. Euro 5 and India's BIS emission timelines are forcing widespread adoption of closed-loop fuel injection and catalytic aftertreatment.
- Electric:Battery-electric powertrains with 300cc-equivalent performance are gaining traction in Chinese and Taiwanese urban markets. Gogoro-style swapping networks in Taipei and emerging Indian battery-as-a-service models eliminate home-charging barriers for apartment dwellers. Range limitations constrain adoption for intercity travel.
- Hybrid:Mild-hybrid architectures with integrated starter-generators are penetrating premium commuter segments in Japan and South Korea.
- CNG:Compressed natural gas conversions serve niche fleet applications in India where fuel price arbitrage justifies infrastructure investment.
Petrol retains the steepest share of production throughput; Electric is gaining share fastest as battery costs decline and swapping infrastructure spreads.
Distribution Channel:
Channel configuration determines working capital requirements, brand control, and aftermarket revenue capture for manufacturers.
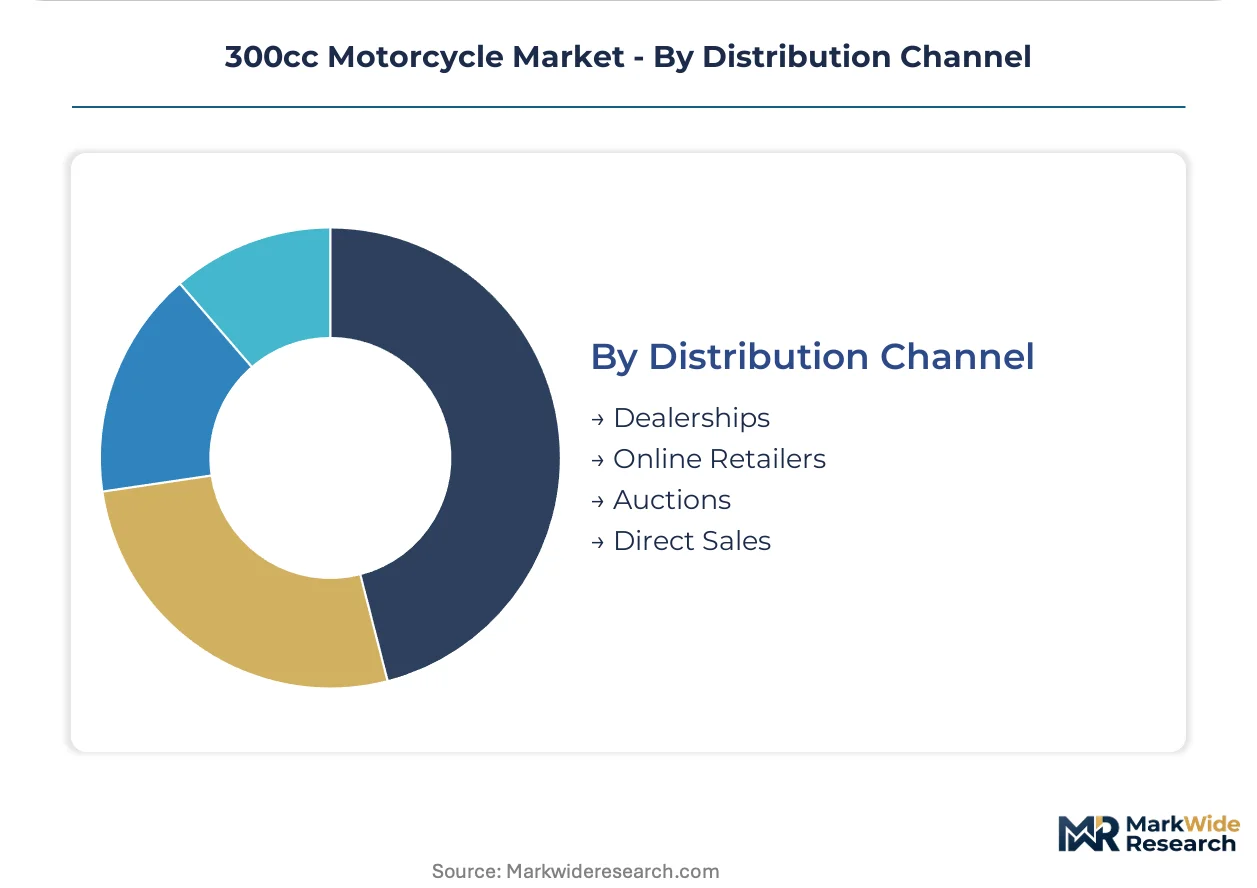
- Dealerships:Physical retail networks with service bays dominate in markets requiring test rides and financing facilitation. Indian and Indonesian buyers depend on dealer relationships for maintenance continuity and parts availability. OEMs are consolidating dealer counts while expanding per-location service capacity.
- Online Retailers:Digital-first sales with home delivery or pickup-point fulfillment are penetrating Malaysian and Thai urban markets. Younger buyers accept remote purchase for known models, though physical inspection remains preferred for first-time 300cc adoption. Logistics complexity limits penetration outside major metropolitan zones.
- Auctions:Secondary market clearinghouses handle fleet turnover and insurance salvage in mature markets.
- Direct Sales:Manufacturer-owned stores and subscription programs are emerging in Singapore and Hong Kong.
Dealerships anchor the majority of transaction volume; Online Retailers are expanding most quickly among digitally native buyer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment Zone 3 tax incentives have concentrated 300cc assembly capacity in the Eastern Economic Corridor, drawing component suppliers from across ASEAN to Rayong and Chonburi provinces.
India
Maharashtra and Tamil Nadu host the densest clusters of 300cc manufacturing, with Pune-based plants serving domestic sport-bike demand and Chennai facilities feeding Southeast Asian exports. India's BIS is tightening noise and emission testing protocols for 2025 model-year certification, extending laboratory test cycles to capture real-driving-condition variability. The Delhi-NCR corridor generates disproportionate premium-variant uptake despite severe air-quality restrictions on older petrol vehicles.
Indonesia
Jakarta's congestion premium drives trading-up from 125cc scooters to 300cc motorcycles that cut through gridlock with superior torque delivery. The Ministry of Industry's local content requirements force foreign OEMs to source forgings and castings from Indonesian suppliers, creating archipelago logistics vulnerabilities. Surabaya and Bandung have emerged as secondary demand poles where younger riders prioritize performance aesthetics.
Vietnam
Ho Chi Minh City and Hanoi dominate unit volumes, yet Da Nang and Hue represent underserved white-space markets where 300cc adoption lags despite comparable income levels. The government's electric vehicle roadmap includes two-wheeler charging infrastructure commitments that favor battery-swapping networks over home-charging solutions. Hai Phong's port facilities are attracting regional distribution center investments.
Thailand
Bangkok's stop-start traffic demands integrated starter-generator systems that consolidate starting, charging, and mild-hybrid assist functions. The Excise Department's revised CO2-based levy favors sub-150g/km motorcycles, creating regulatory tailwinds for efficient 300cc designs. The Eastern Economic Corridor's Zone 3 incentives have anchored Honda and KTM assembly operations alongside tier-one component suppliers.
Philippines
Metro Manila's motorcycle-taxi regulatory experiments are professionalizing fleet procurement around specific 300cc models with proven uptime records. The Department of Trade and Industry's tariff structures favor ASEAN-sourced over fully-imported units. Cebu has developed as a Visayas distribution hub serving island-hopping commercial operators.
300cc Motorcycle Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the 300cc segment, creating a tiered structure where integrated powertrain manufacturers sustain margin resilience under tighter emission budgets. The competitive landscape consolidates around three strategic archetypes: Japanese conglomerates with captive component ecosystems, European performance specialists commanding premium positioning, and Chinese scale players leveraging domestic manufacturing depth. Dominant competitive moves include strategic partnerships for battery-swapping infrastructure and geographic expansion into underserved provincial markets.
Within the integrated conglomerate tier, Honda anchors Japanese manufacturing presence through Thai and Indian assembly networks. European specialists KTM and Husqvarna occupy performance-positioning segments that command pricing premiums through Austrian-engineered architectures. At the scale-driven end, CFMOTO exemplifies Chinese export expansion into Southeast Asian markets through aggressive pricing and platform-sharing across multiple displacement categories.
| Leading Market Players |
|---|
| Benelli |
| CFMOTO |
| Honda |
| Voge |
| Zontes |
| KTM |
| Rieju |
| QJMOTOR |
| Husqvarna |
| Others |
Supply Flow & Price Mechanics
Precision machining labor pools in Pune and Chennai create labor-cost differentials that widen pricing-tier spreads between premium Austrian-engineered models and mass-market Chinese exports.
Pricing Analysis
Short lead-time premiums attach to Thai-assembled Honda and KTM units serving Southeast Asian dealers, while spot inventory discounts clear aging Euro 4-compliant stock ahead of BIS certification deadlines. Pricing stratifies across premium, standard, and economy tiers based on emission certification grade and after-sales service bundling. Cost compression in entry-level segments intensifies as palladium-loaded catalytic converters absorb margin. Fleet operators in Indonesia exhibit highest price sensitivity; European performance buyers show lowest.
Supply Chain Analysis
Regional distribution centers in Hai Phong, Rayong, and Jakarta anchor hub-and-spoke patterns feeding ASEAN dealer networks. Manufacturing concentrates in Thailand, India, and China. Engine forgings draw from Indonesian suppliers; electronics modules feed from South Korean and Taiwanese sources. Single-source vulnerability runs through archipelago-dependent Indonesian casting supply. Distribution runs through OEM-controlled dealer networks with captive parts warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated starter-generator systems are displacing conventional electrical architectures, creating a technology-transition phase where firmware capability separates viable platforms from legacy mechanical designs.
For Market Incumbents: Lock in catalytic converter supply agreements with South Korean palladium processors before Euro 6 pre-announcements tighten further. Deepen backward integration into ECU firmware development to counter emerging Chinese scale players with in-house motor control algorithms.
For New Entrants and Emerging Players: India's PLI scheme for electric components opens a window for battery-pack assembly joint ventures serving 300cc-equivalent electric variants. Target Vietnam's central provinces with swapping-network partnerships. Pursue direct-to-fleet sales bypassing dealer margin capture.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated powertrain manufacturers given BIS certification timeline compression favoring captive engine development. Long-term viability hinges on electric-variant platform readiness. Monitor Gogoro-style swapping network expansion rates as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Partnership | Gogoro-style networks eliminate apartment-dwelling charging barriers in Taipei and emerging Indian metros. |
| Integrated Starter-Generator Platform Standardization | Honda's Thai assembly consolidation reduces component count thirty percent versus conventional electrical setups. |
| Backward Integration into Catalytic Converter Supply | KTM's Austrian engineering captive sourcing insulates margin from volatile palladium spot markets. |
| Direct Fleet Sales Channel Development | Indonesian logistics platforms professionalize procurement around uptime-guaranteed 300cc models. |
| Firmware-Defined Performance Mapping Investment | Electric variant differentiation shifts from mechanical refinement to motor control algorithm sophistication. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, ASEAN dealer principals, Tier 1 forging suppliers, and fleet procurement managers at Indonesian logistics platforms. BIS certification databases, Thai Excise Department CO2 levy schedules, and India PLI scheme disclosures provided regulatory calibration. Bottom-up production volume estimates triangulated against top-down regional demand aggregation.
Data-stream reconciliation across shipment records, registration databases, and dealer inventory indices shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, fuel architecture, end-use category, and distribution channel. CAGRs derived from regression against macroeconomic drivers and regulatory phase-in schedules. Battery cost curves and swapping network deployment rates informed electric-variant trajectory assumptions.
Caveats apply where palladium price spikes, Indonesian logistics disruptions, or Euro 6 acceleration could materially shift the outlook. Forecasts reflect documented assumptions on emission compliance timelines and infrastructure buildout rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Switzerland E-Bike Market