
 United Arab Emirates E-Bike Market | 2026-2036
United Arab Emirates E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates E-Bike Market Analytics
Modular battery subscription bundles is consolidating buyer choice across the United Arab Emirates E-Bike Market, as fleet operators prefer separating hardware ownership from energy service costs. EMOTORAD Electric Bikes leverages direct-to-fleet partnerships to anchor its position in commercial delivery channels. Giant Manufacturing Co. Ltd sustains manufacturing scale advantages that allow competitive positioning across multiple price tiers. Trek Bicycle Corporation differentiates through service-network density in Dubai and Abu Dhabi retail corridors.
An e-bike integrates an electric motor, rechargeable battery pack, and pedal-assist or throttle-based propulsion system into a bicycle frame, typically delivering power outputs between 250W and 750W for regulated road use. The primary commercial purpose spans urban commuting, cargo logistics, and recreational mobility where human-powered effort requires electric augmentation for distance, load, or terrain. City E-Bikes dominate unit volumes among consumers seeking commuting solutions, while Cargo E-Bikes capture expanding margin pools as delivery services replace van-based last-mile operations. Lithium-Ion battery configurations lead technology adoption due to energy density advantages, though fleet operators increasingly scrutinize total-cycle-cost economics against emerging sodium-ion alternatives.
MOHAP product safety standards, UAE Cabinet Resolution on sustainable mobility frameworks, and Dubai Municipality cycling infrastructure codes collectively shape import clearance, vehicle classification, and road-access permissions for electric-assisted bicycles. The UAE's federal net-zero pathway tightens emissions benchmarks for commercial logistics, indirectly accelerating e-bike fleet substitution against internal-combustion delivery vehicles. Stakeholders must monitor how MOHAP and local transport authorities reconcile personal-mobility classifications with emerging commercial-use registrations, as this boundary determines insurance obligations, operator licensing, and permissible motor-power thresholds.
Market Dynamics
Fleet operators in Dubai and Abu Dhabi are decoupling hardware ownership from energy service costs through modular battery subscription bundles, restructuring procurement economics across commercial delivery channels.
Growth Catalysts
- MOHAP Safety Certification:Tightened product standards under the UAE's federal health regulator are accelerating import compliance investments, filtering low-quality suppliers from the market and elevating certified hardware penetration in commercial fleets.
- Net-Zero Mobility Targets:The UAE Cabinet Resolution on sustainable transport frameworks mandates emissions reductions in urban logistics, indirectly compelling delivery operators to substitute internal-combustion vans with electric-assisted cargo bicycles.
- Last-Mile Delivery Expansion:E-commerce fulfillment networks across Dubai's commercial corridors are scaling e-bike procurement to compress operating costs and navigate congestion-prone urban cores.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian manufacturing hubs, exposing UAE importers to shipping cost volatility and currency fluctuation risks that compress fleet procurement budgets.
- MOHAP Classification Ambiguity:Unclear boundaries between personal-mobility and commercial-use registrations under federal transport rules create insurance and licensing friction for fleet operators scaling beyond pilot deployments.
- Desert Climate Degradation:Extreme heat cycling accelerates lithium-ion cell degradation, shortening replacement intervals and raising total-cost-of-ownership calculations against conventional delivery vehicles.
Strategic Opportunities
- Ras Al Khaimah Tourism Corridors:Underpenetrated northern emirate markets present expansion potential for guided e-bike tour operators seeking alternatives to saturated Dubai and Abu Dhabi leisure zones.
- Sodium-Ion Battery Convergence:Emerging chemistry alternatives promise improved thermal stability and lower raw-material dependency, offering fleet operators a pathway to reduce lifecycle energy costs.
- Dubai Municipality Cycling Infrastructure Codes:Dedicated lane expansion and parking bay mandates are creating regulatory tailwinds that reduce operational friction for commercial delivery cyclists in urban core zones.
Industry Challenges
- Certification Timeline Compression:MOHAP product safety testing protocols require extended lead times for new model approvals, delaying fleet refresh cycles and locking operators into legacy hardware longer than planned.
- Technician Skill Scarcity:Specialized repair capabilities for mid-drive motor systems and battery management electronics remain concentrated in Dubai service centers, creating maintenance bottlenecks for fleets operating across dispersed emirate networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates E-Bike Market |
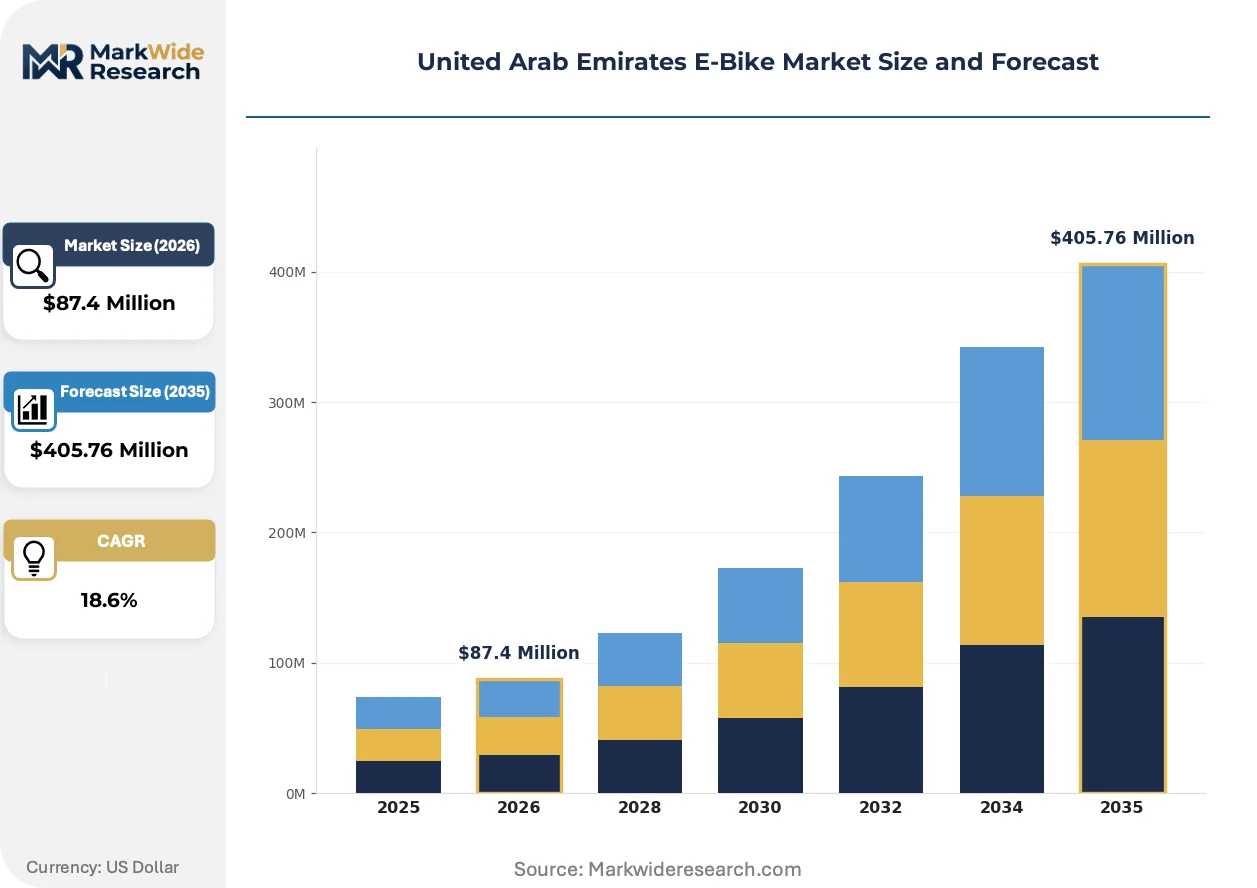
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $405.76 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes End User: Consumers, Delivery Services, Tour Operators, Municipalities Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Sales Channel: Online Retail, Specialty Stores, Distributors, Direct Sales |
| Companies Covered | EMX Motors LLC, Giant Manufacturing Co. Ltd, EMOTORAD Electric Bikes, Sulmi, Eveons Mobility Systems LLC, Trek Bicycle Corporation, Wolfis Bikes, Specialized Bicycle Components, Inc, Saluki Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates E-Bike Market Evolving Landscape
Hardware-software integration and energy-service unbundling are restructuring how commercial buyers acquire and operate electric-assisted bicycles across UAE urban logistics networks.
Sodium-ion battery chemistry is absorbing fleet operator attention as a thermal-stability alternative to lithium-ion configurations. Delivery services in Dubai's commercial corridors are piloting sodium-powered cargo models during summer peak loads. This chemistry shift is absorbing total-cost-of-ownership calculations previously dominated by energy density metrics alone.
MOHAP product safety standards are tightening import clearance protocols for electric-assisted bicycles entering UAE free zones. The federal regulator's expanded testing requirements are extending pre-market approval timelines. Commercial fleet operators are responding by consolidating procurement around established certified suppliers to reduce compliance risk exposure.
Subscription-based battery service models are displacing upfront capital expenditure for energy storage components. Logistics operators in Abu Dhabi's last-mile networks are separating hardware ownership from monthly energy access fees. This financing structure is most visible among mid-scale delivery fleets seeking to preserve working capital for route expansion.
United Arab Emirates E-Bike Market Segmentation
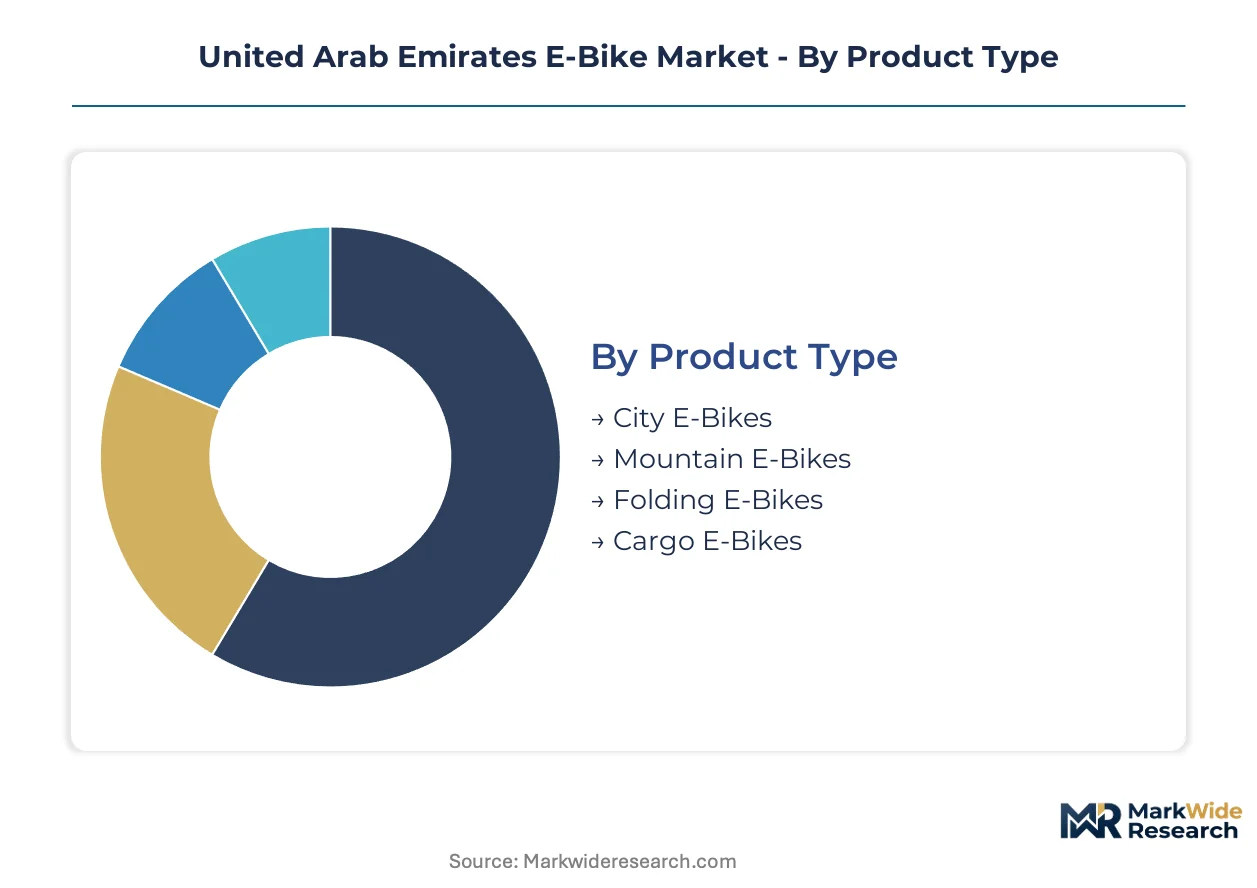
E-bike segmentation in the UAE reflects divergent procurement logics between integrated fleet systems and standalone consumer purchases. Commercial buyers prioritize total-cost-of-ownership metrics, while individual riders emphasize convenience and recreational utility. Understanding these segment boundaries clarifies where hardware ownership, energy services, and maintenance obligations separate across buyer types.
Product Type:
Standalone hardware dominates consumer-facing channels, whereas embedded fleet systems concentrate in commercial logistics configurations where bicycles integrate with route management platforms.
- City E-Bikes:Step-through frames and moderate motor outputs characterize urban commuting specifications. Dubai's residential corridors and metro-adjacent neighborhoods concentrate consumer demand, driven by congestion avoidance and parking scarcity in commercial districts.
- Cargo E-Bikes:Extended wheelbases and reinforced frames accommodate parcel loads exceeding 100kg. Abu Dhabi and Dubai delivery fleets are replacing van-based last-mile operations, compelled by fuel cost compression and MOHAP emissions alignment requirements.
- Mountain E-Bikes:Full-suspension systems and torque-rich mid-drive motors serve Hatta and Jebel Jais recreational terrain.
- Folding E-Bikes:Collapsible frames address multi-modal commuters bridging metro and final-mile segments.
Volume placements concentrate in City E-Bikes; the faster expansion belongs to Cargo E-Bikes.
End User:
Cost tier separation distinguishes capital-intensive fleet operators from discretionary consumer spenders, with procurement scale and financing structure diverging sharply across these boundaries.
- Delivery Services:Fleet-scale procurement with subscription-based battery service models compresses upfront capital requirements. Dubai's e-commerce fulfillment networks and Abu Dhabi's food delivery aggregators anchor commercial volume, restructuring total-cost-of-ownership calculations through hardware-software integration.
- Consumers:Individual purchasers prioritize retail accessibility and service network density for warranty claims. Dubai Marina and Downtown Dubai residential clusters show strongest penetration, supported by cycling lane expansion under Dubai Municipality infrastructure codes.
- Tour Operators:Guided leisure rentals in Ras Al Khaimah and Al Ain seek durable hardware with simplified maintenance protocols.
- Municipalities:Public bike-share procurement emphasizes standardization and centralized fleet management capabilities.
Delivery Services command the largest transaction values; Consumers maintain the broadest unit placement base.
Battery Type:
Margin concentration tracks chemistry maturity, with established lithium-ion configurations defending position against emerging alternatives promising thermal stability advantages.
- Lithium-Ion:Cylindrical and prismatic cell formats deliver energy density above 250Wh/kg, enabling range specifications critical for commercial route completion. Dubai and Abu Dhabi fleet operators standardize on this chemistry despite desert heat degradation shortening replacement cycles.
- Lithium Polymer:Pouch cell architectures permit flexible form factors for frame-integrated battery designs. Folding E-Bike manufacturers favor this configuration where space constraints override energy density priorities.
- Lead-Acid:Legacy chemistry persists in price-sensitive entry-level consumer segments.
- Nickel-Metal Hydride:Limited penetration remains confined to replacement markets and specific municipal procurement specifications.
Lithium-Ion retains dominant placement share; Lithium Polymer is gaining share fastest in compact form-factor applications.
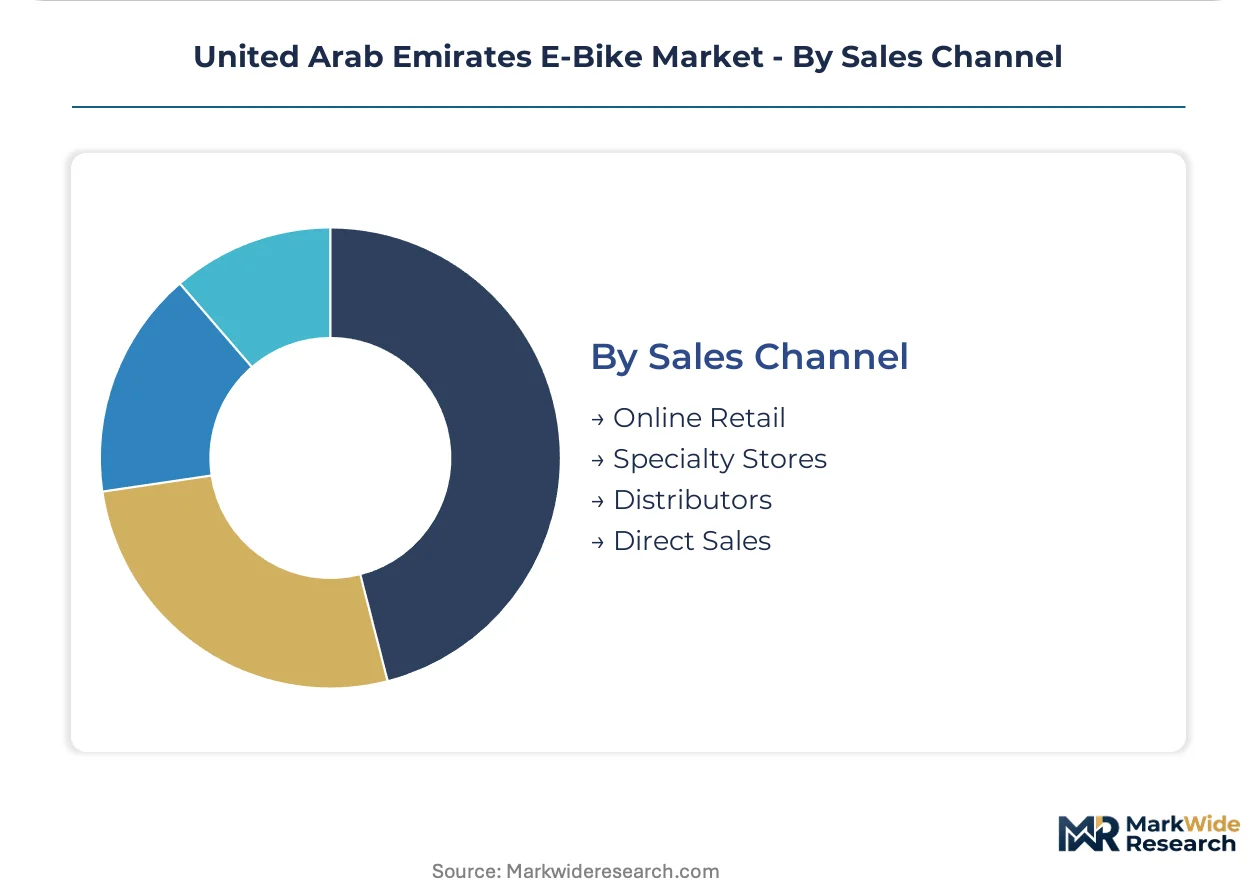
Sales Channel:
Supply concentration in Dubai's retail corridors shapes channel economics, with service proximity determining procurement preferences across dispersed emirate networks.
- Specialty Stores:Physical showrooms with certified technician capacity dominate consumer confidence, particularly for mid-drive motor systems requiring specialized maintenance. Dubai's Deira and Abu Dhabi's Al Wahda Mall corridors concentrate this channel.
- Direct Sales:Fleet operators in Dubai's logistics zones negotiate hardware-software bundles directly with manufacturers, bypassing retail markups and consolidating procurement across multi-hundred-unit deployments.
- Online Retail:E-commerce platforms serve price-comparison shoppers in secondary emirates with limited specialty store presence.
- Distributors:Wholesale networks extend reach into northern emirates and commercial procurement channels requiring consolidated invoicing.
Specialty Stores anchor consumer volume; Direct Sales commands the steepest expansion trajectory in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's free zone incentives and logistics corridor density concentrate commercial e-bike deployment across the emirate. Abu Dhabi's sovereign wealth-backed infrastructure programs accelerate fleet procurement timelines. Northern emirates present expansion frontiers where tourism and light logistics applications remain underdeveloped.
Dubai
Last-mile delivery networks and e-commerce fulfillment hubs drive fleet-scale procurement across Jebel Ali and Al Quoz industrial zones. Dubai Municipality cycling infrastructure codes mandate dedicated lane expansion and commercial parking bay allocations. Deira and Al Qusais corridors host the highest density of specialty retail and service technician capacity.
Abu Dhabi
Food delivery aggregators and pharmaceutical logistics operators anchor commercial demand in the capital's central business district. The Department of Municipalities and Transport integrates e-bike access into sustainable mobility framework implementations. Yas Island and Saadiyat tourism zones pilot guided rental fleets for leisure mobility substitution.
Sharjah
Price-sensitive consumer segments and university-adjacent commuting corridors sustain retail volume in the emirate's residential clusters. Sharjah Roads and Transport Authority aligns with federal MOHAP safety certification requirements for personal mobility classifications. University City and Al Nahda districts concentrate folding e-bike adoption among student populations.
Ras Al Khaimah
Adventure tourism operators and coastal hospitality developers seek durable hardware for guided excursion fleets across Jebel Jais mountain terrain. The Ras Al Khaimah Tourism Development Authority promotes sustainable mobility integration within hospitality masterplans. Al Marjan Island and Dhayah Fort corridors represent emerging deployment zones for rental and tour applications.
Ajman and Fujairah
Light commercial logistics and cross-emirate delivery routes sustain entry-level cargo e-bike penetration in these smaller northern markets. Federal transport regulations apply uniformly without emirate-specific mobility framework variations. Ajman Industrial Area and Fujairah Port periphery concentrate limited fleet operations serving last-mile connectivity gaps.
United Arab Emirates E-Bike Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing and energy service provision. Market structure exhibits moderate consolidation with tiered positioning between mass-market assemblers and premium-tier brands. Three archetypes dominate: global bicycle manufacturers leveraging manufacturing scale, regional fleet-service integrators unbundling hardware from energy subscriptions, and specialty retailers anchoring consumer confidence through service network density. Competitive moves center on direct-to-fleet partnership structures and certified service capacity expansion.
Among global-scale fabricators, Giant Manufacturing Co. Ltd and Trek Bicycle Corporation occupy positions defined by manufacturing throughput and retail corridor presence respectively. EMOTORAD Electric Bikes exemplifies the fleet-integrator archetype through direct commercial channel engagement. EMX Motors LLC and Eveons Mobility Systems LLC represent UAE-based entities positioned within local assembly and distribution functions.
| Leading Market Players |
|---|
| EMX Motors LLC |
| Giant Manufacturing Co. Ltd |
| EMOTORAD Electric Bikes |
| Sulmi |
| Eveons Mobility Systems LLC |
| Trek Bicycle Corporation |
| Wolfis Bikes |
| Specialized Bicycle Components, Inc |
| Saluki Bikes |
| Others |
Value Network & Pricing Analysis
The UAE Cabinet Resolution on sustainable mobility frameworks gates qualified supply and premium-tier pricing access, as MOHAP certification compliance separates certified fleet-grade hardware from uncertified consumer imports while subscription-based battery service models restructure how commercial buyers absorb upfront capital requirements.
Pricing Analysis
Cost-down pressure on mid-tier cargo configurations accelerates because fleet operators decouple hardware ownership from energy service costs through modular battery subscriptions. Three-tier pricing structure across premium certified fleet-grade, standard consumer retail, and economy direct-import levels separates buyers by MOHAP compliance status and after-sales service bundling. Price differentiation traces to certification tier and volume procurement scale, with delivery aggregators least price-sensitive due to total-cost-of-ownership optimization against van-based alternatives.
Supply Chain Analysis
Regional distribution centers in Dubai's Jebel Ali Free Zone anchor hub-and-spoke patterns feeding northern emirate markets. Battery cell production concentrates in China, South Korea, and Japan, with frame fabrication and final assembly drawing from Taiwan and Vietnam. Lithium carbonate, nickel sulfate, and rare-earth magnet materials feed from concentrated extraction zones. Single-source vulnerability in cylindrical cell formats exposes fleet procurement timelines to shipping volatility. Distribution runs through direct-to-fleet partnerships for commercial volumes and specialty retail corridors for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing backward integration into battery cell supply and captive service technician training to control total-cost-of-ownership calculations.
For Market Incumbents: Lock in fleet-grade certification pipelines by deepening MOHAP testing relationships and expanding Jebel Ali service technician capacity before sodium-ion chemistry shifts disrupt lithium-ion replacement cycle economics. Defend against emerging pure-play battery-service entrants by anchoring direct commercial channel control. For New Entrants and Emerging Players: Capture Ras Al Khaimah tourism corridor whitespace and Sharjah university-adjacent folding e-bike segments where incumbent service network density remains thinnest. Penetrate through direct online-to-offline distribution partnerships with northern emirate hospitality developers. For Investors and Strategic Acquirers: Sodium-ion pilot deployments by Dubai delivery fleets reaching commercial scale is the leading indicator that chemistry transition timelines are compressing. Long-term viability favors fleet-service integrators with hardware-software platform control over pure manufacturing plays. Target acquisition archetypes combine MOHAP-certified assembly capacity with subscription billing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Transition | Sodium-ion pilot programs by Dubai delivery operators signal thermal-stability validation timelines. |
| Direct-to-Fleet Partnership | Hardware-software bundles bypass retail markups and consolidate multi-hundred-unit procurement decisions. |
| Service Network Expansion | Certified technician capacity in Deira and Al Wahda Mall corridors anchors consumer warranty confidence. |
| MOHAP Certification Investment | Pre-market approval capabilities filter low-quality suppliers and accelerate fleet refresh cycles. |
| Tourism Corridor Development | Ras Al Khaimah and Al Ain guided rental fleets substitute sustainable mobility for van-based excursion logistics. |
Research Methodology
Document review covered MOHAP regulatory filings, Dubai Municipality infrastructure codes, and UAE federal transport resolutions, complemented by interviews with fleet operations directors at delivery aggregators, procurement leads at e-commerce fulfillment networks, specialty retail service managers, and lithium-ion battery supply specialists. Secondary validation drew from customs import records, free zone trade data, and cycling infrastructure investment disclosures. Bottom-up unit placement estimates triangulated against top-down addressable logistics fleet calculations.
Cross-referencing historical procurement patterns against panel input from commercial buyers and distributor networks shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, battery chemistry configuration, and sales channel structure. CAGRs derived from logistic function fitting to fleet penetration curves and consumer adoption saturation levels, with inputs from route-density optimization models and thermal-degradation replacement cycle assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sodium-ion commercialization timelines, MOHAP classification rule clarifications, and lithium raw material price volatility. Outputs reflect documented assumption sets around fleet-scale deployment rates and infrastructure buildout schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Motorcycle Airbag Market