
 Sweden E-Bike Market | 2026-2036
Sweden E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden E-Bike Market Analytics
Market Context
China is fragmenting as Taiwanese and Vietnamese assembly plants capture mid-motor contracts from European brands. Kalkhoff Werke GmbH leverages German engineering heritage to dominate premium trekking configurations in Nordic markets. VanMoof BV sustains direct-to-consumer channel control with integrated electronics and app-locked security systems. Ecoride AB anchors domestic assembly capacity outside Jönköping, supplying municipal procurement frameworks with service-ready fleet models.
Technical Definition and Segments
An e-bike is a bicycle equipped with an integrated electric motor delivering pedal-assist or throttle-driven propulsion, typically powered by lithium-ion battery packs rated between 250W and 750W output with torque sensors governing power modulation. The primary commercial purpose centers on extending rider range, reducing physical exertion thresholds, and displacing short-distance combustion-engine trips in urban and suburban environments. City e-bikes occupy the volume core as Swedish municipalities expand bike-lane networks and employer subsidy schemes, while cargo e-bikes represent the fastest-expanding margin pool as logistics operators and family buyers replace second cars with electric-assisted load carriers. Folding e-bikes attract apartment-dwelling commuters in dense Stockholm and Malmö districts where storage constraints limit full-frame alternatives.
Regulatory Environment
Sweden's Transport Agency enforces EU type-approval framework 168/2013 capping motor assistance at 25 km/h for unlicensed operation, while the Swedish Environmental Protection Agency coordinates with the EU Green Deal to channel infrastructure grants toward cycling superhighways. The National Board of Housing, Building and Planning mandates parking minimums for residential developments, indirectly shaping e-bike storage and charging access in new construction. Stakeholders must monitor proposed revisions to EU battery passport requirements and Sweden's national carbon budget allocations that could reshape subsidy eligibility and end-of-life recycling obligations.
Market Dynamics
Sweden's municipal cycling infrastructure grants are compressing replacement cycles for conventional bicycles while channeling procurement toward cargo-configured fleet models with integrated service contracts.
Growth Catalysts
- EU Green Deal infrastructure funding:Sweden's cycling superhighway allocations accelerate lane construction in Stockholm, Gothenburg, and Malmö metropolitan corridors.
- Last-mile logistics electrification:Postal operators and grocery chains in Scania County are standardizing cargo e-bike fleets for urban delivery routes under 15 kilometers.
- Lithium-ion cell cost curves:Battery pack economics improve range-to-weight ratios for family transport configurations replacing second household vehicles.
Market Restraints
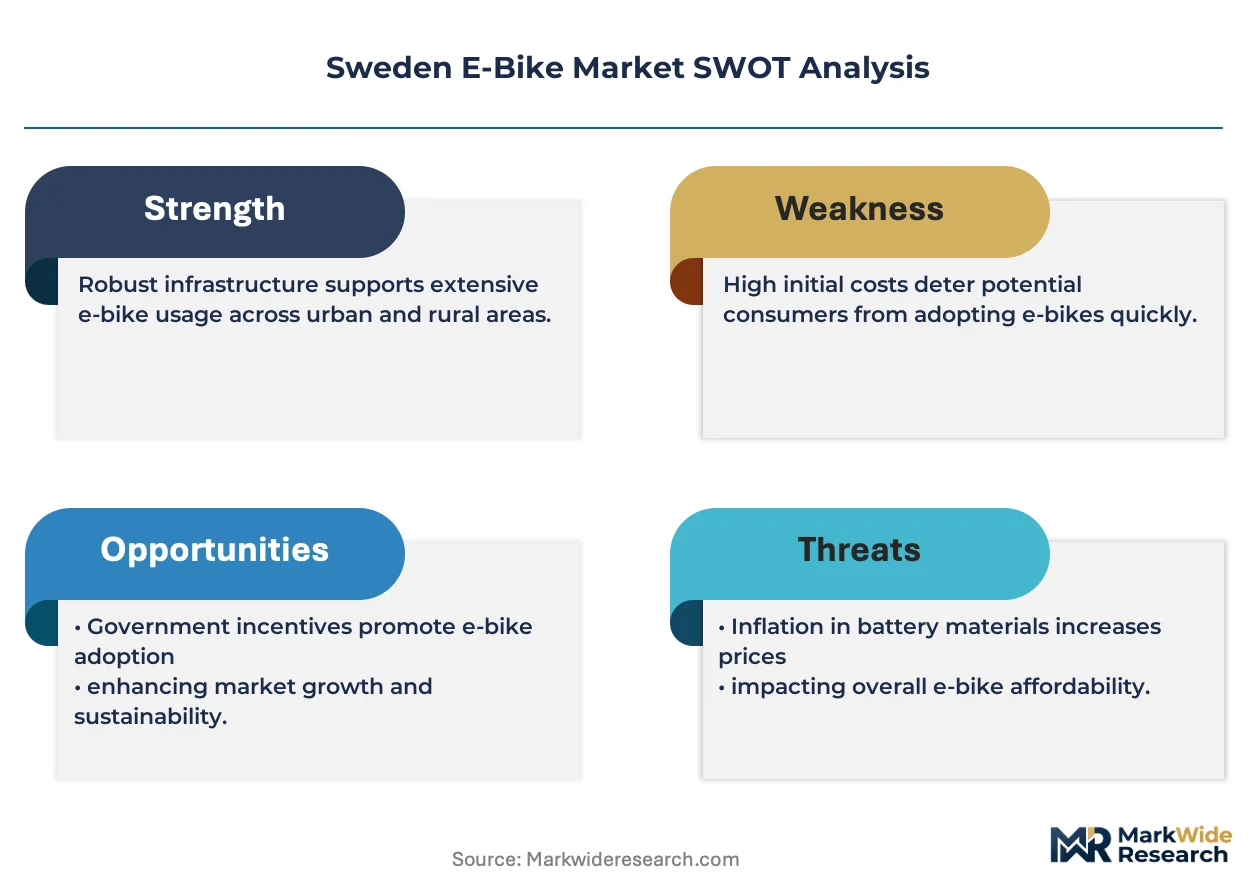
- Mid-motor supply concentration:Taiwanese and Vietnamese assembly plants control contract manufacturing for European brand motor systems, creating single-source vulnerability.
- EU battery passport compliance:Traceability mandates for cell chemistry and recycling chains add documentation overhead before products reach Swedish retailers.
- Winter performance degradation:Cold-weather range contraction limits year-round commuter reliance on pedal-assist systems in Norrland counties.
Strategic Opportunities
- Västra Götaland county expansion:Gothenburg's employer mobility subsidy schemes remain underpenetrated by fleet service providers with maintenance networks.
- Integrated electronics convergence:Torque sensors, GPS tracking, and app-locked security systems merge into subscription-managed mobility packages.
- Swedish Environmental Protection Agency grants:Carbon budget allocations for cycling infrastructure create dedicated procurement pools for domestic assemblers.
Industry Challenges
- Certification timeline compression:EU type-approval framework 168/2013 revisions require retesting for software-updatable motor controllers.
- Service network scaling:Municipal fleet contracts demand 4-hour response times for mechanical failures, straining technician deployment in rural Norrland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden E-Bike Market |
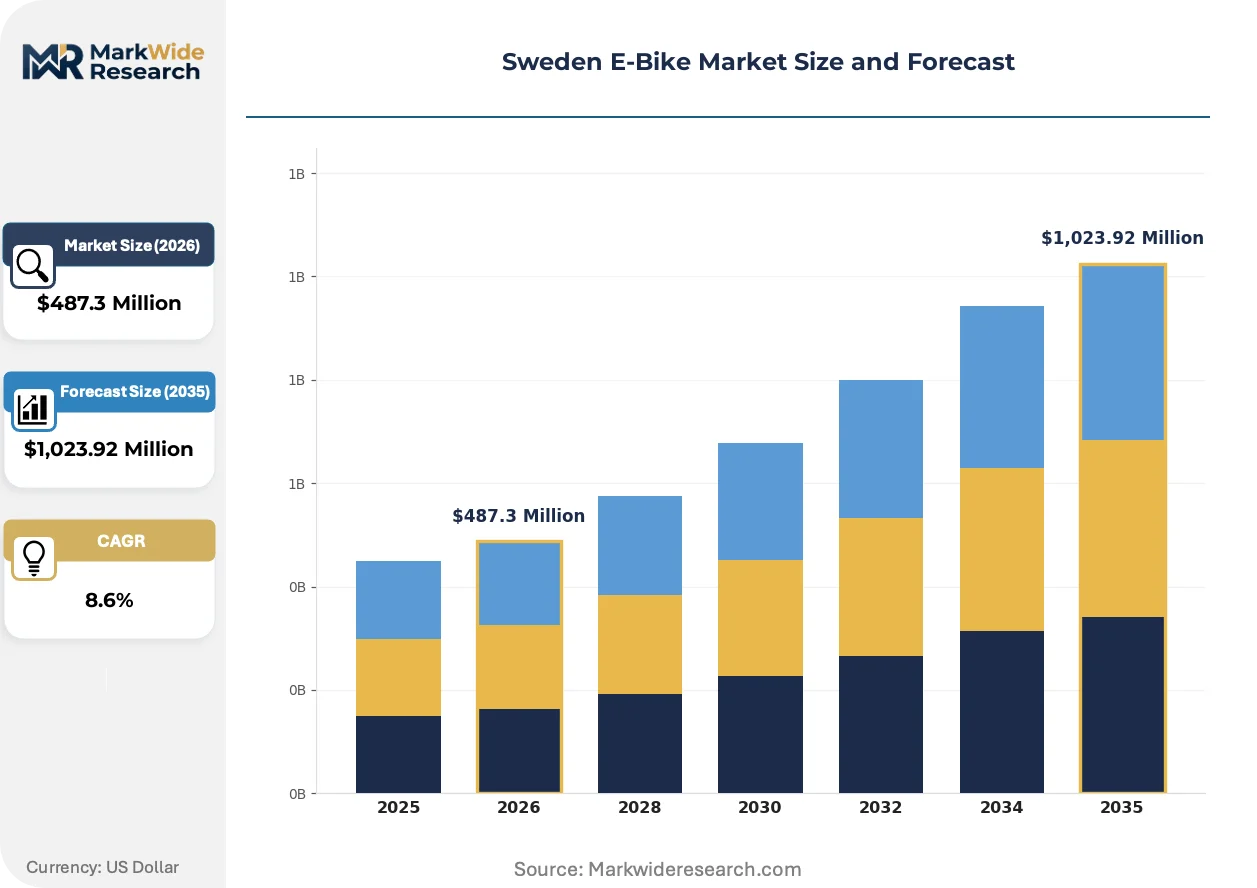
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Purchase Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Usage Purpose: Commuting, Leisure, Delivery, Fitness |
| Companies Covered | Kalkhoff Werke GmbH, VanMoof BV, Ecoride AB, Batavus Intercycle Corporation, Blix Electric Bikes, Trek Sweden AB, Royal Dutch Gazelle, Cycleurope, Giant Manufacturing Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden E-Bike Market Evolving Landscape
Electronics integration and regulatory pressure on battery traceability are compressing product development timelines while fragmenting competitive advantage between hardware engineering and software service layers.
Hub motor systems with integrated regenerative braking are collapsing the cost premium between entry-level and mid-tier urban commuter configurations. Stockholm apartment dwellers now spec folding frames with embedded battery packs previously reserved for premium trekking models. The price-performance boundary between segments is dissolving as Chinese cell suppliers capture mid-motor controller contracts.
Sweden's Transport Agency enforces stricter interpretation of EU type-approval framework 168/2013 for software-modifiable assistance limits, treating over-the-air updates as type-approval events. Manufacturers must resubmit documentation for firmware revisions that alter power curves or speed thresholds. Cargo e-bike fleets with connected diagnostics face the steepest compliance burden as municipalities demand continuous feature updates.
Employer subsidy schemes in dense urban districts are displacing individual retail purchases with bulk fleet procurement managed through mobility-as-a-service platforms. Stockholm county councils now contract integrated bike-share and private fleet operators for employee commuting benefits. Channel control shifts from specialty retailers to municipal procurement frameworks with multi-year service level agreements.
Sweden E-Bike Market Segmentation
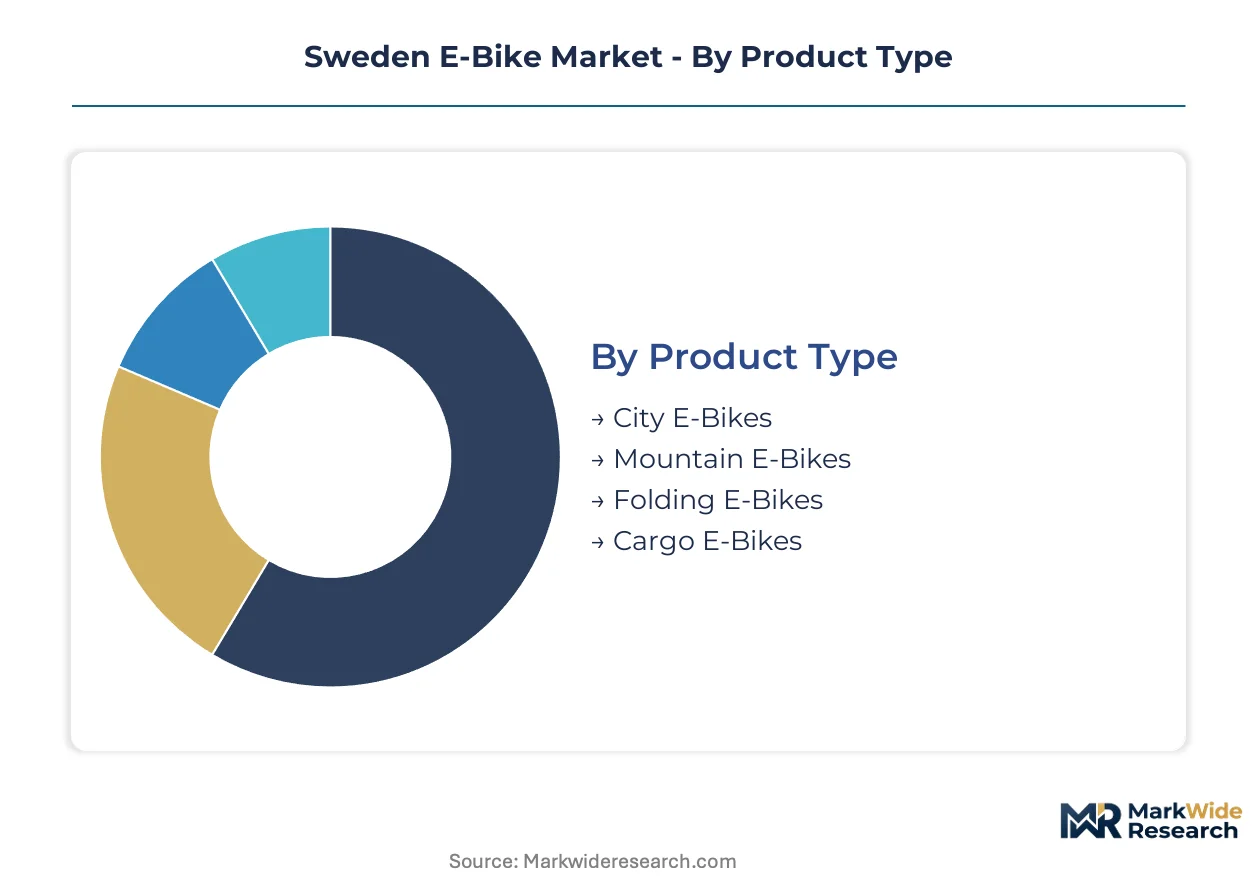
E-bike segmentation in Sweden reveals distinct replacement cycles and margin profiles across product configurations. Municipal fleet procurement and household transport substitution drive divergent demand patterns that reward targeted positioning.
Product Type:
Replacement cycles vary dramatically: urban commuters refresh city models every 3-4 years while cargo configurations operate on 7-10 year fleet amortization schedules.
- City E-Bikes:Step-through frames with integrated lighting and fender systems dominate Stockholm county employer subsidy schemes. Range specifications cluster around 60-80 kilometers to match metropolitan commuting distances.
- Cargo E-Bikes:Extended wheelbase designs with dual-battery architectures displace second household vehicles in Malmö and Gothenburg suburbs. Logistics operators in Scania County standardize front-loader configurations for parcel density.
- Mountain E-Bikes:Full-suspension systems with torque-sensor modulation attract recreational riders in Västra Götaland's trail networks.
- Folding E-Bikes:Compact hinge-frame designs with removable battery packs address storage constraints in Stockholm's dense apartment districts.
City E-Bikes anchors the volume base while Cargo E-Bikes gains share at the steepest rate.
Battery Type:
Cost tiers separate premium energy density from commodity replacement markets, with chemistry choice directly determining range-to-weight ratios and winter performance degradation.
- Lithium-Ion:NMC cell chemistry with 500+ cycle ratings powers mid-motor trekking configurations across Nordic temperature extremes. Cell cost curves from Chinese suppliers compress pack economics for family transport segments.
- Lithium Polymer:Pouch-cell architectures enable custom form factors in folding frame designs where cylindrical constraints limit integration. Energy density advantages command 15-20% price premiums in premium urban commuter channels.
- Nickel-Metal Hydride:Legacy chemistry persists in entry-level hub-motor configurations through established supply contracts with Taiwanese assemblers.
- Lead-Acid:Sealed AGM variants retain niche positioning in fleet refurbishment cycles where capital constraints override weight penalties.
Lithium-Ion captures the dominant revenue share while Lithium Polymer expands most quickly in compact-frame premium tiers.
Purchase Channel:
Channel control is fragmenting between municipal procurement frameworks and direct-to-consumer platforms, with service integration becoming the decisive selection criterion.
- Specialty Stores:Technician-staffed outlets in Gothenburg and Stockholm maintain fleet service contracts with 4-hour response SLAs. Test-ride infrastructure and maintenance bundling defend margin against online price transparency.
- Direct Sales:Integrated electronics brands bypass retail markup through app-locked security systems and over-the-air diagnostic subscriptions. Channel concentration in employer mobility benefit platforms accelerates bulk procurement.
- Online Retail:Pure-play platforms aggregate price comparison for hub-motor entry configurations with standardized battery specifications.
- Supermarkets:Mass-merchandise placement targets impulse replacement of conventional bicycles with basic pedal-assist specifications.
Specialty Stores retain the service-intensive fleet base while Direct Sales climbs the fastest in employer-subsidized commuter segments.
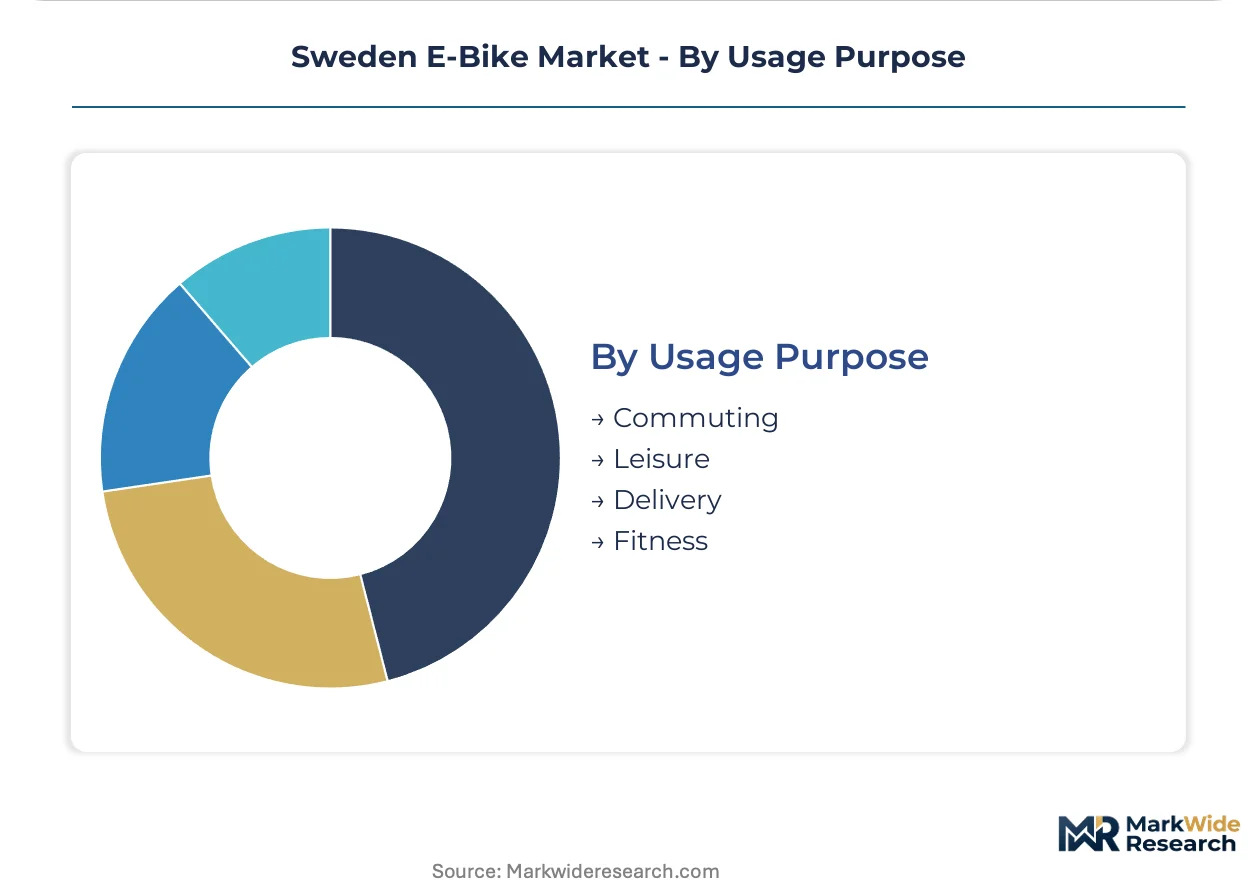
Usage Purpose:
Application maturity separates established commuting infrastructure from emerging logistics substitution patterns across Sweden's metropolitan corridors.
- Commuting:Daily urban transport with integrated pannier systems and weather protection dominates Stockholm county cycling superhighway traffic. Employer subsidy schemes and bike-lane network expansion sustain replacement demand.
- Delivery:Last-mile logistics operators in Scania and Västra Götaland counties deploy front-loader cargo configurations for grocery and parcel routes under 15 kilometers. Fleet electrification mandates from postal operators standardize procurement specifications.
- Leisure:Recreational weekend usage in lake district trail networks drives full-suspension mountain e-bike specifications with extended range reserves.
- Fitness:Training-oriented riders with power-meter integration represent a niche segment with high accessory attachment rates.
Commuting anchors the volume base while Delivery gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Swedish Transport Agency anchors Nordic regulatory alignment through EU type-approval enforcement, while sub-regional cycling infrastructure investments concentrate procurement demand across three metropolitan corridors.
Stockholm County
Employer mobility subsidy schemes and cycling superhighway construction drive fleet procurement volumes. The National Board of Housing mandates residential parking minimums that shape charging access in new developments. Municipal procurement frameworks in Solna and Södermalm prioritize service-ready cargo configurations with 4-hour response SLAs.
Västra Götaland County
Gothenburg's port logistics electrification and family transport substitution patterns accelerate front-loader cargo adoption. The Swedish Environmental Protection Agency channels EU Green Deal grants toward lane expansion in Mölndal and Partille. Specialty retailers maintain technician networks defending against direct-to-consumer platform encroachment.
Scania County
Last-mile delivery operators standardize electric-assisted fleets for urban routes under 15 kilometers. Postal electrification mandates from national operators compress replacement cycles for conventional delivery vehicles. Logistics clusters in Malmö and Lund deploy dual-battery architectures for parcel density optimization.
Norrland Counties
Cold-weather range contraction limits year-round commuter reliance on pedal-assist systems. Winter performance degradation shapes battery chemistry selection toward NMC cell architectures with temperature resilience. Umeå and Luleå municipal contracts emphasize service network density for rural technician deployment.
Sweden E-Bike Market Competitive Landscape
Capability concentration sits with integrated electronics specialists; scale advantage sits with assembly plants capturing mid-motor controller contracts. The vendor base separates between premium trekking configurations with German engineering heritage and direct-to-consumer platforms controlling channel margins through app-locked security systems. Two strategic archetypes dominate: domestic assemblers with municipal procurement relationships, and integrated brands bypassing retail markup through subscription-managed mobility packages. Competitive moves center on backward integration into battery pack assembly and geographic expansion through employer mobility benefit platforms.
Within the domestic assembly tier, Ecoride AB anchors Swedish production capacity outside Jönköping, supplying municipal frameworks with fleet-ready models. Kalkhoff Werke GmbH and VanMoof BV exemplify divergent channel strategies—the former leveraging engineering heritage for premium trekking positioning, the latter sustaining direct-to-consumer control through integrated electronics and security subscriptions.
| Leading Market Players |
|---|
| Kalkhoff Werke GmbH |
| VanMoof BV |
| Ecoride AB |
| Batavus Intercycle Corporation |
| Blix Electric Bikes |
| Trek Sweden AB |
| Royal Dutch Gazelle |
| Cycleurope |
| Giant Manufacturing Co. Ltd |
| Others |
Value Network & Pricing Analysis
Overcapacity at Taiwanese mid-motor assembly plants is compressing contract manufacturing margins while forcing European brand procurement teams toward multi-source qualification. This utilization squeeze transmits downward through battery pack integrators and frame fabricators, reshaping how Swedish fleet operators negotiate service-inclusive pricing.
Pricing Analysis
Stockholm county employer subsidy schemes command 12-18% premiums over Scania County logistics procurement for equivalent cargo configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated electronics brands from hub-motor commodity suppliers and refurbished fleet tiers. Cost compression in entry-level urban commuter segments intensifies as Chinese cell suppliers capture controller contracts. Municipal procurement frameworks exhibit lowest price sensitivity due to multi-year service level requirements, while individual retail buyers in dense apartment districts drive hardest bargain on folding frame specifications.
Supply Chain Analysis
Taiwanese contract manufacturers including Bafang and TDC dominate mid-motor system assembly for European brand motor systems. Chinese cell suppliers and South Korean cathode material providers anchor lithium-ion energy density improvements, while Vietnamese frame fabricators feed hub-motor commodity tiers. Single-source vulnerability concentrates around Taiwanese motor controller firmware where retesting requirements for EU type-approval revisions create certification bottlenecks. Distribution runs through municipal procurement frameworks with integrated service contracts, bypassing traditional specialty retail markup in Stockholm and Gothenburg metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's e-bike market operates as a substitution defense against second vehicle ownership and combustion-engine delivery fleets, with incumbents navigating pressure from shared micromobility platforms and employer-funded car subscriptions.
For Market Incumbents: Entrench municipal procurement relationships through captive service networks with 4-hour response commitments in Västra Götaland and Scania counties. Backward integration into battery pack assembly mitigates EU battery passport compliance overhead while defending margin against direct-to-consumer platform encroachment. For New Entrants and Emerging Players: Pursue Gothenburg employer mobility subsidy schemes that remain underpenetrated by fleet service providers with maintenance networks. Target front-loader cargo configurations for grocery logistics operators in Malmö and Lund where electrification mandates compress replacement cycles. Lead with subscription-managed diagnostics and over-the-air update capabilities to differentiate from established hardware-centric competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated electronics brands with app-locked security subscriptions and diagnostic service tiers. Long-term viability across the analysis window favors domestic assemblers with municipal framework relationships and captive battery integration capabilities. Monitor Swedish Environmental Protection Agency carbon budget allocation announcements as inflection signal for dedicated procurement pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captures EU battery passport margin and insulates against cell cost volatility from Chinese suppliers. |
| Municipal Fleet Service Contract Expansion | Locks in 4-hour response SLA revenue streams across Stockholm and Gothenburg metropolitan corridors. |
| Integrated Electronics Platform Launch | Enables subscription diagnostics and over-the-air firmware updates under EU type-approval framework 168/2013. |
| Cargo Configuration Capacity Addition | Addresses front-loader demand from Scania County logistics operators replacing conventional delivery vehicles. |
| Employer Mobility Benefit Platform Partnership | Captures bulk procurement volume shifting from individual retail to subsidy-managed commuter schemes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU transport agency filings, Swedish municipal procurement databases, and lithium-ion trade flow records. Conversations with fleet procurement managers at postal operators, specialty retailer service directors, and mid-motor system engineers informed demand segmentation and replacement cycle assumptions. Bottom-up unit economics from battery pack cost curves and top-down infrastructure grant allocations were cross-validated for volume reconciliation.
Forecast inputs span product type, battery chemistry, purchase channel, and usage purpose dimensions across the projection horizon. CAGRs derive from segment-level replacement cycle analysis and infrastructure investment correlation with fleet procurement timing. Modeled variables include EU Green Deal cycling superhighway completion schedules, employer subsidy scheme enrollment trajectories, and cold-weather performance degradation coefficients for Norrland county adoption ceilings.
Sensitivities concentrate around EU battery passport implementation timelines and Swedish Transport Agency interpretation of software-updatable motor controller type-approval requirements. Forecasts reflect documented assumptions on lithium-ion cell cost curve trajectories and municipal procurement framework award patterns. Quarterly review of carbon budget allocation announcements and mid-motor contract manufacturing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Smart Electric Bikes Market