
 Carbon Fiber Bicycle Market | 2026-2036
Carbon Fiber Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Bicycle Market Insights
Multi-source carbon fiber procurement from Japanese and Taiwanese prepreg suppliers is hardening as a standard practice among premium frame builders. Trek Bicycle Corporation leverages in-house OCLV carbon layup expertise to sustain margin control over its domestic assembly network. Giant Manufacturing Co. anchors volume production through vertically integrated composite facilities in Taichung, while Specialized Bicycle Components competes via rider-data feedback loops that inform layup schedules.
A carbon fiber bicycle comprises a frame, fork, and components fabricated from polyacrylonitrile-derived carbon fiber reinforced polymer, typically using T700 or T800 modulus fiber with thermoset epoxy resin cured under pressure in bladder-molded monocoque structures to achieve strength-to-weight ratios exceeding 150 kN·m/kg for competitive cycling applications. Road bikes dominate value pools due to professional team sponsorship economics, yet electric bikes represent the fastest-expanding product type as motor-assisted commuters accept carbon frame premiums for reduced total vehicle weight. Professional cyclists command the highest per-unit spending among end user segments, while specialty stores retain disproportionate influence over high-consideration purchases through fit services and test-ride programs.
FDA oversight applies to cycling equipment sold with biometric monitoring integrations, while EPA guidelines govern volatile organic compound emissions from composite curing operations in domestic manufacturing. ISO 4210 and CEN standards define frame fatigue and impact resistance thresholds that determine market access across European and North American retail channels. Stakeholders must monitor evolving e-bike motor integration standards and recycled carbon fiber certification protocols as these frameworks reshape material qualification timelines and supplier qualification costs.
Market Dynamics
The EU F-Gas Regulation and REACH compliance are forcing frame builders to abandon solvent-heavy prepreg curing and adopt recycled carbon fiber feedstocks, reshaping supplier qualification timelines and resin system selection across premium road and mountain bike production.
Growth Catalysts
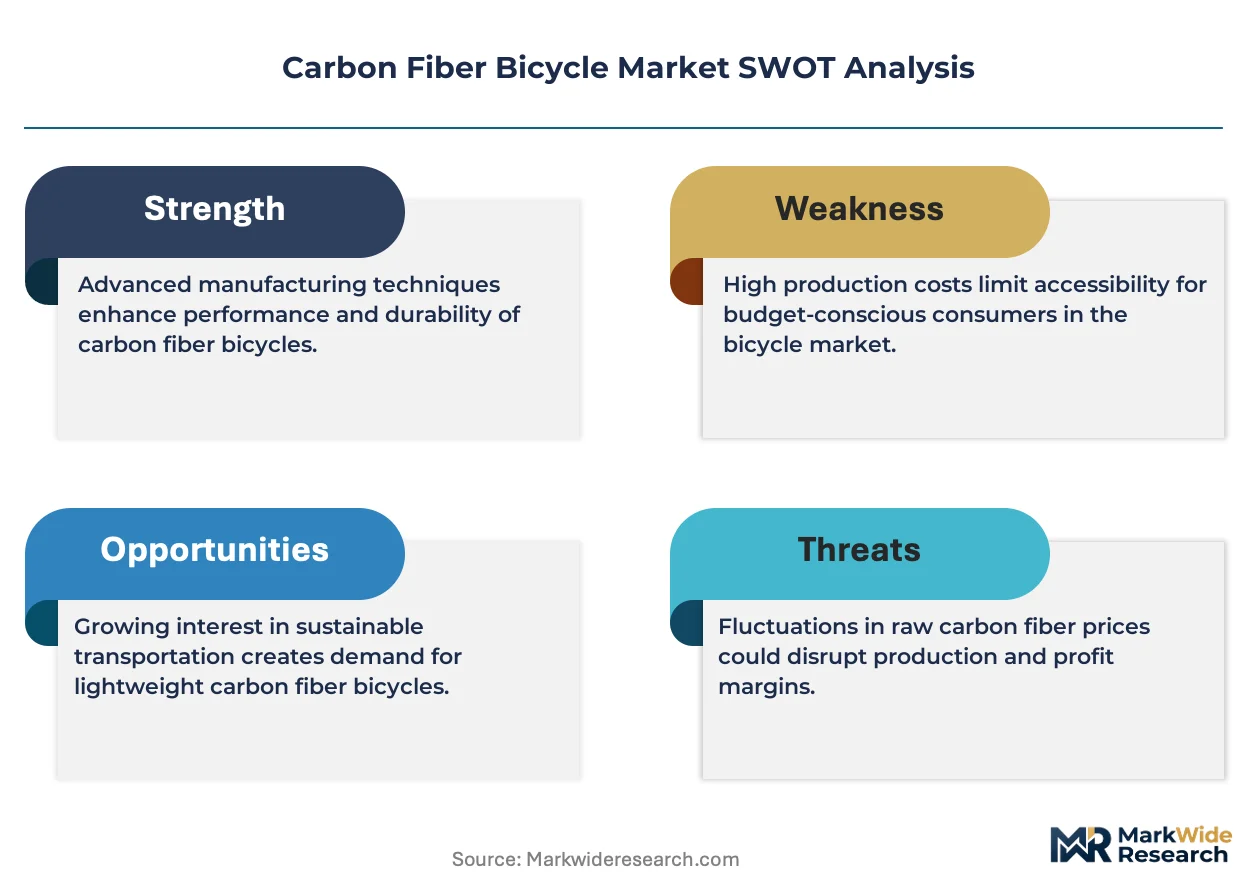
- Professional cycling sponsorship economics:Elite racing teams demand sub-800-gram frames to secure competitive advantage, pulling T800 modulus fiber through team supply contracts.
- REACH cleaner resin mandates:European compliance requirements accelerate water-based epoxy adoption and closed-mold infusion techniques that reduce volatile organic compound emissions.
- E-bike motor integration:Motor-assisted commuters accept carbon frame premiums for reduced total vehicle weight, expanding addressable demand beyond traditional performance cyclists.
Market Restraints
- Japanese prepreg supply concentration:Toray and Mitsubishi Chemical control high-modulus fiber qualification pathways, creating single-source vulnerability for T800-grade frame production.
- Bladder-molded monocoque capex intensity:Autoclave and mandrel equipment for competitive-grade frames requires seven-figure facility investments that freeze out mid-tier assemblers.
- Thermoset epoxy technical limitation:Non-recyclable cured resin structures face end-of-life disposal constraints under evolving extended producer responsibility frameworks.
Strategic Opportunities
- India cycling infrastructure expansion:Metro rail integration and dedicated lane construction in Bangalore and Mumbai create first-mile/last-mile demand for lightweight commuter frames.
- Recycled carbon fiber certification:Emerging ISO-aligned protocols for reclaimed aerospace fiber repurposing open feedstock arbitrage against virgin PAN precursor costs.
- Direct-to-consumer fit technology:AI-driven body geometry capture and remote consultation platforms disintermediate specialty retail for standardized frame sizing.
Industry Challenges
- Layup technician skill scarcity:Hand-aligned fiber orientation expertise for competitive-grade frames concentrates in Taichung and northern Italy, constraining production scaling.
- ISO 4210 fatigue certification timelines:Frame impact and cyclic load testing protocols require 12-18 month validation cycles that delay new model launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Bicycle Market |
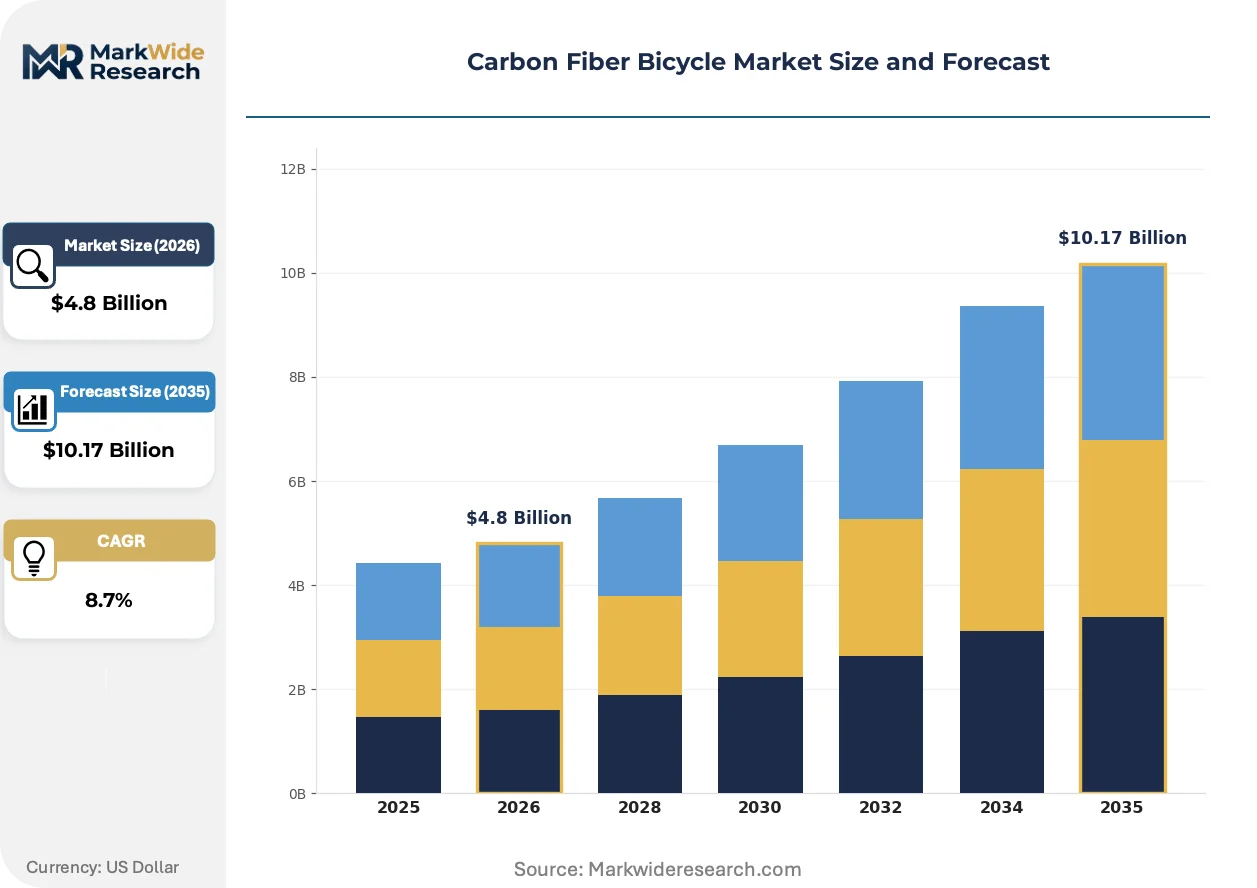
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Road Bikes, Mountain Bikes, Hybrid Bikes, Electric Bikes End User: Professional Cyclists, Recreational Riders, Fitness Enthusiasts, Commuters Distribution Channel: Online Retail, Specialty Stores, Chain Stores, Direct Sales Frame Design: Full Suspension, Hardtail, Aero, Standard |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co., Specialized Bicycle Components, Merida Industry Co., Ltd., Cannondale Bicycle Corporation, Scott Sports SA, Colnago Ernesto & C. S.r.l., Pinarello SRL, Canyon Bicycles GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Bicycle Market Trends and Innovations
Active matrix integration and thermoplastic resin systems are compressing traditional manufacturing timelines while regulatory pressure on composite waste streams accelerates material recovery investments across the value chain.
Recycled aerospace-grade carbon fiber is expanding into mid-tier road bike frames as reclaimed T700 fiber from decommissioned aircraft structures meets strength-to-weight thresholds at 40% below virgin feedstock cost. German and Italian frame builders are qualifying this material fastest, securing margin relief against Japanese prepreg pricing power. The technology is expanding into previously cost-prohibited entry-level performance segments where weight sensitivity still governs purchase decisions.
EU F-Gas Regulation phase-down schedules are mandating hydrofluorocarbon elimination from composite curing auxiliary systems, forcing manufacturers to retrofit thermal management equipment or relocate curing operations to jurisdictions with less stringent fluorinated gas controls. Frame fabrication clusters in Germany face the steepest compliance costs. Premium assemblers are responding by consolidating curing capacity in vertically integrated facilities where emission capture investments amortize across higher throughput.
Specialty retail channel influence is fragmenting as rider-data feedback loops from connected training platforms inform direct manufacturer layup schedules, bypassing traditional fit-service intermediaries. Zwift and TrainerRoad usage patterns now shape frame geometry decisions at Specialized and Canyon. This disintermediation is most visible in North American and Australian markets where digital-native cyclists dominate premium purchase cohorts and test-ride dependency has weakened.
Carbon Fiber Bicycle Market Segmentation
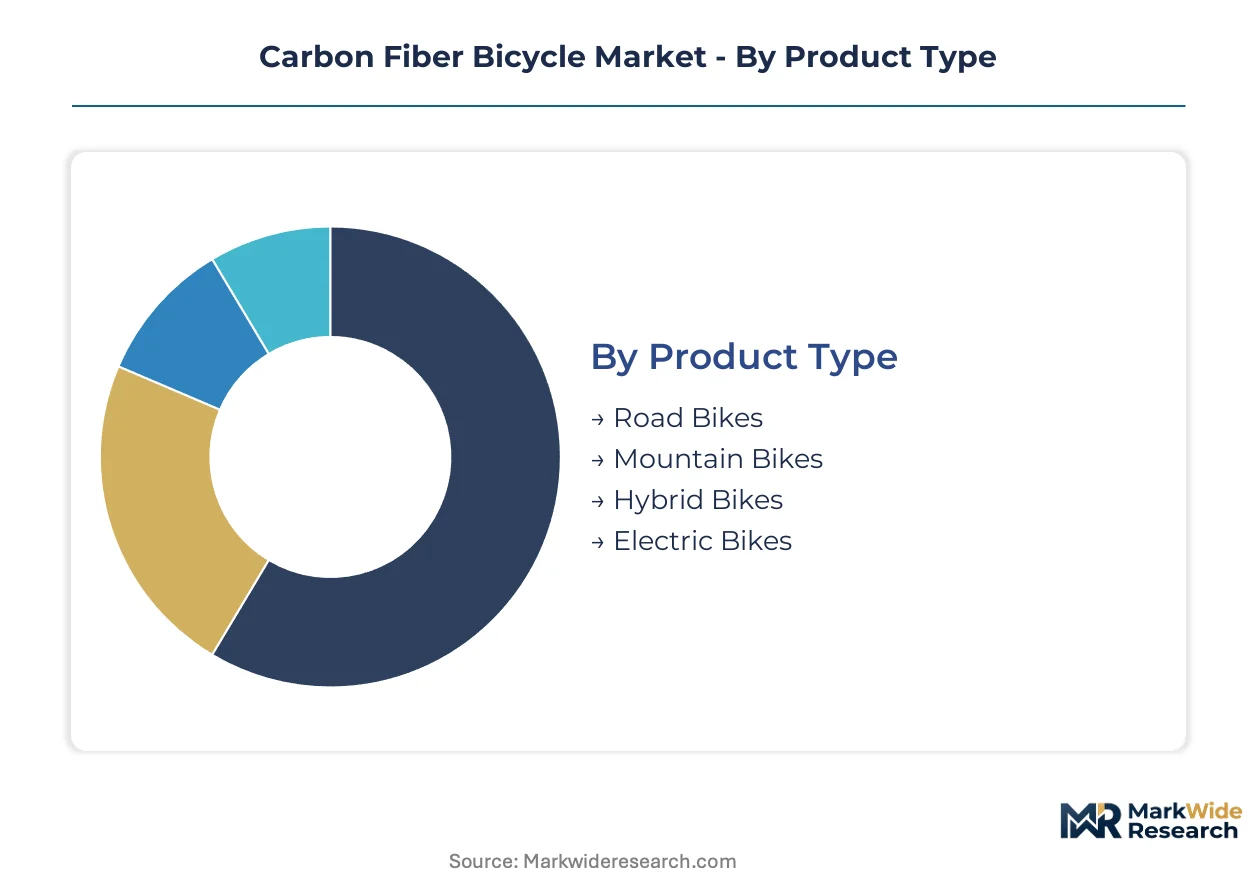
Carbon fiber bicycle segmentation reveals divergent certification burdens across product tiers. Professional-grade frames face ISO 4210 fatigue testing cycles lasting 12-18 months, while commuter-oriented models navigate lighter compliance loads in major retail channels.
Product Type:
Road bike frames require CEN impact resistance certification for European market access, while electric bike motor integration triggers additional FCC electromagnetic compliance in the US and CE marking for EU distribution.
- Road Bikes:T800 modulus monocoque frames dominate professional team sponsorship contracts. Germany and Italy concentrate fabrication demand where sub-800-gram weight thresholds determine competitive viability against sponsorship economics.
- Electric Bikes:Motor-assisted carbon frames reduce total vehicle weight for commuter acceptance. Bangalore and Mumbai infrastructure expansion drives fastest segment expansion as metro rail integration creates first-mile demand.
- Mountain Bikes:Full-suspension carbon rear triangles face amplified impact load certification under ISO 4210.
- Hybrid Bikes:Moderate modulus T700 construction balances cost against weight for recreational positioning.
Road bikes sit at the top of the volume ranking, with electric bikes climbing the fastest.
End User:
Professional cyclists command per-unit spending multiples above recreational segments, with frame procurement running through team supply contracts rather than retail channels. Fitness enthusiasts and commuters occupy divergent price elasticity positions.
- Professional Cyclists:Elite racing teams mandate hand-aligned fiber orientation from Taichung and northern Italy technician pools. Sponsorship economics pull T800 modulus fiber through exclusive supply agreements that freeze out mid-tier assemblers.
- Commuters:Motor-assisted carbon frame acceptance expands addressable demand beyond traditional performance cyclists. Dedicated lane construction in Indian metro corridors accelerates lightweight commuter frame adoption.
- Recreational Riders:Standardized geometry from AI-driven fit platforms reduces specialty store dependency.
- Fitness Enthusiasts:Zwift and TrainerRoad usage patterns now inform manufacturer layup schedules directly.
Professional cyclists anchor premium revenue concentration, with commuters expanding most quickly as e-bike motor integration matures.
Distribution Channel:
Channel selection determines margin capture versus customer acquisition cost tradeoffs. Specialty stores retain fit-service premiums for high-consideration purchases, while direct models compress intermediaries.
- Specialty Stores:Test-ride programs and body geometry consultation sustain pricing power for premium road and mountain bike segments. North American and Australian digital-native cyclist cohorts weaken this channel's historical dominance.
- Direct Sales:Canyon and Specialized bypass retail intermediaries through rider-data feedback loops from connected training platforms. Remote consultation platforms disintermediate traditional fit services for standardized frame sizing.
- Online Retail:Aggregator platforms concentrate price transparency for entry-level performance segments.
- Chain Stores:Volume throughput amortizes inventory carrying costs across standardized hybrid and commuter models.
Specialty stores maintain revenue per unit leadership, with direct sales gaining share fastest through digital-native purchase cohorts.
Frame Design:
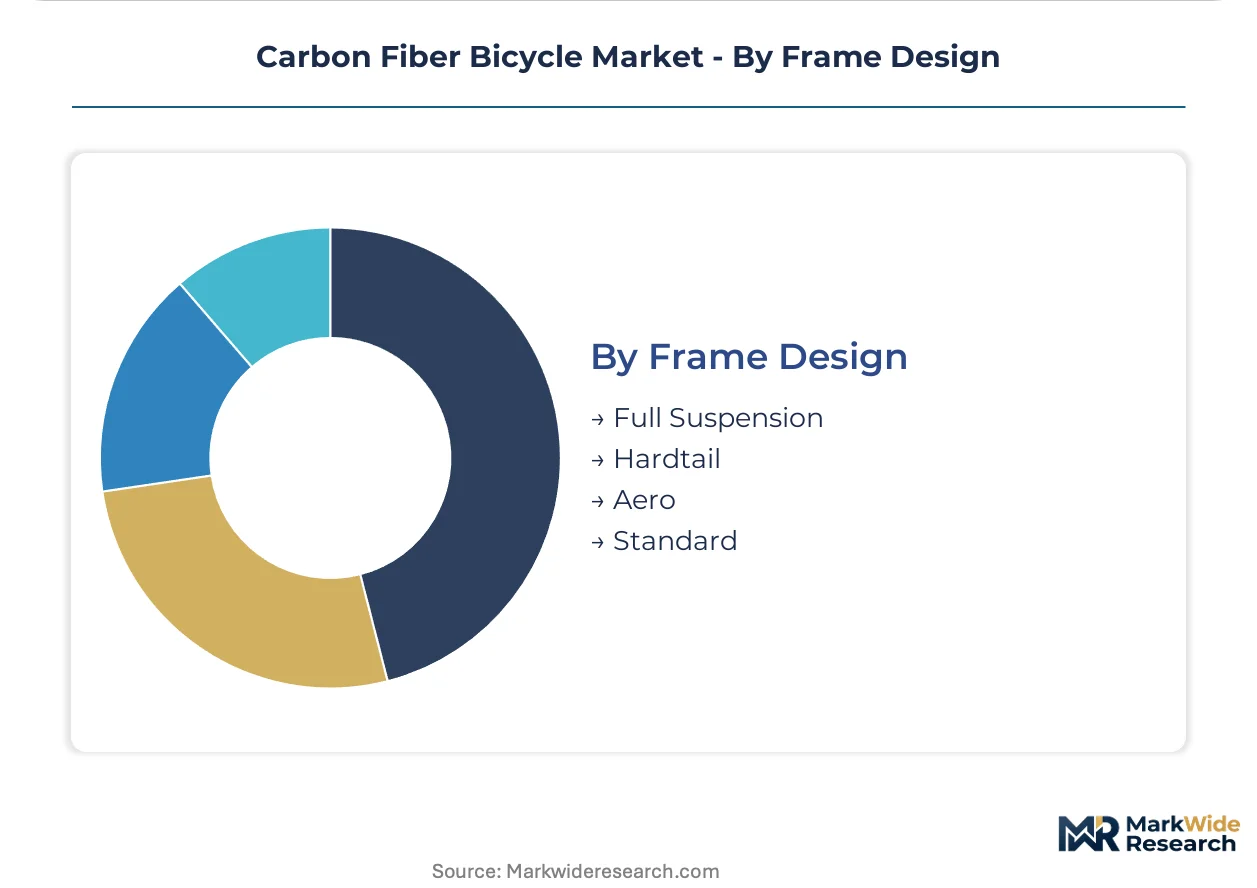
Structural configuration dictates bladder-molded monocoque capex requirements and resin system selection under REACH compliance. Aero and full-suspension designs concentrate in premium fabrication clusters.
- Aero:Wind-tunnel-validated tube profiles require seven-figure autoclave investments that concentrate production in vertically integrated Taichung facilities. German frame builders face steepest EU F-Gas Regulation retrofit costs for thermal management equipment.
- Full Suspension:Carbon rear triangle pivot integration demands enhanced fatigue certification timelines. Recycled aerospace-grade T700 fiber qualification expands into this segment at 40% below virgin feedstock cost.
- Hardtail:Simplified rear triangle construction reduces layup technician skill requirements.
- Standard:Conventional geometry serves price-sensitive recreational positioning with moderate modulus construction.
Aero frames command premium positioning, with full suspension designs steepest expansion trajectory as recycled fiber qualification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taichung anchors global carbon fiber bicycle frame fabrication, with vertically integrated composite facilities serving premium road and mountain bike demand across export markets. Frame production clusters in northern Italy and southern Germany concentrate hand-aligned fiber orientation expertise for professional team supply contracts. Regulatory pressure from EU F-Gas and REACH compliance is reshaping curing operation geography.
United States
Domestic assembly networks concentrate in Wisconsin and California, serving North American specialty retail channels with sub-800-gram road frames. EPA volatile organic compound guidelines govern composite curing emissions from bladder-molded monocoque production. Trek Bicycle Corporation leverages in-house OCLV carbon layup expertise from its Waterloo, Wisconsin headquarters to sustain margin control.
Germany
Professional team sponsorship economics pull T800 modulus fiber through exclusive supply agreements with Stuttgart and Munich-based racing organizations. EU F-Gas Regulation phase-down schedules mandate hydrofluorocarbon elimination from thermal management equipment, forcing retrofit investments or curing capacity consolidation. Frame builders in Baden-Württemberg face steepest compliance costs among European fabrication clusters.
Italy
Elite racing heritage concentrates demand for hand-finished aero frames around Treviso and Milan manufacturing districts. REACH cleaner resin mandates accelerate water-based epoxy adoption across Veneto and Lombardy production facilities. Colnago Ernesto & C. S.r.l. and Pinarello SRL exemplify the artisan-tier positioning that dominates premium road bike value pools.
Japan
Toray and Mitsubishi Chemical control high-modulus T700 and T800 fiber qualification pathways from Tokyo and Nagoya headquarters. METI industrial standards govern prepreg export specifications for frame builders in Taiwan and Europe. Japanese prepreg supply concentration creates single-source vulnerability for competitive-grade carbon bicycle production globally.
India
Metro rail integration and dedicated lane construction in Bangalore and Mumbai create first-mile/last-mile demand for lightweight commuter frames. BIS certification requirements for electric bicycle motor integration trigger additional compliance timelines for carbon frame assemblers. Domestic production capacity remains limited, with premium imports dominating Bangalore and Delhi-NCR specialty retail channels.
Carbon Fiber Bicycle Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue recycled fiber qualification and direct-to-consumer fit technology. The vendor base stratifies across three tiers: vertically integrated volume manufacturers, specialist artisan builders, and digitally native direct-sales operators. Consolidation pressure concentrates among premium road frame specialists facing ISO 4210 fatigue certification timeline constraints. Dominant competitive moves include backward integration into prepreg supply relationships and geographic consolidation of curing capacity to amortize emission capture investments.
Among North American and European fabricators, Trek Bicycle Corporation, Specialized Bicycle Components, and Canyon Bicycles GmbH exemplify divergent strategic archetypes. Trek represents the vertically integrated domestic assembler model with captive layup expertise. Specialized occupies the data-driven product development position, leveraging rider feedback loops from connected training platforms. Canyon anchors the direct-to-consumer vector, disintermediating specialty retail through remote consultation platforms for standardized frame sizing.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. |
| Specialized Bicycle Components |
| Merida Industry Co., Ltd. |
| Cannondale Bicycle Corporation |
| Scott Sports SA |
| Colnago Ernesto & C. S.r.l. |
| Pinarello SRL |
| Canyon Bicycles GmbH |
| Others |
Pricing and Supply Chain Analysis
Water-based epoxy adoption under REACH cleaner resin mandates simultaneously compresses curing cost economics and consolidates production capacity among vertically integrated Taichung facilities capable of amortizing emission capture investments across higher throughput. This technical transition rewards frame builders with captive prepreg supply relationships while marginalizing mid-tier assemblers dependent on outsourced curing operations.
Pricing Analysis
Japanese T700 and T800 prepreg pricing power passes through directly to frame cost structures, with three-tier pricing separating professional-grade T800 monocoques from standard T700 recreational frames and entry-level hybrid constructions. Price differentiation hinges on ISO 4210 fatigue certification grade and hand-aligned fiber orientation labor intensity. Cost compression in mid-tier road segments is intensifying because recycled aerospace-grade fiber qualification at 40% below virgin feedstock cost expands supply alternatives. Commuter e-bike buyers exhibit highest price sensitivity, while professional racing teams show near-zero elasticity given sponsorship economics.
Supply Chain Analysis
Dual-sourcing requirements from premium frame builders now mandate simultaneous qualification of Toray and Mitsubishi Chemical prepreg specifications to mitigate single-source vulnerability in T800-grade fiber supply. Raw material dependencies center on polyacrylonitrile precursor, thermoset epoxy resin systems, and bladder-molded monocoque tooling. Supply chain risk concentrates in Japanese high-modulus fiber qualification pathways. Distribution runs through vertically integrated assembly networks in Taichung, specialty retail fit-service channels in Germany and Italy, and direct-to-consumer remote consultation platforms displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where professional team sponsorship economics pull sub-800-gram frame specifications through exclusive supply agreements, elevating technical performance thresholds beyond commodity competition.
For Market Incumbents: Hedge against recycled carbon fiber feedstock arbitrage by qualifying reclaimed aerospace T700 fiber ahead of ISO-aligned certification protocol finalization. Secure backward integration into water-based epoxy resin supply to preempt REACH compliance cost pass-through from chemical suppliers. Consolidate curing capacity in Taichung or northern Italy fabrication clusters to amortize EU F-Gas Regulation thermal management retrofit investments across higher throughput volumes. For New Entrants and Emerging Players: Begin with direct-to-consumer AI-driven body geometry capture platforms targeting North American and Australian digital-native cyclist cohorts where test-ride dependency has weakened. Penetrate Indian metro rail first-mile/last-mile commuter demand in Bangalore and Mumbai where dedicated lane construction accelerates lightweight frame adoption. Pursue recycled fiber qualification partnerships with German and Italian artisan builders seeking margin relief against Japanese prepreg pricing power. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier road frame specialists facing ISO 4210 fatigue certification timeline constraints that delay new model launches and compress working capital efficiency. Long-term viability favors vertically integrated assemblers with captive layup expertise and established professional team supply contracts. Watch for inflection where e-bike motor integration standards mature sufficiently to open carbon frame premiums to mass-market commuter acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Carbon Fiber Qualification | Reclaimed aerospace T700 fiber repurposing opens 40% feedstock cost arbitrage against virgin PAN precursor pricing. |
| Water-Based Epoxy Resin Transition | REACH cleaner resin mandates accelerate closed-mold infusion adoption that reduces volatile organic compound emissions from curing operations. |
| Direct-to-Consumer Fit Technology | AI-driven body geometry capture platforms disintermediate specialty retail for standardized frame sizing in digital-native purchase cohorts. |
| Professional Team Supply Contract Consolidation | Exclusive T800 modulus fiber procurement agreements freeze out mid-tier assemblers from premium sponsorship economics. |
| Vertical Curing Capacity Consolidation | Taichung and northern Italy fabrication clusters amortize EU F-Gas Regulation thermal management retrofit costs across higher throughput. |
Research Methodology
Multiple input streams — primary interviews with frame fabrication engineers, procurement leads at premium bicycle assemblers, specialty retail fit-service operators, and composite materials R&D directors, alongside secondary validation through customs/trade data, ISO certification registries, SEC filings from publicly traded manufacturers, and EU regulatory compliance disclosures — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured layup technician skill scarcity constraints, prepreg supply concentration dynamics, and REACH implementation timelines across German and Italian production facilities. Secondary sources documented Toray and Mitsubishi Chemical fiber qualification pathways, recycled aerospace fiber repurposing protocols, and e-bike motor integration standard evolution.
Data-stream reconciliation anchored volume and value outputs across product type, frame design, end user segment, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory modeling incorporating professional team sponsorship contract velocity, commuter e-bike motor integration acceptance curves, and recycled fiber certification protocol adoption rates. Industry-specific forecast inputs included bladder-molded monocoque production capacity utilization patterns and ISO 4210 fatigue certification pipeline backlogs.
Caveats apply where Japanese prepreg supply disruption, EU F-Gas Regulation enforcement variance, or extended producer responsibility framework implementation could materially shift the outlook. Deviation in professional cycling sponsorship economics or e-bike motor integration standard harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Motorcycle Filter Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Cargo Bike Market