
 Electric Cargo Bikes Market | 2026-2036
Electric Cargo Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Cargo Bikes Market Intelligence
EN 15194 certification is redrawing competitive boundaries by mandating electromagnetic compatibility and mechanical integrity thresholds that smaller assemblers cannot meet. Riese & Müller leverages German engineering heritage to dominate premium long-john configurations with in-house frame production. Rad Power Bikes competes on direct-to-consumer pricing while sustaining volume through simplified hub-motor architectures. Urban Arrow anchors the Dutch commercial segment with specialized front-loader designs optimized for postal and courier contracts.
Electric cargo bikes are pedal-assisted commercial vehicles with reinforced frames, extended wheelbases, and integrated cargo platforms rated for loads between 100 and 250 kilograms, powered by lithium-ion battery packs and electric motors to replace internal-combustion urban freight. Front-loader configurations lead European municipal procurement due to superior maneuverability in narrow historic centers, while mid-drive motor technology captures the fastest growth in hilly North American cities where torque sensing improves loaded hill performance. Three-wheel variants occupy stable niche positions among independent couriers prioritizing balance over speed on uneven surfaces.
FDA and EPA frameworks in the United States govern battery transport classification and charger efficiency standards, while the EU Green Deal and F-Gas Regulation shape European procurement by embedding lifecycle carbon metrics into municipal fleet tenders. The EU AI Act and emerging smart-bike connectivity protocols will soon govern telematics data handling across connected fleet management systems. Stakeholders must monitor how battery passport requirements and right-to-repair legislation reshape total cost of ownership calculations against leasing models.
Market Dynamics
Mid-drive motor systems are compressing hub-motor margins across premium configurations as torque-sensitive fleet buyers prioritize loaded hill performance over acquisition cost.
Growth Catalysts
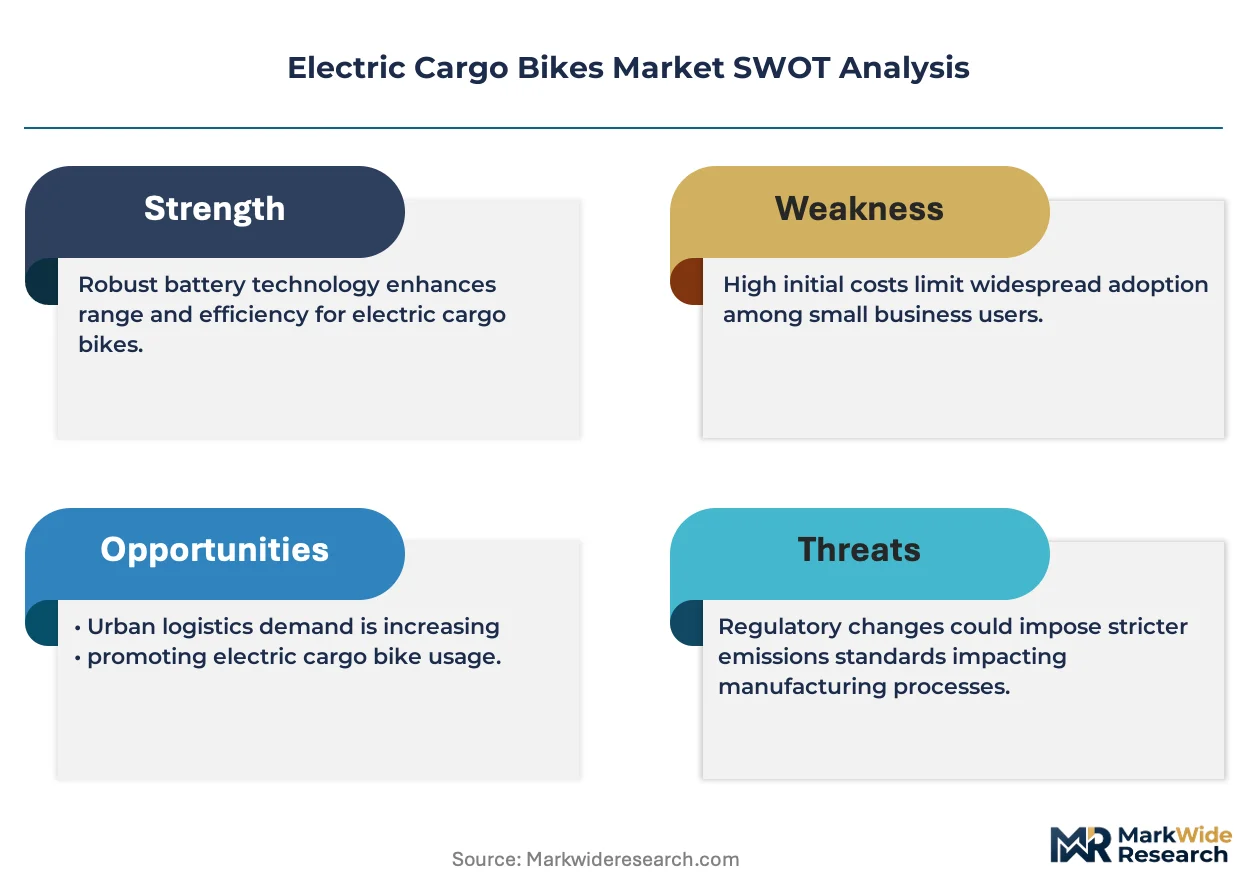
- Urban Low-Emission Zones:Municipal mandates in Amsterdam, Berlin, and Copenhagen are forcing last-mile operators to retire diesel vans ahead of schedule, creating immediate replacement demand for certified cargo platforms.
- Battery Passport Requirements:The EU Green Deal is embedding lifecycle carbon accounting into municipal fleet tenders, advantaging manufacturers with transparent supply chains and verified cell provenance.
- Front-Loader Geometry:Dutch postal contracts are normalizing front-loading cargo configurations that maneuver through historic city cores where conventional delivery vehicles face access restrictions.
Market Restraints
- Lithium-Ion Cell Volatility:Cathode material costs fluctuate with nickel and cobalt spot markets, compressing assembler margins on fixed-price municipal contracts.
- EN 15194 Certification Barriers:Electromagnetic compatibility and mechanical integrity testing requirements exclude smaller frame builders from premium commercial procurement channels.
- Three-Wheel Stability Trade-offs:Independent courier preference for balance over speed limits addressable market expansion in time-sensitive express segments.
Strategic Opportunities
- North American Hill Cities:Mid-drive torque sensing is penetrating hilly urban corridors like San Francisco and Pittsburgh where loaded gradient performance determines fleet selection.
- Connected Fleet Telematics:The EU AI Act is creating compliant data-handling requirements that favor early movers in battery-state monitoring and predictive maintenance platforms.
- Right-to-Repair Legislation:Modular component architectures are opening leasing-model economics by reducing total cost of ownership through field-serviceable drivetrains.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of torque sensors, motor controllers, and CAN-bus diagnostics requires skill sets concentrated in automotive and e-mobility sectors.
- CSRD Reporting Timelines:Corporate sustainability disclosure requirements are forcing mid-cap assemblers to build carbon accounting infrastructure without dedicated compliance functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Cargo Bikes Market |
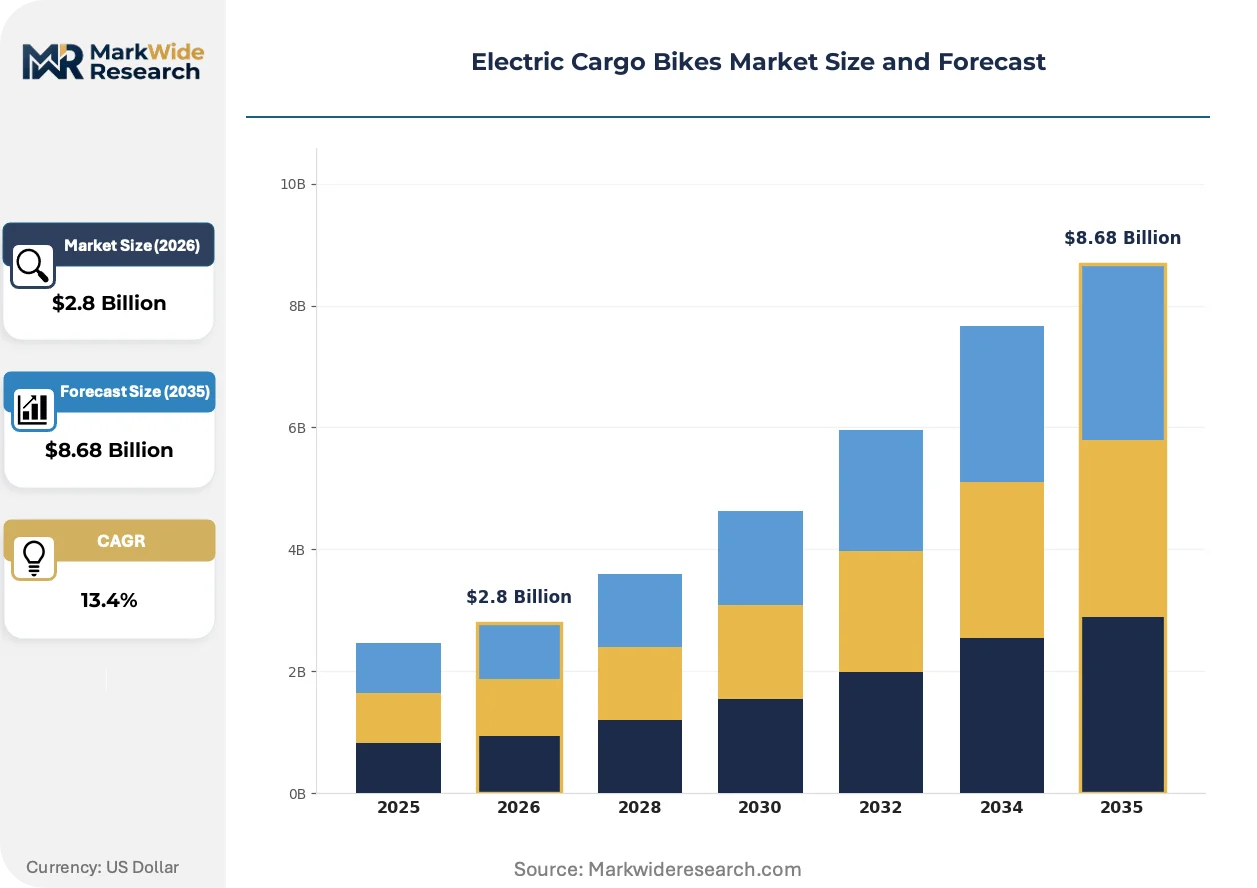
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.68 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Loader, Long John, Flatbed, Three-Wheel, Side Loader Technology: Hub Motor, Mid-Drive Motor, Geared Hub Motor, Friction Drive Application: Last Mile Delivery, Food & Beverage Transport, Courier Services, Municipal Services, Package Distribution End User: Small Businesses, Logistics Companies, Postal Services, Urban Retailers, Independent Couriers |
| Companies Covered | Accell Group, Riese & Müller, Rad Power Bikes, Urban Arrow, Tern Bicycles, Yuba Bicycles, Douze Cycles, Giant Manufacturing, Babboe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Cargo Bikes Market Strategic Shifts & Innovations
Active bifurcation between premium mid-drive configurations and simplified hub-motor architectures is segmenting the vendor base by technical capability rather than scale alone.
Mid-drive motor technology is bifurcating the competitive landscape between torque-optimized premium platforms and cost-minimized hub alternatives. Fleet operators in gradient-intensive municipalities are specifying mid-drive systems for loaded hill starts, while direct-to-consumer channels sustain volume through simpler hub-motor designs. This technical split is compressing the addressable middle market where neither specification satisfies procurement requirements.
REACH substance restrictions and the F-Gas Regulation are eliminating certain refrigerants and flame retardants from battery thermal management systems. Manufacturers are reformulating pack enclosures and cooling circuits to maintain safety ratings under tightened chemical thresholds. Dutch and German municipal tenders now embed these compliance requirements as disqualification criteria, accelerating supplier consolidation.
Direct-to-consumer channels are displacing traditional bicycle retail for private cargo bike purchases, though commercial fleet procurement remains anchored in specialized dealer networks. Urban delivery operators require localized service contracts and rapid parts availability that pure-play e-commerce cannot match. This channel tension is most visible in the Netherlands, where established commercial relationships protect incumbent suppliers from price-driven digital entrants.
Electric Cargo Bikes Market Segmentation
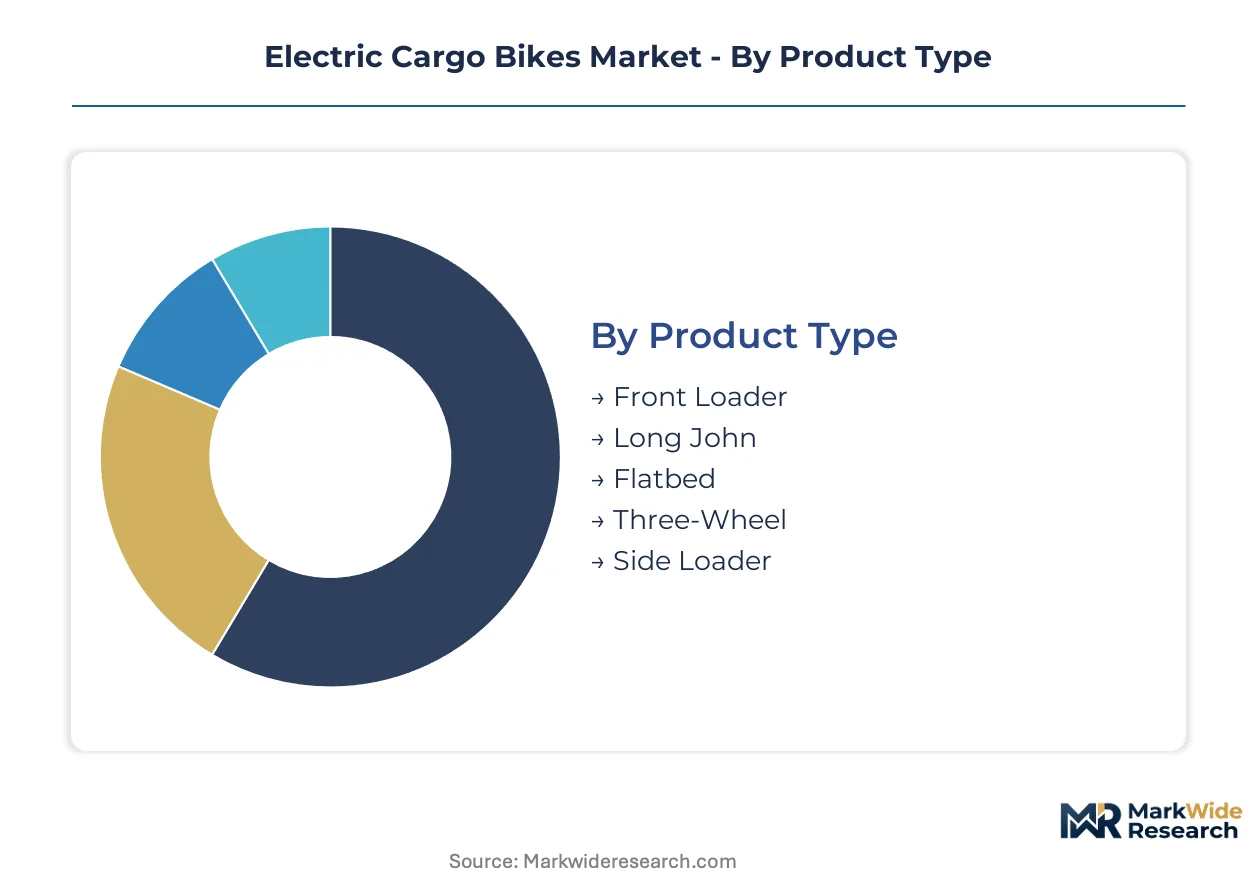
Segmentation in electric cargo bikes reveals how technical specifications align with operational economics across divergent use cases. Fleet procurement patterns and private purchase behaviors split sharply across product geometry, motor architecture, and service intensity requirements.
Product Type:
Margin pools concentrate in front-loading configurations where municipal certification requirements and specialized frame engineering sustain premium pricing power.
- Front Loader:Low-center-of-gravity platforms position cargo between the rider and front wheel, enabling 150-200 kilogram ratings with superior maneuverability in Amsterdam and Copenhagen historic districts. Dutch postal contracts specify this geometry exclusively for narrow-street access where diesel vans face restrictions.
- Long John:Extended wheelbase designs with rear-mounted powertrains distribute weight across longer frames for stability at speed. German premium manufacturers dominate this segment through in-house aluminum fabrication and EN 15194 electromagnetic compliance certification.
- Flatbed:Open-platform configurations serve construction material transport and bulky goods with modular rail systems for load securing.
- Three-Wheel:Delta and tadpole layouts prioritize balance over velocity for independent couriers navigating uneven surfaces.
- Side Loader:Asymmetric frame designs enable curb-level loading without dismounting, penetrating parcel locker integration contracts.
The dominant share belongs to Front Loader, while Long John is closing the gap fastest.
Technology:
Cost tier stratification separates hub-motor volume plays from mid-drive precision engineering where torque sensing commands procurement premiums.
- Hub Motor:Direct-drive and geared variants integrate motors into wheel hubs for simplified maintenance and lower acquisition costs. Direct-to-consumer channels sustain volume through this architecture despite gradient performance limitations in Pittsburgh and San Francisco hill corridors.
- Mid-Drive Motor:Central-mounted systems leverage drivetrain gearing for torque multiplication under loaded hill starts. Fleet operators in gradient-intensive municipalities specify Bosch and Shimano units for cargo stability and regenerative braking integration.
- Geared Hub Motor:Internal planetary gearsets multiply torque output without mid-drive complexity, occupying middle-market positioning.
- Friction Drive:Roller-based propulsion systems press against rear tires for retrofit applications and emergency backup power.
Mid-Drive Motor commands the steepest expansion trajectory as fleet procurement prioritizes loaded performance metrics.
Application:
Customer type concentration varies by service intensity, with scheduled municipal routes sustaining predictable revenue against volatile express delivery demand.
- Last Mile Delivery:Scheduled urban freight routes replacing diesel vans under low-emission zone mandates in Berlin and Amsterdam. Operators optimize for 100-150 kilogram payloads with rapid battery swap protocols.
- Food & Beverage Transport:Insulated cargo boxes with temperature maintenance for restaurant supply and meal delivery services. Cold-chain requirements drive specification of thermal management accessories and sealed enclosures.
- Courier Services:Time-sensitive document and small parcel transport prioritizing speed over payload capacity.
- Municipal Services:Parks maintenance, waste collection, and facility management contracts with standardized procurement specifications.
- Package Distribution:Hub-and-spoke consolidation from micro-fulfillment centers to residential addresses.
Last Mile Delivery anchors current volume, though Food & Beverage Transport is gaining share fastest through cold-chain specialization.
End User:
Supply concentration favors established dealer networks for commercial procurement against direct-to-consumer disruption in private purchase channels.
- Logistics Companies:Integrated fleet operators with centralized maintenance facilities and volume purchasing agreements. DHL and UPS deployment programs in European cities specify standardized platforms for parts commonality.
- Postal Services:National mail carriers with dedicated procurement teams and multi-year fleet replacement schedules. Royal Mail and PostNL contracts normalize front-loader specifications across urban route networks.
- Small Businesses:Independent retailers and tradespeople with mixed-use requirements and limited capital budgets.
- Urban Retailers:Grocery chains and specialty stores with scheduled restocking routes from distribution centers.
- Independent Couriers:Gig-economy operators prioritizing acquisition cost over durability specifications.
Logistics Companies hold the dominant share, while Postal Services are expanding their procurement fastest through national fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low-emission zone mandates and dedicated cycling infrastructure investments are concentrating electric cargo bike adoption in specific European and North American urban corridors where municipal procurement programs normalize commercial deployment.
Netherlands
Dutch postal contracts and municipal fleet programs specify front-loader configurations for narrow historic center access. The EU Green Deal embeds lifecycle carbon metrics into Randstad procurement tenders, advantaging suppliers with transparent battery provenance. Amsterdam and Utrecht anchor commercial adoption through dedicated lane networks and standardized charging infrastructure.
Germany
Berlin's diesel van restrictions and Hamburg's port-city logistics demands accelerate fleet replacement schedules. EN 15194 electromagnetic compatibility certification requirements exclude smaller frame builders from premium municipal channels. Bavaria and North Rhine-Westphalia concentrate manufacturing through in-house aluminum fabrication clusters serving long-john configurations.
United States
San Francisco and Pittsburgh hill corridors prioritize mid-drive torque sensing for loaded gradient performance in courier fleet selection. EPA battery transport classification and charger efficiency standards govern interstate distribution logistics. Pacific Northwest municipalities pilot cold-chain food delivery programs with insulated cargo box specifications.
Denmark
Copenhagen's integrated cycling infrastructure and national fleet electrification targets normalize commercial cargo bike operations ahead of 2030 diesel phase-out deadlines. REACH substance restrictions on battery thermal management materials reshape supplier qualification criteria. The Øresund Region concentrates food and beverage transport contracts through temperature-controlled platform specifications.
Belgium
Brussels low-emission zone enforcement and Antwerp port logistics demands drive last-mile operator fleet transitions. CSRD reporting timelines force mid-cap assemblers to build carbon accounting infrastructure for municipal tender compliance. Flanders anchors three-wheel variant adoption among independent couriers prioritizing balance on cobblestone surfaces.
Electric Cargo Bikes Market Key Industry Players
Listed leaders compete with private specialists across certification capability and frame engineering depth. The vendor base stratifies between premium mid-drive platforms and simplified hub-motor architectures. Three strategic archetypes dominate: German engineering heritage specialists, Dutch commercial fleet incumbents, and North American direct-to-consumer volume players. Competitive moves concentrate on EN 15194 certification acquisition and in-house frame production capacity expansion.
Within the premium engineering tier, Riese & Müller exemplifies German fabrication depth through captive aluminum frame production. Urban Arrow anchors Dutch commercial positioning through specialized front-loader designs optimized for postal procurement specifications. Rad Power Bikes occupies the direct-to-consumer volume position through simplified hub-motor architectures and price-driven market penetration. These three represent divergent competitive vectors rather than overlapping addressable markets.
| Leading Market Players |
|---|
| Accell Group |
| Riese & Müller |
| Rad Power Bikes |
| Urban Arrow |
| Tern Bicycles |
| Yuba Bicycles |
| Douze Cycles |
| Giant Manufacturing |
| Babboe |
| Others |
Cost & Logistics Intelligence
EN 15194 electromagnetic compatibility certification gates both supplier qualification and price differentiation in European procurement channels, compressing margins for uncertified assemblers while sustaining premium positioning for compliant manufacturers.
Pricing Analysis
Certification level creates the primary spread across the price spectrum, with EN 15194-compliant platforms commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium mid-drive, standard geared-hub, and economy direct-drive configurations reflects torque performance and battery provenance transparency. Cost compression in the hub-motor tier is intensifying because direct-to-consumer channels prioritize acquisition cost over loaded gradient capability. Independent couriers exhibit highest price sensitivity, while municipal fleet operators prioritize total cost of ownership and field-serviceability over unit economics.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production, with Taiwan and Japan supplying critical power electronics and motor controllers. German and Dutch frame fabricators draw from Asian battery ecosystems while maintaining captive aluminum welding and electromagnetic testing capacity. Single-source vulnerability concentrates in cathode material supply chains tethered to nickel and cobalt spot volatility. Distribution runs through specialized commercial dealer networks for fleet procurement, while direct-to-consumer channels bypass traditional bicycle retail through e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric cargo bikes represent a high-growth urban freight disruption as EU low-emission zone mandates force diesel van retirement ahead of regulatory deadlines.
For Market Incumbents: Fortify EN 15194 certification moats through in-house electromagnetic testing facilities and captive frame fabrication capacity. Deepen backward integration into aluminum welding and thermal management assembly to defend margin position against hub-motor price erosion from direct-to-consumer entrants. Prioritize municipal service contract renewals through localized parts availability guarantees. For New Entrants and Emerging Players: Differentiate on modular right-to-repair architectures that reduce total cost of ownership for small-business owner-operators. North American hill cities present the most penetrable geography where mid-drive torque sensing remains undersupplied against Pittsburgh and San Francisco fleet demand. Pursue cold-chain food delivery specialization with insulated cargo box integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Battery passport requirements reshape the acquisition landscape by advantaging targets with transparent cell provenance and established EU Green Deal compliance infrastructure. Five-to-ten year viability hinges on municipal fleet electrification permanence rather than subsidy dependency. Monitor EN 15194 certification backlog timelines as the critical signal for supply-constrained pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EN 15194 Certification Investment | Electromagnetic compliance unlocks premium municipal procurement channels in Amsterdam and Berlin. |
| Mid-Drive Motor Platform Standardization | Bosch and Shimano system integration improves fleet interoperability for DHL and UPS operators. |
| Battery Passport Compliance Program | Lifecycle carbon transparency satisfies EU Green Deal tender requirements for Randstad contracts. |
| Right-to-Repair Modular Architecture | Field-serviceable drivetrains reduce total cost of ownership for independent courier segments. |
| Connected Fleet Telematics Partnership | EU AI Act-compliant data handling secures predictive maintenance contracts with postal services. |
Research Approach
Initial hypotheses were tested against primary input from fleet procurement managers, municipal tender officials, frame fabrication engineers, and aftermarket service directors and refined through secondary validation against customs trade data, EN 15194 certification registries, municipal fleet procurement databases, and EU Green Deal implementation disclosures. Bottom-up volume estimates from frame builder production capacity and top-down demand projections from low-emission zone mandate timelines were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates growth contributions from motor technology substitution, regulatory compliance thresholds, and channel structure evolution. Segmentation dimensions modeled include cargo platform geometry, motor architecture tier, end-use application intensity, and municipal procurement cluster. CAGRs were derived from logistic diffusion curves fitted to fleet replacement schedules and diesel van retirement timelines, with battery cell cost trajectories and certification adoption rates as key industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained low-emission zone enforcement and lithium-ion cell supply continuity; material deviation in cathode material costs or regulatory delay would warrant model refresh. Recalibration cycles align with material shifts in EU battery passport implementation timelines and municipal fleet tender award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Motorcycle Seat Market