
 Motorcycle Headlight Market | 2026-2036
Motorcycle Headlight Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Headlight Market Analysis
A widening capability gap between capital-intensive LED platform developers and legacy halogen suppliers is reorganizing supplier tiers in motorcycle lighting. Valeo SA leverages its full-system integration expertise to dominate premium OEM contracts across European and Asian motorcycle brands. Koito Manufacturing Co., Ltd. anchors its position through deep manufacturing scale in projector and adaptive headlamp modules for Japanese OEMs. Varroc Engineering Limited competes aggressively on cost-optimized LED designs tailored to high-volume commuter motorcycles in emerging markets.
A motorcycle headlight is an electromechanical lighting assembly mounted to the front of a two-wheeled motor vehicle, typically incorporating a housing, reflector or projector optics, a light source operating between 12V and 48V DC, and a lens with specified beam cutoff patterns to illuminate road surfaces without dazzling oncoming traffic. Its primary commercial purpose is to ensure rider visibility and safety compliance under varying ambient conditions while supporting vehicle styling differentiation. LED product types now command the dominant margin pool as thermal management and optical efficiency improvements displace halogen across mid-range and premium motorcycles. Adaptive Lighting technology leads growth velocity as camera-integrated systems enable dynamic beam shaping for cornering and oncoming vehicle detection. OEM Manufacturers represent the most concentrated demand channel, though Enthusiast end users are driving aftermarket upgrade volumes for Smart Headlight retrofits.
Europe's ECE R19 and ECE R48 regulations mandate precise beam patterns and daytime running light functionality, forcing non-compliant suppliers out of EU market access while accelerating LED and adaptive system adoption. India's BIS certification requirements and the Automotive Industry Standard AIS-010 for lighting components impose parallel technical barriers on imports and domestic production alike. Japan's METI energy-efficiency guidelines and JIS D 5500 standards shape domestic OEM procurement specifications and export-ready product platforms. Stakeholders must monitor how divergent certification timelines across these three regulatory spheres reshape inventory and platform development priorities.
Market Dynamics
LED thermal management breakthroughs and ECE R19 beam-precision mandates are compressing legacy halogen supplier margins while rewarding full-system integrators with premium OEM contracts.
Growth Catalysts
- ECE R19 mandates:Europe's beam-pattern precision requirements are forcing LED and adaptive system adoption across all motorcycle classes entering EU markets.
- India two-wheeler production:Domestic component sourcing acceleration under BIS certification is creating captive demand for cost-optimized LED headlamp suppliers.
- Adaptive lighting modules:Camera-integrated dynamic beam shaping for cornering detection is penetrating premium motorcycle platforms.
Market Restraints
- Aluminum heat-sink cost volatility:LED thermal management hardware faces input price swings that compress module margins at the economy tier.
- Japanese OEM supply concentration:Koito Manufacturing and Stanley Electric anchor projector module supply, creating single-source risk for adaptive headlamp procurement.
- Legacy reflector tooling amortization:Halogen housing manufacturers face stranded capital in stamping dies and coating equipment.
Strategic Opportunities
- Indonesia commuter segment:Underpenetrated LED adoption in 110-150cc motorcycles creates white space for cost-engineered optical designs.
- Smart headlight retrofits:Enthusiast aftermarket channels are absorbing Bluetooth-connected, app-configurable beam modules.
- EU Green Deal procurement incentives:Energy-efficiency mandates in public fleet tenders favor adaptive LED systems with regenerative braking integration.
Industry Challenges
- Optical engineer scarcity:Adaptive beam algorithm development requires rare combinations of illumination physics and machine vision expertise.
- Multi-homologation timelines:Parallel ECE R19, BIS AIS-010, and JIS D 5500 certification cycles delay platform launches by 8-14 months.
- Legacy wiring harness incompatibility:CAN-bus integration with 12V halogen architectures forces expensive gateway module redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Headlight Market |
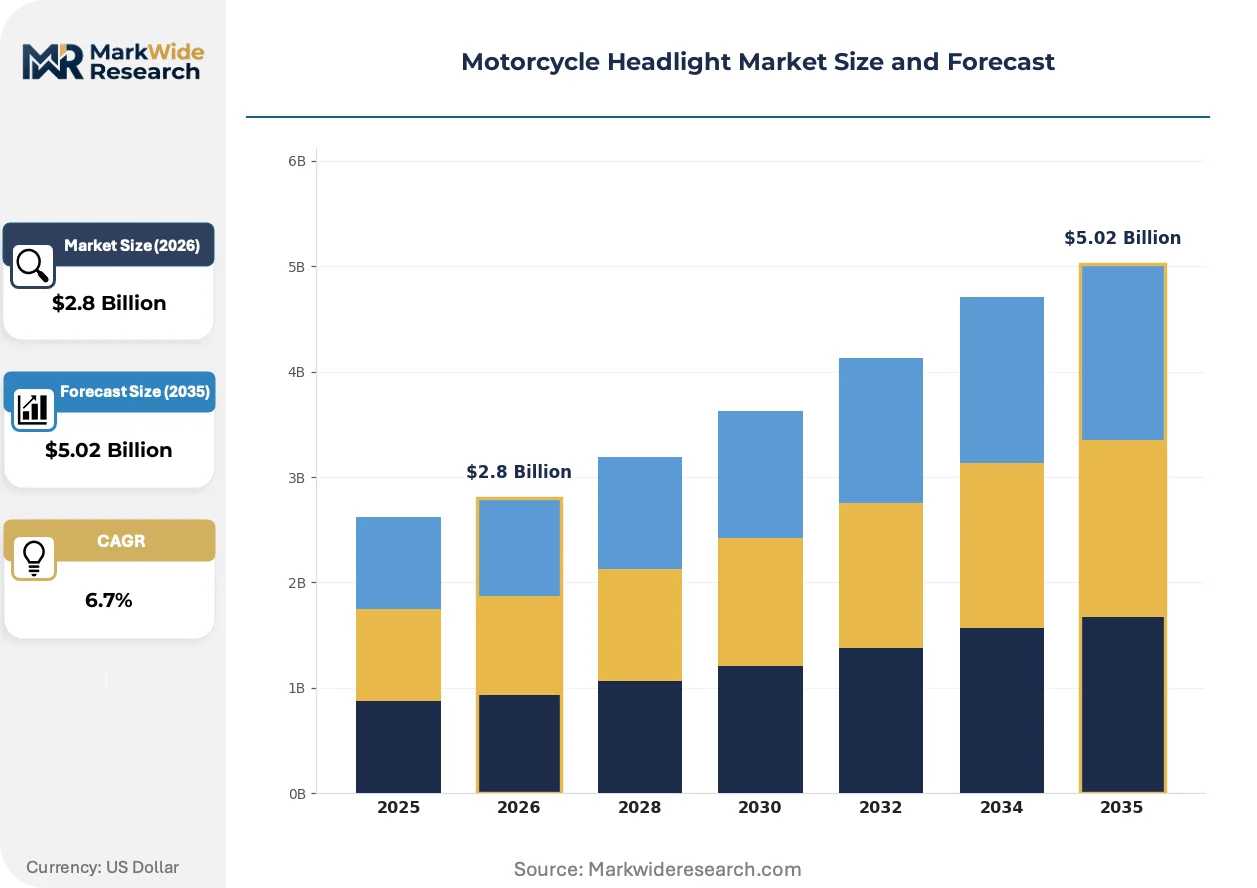
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, LED, HID, Xenon Technology: Adaptive Lighting, Smart Headlights, Projector, Reflector End User: Enthusiasts, Casual Riders, Commercial Fleet, OEM Manufacturers Application: Street Riding, Off-Roading, Touring, Racing |
| Companies Covered | Valeo SA, ZKW Group GmbH, Hella GmbH & Co. KGaA, Marelli Holdings Co., Ltd., OSRAM GmbH, Koito Manufacturing Co., Ltd., Varroc Engineering Limited, Lumax Industries Limited, Stanley Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Headlight Market Emerging Trajectories
Active matrix LED arrays and camera-fusion beam control are redrawing competitive boundaries between optical component suppliers and full-system integrators.
Matrix LED source technology is fragmenting the supplier landscape. These semiconductor emitter arrays enable pixel-level beam modulation for glare-free high beams. Tier-1 motorcycle OEMs in Germany and Japan are adopting them for 2026 model-year launches. The technology is fragmenting procurement patterns as lighting divisions bypass traditional bulb vendors to source directly from semiconductor foundries.
Europe's ECE R48 daytime running light mandate is reshaping front-end electrical architecture. The regulation requires dedicated DRL circuits independent of low-beam operation. Motorcycle electrical system designers must add control modules and wiring capacity. Premium European brands are responding with signature LED daytime signatures that double as brand identifiers.
Aftermarket upgrade behavior is compressing replacement cycles for halogen-to-LED conversions. Enthusiast riders now treat headlamps as styling and performance accessories rather than maintenance items. E-commerce direct-to-consumer channels in the United States and Germany are capturing this demand shift from traditional parts distributors.
Motorcycle Headlight Market Segmentation
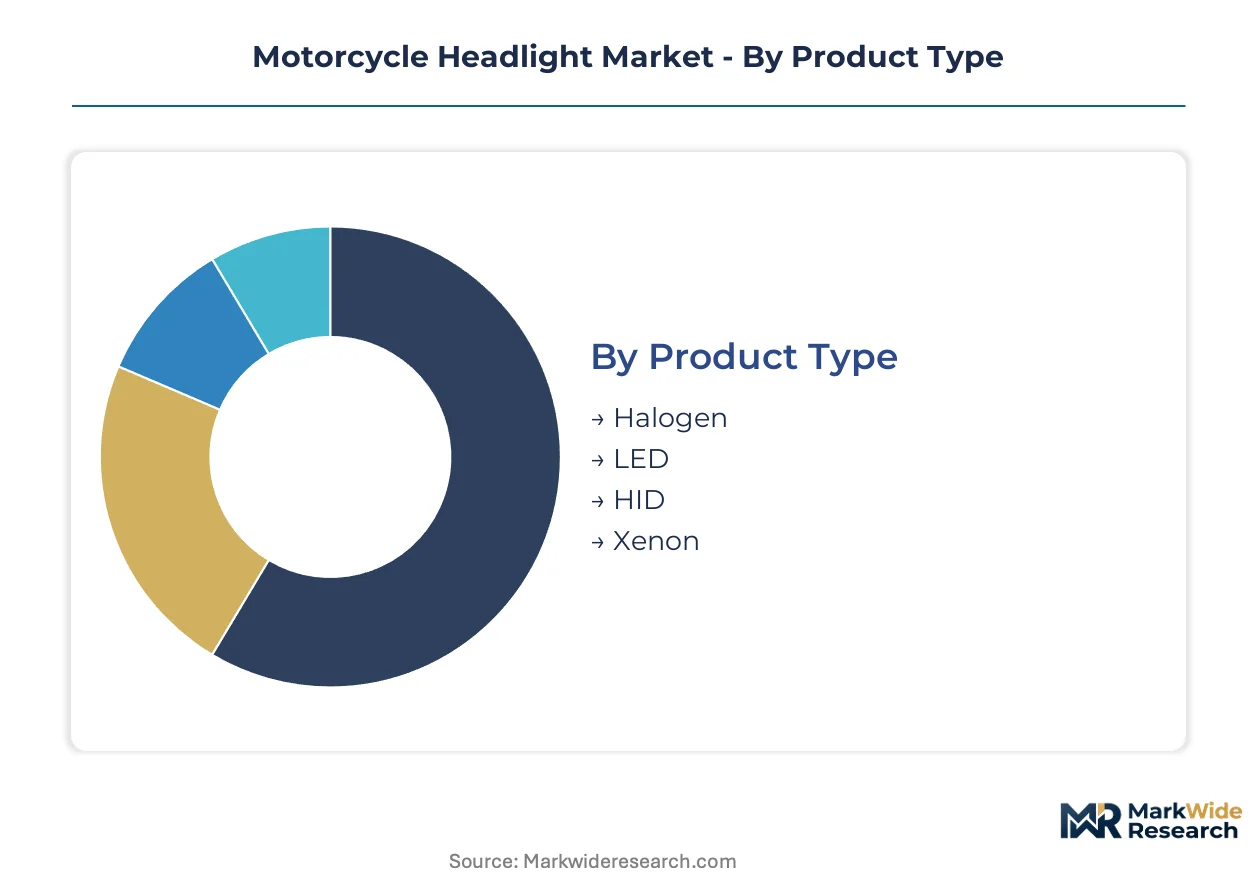
Motorcycle headlight segmentation reveals how procurement channels fragment across performance tiers and regulatory environments. OEM Manufacturers concentrate orders in certified LED and adaptive systems, while enthusiast channels absorb premium aftermarket upgrades.
Product Type:
Channel distribution splits sharply: OEM Manufacturers source LED modules directly from tier-1 integrators, while halogen replacement demand flows through aftermarket distributors and service centers.
- LED:Solid-state semiconductor emitters operating at 12V-48V DC with aluminum heat-sink thermal management. OEM Manufacturers in Germany and Japan specify these for ECE R19 compliance and adaptive beam integration. Demand concentrates in premium motorcycle platforms where energy efficiency mandates from the EU Green Deal accelerate displacement of legacy sources.
- Halogen:Tungsten-filament bulbs with halogen gas regeneration cycles, dominant in 110-150cc commuter motorcycles across India and Indonesia. Cost-optimized housing designs and established supplier tooling sustain volume production despite margin compression from LED thermal management breakthroughs.
- HID:High-intensity discharge arc lamps using xenon gas and metal halide salts, positioned in mid-tier sport motorcycles where output intensity exceeds halogen limits but LED costs remain prohibitive.
- Xenon:Gas-discharge technology with rapid ignition systems, primarily specified in aftermarket retrofit channels for styling differentiation rather than OEM factory fitment.
By volume, Halogen leads. By growth pace, LED is climbing the fastest.
Technology:
Margin concentration follows complexity gradients, with full-system integrators capturing premium value in camera-fused architectures while component suppliers compete in passive optical modules.
- Adaptive Lighting:Camera-integrated dynamic beam shaping with cornering detection and oncoming vehicle glare avoidance. METI energy-efficiency guidelines in Japan and ECE R19 precision mandates in Europe drive OEM specification. This segment commands the steepest expansion trajectory as 2026 model-year platforms from German and Japanese manufacturers adopt matrix LED source arrays.
- Smart Headlights:Bluetooth-connected modules with app-configurable beam patterns and diagnostic feedback. Enthusiast aftermarket channels in the United States and Germany absorb volumes as riders treat lighting as performance accessories rather than maintenance items.
- Projector:Ellipsoidal reflector-lens combinations producing sharp beam cutoffs, anchored by Japanese suppliers for domestic OEM procurement and export-ready platforms.
- Reflector:Parabolic aluminum-coated housings with replaceable bulb access, stranded capital in stamping dies faces obsolescence as LED module integration eliminates serviceable components.
By installed base, Reflector dominates. By value capture, Adaptive Lighting is gaining share fastest.
End User:
Customer type determines specification intensity, with fleet operators prioritizing total cost of ownership against enthusiast willingness to pay for connected features.
- OEM Manufacturers:Factory-fit procurement with multi-homologation requirements spanning ECE R19, BIS AIS-010, and JIS D 5500 certification cycles. These buyers concentrate demand for adaptive LED systems in premium platforms and cost-optimized designs for high-volume commuter motorcycles.
- Enthusiasts:Aftermarket upgrade behavior treating headlamps as styling investments, absorbing smart headlight retrofits through e-commerce direct-to-consumer channels.
- Casual Riders:Replacement-cycle demand for standard halogen and entry LED units through traditional parts distributors.
- Commercial Fleet:Logistics and rental operators specifying durability-optimized LED modules with extended service intervals under EU Green Deal fleet procurement incentives.
By order volume, OEM Manufacturers lead. By margin expansion, Enthusiasts are ahead.
Application:
Riding environment dictates beam pattern requirements, with regulatory certification varying across on-road compliance and off-road performance exemptions.
- Street Riding:ECE R48 daytime running light mandates and ECE R19 beam precision requirements govern specification. European and Japanese OEMs integrate signature LED daytime signatures as brand identifiers alongside low-beam compliance.
- Touring:Long-distance applications demanding adaptive range and cornering illumination, camera-fused systems penetrate premium touring motorcycles from German manufacturers.
- Off-Roading:High-output flood patterns exempt from on-road glare regulations, aftermarket suppliers dominate with auxiliary LED pod integration.
- Racing:Minimal homologation constraints allow experimental matrix arrays and weight-optimized housing designs, technology transfer flows to premium street platforms.
By unit volume, Street Riding leads. By technology adoption intensity, Touring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese engineering clusters while cost-engineered production scales through Indian and Indonesian manufacturing corridors. This asymmetry reshapes supplier investment priorities across the analysis window.
Germany
ECE R19 precision mandates and EU Green Deal fleet procurement drive specification intensity for adaptive LED systems. KBA homologation requirements enforce beam-pattern certification that blocks non-compliant imports. Stuttgart and Munich engineering centers host full-system integrators developing matrix LED platforms for 2026 model-year launches.
India
Two-wheeler production volumes exceeding domestic component absorption create captive demand for cost-optimized LED designs. BIS certification and AIS-010 lighting standards impose technical barriers that favor local sourcing. Chennai and Pune manufacturing belts concentrate stamping and optical housing production for 110-150cc commuter motorcycles.
Japan
METI energy-efficiency guidelines and JIS D 5500 standards shape OEM procurement specifications for domestic and export markets. Projector module supply concentrates through long-established supplier relationships. Aichi and Shizuoka prefectures anchor manufacturing scale in adaptive headlamp architectures for premium motorcycle platforms.
Indonesia
Underpenetrated LED adoption in 110-150cc commuter motorcycles creates white space for cost-engineered optical suppliers. The national industrial ministry's localization incentives accelerate domestic component sourcing requirements. Bekasi and Karawang industrial zones concentrate assembly operations serving ASEAN distribution networks.
United States
Enthusiast aftermarket channels absorb premium smart headlight retrofits through e-commerce direct-to-consumer distribution. NHTSA Federal Motor Vehicle Safety Standard 108 governs beam performance without mandating specific source technology. Southern California and Texas rider clusters drive demand for Bluetooth-connected, app-configurable beam modules.
Motorcycle Headlight Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure. Full-system integrators with semiconductor sourcing relationships capture premium OEM contracts, while component specialists compete on manufacturing scale for high-volume commuter platforms. The market organizes around three strategic archetypes: adaptive lighting platform developers, cost-optimized LED module fabricators, and legacy optical housing suppliers. Dominant competitive moves include backward integration into thermal management hardware and geographic expansion through joint ventures in Indian and Indonesian manufacturing corridors.
Among European-based full-system integrators, Valeo SA and ZKW Group GmbH exemplify the engineering-intensive archetype with deep OEM relationships. Japanese specialists Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. occupy positions anchored in projector module manufacturing scale. Indian cost-engineered suppliers Varroc Engineering Limited and Lumax Industries Limited represent the volume-focused tier serving high-production commuter markets. These six entities collectively illustrate the geographic and technological segmentation that defines competitive positioning.
| Leading Market Players |
|---|
| Valeo SA |
| ZKW Group GmbH |
| Hella GmbH & Co. KGaA |
| Marelli Holdings Co., Ltd. |
| OSRAM GmbH |
| Koito Manufacturing Co., Ltd. |
| Varroc Engineering Limited |
| Lumax Industries Limited |
| Stanley Electric Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
LED thermal management hardware replacing legacy halogen bulb assemblies simultaneously shifts procurement geography toward semiconductor foundries and compresses margin structures across tier-2 housing suppliers. Aluminum heat-sink cost volatility feeds directly into module pricing, while ECE R19 certification requirements stratify supplier tiers between premium integrators and commodity assemblers.
Pricing Analysis
The customization-premium spread separates configured-to-order adaptive LED systems from standard halogen replacement units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in the economy tier intensifies because aluminum heat-sink input prices fluctuate with commodity markets. OEM Manufacturers exhibit lowest price sensitivity for ECE R19-compliant adaptive modules, while Casual Riders drive replacement-cycle volume at entry price points.
Supply Chain Analysis
China and Taiwan anchor semiconductor emitter fabrication for matrix LED source arrays, while India and Indonesia concentrate optical housing stamping and final assembly. The supply chain draws from aluminum heat-sink extrusions, optical-grade polycarbonate lenses, and camera-fusion sensor modules. Single-source vulnerability concentrates in Japanese projector module supply through Koito Manufacturing and Stanley Electric. Distribution runs through tier-1 OEM direct procurement for factory-fit systems and aftermarket e-commerce channels for enthusiast retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward OEM Manufacturers as adaptive lighting platform consolidation reduces viable supplier counts. Japanese and German motorcycle brands now specify full-system integrators rather than component assemblers.
For Market Incumbents: Shield premium OEM relationships through backward integration into thermal management hardware and captive semiconductor sourcing partnerships. ECE R19 beam-precision mandates threaten non-compliant suppliers with EU market exclusion. Certification investment in parallel BIS AIS-010 and JIS D 5500 cycles secures multi-homologation readiness. For New Entrants and Emerging Players: Lead with cost-engineered LED optical designs targeting Indonesia's 110-150cc commuter segment where LED penetration remains underdeveloped. The enthusiast aftermarket channel offers lowest entry barriers through Bluetooth-connected smart headlight modules sold via direct-to-consumer e-commerce. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive lighting divisions seeking motorcycle vertical expansion. The five-to-ten year viability window favors full-system integrators with semiconductor foundry relationships over legacy housing stampers. Watch matrix LED array adoption rates in 2026 model-year German and Japanese premium platforms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Management | Captive aluminum heat-sink production shields margins from commodity volatility in LED modules. |
| Multi-Homologation Certification Investment | Parallel ECE R19, BIS AIS-010, and JIS D 5500 approval accelerates platform launch velocity across EU, India, and Japan. |
| Semiconductor Foundry Partnership | Direct matrix LED emitter sourcing bypasses traditional bulb vendors and secures supply priority. |
| Indonesia Manufacturing Joint Venture | Local assembly operations satisfy national industrial ministry localization incentives for ASEAN distribution. |
| Smart Headlight Aftermarket Platform Launch | Bluetooth-connected app-configurable modules capture enthusiast upgrade demand through e-commerce channels. |
Methodological Framework
The analysis maps LED source technology, adaptive lighting platforms, and halogen replacement cycles, each validated through procurement directors at tier-1 motorcycle OEMs, thermal management hardware suppliers, optical engineering specialists, and aftermarket distribution channel managers. Primary interview findings triangulate against vehicle production databases, customs and trade flow records, ECE R19 regulatory filing documents, and SEC disclosures from listed lighting component suppliers. Bottom-up unit volume estimates reconcile with top-down market value assessments.
Consistency checks validate projection outputs against external benchmarks including IHS Markit motorcycle registration data and regional production statistics. The analytical framework models technology penetration, end-user procurement channel, application use case, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level volume trajectories and value-per-unit trends, with specific inputs from aluminum commodity price indices and semiconductor foundry capacity utilization rates.
The analysis sits within stated boundaries; outcomes outside ECE R19 regulatory enforcement intensity or Indian two-wheeler production volumes would require recalibration. Forecasts reflect assumptions about thermal management cost curves and OEM platform standardization timelines. Recalibration cycles align with material shifts in EU Green Deal procurement incentives and matrix LED array adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market