
 Latin America Two-Wheeler Market | 2026-2036
Latin America Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Two-Wheeler Market Intelligence
Dealer networks across Brazil and Mexico are tilting toward multi-brand showrooms and integrated service centers to capture maintenance revenue. Honda Motor Co. Ltd. leverages its established manufacturing presence in Manaus to sustain cost-competitive petrol motorcycle output for Brazilian commuters. Hero MotoCorp Ltd. anchors its regional strategy through assembly partnerships that bypass full import duties. Italika dominates Mexico's mass-market tier through exclusive distributor relationships and localized production in Toluca.
Two-wheelers in Latin America encompass motorized vehicles with engine displacements ranging from 50cc to 250cc, constructed from steel tube frames, aluminum castings, and injection-molded polypropylene body panels, serving primarily as affordable individual transport and last-mile commercial logistics platforms. Motorcycles occupy the dominant revenue position given their fuel efficiency on poor road infrastructure and cargo-carrying adaptations for informal commerce. Scooters command growing share in Colombian and Mexican metropolitan cores where step-through convenience reduces rider training barriers. Electric bikes remain nascent but attract policy attention as cities implement congestion charges and fuel subsidy reforms.
Brazil's PROCONVE standards administered by IBAMA enforce escalating emission limits that compel manufacturers to invest in fuel injection and catalytic converter technology. Mexico's SEMARNAT coordinates with state environmental agencies to pilot electric two-wheeler incentives in Mexico City and Guadalajara. ANVISA in Brazil and COFEPRIS in Mexico regulate helmet and safety equipment standards that shape aftermarket accessory demand. Stakeholders must monitor how fiscal consolidation pressures across Argentina, Brazil, and Mexico affect consumer credit availability for vehicle purchases.
Market Dynamics
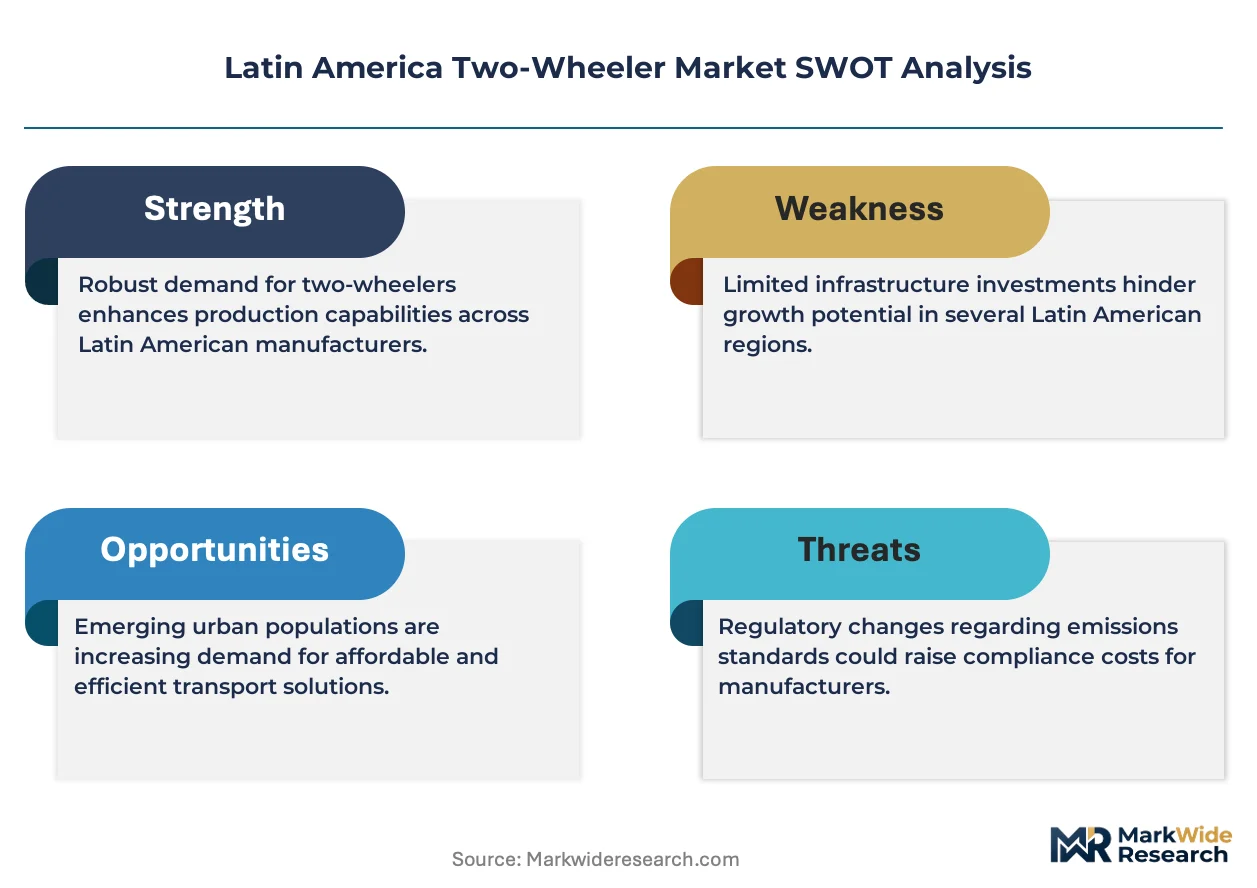
Brazil's PROCONVE L-7 emission standards are forcing fuel-injection retrofits across petrol motorcycle portfolios, compressing margins for manufacturers serving price-sensitive commuters while creating technology gaps between domestic and import-dependent competitors.
Growth Catalysts
- E-commerce logistics penetration:Last-mile delivery fleets in São Paulo and Mexico City are expanding two-wheeler procurement to serve urban fulfillment networks.
- PROCONVE regulatory progression:Brazil's escalating emission mandates are accelerating technology upgrades that improve fuel efficiency and extend vehicle lifecycles.
- Aluminum frame casting advances:Lightweighting innovations are reducing curb weights for 125cc-150cc commuter segments without sacrificing cargo capacity.
Market Restraints
- Steel tube frame cost volatility:Input price fluctuations for high-tensile steel constrain pricing flexibility for mass-market manufacturers.
- Import duty stacking:Argentina's layered tariff regime on CKD kits creates structural disadvantages versus localized assembly operations.
- Petrol scooter substitution pressure:Electric two-wheeler pilots in Bogotá and Santiago threaten displacement of 50cc-110cc urban commuter models.
Strategic Opportunities
- Colombia's Andean corridor:Medellín and Cali present underpenetrated demand for step-through scooters targeting female rider demographics.
- Battery-swapping infrastructure:Mexico City's congestion-pricing zones are creating regulatory tailwinds for electric motorcycle subscription models.
- Integrated service center networks:Multi-brand maintenance hubs are capturing aftermarket revenue streams previously fragmented across independent mechanics.
Industry Challenges
- Powertrain calibration expertise:Fuel-injection system tuning for high-altitude Andean operation requires specialized engineering talent scarce in regional R&D centers.
- Homologation timeline compression:PROCONVE certification cycles are shortening while test facility capacity in Brazil remains constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Two-Wheeler Market |
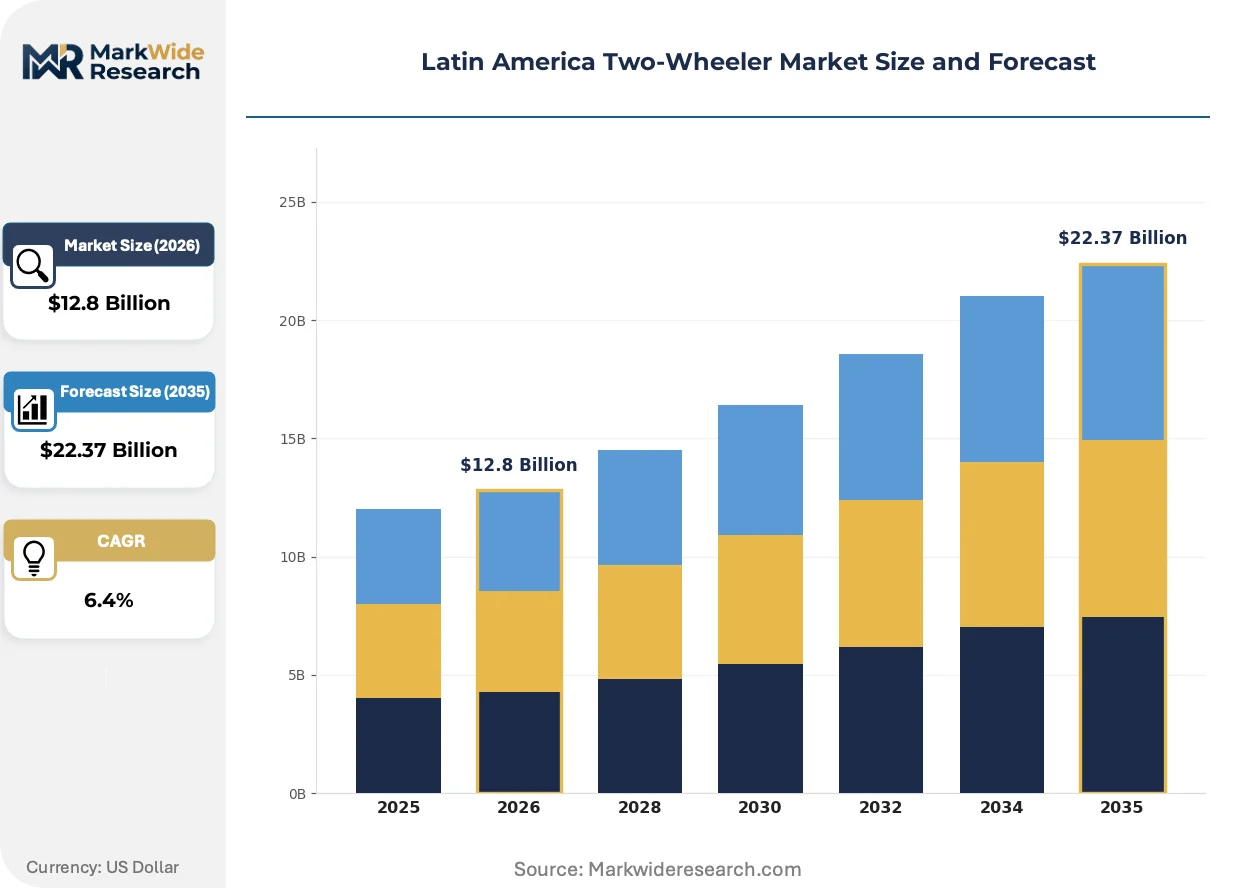
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorcycles, Scooters, Mopeds, Electric Bikes End User: Commuters, Delivery Services, Recreational Riders, Tourists Fuel Type: Petrol, Diesel, Electric, Hybrid Distribution Channel: Dealerships, Online Retail, Direct Sales, Rentals |
| Companies Covered | Suzuki Motor Corporation, Hero MotoCorp Ltd., Honda Motor Co. Ltd., Kawasaki Heavy Industries Ltd., Italika, Yamaha Motor Co. Ltd., TVS Motor Company Limited, CF Moto, Bajaj Auto Limited, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Two-Wheeler Market Strategic Shifts & Innovations
Powertrain architecture and distribution economics are converging to reshape competitive positioning across Latin America's two-wheeler value chain, with technology transitions outpacing legacy infrastructure in key metropolitan corridors.
Flex-fuel engine technology is hybridizing with electronic fuel injection to enable ethanol-gasoline blending ratios up to 100 percent in Brazilian commuter motorcycles. Sugarcane belt fleet operators are adopting these powertrains fastest, recognizing fuel cost arbitrage against pure petrol alternatives. The technology is hybridizing procurement criteria for municipal and corporate buyers, forcing manufacturers to maintain dual-calibration capabilities.
SEMARNAT's electric mobility incentive pilots in Mexico City and Guadalajara are mandating zero-emission vehicle quotas for commercial delivery operators. The policy is redirecting manufacturer product planning toward lithium-ion platform development previously deprioritized for Latin America. Metropolitan courier services are responding by trialing battery-as-a-service contracts to circumvent upfront capital barriers.
Digital platform integration is restructuring how informal commerce operators acquire and finance two-wheeler assets. App-based lender networks in Brazil's southeastern corridor are displacing traditional consumer finance channels for sub-250cc purchases. This behavioral shift concentrates most visibly among São Paulo's gig economy delivery workforce, where vehicle ownership is unbundling from employment relationships.
Latin America Two-Wheeler Market Segmentation
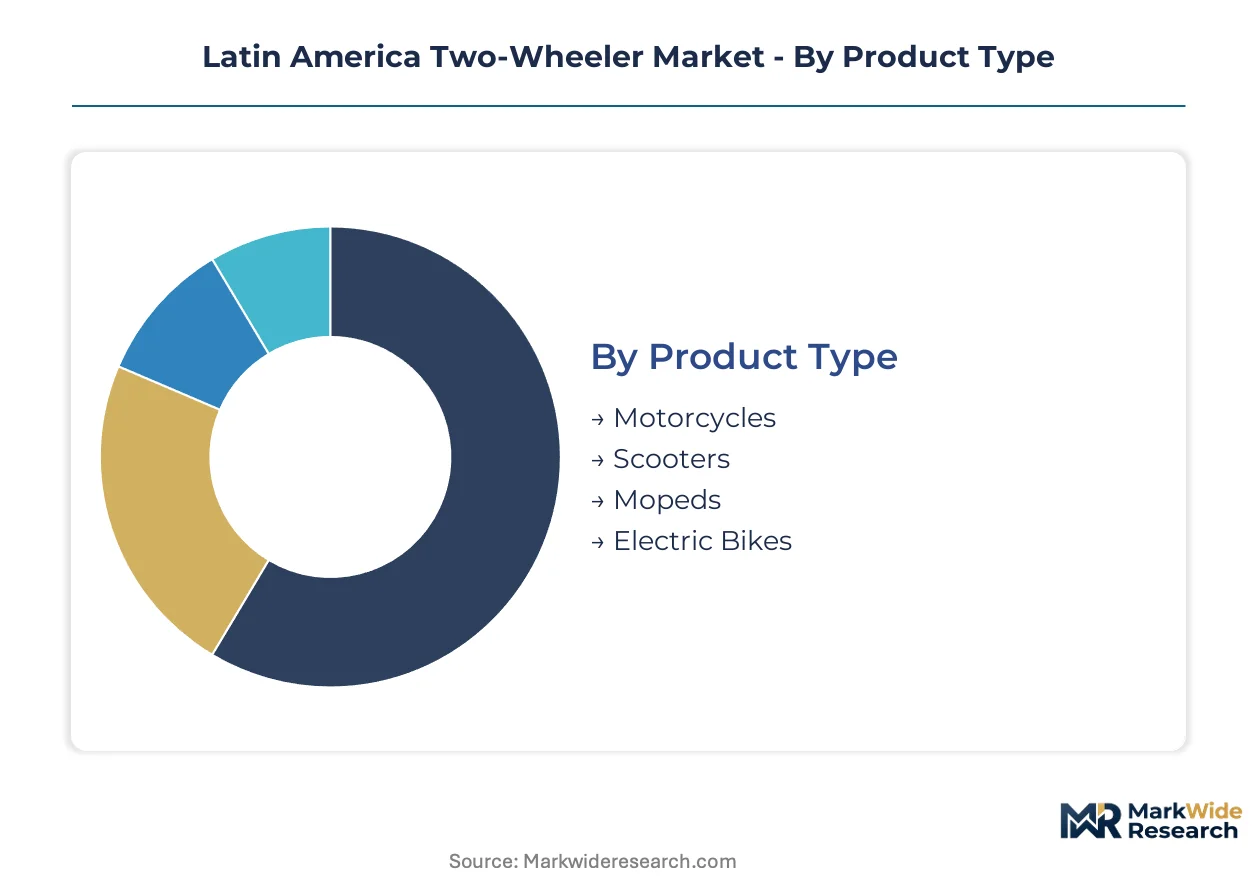
Segmentation reveals how Latin America's two-wheeler demand fragments across distinct mobility missions. Each category exposes divergent margin profiles, regulatory exposure, and channel economics that manufacturers must navigate simultaneously.
Product Type:
Use-case spectrum spans heavy-load commercial workhorses to lightweight urban runabouts, with frame architecture and powertrain calibration diverging sharply across the quartet.
- Motorcycles:Steel-tube framed vehicles with 125cc-250cc displacement dominate Brazilian sugarcane belt logistics and Colombian Andean freight corridors. São Paulo's delivery fleets specify reinforced rear subframes for 150kg cargo ratings, while PROCONVE L-7 compliance costs compress entry-level pricing bandwidth.
- Scooters:Step-through designs with automatic transmissions concentrate in Mexico City's congestion-priced zones and Medellín's steep hillside barrios. Female rider demographics in Colombian metropolitan cores favor the format's reduced training barriers and skirt-friendly ergonomics.
- Mopeds:50cc restricted-displacement units serve Brazilian favela access roads and Argentine provincial towns where licensing exemptions lower ownership thresholds. ANVISA helmet mandates and state-level insurance requirements reshape total cost of ownership calculations.
- Electric Bikes:Lithium-ion powered two-wheelers attract SEMARNAT pilot subsidies in Guadalajara and battery-swapping trials in Santiago's central business district. Range anxiety and charging infrastructure gaps limit penetration beyond municipal fleet procurement.
The dominant share belongs to Motorcycles, while Electric Bikes are gaining share fastest through regulatory tailwinds.
End User:
Customer economics separate stable ownership patterns from high-churn gig employment, with financing risk profiles diverging accordingly.
- Commuters:Individual purchasers across Brazil's southeastern industrial corridor seek 125cc-150cc fuel-injected models for daily São Paulo-Guarulhos corridor transit. Credit availability through digital lending platforms is displacing traditional bank motorcycle loans.
- Delivery Services:Fleet operators for Mercado Libre and Rappi specify 150cc-200cc cargo-modified units with reinforced suspension for Brazilian e-commerce logistics expansion into semi-urban zones. Asset utilization rates above 12 hours daily accelerate depreciation schedules.
- Recreational Riders:Weekend touring enthusiasts in Mexico's Bajío region and Colombia's coffee zone purchase 250cc+ displacement models with ABS braking. Seasonal demand concentration creates inventory management complexity for Toluca-area distributors.
- Tourists:Rental operators in Cancún and Cartagena deploy 110cc-125cc automatic scooters for short-term beach corridor mobility. COFEPRIS safety equipment standards and local licensing reciprocity agreements shape fleet specification.
Commuters anchor volume throughput, though Delivery Services are expanding most quickly through last-mile logistics deepening.
Fuel Type:
Powertrain selection locks in regulatory compliance pathways and operating cost structures that diverge across Brazil's ethanol corridor versus Andean petrol dependence.
- Petrol:Pure gasoline and E22 blend-compatible engines still power the majority of Colombian and Argentine two-wheeler fleets where ethanol infrastructure remains sparse. PROCONVE catalytic converter mandates add hardware cost without fuel arbitrage benefit.
- Diesel:Compression-ignition variants occupy niche commercial three-wheeler segments in Peruvian mining logistics and Bolivian high-altitude freight, though particulate emissions face tightening municipal restrictions.
- Electric:Battery-electric platforms attract Mexico City commercial fleet quotas and Bogotá congestion-exemption permits. Lithium-cell thermal management challenges persist for high-altitude Andean operation above 2,500 meters.
- Hybrid:Series-hybrid architectures with range-extender generators remain experimental, with pilot deployments limited to Brazilian corporate sustainability demonstration fleets seeking flex-fuel compatibility.
Petrol retains installed-base dominance, yet Electric is climbing the fastest through metropolitan zero-emission procurement mandates.
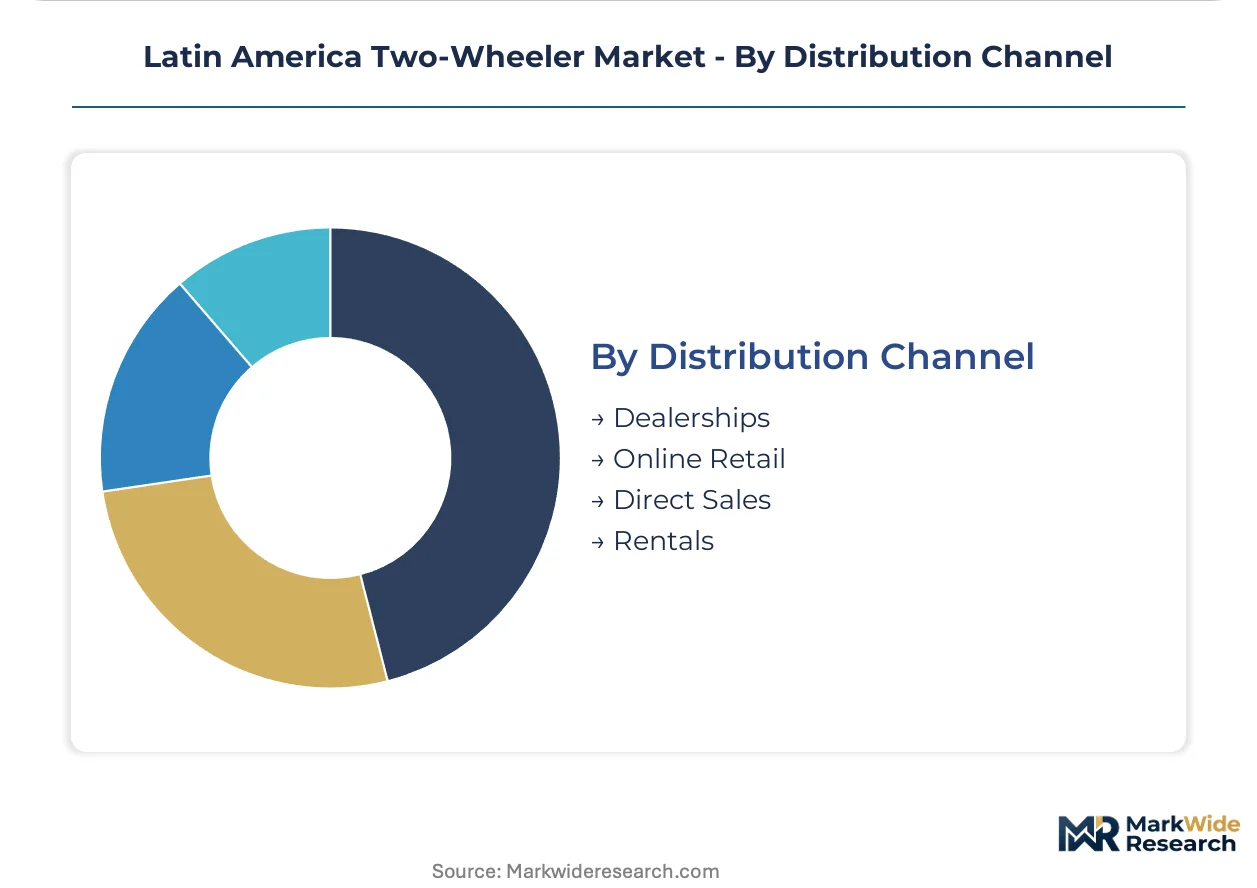
Distribution Channel:
Channel structure determines margin capture versus customer acquisition cost tradeoffs, with digital penetration reshaping traditional dealership economics.
- Dealerships:Multi-brand showrooms with integrated service centers concentrate aftermarket revenue in Brazil's Manaus Free Trade Zone and Mexico's Toluca manufacturing corridor. Honda and Italika anchor exclusive and semi-exclusive network tiers respectively.
- Online Retail:Digital-native lenders in São Paulo's southeastern corridor unbundle vehicle selection from financing approval, reducing showroom visit requirements for sub-250cc purchases. Logistics complexity for vehicle delivery constrains pure-play expansion.
- Direct Sales:Manufacturer-owned outlets serve corporate fleet procurement in Mexico City and Bogotá with volume pricing and maintenance contract bundling. Hero MotoCorp's assembly partnerships enable duty-advantaged direct channel economics.
- Rentals:Subscription and short-term lease models target tourist corridors and gig economy workers seeking asset-light mobility. Battery-as-a-service contracts for electric two-wheelers circumvent upfront capital barriers in Guadalajara pilot zones.
Dealerships command the dominant share, while Online Retail is narrowing the gap fastest through fintech integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing power through localized manufacturing and duty advantages, while Argentina's import-dependent structure forces cost premiums that compress volume throughput. This asymmetry shapes manufacturer capacity allocation and product mix decisions across the continent.
Brazil
São Paulo's industrial corridor and Minas Gerais anchor commuter demand for 125cc-250cc fuel-injected motorcycles serving daily transit between Guarulhos and the capital. IBAMA's PROCONVE L-7 emission standards mandate catalytic converter retrofits that elevate hardware costs for entry-level portfolios. Manaus Free Trade Zone assembly operations enable Honda and Yamaha to sustain cost-competitive petrol output against import-dependent rivals.
Mexico
Mexico City and Guadalajara concentrate step-through scooter demand among female commuters navigating congestion-priced metropolitan cores. SEMARNAT coordinates electric mobility incentive pilots that redirect manufacturer planning toward lithium-ion platform development. Toluca's manufacturing belt hosts Italika's localized production, anchoring mass-market supply through exclusive distributor relationships across the Bajío region.
Colombia
Medellín and Cali present underpenetrated demand for automatic scooters targeting female rider demographics in steep hillside barrios. The Ministry of Transport oversees municipal congestion-exemption permits that favor electric two-wheeler pilots in Bogotá's central business district. Andean freight corridors rely on 150cc-200cc cargo-modified units with reinforced rear subframes for 150kg ratings.
Argentina
Buenos Aires and Córdoba concentrate individual ownership patterns for 110cc-125cc commuters amid constrained consumer credit availability. The national customs authority administers layered tariff regimes on CKD kits that disadvantage import-dependent assemblers versus Mercosur-origin competitors. Mendoza's provincial logistics operators favor diesel three-wheelers for high-altitude freight despite tightening municipal particulate restrictions.
Chile
Santiago's central business district hosts battery-swapping trials for electric motorcycle subscription models targeting gig economy delivery workers. The Ministry of Energy coordinates metropolitan zero-emission procurement mandates that accelerate displacement of 50cc-110cc urban petrol models. Valparaíso's port logistics corridor sustains niche demand for 250cc+ displacement touring units among recreational riders.
Latin America Two-Wheeler Market Key Industry Players
Full-service manufacturers and assembly-specialist partners split the market between integrated production economies and duty-optimized import structures. The vendor base concentrates around three strategic archetypes: Japanese multinationals with regional manufacturing footprints, Indian volume exporters leveraging CKD partnerships, and Chinese value-positioned entrants. Competitive dynamics center on backward integration into engine casting and transmission machining, alongside geographic expansion through multi-brand showroom networks.
Within the multinational tier, Honda Motor Co. Ltd. and Yamaha Motor Co. Ltd. exemplify full-service manufacturers with established regional assembly presence. Hero MotoCorp Ltd. occupies a position among Indian exporters utilizing partnership structures to bypass complete-knockdown duties. Italika anchors the localized specialist archetype through captive production and exclusive distribution control in Mexico's mass-market tier.
| Leading Market Players |
|---|
| Suzuki Motor Corporation |
| Hero MotoCorp Ltd. |
| Honda Motor Co. Ltd. |
| Kawasaki Heavy Industries Ltd. |
| Italika |
| Yamaha Motor Co. Ltd. |
| TVS Motor Company Limited |
| CF Moto |
| Bajaj Auto Limited |
| Others |
Cost & Logistics Intelligence
Argentina's layered tariff regime on CKD kits determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic distribution of assembly capacity. This regulatory chokepoint compresses margins for import-dependent assemblers while amplifying cost advantages for Mercosur-origin manufacturers with captive Brazilian production.
Pricing Analysis
Configured-to-order cargo modifications for delivery fleets command 15-25% premiums over standard commuter specifications. Pricing stratifies across premium, standard, and economy tiers based on PROCONVE certification grade and after-sales service bundling. Cost compression in entry-level petrol portfolios is intensifying because IBAMA's emission mandates elevate fuel-injection hardware requirements. Fleet operators exhibit lowest price sensitivity given asset utilization rates above 12 hours daily, while individual commuters in Argentina's credit-constrained environment demonstrate highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates at Honda's Manaus Free Trade Zone operations, Italika's Toluca facilities, and Hero MotoCorp's Brazilian assembly partnerships. Steel tube frame sourcing draws from domestic Brazilian mills and Chinese high-tensile steel exporters, while aluminum die-casting for powertrain components rests on Mexican and Colombian foundry capacity. Single-source vulnerability persists for electronic fuel injection systems calibrated to PROCONVE specifications. Distribution runs through multi-brand showroom networks with integrated service centers capturing aftermarket revenue previously fragmented across independent mechanics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel-injection calibration expertise for high-altitude Andean operation represents a binding constraint, with regional R&D centers lacking sufficient engineering talent to support PROCONVE compliance timelines. This capability gap separates manufacturers with in-house powertrain development from assembly-dependent competitors.
For Market Incumbents: Insulate margin position by deepening backward integration into engine casting and transmission machining to offset steel tube frame cost volatility. Secure exclusive channel control through multi-brand service center networks in Brazil's southeastern corridor, defending against digital-native lenders unbundling vehicle selection from financing approval. For New Entrants and Emerging Players: Pursue Colombia's Andean corridor where Medellín and Cali present underpenetrated demand for automatic scooters targeting female rider demographics. Battery-as-a-service subscription models in Mexico City's congestion-priced zones offer the most penetrable entry path, circumventing upfront capital barriers that constrain pure retail plays. For Investors and Strategic Acquirers: PROCONVE L-7 certification deadline compression reshapes the acquisition landscape toward manufacturers with validated emission compliance and test facility access. Long-term viability favors assembly operations with duty-advantaged Mercosur positioning over import-dependent Argentine structures. Monitor IBAMA homologation queue lengths as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel-Injection Technology Retrofit | PROCONVE L-7 compliance enables continued market access across Brazilian industrial corridors. |
| Battery-Swapping Infrastructure Partnership | SEMARNAT pilot zones in Guadalajara create regulatory tailwinds for subscription-based electric mobility. |
| Multi-Brand Service Center Expansion | Integrated maintenance hubs capture aftermarket revenue from fragmented independent mechanic networks. |
| Aluminum Frame Lightweighting Investment | Casting advances reduce curb weights for 125cc-150cc segments without sacrificing cargo capacity ratings. |
| Digital Lending Platform Integration | Fintech partnerships in São Paulo's southeastern corridor displace traditional bank motorcycle loans for gig workers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, PROCONVE certification databases, and SEMARNAT electric mobility pilot documentation. Interviews with OEM platform engineers, aftermarket service heads, and fleet procurement managers at delivery operators across Brazil, Mexico, and Colombia anchored demand-side validation. Customs records and production data from the Manaus Free Trade Zone supplemented bottom-up volume triangulation against top-down macroeconomic indicators.
Forecast inputs span product type segmentation by frame architecture, fuel type transitions across ethanol and electric platforms, end-user bifurcation between individual commuters and commercial fleets, and distribution channel evolution toward digital-native financing. Modeled CAGRs derive from segment-level volume build-ups and value-per-unit trajectories across the projection horizon. PROCONVE regulatory phase-in schedules and SEMARNAT incentive pilot scaling assumptions shaped scenario-weighted outcomes.
Macroeconomic conditions sit as an overlay; deviation in Brazilian consumer credit availability, Argentine peso volatility, or Mexican fiscal consolidation pressures would shift the trajectory. Forecasts reflect documented assumptions regarding emission standard enforcement timelines and battery-swapping infrastructure deployment. Quarterly review of IBAMA homologation backlogs and fleet operator procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Two Wheeler Handlebars Market