
 Urn Liners Market | 2026-2036
Urn Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Urn Liners Market Analytics
North American specialty film producers is restructuring capacity toward compostable barrier formulations. Liquibox leverages its flexible packaging expertise to develop plant-based liner substrates with controlled decomposition rates. Pansaver anchors the commercial segment through heat-resistant polymer lines optimized for cremation protocols. Shurtape Technologies LLC competes via adhesive-backed liner systems that simplify installation for funeral directors.
Urn liners are protective inserts installed within cremation or burial urns to contain ashes, prevent leakage, and shield interior surfaces from moisture or corrosion; manufacturers typically extrude multilayer films or form pressed fibers with specified thickness between 0.5 and 3 millimeters to achieve tensile strength and barrier performance. Plastic liners still dominate volume across memorial and burial applications where cost sensitivity remains acute. Biodegradable variants are expanding fastest within the keepsake segment as consumers seek earth-friendly disposition options that align with natural cemetery requirements. Metal and textile categories occupy premium niches in display applications where heirloom aesthetics command higher margin pools.
FDA regulations on indirect food-contact polymers provide a compliance baseline for barrier film safety, while EPA guidelines on landfill biodegradation shape certification requirements for compostable alternatives. The EU Green Deal and REACH chemical restrictions are forcing European suppliers to eliminate conventional plasticizers and accelerate bio-based resin adoption. Stakeholders must monitor evolving state natural burial statutes and cemetery operator procurement standards to align product portfolios with shifting compliance and consumer preference trajectories.
Market Dynamics
Material transition pressure from the EU Green Deal and proliferating state natural burial statutes is forcing manufacturers to reconfigure resin portfolios and certification pipelines faster than production cycles typically permit.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH restrictions on conventional plasticizers compel European suppliers to accelerate bio-based resin qualification, opening first-mover margin pools for certified compostable barrier films.
- California natural burial statute expansion:Cemetery operator procurement mandates in the state are converting memorial product specifications toward biodegradable specifications, pulling demand from conventional polymer liners.
- Japan's green cemetery cluster development:METI-supported natural burial site construction in prefectures with aging demographics is concentrating demand for earth-friendly disposition accessories.
Market Restraints
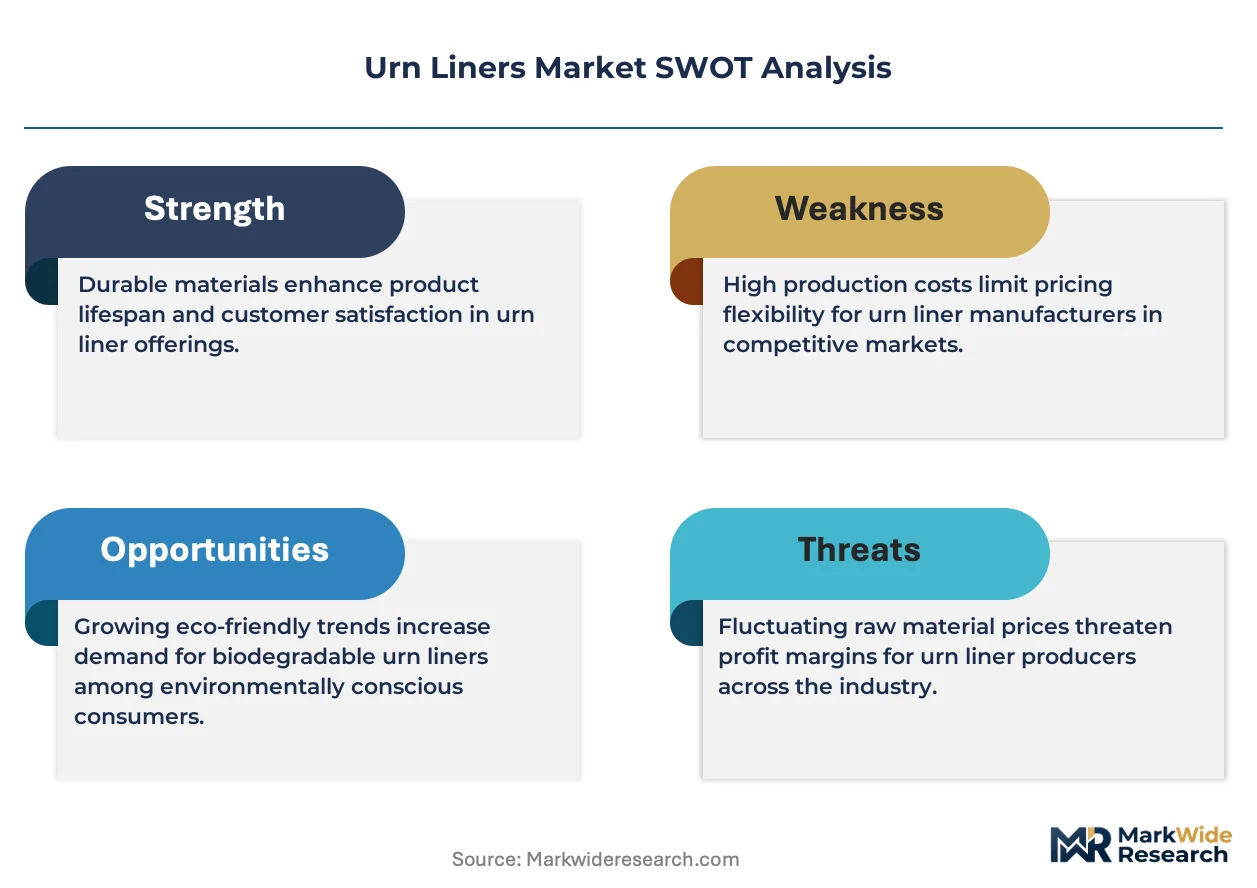
- Compostable resin feedstock volatility:PLA and PHA supply concentrates among a handful of fermentation-based producers, exposing liner manufacturers to agricultural commodity price swings.
- Cremation protocol thermal constraints:Biodegradable substrates face technical ceilings around heat resistance thresholds, limiting their deployment in high-temperature memorial applications where polymer liners retain functional advantage.
- FDA indirect food-contact compliance baselines:Barrier film safety requirements designed for food packaging create friction when adapted to ash-containment applications, lengthening certification timelines.
Strategic Opportunities
- Germany's cemetery privatization wave:Municipal-to-private operator transitions in Bavaria and Baden-Württemberg are unbundling procurement, creating entry points for specialized liner suppliers outside incumbent funeral home networks.
- Direct-to-consumer memorial retail:E-commerce channels for keepsake urns bypass traditional funeral home distribution, enabling biodegradable liner brands to capture margin previously absorbed by intermediaries.
- Dual carbon goal alignment in China:Provincial cemetery administrators in Jiangsu and Zhejiang are piloting low-carbon disposition standards, positioning compostable liners as compliance instruments for public procurement.
Industry Challenges
- Decomposition rate calibration expertise:Manufacturers lack sufficient polymer scientists capable of tuning controlled degradation timelines to match specific soil chemistry and burial depth requirements across cemetery microclimates.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of ASTM D6400, EN 13432, and emerging state-level biodegradable standards strains quality assurance bandwidth and extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urn Liners Market |
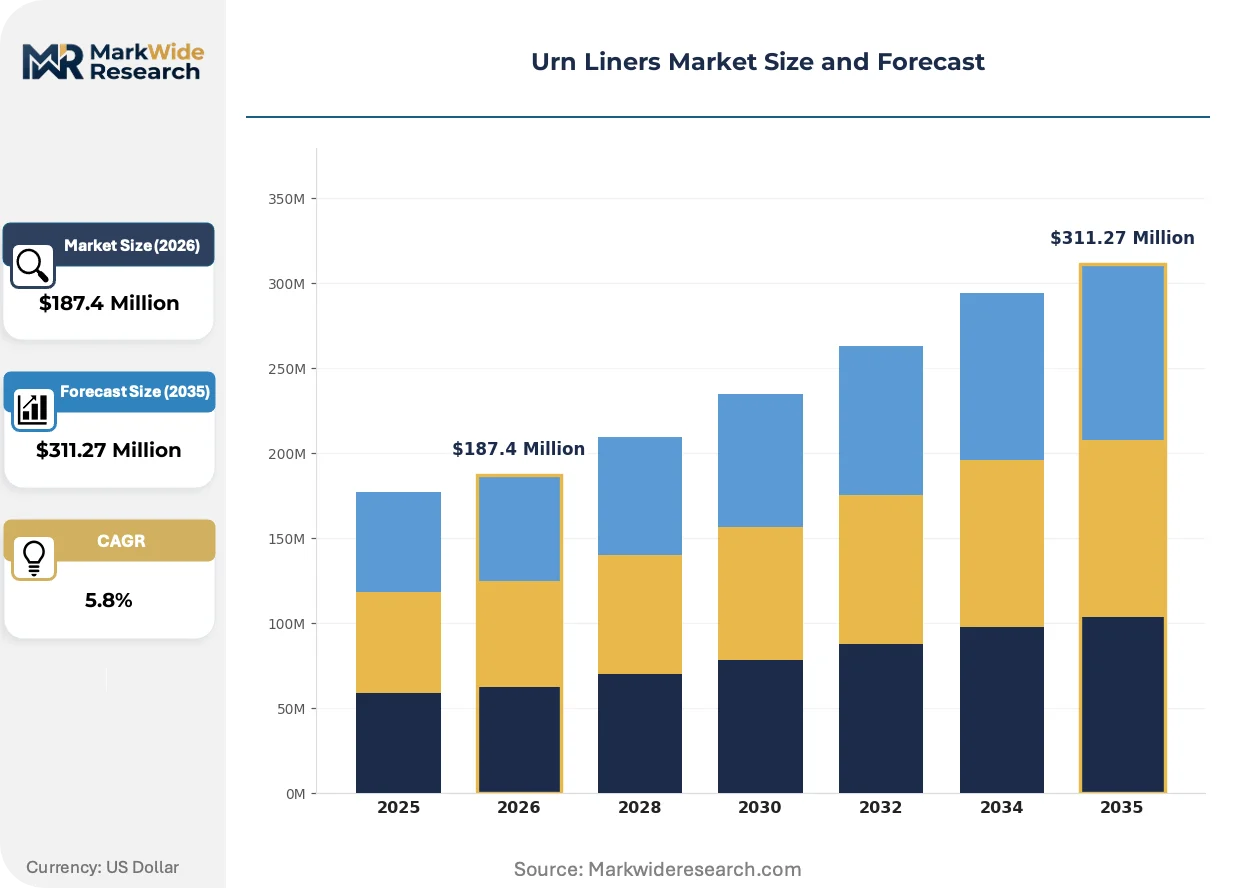
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Biodegradable, Metal, Textile Material: Clay, Steel, Wood, Composite Size: Small, Medium, Large, Extra Large Application: Burial, Memorial, Display, Keepsake |
| Companies Covered | Liquibox, Pansaver, Shurtape Technologies LLC, Kittrich Corporation, Seville Classics Inc, Drymate, Hills Point Industries LLC, Konrad Hornschuch AG, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urn Liners Market Evolving Landscape
Active material science investment is collapsing the performance gap between petroleum-derived barriers and plant-based alternatives, while regulatory chemistry restrictions and buyer channel fragmentation are rewriting competitive access rules.
Multilayer coextrusion of polylactic acid with nanocellulose reinforcement is rewriting tensile strength benchmarks for biodegradable urn liners. Crematorium operators in Germany and Japan are piloting these substrates for primary containment applications previously reserved for fossil-based films. The technology is compressing the premium pricing window that conventional polymers commanded in high-performance memorial segments.
REACH Annex XVII expansion on phthalate plasticizers is eliminating legacy formulation options for European barrier film producers. Manufacturers must qualify bio-based plasticizer alternatives or exit the EU memorial supply chain entirely. Compostable liner categories capture disproportionate investment attention as a result, with certification bodies in Germany and the Netherlands experiencing backlog in biodegradation testing capacity.
Funeral home purchasing consolidation is compressing supplier negotiation cycles and unbundling accessory procurement from casket and urn package contracts. Independent liner manufacturers now face direct price comparison against vertically integrated memorial product houses. California and New York exhibit the most acute channel restructuring, where group purchasing organizations for funeral homes have centralized liner specification authority.
Urn Liners Market Segmentation
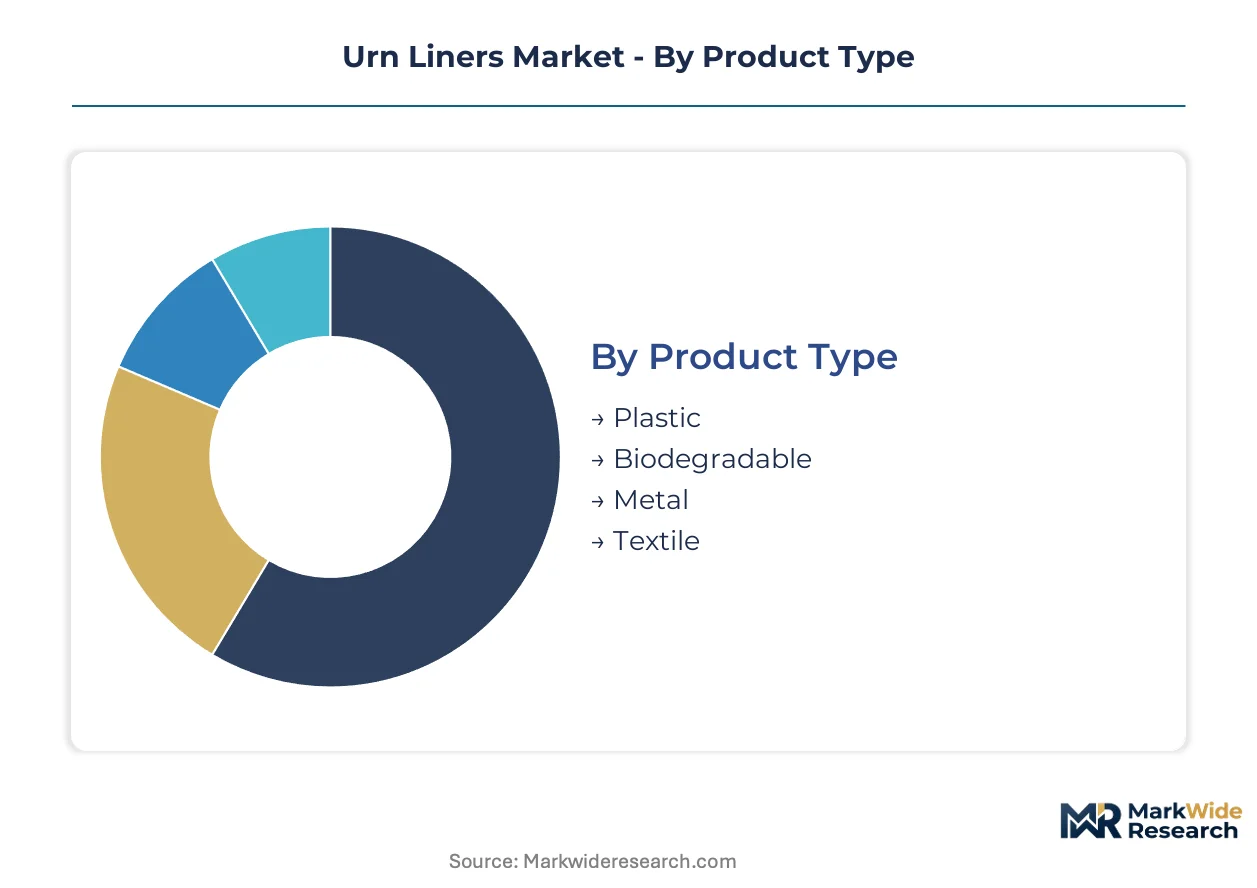
Segmentation in the urn liners market reveals sharp divides between cost-driven volume categories and premium-positioned alternatives. Manufacturers must navigate divergent certification requirements and procurement channels across each tier.
Product Type:
Plastic liners dominate unit volume while biodegradable variants capture expanding margin pools in green burial corridors.
- Plastic:Multilayer polyethylene and polypropylene films, typically 0.5–3 millimeters thick, deliver moisture barriers and tensile strength for cremation protocols. Demand concentrates in North American funeral home networks where cost sensitivity in memorial packages preserves polymer dominance despite regulatory pressure.
- Biodegradable:Polylactic acid and nanocellulose-reinforced substrates achieve controlled decomposition aligned with natural cemetery requirements. California cemetery operators and Japan's METI-supported green burial sites are pulling specification shifts fastest, though thermal constraints limit high-temperature memorial applications.
- Metal:Stainless steel and aluminum inserts serve heirloom display applications where corrosion resistance and aesthetic permanence justify premium positioning.
- Textile:Woven natural fibers and treated cotton blends occupy niche keepsake segments where tactile warmth and customization options differentiate from industrial alternatives.
Today's leader: Plastic. Tomorrow's challenger: Biodegradable.
Material:
Material selection tracks directly against end-use thermal and decomposition requirements, with composite formulations bridging performance gaps.
- Clay:Fired ceramic liners provide inert containment for burial applications where soil chemistry compatibility matters; German natural cemetery operators specify these for pH-sensitive sites.
- Steel:Galvanized and stainless grades anchor cremation containment where structural integrity under thermal stress is non-negotiable.
- Wood:Untreated and oil-finished variants serve biodegradable burial mandates; supply concentrates among Central European craftsmen serving Bavarian and Baden-Württemberg privatized cemeteries.
- Composite:Hybrid mineral-polymer formulations merge barrier performance with accelerated degradation timelines; Jiangsu and Zhejiang provincial administrators in China are piloting these for dual carbon goal alignment.
Steel holds the installed base. Composites are climbing the fastest.
Size:
Size specifications fragment procurement across cremation volume standards and cemetery plot constraints.
- Small:Designed for partial ash containment and keepsake urns; direct-to-consumer e-commerce channels are expanding this segment outside traditional funeral home distribution.
- Medium:Matches standard adult cremation volumes; group purchasing organizations in California and New York centralize specification authority here.
- Large:Accommodates above-average remains or companion urns; cemetery operators in Japan's aging prefectures drive demand for dual-capacity designs.
- Extra Large:Serves specialized memorial applications and institutional procurement; limited production runs sustain premium pricing.
Medium sizes command procurement volume. Small sizes are gaining share fastest through retail bypass.
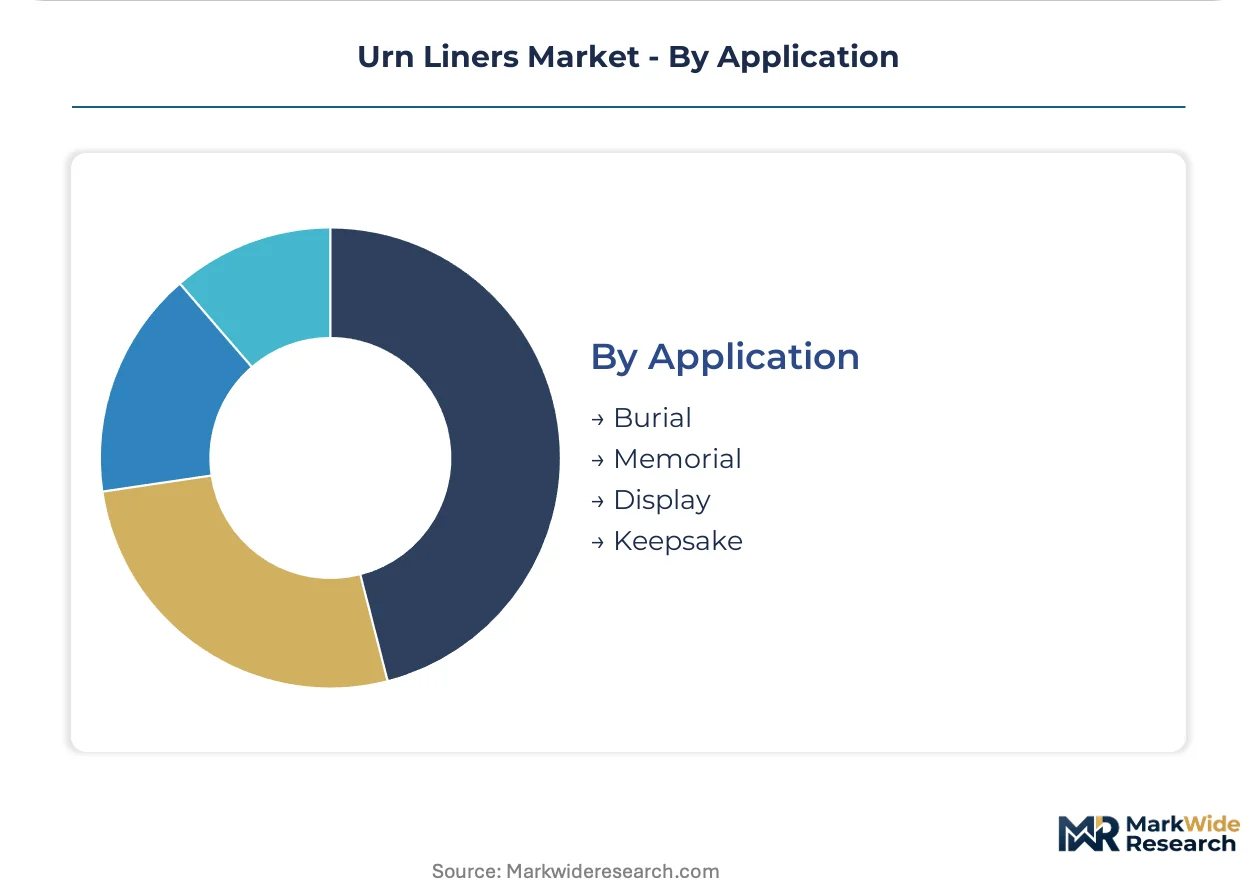
Application:
Application segmentation separates regulated burial compliance from discretionary memorial spending.
- Burial:Requires biodegradable or inert materials meeting state natural burial statutes and cemetery operator procurement standards; EU Green Deal chemical restrictions are forcing resin transitions fastest here.
- Memorial:Balances durability with aesthetic presentation; REACH Annex XVII phthalate phase-outs are eliminating legacy European formulations.
- Display:Prioritizes heirloom aesthetics and corrosion resistance; metal and textile categories concentrate margin capture.
- Keepsake:Smallest format segment where consumer preference for earth-friendly options is expanding biodegradable penetration fastest.
Burial applications anchor regulatory compliance investment. Keepsake applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers relocate capacity to jurisdictions with lower compliance costs for conventional polymers while positioning bio-based qualification labs in markets with strictest certification requirements.
United States
California's natural burial statute expansion is converting cemetery procurement specifications toward biodegradable liners, pulling demand from conventional polymer alternatives. EPA landfill biodegradation guidelines shape certification baselines for compostable products entering the market. Los Angeles and San Francisco funeral home networks are piloting plant-based liner programs with controlled decomposition timelines.
Germany
Cemetery privatization in Bavaria and Baden-Württemberg is unbundling procurement from municipal operators, creating entry points for specialized suppliers. REACH Annex XVII restrictions on phthalate plasticizers are eliminating legacy formulation options for barrier film producers. Cologne and Düsseldorf certification bodies are experiencing backlog in biodegradation testing capacity for compostable alternatives.
Japan
METI-supported green burial site construction in prefectures with aging demographics is concentrating demand for earth-friendly disposition accessories. JIS standards for biodegradable materials provide technical baselines for domestic qualification. Tokyo and Osaka memorial product distributors are expanding keepsake urn lines with compostable liner options.
China
Provincial cemetery administrators in Jiangsu and Zhejiang are piloting low-carbon disposition standards under dual carbon goal alignment. SAMR standards development for biodegradable packaging creates regulatory overlap with memorial applications. Shanghai and Suzhou flexible packaging producers are reconfiguring extrusion capacity toward polylactic acid substrates.
United Kingdom
Natural burial ground expansion in England and Wales is driving specification shifts for biodegradable containment products. Environment Agency guidance on cemetery waste streams influences operator procurement decisions. London and Birmingham funeral service consolidators are centralizing liner specification authority through group purchasing arrangements.
Urn Liners Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and direct-to-consumer channels to bypass traditional funeral home distribution. The market structure fragments across specialty film extruders, adhesive systems manufacturers, and flexible packaging converters with adjacent memorial applications. Three archetypes dominate: multilayer barrier specialists, installation-system integrators, and compostable substrate innovators. Capacity reconfiguration toward plant-based resins and strategic partnerships with certification bodies represent the dominant competitive moves.
Within the barrier film tier, Liquibox and Pansaver exemplify divergent specialization paths. Liquibox anchors flexible packaging expertise applied to plant-based liner substrates with controlled decomposition rates. Pansaver occupies heat-resistant polymer positioning optimized for cremation protocol requirements. Konrad Hornschuch AG represents European adhesive-backed system integration that simplifies installation workflows for funeral directors. These three entities sit within distinct competitive vectors rather than direct product overlap.
| Leading Market Players |
|---|
| Liquibox |
| Pansaver |
| Shurtape Technologies LLC |
| Kittrich Corporation |
| Seville Classics Inc |
| Drymate |
| Hills Point Industries LLC |
| Konrad Hornschuch AG |
| 3M |
| Others |
Value Network & Pricing Analysis
PLA and PHA resin feedstock costs cascade from agricultural commodity markets through fermentation-based producers to liner manufacturers, compressing margin pools in biodegradable tiers while petroleum-derived multilayer films retain cost advantages in cremation-heavy segments.
Pricing Analysis
Funeral home group purchasing organization margins absorb pricing power from specialized liner suppliers, particularly in California and New York where procurement authority has centralized. Three-tier pricing structure across premium, standard, and economy levels separates certified compostable barrier films from conventional polymer alternatives and basic polyethylene liners. Cost compression in biodegradable categories is intensifying because agricultural commodity volatility feeds through PLA and PHA supply chains. Cemetery operators and direct-to-consumer channels show divergent price sensitivity, with institutional buyers negotiating volume discounts while retail purchasers accept premiums for earth-friendly specifications.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for barrier film producers serving cemetery operator networks. Raw material sourcing draws from Chinese polylactic acid fermentation capacity, South Korean nanocellulose production, and North American polyethylene resin corridors. Single-source vulnerability concentrates in PLA feedstock supply among a handful of agricultural commodity processors. Distribution runs through funeral home consolidators and direct-to-consumer e-commerce channels, with biodegradable liner brands increasingly bypassing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable liner adoption creates margin-expansion headroom as certification premiums offset agricultural commodity cost volatility through cemetery operator procurement shifts.
For Market Incumbents: Cement barrier film formulation leadership by accelerating bio-based plasticizer qualification ahead of REACH Annex XVII enforcement. Deepen backward integration into polylactic acid resin supply through partnerships with fermentation-based producers to defend against feedstock volatility. Channel control through group purchasing organization relationships in California and New York preserves volume access against direct-to-consumer disruption. For New Entrants and Emerging Players: Direct-to-consumer keepsake urn buyers represent the most penetrable entry point, bypassing funeral home consolidators that dominate medium and large format procurement. Germany's privatized cemetery operators in Bavaria and Baden-Württemberg offer white-space access outside incumbent funeral home networks. E-commerce platform positioning with compostable liner bundling captures margin previously absorbed by distribution intermediaries. For Investors and Strategic Acquirers: Roll-up economics work for specialty film extruders with adjacent flexible packaging expertise because certification body relationships and resin qualification pipelines create scarce capabilities difficult to replicate. Five-to-ten year viability hinges on bio-based resin adoption curves rather than petroleum-derived incumbent defense. Watch biodegradable certification backlog at German and Dutch testing facilities as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PLA Resin Supply | Captive agricultural commodity sourcing insulates margins from fermentation capacity bottlenecks in China and Thailand. |
| Certification Body Partnership | Priority testing access at German and Dutch facilities accelerates ASTM D6400 and EN 13432 qualification timelines. |
| Direct-to-Consumer Channel Launch | E-commerce positioning for keepsake urn liners bypasses funeral home GPO consolidation in California and New York. |
| Composite Formulation R&D Investment | Hybrid mineral-polymer substrates bridge thermal performance gaps for cremation applications in Jiangsu and Zhejiang pilots. |
| Cemetery Operator Procurement Alliance | Long-term supply agreements with privatized German and Japanese operators secure volume commitments ahead of specification shifts. |
Research Methodology
Multiple input streams — primary interviews with flexible packaging executives, cemetery procurement managers, and certification laboratory directors; secondary validation through EPA landfill biodegradation guidelines, EU REACH Annex XVII restrictions, and ASTM/EN certification databases; customs and trade data for resin feedstock flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material composition, size specification, and application segmentation dimensions modeled volume and value outputs over the projection horizon. CAGRs were derived from installation base growth rates and replacement cycle analysis. Forecast inputs incorporated natural burial statute adoption curves in California, Germany, and Japan alongside METI-supported green cemetery construction timelines.
Inputs from certification bodies and cemetery operator procurement databases were available through the study window; gaps in real-time PLA and PHA spot pricing introduce uncertainty bands around biodegradable tier projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Global Strapping Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Thermal Insulation Packaging Market