
 Invisible Tapes Market | 2026-2036
Invisible Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Invisible Tapes Market Foresight
Modular packaging kits is restructuring how buyers evaluate invisible tape solutions across e-commerce and retail channels. 3M leverages its polymer science heritage to sustain premium positioning in office and industrial channels. Sicad Group anchors European supply through specialized acrylic formulations for invisible bonding applications. ShurTech Brands competes on brand recognition and channel density in North American consumer segments.
Invisible tapes are pressure-sensitive adhesive strips engineered for optical clarity, typically manufactured from biaxially oriented polypropylene or polyester films coated with solvent-free acrylic emulsions, designed to bond substrates without visible residue or surface distortion. The product serves commercial and consumer markets requiring discrete fastening in document repair, gift wrapping, display assembly, and temporary product fixation. Transparent variants lead volume throughput due to universal compatibility with paper and lightweight packaging substrates, while permanent acrylic formulations capture margin pools in industrial end-use where shear strength and temperature resistance justify price premiums. Double-sided configurations represent the fastest-growing material architecture as manufacturers integrate hidden fastening into premium packaging and point-of-sale displays.
EPA guidelines on volatile organic compound emissions shape adhesive formulation requirements in the United States, while REACH restrictions on hazardous substances constrain chemical inputs for European producers. BIS certification mandates in India and GB standards in China create divergent compliance pathways that fragment supplier qualification protocols. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized formulation adaptation or unified global product platforms offer superior capital efficiency.
Market Dynamics
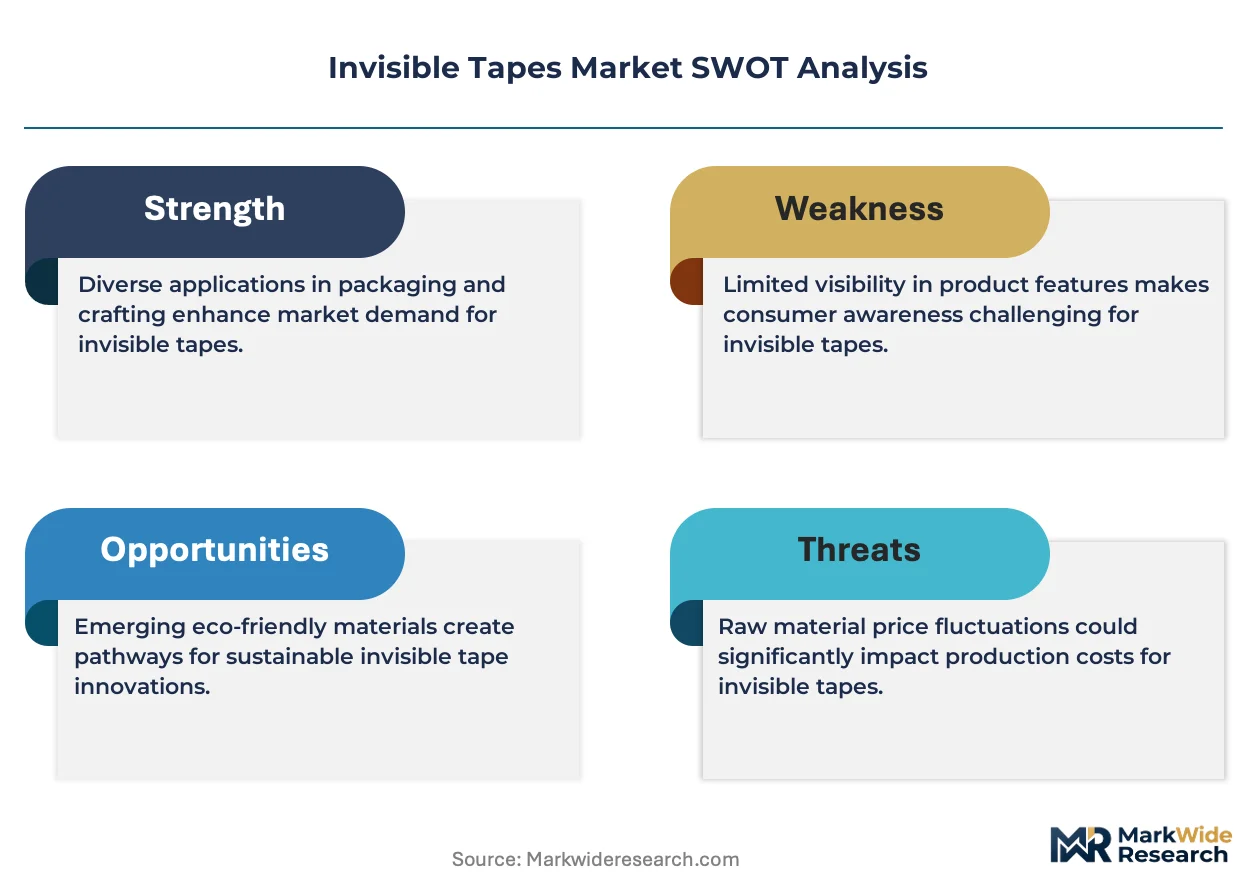
REACH compliance in Europe and EPA guidelines in the United States are forcing solvent-based adhesive producers to retool formulations toward waterborne acrylic emulsions, reshaping raw material procurement and capital allocation across the invisible tapes value chain.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on hazardous substance reduction are accelerating migration to bio-based tackifiers, creating first-mover advantages for compliant suppliers in Germany and France.
- Crafting segment expansion:Hobbyist communities in Japan and South Korea are driving demand for precision-cut invisible tapes in scrapbooking and paper art applications.
- Double-sided bonding technology:Hidden fastening requirements in luxury cosmetics packaging are pulling premium acrylic formulations into point-of-sale display manufacturing.
Market Restraints
- Petrochemical input volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing margin stability for film extrusion specialists in the United States and Germany.
- Asian supply concentration:Biaxially oriented film capacity clusters in China and South Korea, exposing buyers to shipping cost spikes and tariff uncertainty.
- Hot-melt substitution threat:EVA-based adhesives in corrugated sealing applications are displacing solvent-free acrylics in industrial packaging segments.
Strategic Opportunities
- Indian BIS certification pathway:Domestic manufacturing incentives under PLI schemes are opening localized production opportunities for foreign tape converters targeting South Asian e-commerce packaging.
- Medical device bonding:Skin-contact invisible tapes for wearable sensor fixation represent an emerging application with distinct regulatory and margin profiles.
- Direct-to-crafter channels:Subscription box services and maker-space partnerships are bypassing traditional stationery distributors in North American consumer segments.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise in solvent-free emulsion polymerization is concentrated among aging technical workforces in Japan and Germany.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and BIS compliance testing extends product launch cycles by 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Invisible Tapes Market |
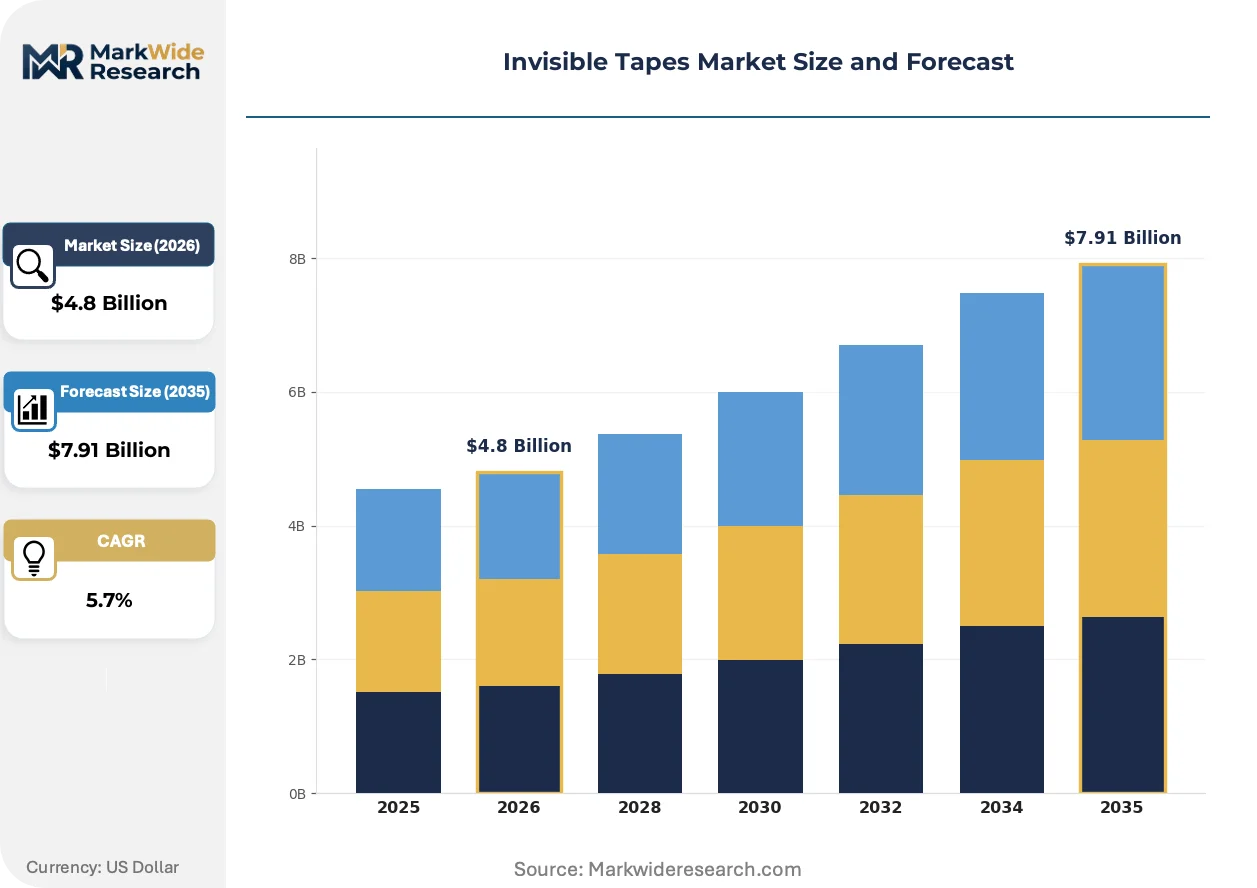
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Transparent, Invisible, Permanent Material: Polyester, Acrylic, Polypropylene, Paper Application: Office Use, Crafting, Packaging, Home Repair End User: Retail, Educational, Industrial, Personal |
| Companies Covered | 3M, Sicad Group, ADH Tape, S-Chem International, ShurTech Brands, Maxingvest, Corely Belgium SPRL, Bolex(Shenzhen) Adhesive Products, Mexim Adhesive Tapes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Invisible Tapes Market Shifts & Advancements
Coating line automation and digital print integration are compressing batch sizes and accelerating SKU proliferation, forcing manufacturers to choose between flexible asset footprints and scale economics in film extrusion.
Ultraviolet-curable adhesive deposition is automating precision coating control on polypropylene films, enabling micron-level thickness consistency that manual roller systems cannot achieve. Japanese packaging converters are adopting these lines fastest, driven by cosmetic brand specifications for optical clarity. The technology is automating quality assurance and reducing material waste in high-margin display applications.
EPA volatile organic compound emission standards are tightening solvent content thresholds in adhesive manufacturing, compelling U.S. producers to invest in waterborne emulsion reactors and thermal oxidizers. Industrial tape facilities in Ohio and Texas face the steepest retrofit costs. The regulation is segmenting the supplier base between compliant capital-intensive operators and regional players exiting industrial grades.
Crafter and small-business buyers are consolidating purchases through specialized e-commerce platforms that aggregate specialty tape SKUs with complementary materials. Traditional office supply distributors in Germany and the United States are losing share to these curated marketplaces. The shift is most pronounced among Etsy sellers and boutique packaging designers seeking aesthetic-grade finishes unavailable in big-box retail.
Invisible Tapes Market Segmentation
Invisible tapes fragment across four dimensions that reshape procurement priorities. Product architecture determines optical performance thresholds, while material selection locks in regulatory compliance pathways and cost structures.
Product Type:
Buyers differentiate by permanence requirements and visual discretion needs rather than price sensitivity alone.
- Transparent:Biaxially oriented polypropylene films coated with solvent-free acrylic emulsions deliver universal substrate compatibility. Document repair and gift wrapping applications in Germany and Japan concentrate procurement, driven by premium stationery retailer specifications for residue-free removal.
- Double-Sided:Pressure-sensitive adhesive layers on both faces enable hidden fastening in display assembly and luxury packaging. Point-of-sale manufacturing in the United States pulls premium formulations as cosmetic brands mandate invisible bonding for shelf aesthetics.
- Invisible:Engineered for near-zero visual detection on white paper stocks through refractive index matching. Archival document restoration and legal filing systems in France specify these grades.
- Permanent:High-shear acrylic chemistry withstands temperature cycling in industrial fixture mounting. Automotive interior assembly in Japan adopts these for trim bonding.
Volume sits with Transparent; growth tilts toward Double-Sided.
Material:
Raw material selection constrains which regulatory certifications converters can achieve and which end-use margins become accessible.
- Polypropylene:Dominant film substrate offering tear resistance and moisture barrier properties at cost-efficient extrusion economics. Office supply distributors in the United States standardize on this material for high-volume SKUs.
- Acrylic:Waterborne emulsion adhesives meeting EPA volatile organic compound thresholds in Ohio and Texas manufacturing facilities. REACH-compliant European producers favor these formulations for hazardous substance reduction mandates.
- Polyester:Dimensionally stable films for precision die-cutting in electronics and medical device bonding. South Korean display manufacturers specify polyester carriers for cleanroom assembly.
- Paper:Repulpable backing for corrugated packaging sealing and temporary carton closure. E-commerce fulfillment centers in India adopt paper-based tapes under BIS certification pathways aligned with domestic manufacturing incentives.
Polypropylene captures shipment tonnage; acrylic formulations are climbing the fastest on regulatory tailwinds.
Application:
End-use context dictates performance specifications more sharply than buyer type or channel.
- Office Use:Document mending and presentation assembly requiring clean aesthetic finishes. Corporate procurement contracts in Germany and Japan specify optical clarity grades for professional environments.
- Crafting:Precision-cut tapes for scrapbooking and paper art applications. Hobbyist communities in Japan and South Korea drive demand for archival-safe adhesives with acid-free certification.
- Packaging:Carton sealing and temporary product fixation across retail and industrial logistics. Amazon fulfillment networks standardize on invisible variants for customer-facing unboxing experiences.
- Home Repair:General-purpose bonding for household fixture mounting and temporary repairs. Big-box retail channels in the United States move volume through multi-roll value packs.
Office Use holds established volume; crafting exhibits the steepest expansion trajectory as maker communities professionalize.
End User:
Procurement sophistication separates institutional buyers from consumer segments more than order size alone.
- Retail:Stationery chains and specialty packaging suppliers curating aesthetic-grade finishes. Curated e-commerce marketplaces in Germany and the United States bypass traditional distributors for boutique packaging designers.
- Educational:School districts and university procurement offices standardizing on bulk invisible tape contracts. Budget constraints favor transparent polypropylene grades over premium alternatives.
- Industrial:Manufacturing facilities requiring shear strength and temperature resistance for process automation. Automotive and electronics assembly in Japan specifies permanent acrylic formulations.
- Personal:Individual consumers purchasing through convenience retail and subscription craft boxes. Direct-to-crafter channels in North America aggregate specialty SKUs with complementary materials.
Retail commands margin concentration; industrial procurement is gaining share fastest on hidden fastening requirements in premium packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and bonded warehousing clusters near Rotterdam accelerate invisible tape conversion and distribution. These tax-advantaged nodes concentrate film slitting and adhesive coating capacity for export-oriented supply chains serving premium stationery and cosmetics packaging segments.
United States
Corporate procurement contracts for office supplies and Amazon fulfillment network specifications for customer-facing packaging drive volume. EPA volatile organic compound emission standards compel Ohio and Texas manufacturing facilities to install thermal oxidizers and waterborne emulsion reactors. Cleveland-area converters specialize in high-shear acrylic formulations for automotive interior assembly.
Germany
Premium stationery retailer chains and luxury cosmetics packaging houses specify optical clarity grades for professional and shelf-aesthetic applications. REACH restrictions on hazardous substances mandate bio-based tackifier migration, creating first-mover advantages for compliant suppliers in Baden-Württemberg. Stuttgart industrial clusters host specialized acrylic formulation expertise for archival-grade invisible bonding.
Japan
Hobbyist communities in Tokyo and Osaka drive precision-cut tape demand for scrapbooking and paper art applications. METI industrial standards shape adhesive performance specifications for electronics and display manufacturing. Nagoya automotive assembly plants adopt permanent acrylic formulations for interior trim bonding under cleanroom conditions.
China
E-commerce packaging volume and cosmetics export manufacturing pull film extrusion and coating capacity. GB standards and MIIT regulations create divergent compliance pathways from Western markets. Shenzhen Free Trade Zone concentrates biaxially oriented polypropylene film production for regional supply to South Korean display manufacturers.
India
Domestic e-commerce fulfillment expansion and corrugated packaging growth create procurement scale. BIS certification mandates and PLI manufacturing incentives open localized production opportunities for foreign tape converters. Maharashtra industrial corridors near Mumbai attract slitting and distribution investments targeting South Asian consumer markets.
Invisible Tapes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and channel access dimensions. The supplier base segments into three tiers: multinational adhesive science leaders with polymer heritage, regional European converters with REACH-compliant specialized formulations, and Asian-scale film extrusion operations serving cost-sensitive industrial grades. Competitive positioning hardens through M&A consolidation of coating line capacity and strategic partnerships with cosmetics brands for specification lock-in.
Among diversified science conglomerates, 3M occupies a position exemplifying premium-tier formulation heritage across office and industrial channels. Sicad Group and ShurTech Brands represent contrasting regional archetypes: the former anchors European specialized acrylic supply while the latter exemplifies North American brand-recognition and channel-density positioning in consumer segments.
| Leading Market Players |
|---|
| 3M |
| Sicad Group |
| ADH Tape |
| S-Chem International |
| ShurTech Brands |
| Maxingvest |
| Corely Belgium SPRL |
| Bolex(Shenzhen) Adhesive Products |
| Mexim Adhesive Tapes |
| Others |
Supply & Pricing Matrix
EPA volatile organic compound emission standards gate both qualified supply and premium-tier pricing access, forcing Ohio and Texas converters to install thermal oxidizers and waterborne emulsion reactors while compliant German and Japanese producers capture margin premiums on REACH and METI-certified grades.
Pricing Analysis
Cost-down pressure on standard polypropylene grades accelerates because Asian film extrusion capacity expansion compresses benchmark resin economics. Three-tier pricing structure across premium, standard, and economy levels separates optical clarity certifications from basic document repair SKUs. Price differentiation hinges on REACH compliance status and shear strength performance tier. Corporate procurement offices in Germany exhibit lowest price sensitivity; Indian e-commerce fulfillment buyers drive hardest volume negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cosmetic packaging demand while specialty distributors serve fragmented crafter segments. Biaxially oriented polypropylene film capacity concentrates in China, South Korea, and Japan. Raw material procurement draws from petrochemical resin feedstocks, solvent-free acrylic emulsions, and release liner substrates. Single-source vulnerability in South Korean display-grade polyester supply exposes converters to shipping chokepoint risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Invisible tape manufacturing is consolidating around REACH-compliant formulation expertise as multi-jurisdiction certification timelines force subscale European and North American converters toward exit or acquisition.
For Market Incumbents: Extend coating line automation investments to compress batch economics against emerging Asian-scale competitors. Acquire specialized acrylic formulation capabilities in Baden-Württemberg or Stuttgart industrial clusters before adhesive chemist scarcity worsens. Secure long-term offtake agreements with luxury cosmetics brands to lock in specification-driven pricing power. For New Entrants and Emerging Players: Curated e-commerce marketplaces serving Etsy sellers and boutique packaging designers represent the most penetrable channel white-space. Target Indian BIS certification pathways under PLI manufacturing incentives to establish localized slitting and distribution capacity. Lead with archival-safe acid-free grades to differentiate from commodity office supply incumbents. For Investors and Strategic Acquirers: Japanese automotive interior assembly adoption of permanent acrylic formulations is the leading indicator that high-shear industrial grades will command sustained margin premiums. Acquisition target archetype: REACH-compliant European converters with specialized coating lines and aging technical workforces seeking succession liquidity. Watch for EPA enforcement actions against non-compliant Ohio and Texas facilities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Captures formulation margin and ensures EPA compliance for Ohio manufacturing facilities. |
| REACH-Compliant Coating Line Expansion | Locks in premium access to German luxury cosmetics packaging specifications. |
| Direct-to-Crafter Channel Launch | Bypasses traditional stationery distributors losing share to curated e-commerce marketplaces. |
| Indian BIS Certification Investment | Opens PLI-aligned localized production for South Asian e-commerce packaging growth. |
| Medical Device Bonding Partnership | Positions for wearable sensor fixation applications with distinct regulatory and margin profiles. |
Research Methodology
Document review covered customs and trade flow databases, adhesive chemistry patent filings, and regulatory compliance registries, complemented by interviews with coating line operations managers, procurement leads at cosmetics packaging houses, specialty tape distributors, and technical R&D directors at acrylic formulation specialists. Secondary validation drew from EPA enforcement records, ECHA substance restriction updates, METI industrial standard publications, and BIS certification directories. Bottom-up capacity modeling and top-down demand estimation were triangulated against channel inventory data.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by product architecture, material chemistry, end-use application, and procurement sophistication tier. CAGRs were derived from regression analysis of historical price-volume relationships and forward scenario weighting. Industry-specific forecast inputs included polypropylene resin price volatility indices and cosmetics packaging SKU proliferation rates.
Caveats apply where petrochemical feedstock shocks, tariff reconfigurations on Asian film imports, or accelerated hot-melt adhesive substitution could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Breathable Tape Market
Tapes
Carry Handle Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Application Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
Mastic Tapes Market
Tapes
Pucker Free Tapes Market
Tapes
Replica Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Silicone Tape Market
Tapes
Aerospace Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Release Tape Market