
 Thermal Release Tapes Market | 2026-2036
Thermal Release Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Release Tapes Market Analytics
Electronics original equipment manufacturers is collapsing as the dominant buyer archetype as automotive tier-one suppliers accelerate thermal management tape procurement for battery module assembly. Sekisui Chemical leverages its polyimide film expertise to anchor high-temperature bonding applications in East Asian semiconductor fabs. Tesa SE sustains European automotive qualification pipelines through ISO-certified cleanroom production. 3M Company dominates North American aerospace masking segments with fluoropolymer-adhesive thermal release formulations.
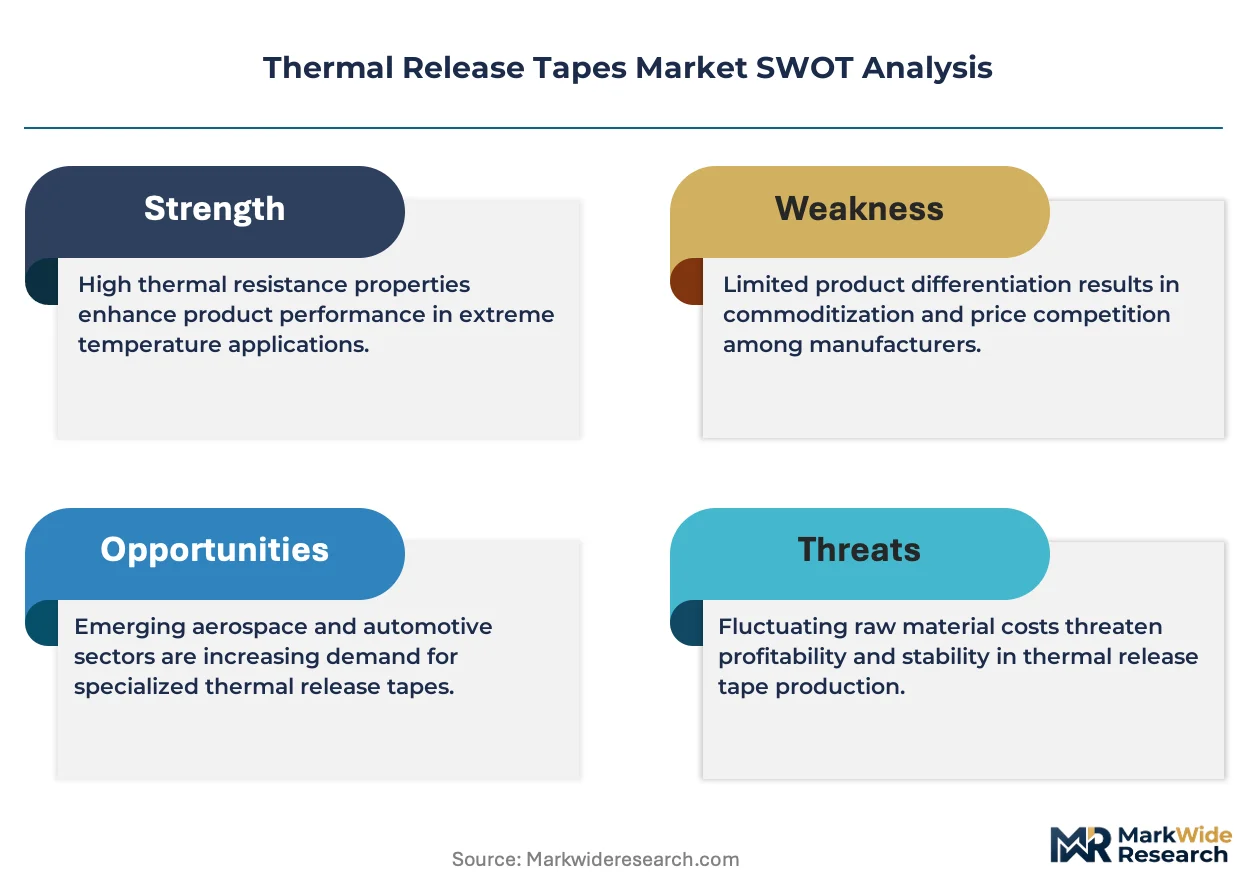
Thermal release tapes are pressure-sensitive adhesive constructions engineered to debond cleanly at controlled temperature thresholds, typically incorporating silicone or acrylic chemistries on polyimide or polyester backings rated between 150°C and 300°C peel-release windows; they serve primarily as temporary fixation media in precision manufacturing where mechanical removal risks substrate damage. Polyimide-based configurations lead value contribution due to their compatibility with lead-free solder reflow profiles, while silicone adhesive systems capture fastest growth in electric vehicle battery pack assembly where thermal cycling tolerance determines specification. Surface protection applications occupy the largest volume share across electronics fabrication, though bonding segments concentrate margin pools through qualification-locked supply agreements.
EPA oversees volatile organic compound limits in adhesive formulations affecting U.S. manufacturing compliance costs, while REACH restricts substance of very high concern in European tape chemistries, and China's GB standards mandate halogen-free backings for domestic electronics procurement. These regulatory frameworks elevate R&D expenditure for reformulation but simultaneously create specification barriers that favor incumbent suppliers with established certification portfolios. Stakeholders must monitor evolving battery thermal runaway testing protocols as automotive safety regulators integrate adhesive performance into cell-to-pack validation requirements.
Market Dynamics
Automotive battery thermal management specifications are displacing semiconductor packaging as the primary demand vector, forcing adhesive reformulation cycles and qualification pipeline reallocation across supplier R&D budgets.
Growth Catalysts
- Cell-to-pack battery architectures:Electric vehicle manufacturers specify silicone-based thermal release tapes for module bonding. These materials accommodate thermal cycling stresses across charge-discharge profiles.
- REACH SVHC restrictions:European adhesive formulators accelerate halogen-free chemistry development. Compliance creates specification barriers favoring certified incumbents.
- Lead-free solder reflow compatibility:Polyimide backing materials rated above 260°C peel-release thresholds enable semiconductor packaging automation. East Asian fabrication capacity expansion drives procurement.
Market Restraints
- Specialized monomer supply concentration:Silicone adhesive precursors depend on limited petrochemical feedstock channels. Price volatility transmits directly to tape manufacturing cost structures.
- Qualification-locked supply agreements:Aerospace and automotive OEMs mandate multi-year validation protocols. New entrants face 18-36 month certification timelines before revenue realization.
- Mechanical fastening substitution:Laser welding and friction-stir joining techniques advance in battery pack assembly. These processes eliminate consumable adhesive requirements entirely.
Strategic Opportunities
- Solid-state battery commercialization:Next-generation cell architectures require thermal runaway containment interfaces. Adhesive suppliers can co-develop bonding specifications with cell manufacturers.
- India electronics manufacturing incentives:PLI scheme subsidies attract semiconductor packaging investments. Domestic tape qualification creates first-mover positioning for compliant suppliers.
- AI-enabled predictive maintenance:Smart manufacturing platforms integrate tape performance monitoring. Data-driven specification optimization opens software-adjacent revenue streams.
Industry Challenges
- Cross-functional materials engineering talent:Formulation chemists with simultaneous polymer science and thermal management expertise command premium compensation. Talent scarcity constrains R&D velocity.
- Multi-jurisdiction certification synchronization:Automotive suppliers must maintain parallel EPA, ECHA, and GB standard compliance. Documentation overhead consumes technical resources without product differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Release Tapes Market |
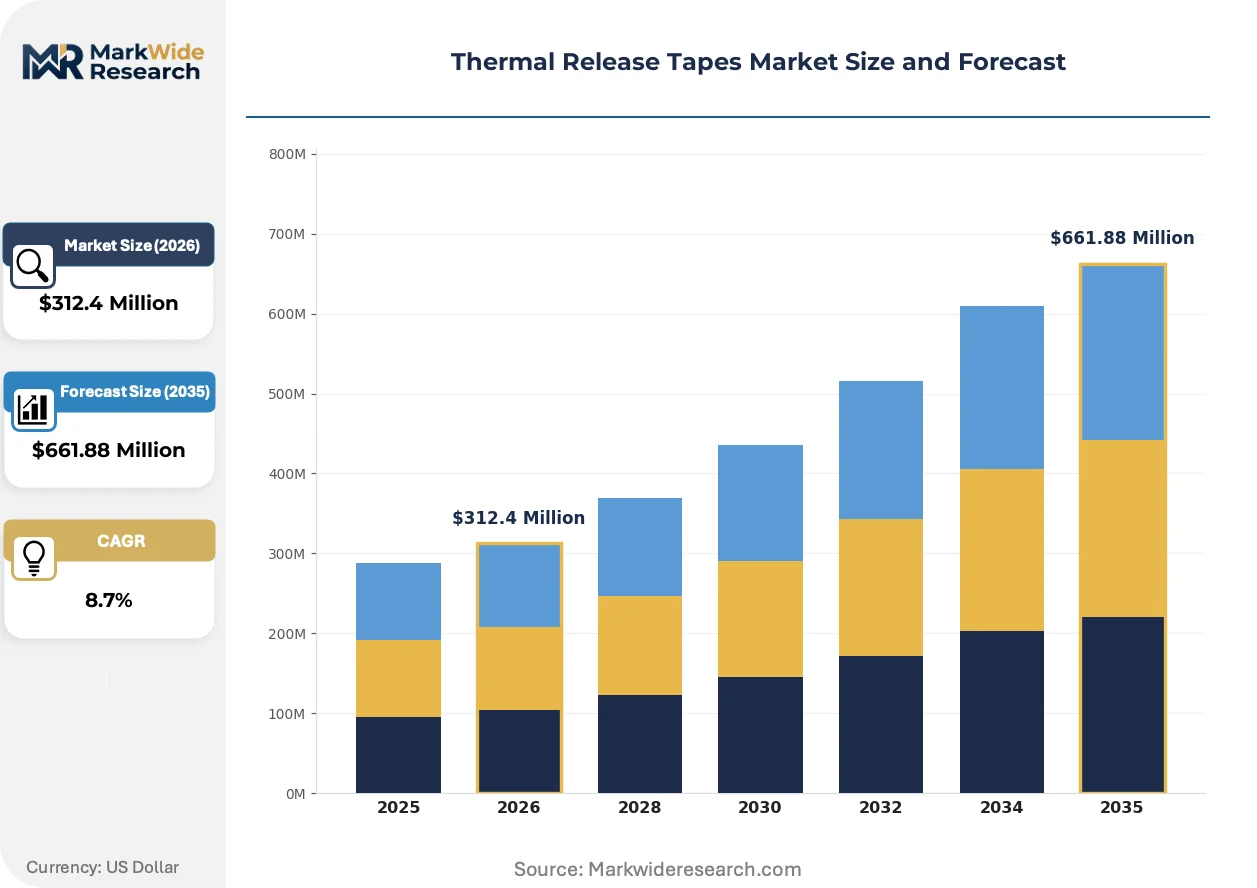
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyimide, Polyester, Silicone, PVC End User: Automotive, Electronics, Aerospace, Medical Application: Surface Protection, Bonding, Masking, Insulation Color: Clear, Black, Blue, Green |
| Companies Covered | Sekisui Chemical Co., Ltd., Tesa SE, Avery Dennison Corporation, 3M Company, Lintec Corporation, Nitto Denko Corporation, Scapa Group plc, Shurtape Technologies, LLC, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Release Tapes Market Evolving Landscape
Bio-based adhesive precursors and precision temperature-threshold engineering are converging to redefine competitive positioning. Suppliers race to align material science capabilities with tightening regulatory parameters across manufacturing geographies.
Silicone-acrylic hybrid adhesive systems are fragmenting established product categories. These formulations combine thermal cycling tolerance with controlled debonding precision. Battery module assemblers in Germany and South Korea specify hybrids for cell-to-pack interfaces. The technology is fragmenting procurement patterns previously dominated by pure silicone or pure acrylic alternatives.
EPA volatile organic compound limits are tightening adhesive manufacturing emissions standards. Formulators must invest in solvent recovery systems or water-based chemistry migration. U.S.-based electronics fabrication facilities face compliance cost elevation that disadvantages smaller tape converters without captive environmental engineering capacity.
Automotive tier-one suppliers now mandate tape performance data integration into digital twin simulations. Buyers require predictive debonding behavior models rather than static specification sheets. This specification shift concentrates procurement authority with adhesive suppliers possessing computational materials science capabilities, particularly visible in Japanese and German automotive supply chains.
Thermal Release Tapes Market Segmentation
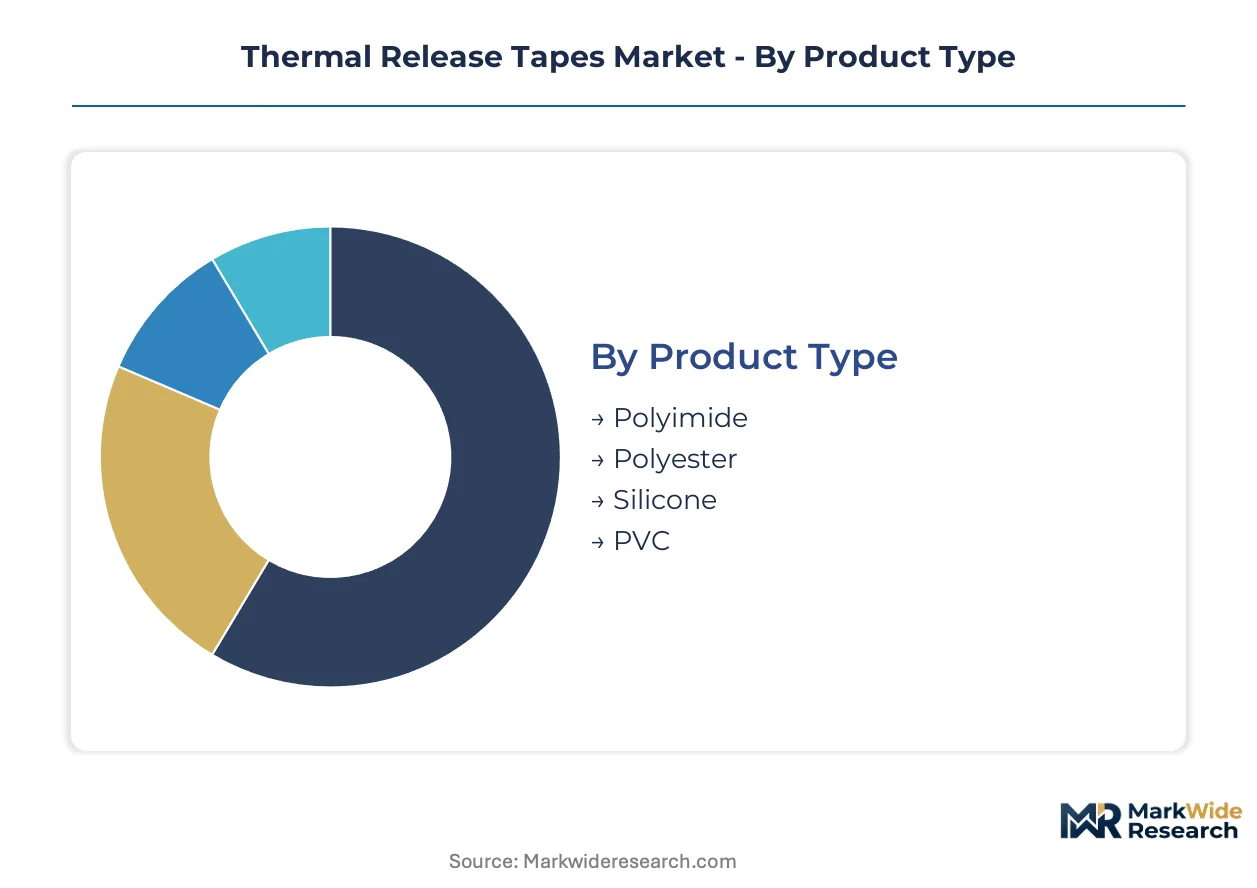
Thermal release tapes serve heterogeneous manufacturing workflows where substrate compatibility and thermal thresholds determine specification. Segmentation reveals how automotive electrification and semiconductor packaging reshape procurement priorities across material categories.
Product Type:
Mechanical fastening substitution pressures vary sharply by backing chemistry, with silicone formulations most exposed to laser welding displacement in battery assembly while polyimide maintains irreplaceability in reflow soldering.
- Polyimide:Aromatic polymer backings rated above 260°C enable lead-free solder reflow compatibility in semiconductor packaging. East Asian fabrication capacity expansion in Taiwan and South Korea drives procurement concentration for flip-chip and wafer-level applications.
- Silicone:Elastomeric adhesive systems deliver thermal cycling tolerance across electric vehicle charge-discharge profiles. German and South Korean battery module assemblers specify silicone for cell-to-pack interfaces where mechanical removal risks cell damage.
- Polyester:Lower-cost thermoplastic backings serve general surface protection in consumer electronics assembly. China's domestic electronics procurement favors polyester for mid-tier display laminations.
- PVC:Chlorinated polymer constructions offer chemical resistance in industrial masking applications. Regulatory pressure from REACH SVHC restrictions and China's GB halogen-free mandates constrains specification growth.
Polyimide anchors the volume base while silicone gains share at the steepest rate.
End User:
Customer procurement authority concentrates with automotive tier-one suppliers as battery thermal management specifications displace electronics OEMs in R&D pipeline allocation.
- Automotive:Cell-to-pack architectures specify thermal release tapes for module bonding and thermal runaway containment interfaces. European and South Korean battery manufacturers mandate predictive debonding models in digital twin simulations.
- Electronics:Semiconductor packaging and display assembly automation require clean debonding at controlled temperature thresholds. Japanese and Taiwanese fabrication facilities prioritize polyimide-based configurations for lead-free reflow compatibility.
- Aerospace:Fluoropolymer-adhesive formulations serve precision masking in composite curing and surface preparation. U.S. and French aerospace OEMs enforce multi-year qualification protocols that lock supply agreements.
- Medical:Biocompatible adhesive systems enable temporary fixation in device assembly and sterilization processes. FDA and EMA regulatory pathways extend certification timelines for tape converters.
Electronics maintains procurement volume leadership while automotive climbs the fastest as electrification accelerates.
Application:
Margin distribution inverts between volume-heavy protection segments and qualification-locked bonding specifications where supply agreements concentrate profitability.
- Surface Protection:Temporary coverage during fabrication, shipping, and assembly occupies the largest volume share across electronics manufacturing. Chinese display panel producers specify clear and blue variants for scratch prevention.
- Bonding:Structural adhesion with controlled thermal debonding captures margin concentration through automotive and aerospace qualification requirements. German automotive suppliers integrate tape performance data into battery pack digital twins.
- Masking:Precision coverage for selective coating, plating, and chemical processing serves aerospace and industrial applications. Japanese automotive paint shops specify green variants for visual verification.
- Insulation:Dielectric separation in high-temperature electrical assemblies supports motor and transformer manufacturing. Indian electronics manufacturing incentives under PLI schemes expand domestic insulation tape procurement.
Surface protection dominates shipment volumes while bonding expands most quickly on electrification demand.
Color:
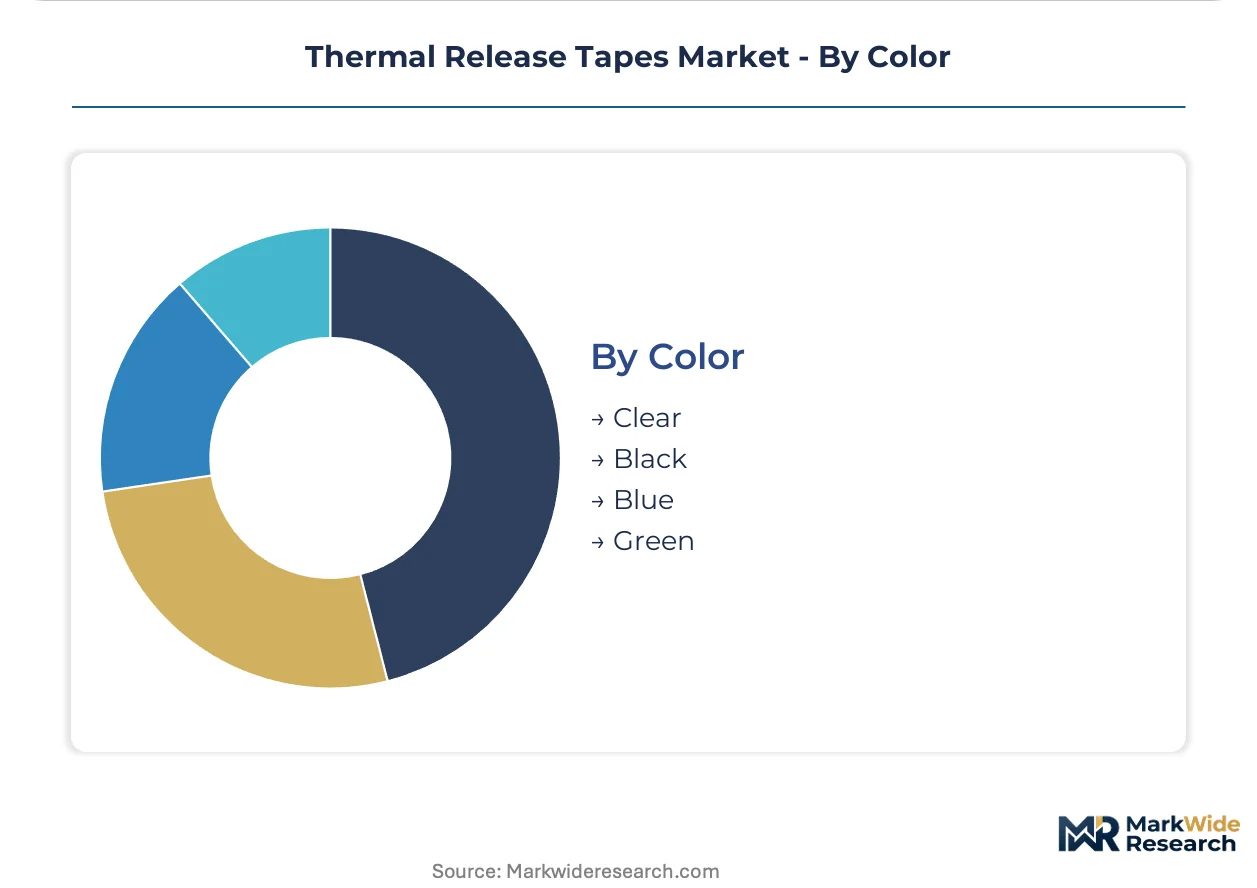
Functional differentiation through color coding supports manufacturing traceability and process verification workflows across automated assembly lines.
- Clear:Unpigmented constructions enable visual inspection of underlying substrates during surface protection and bonding operations. Semiconductor packaging facilities in Taiwan and South Korea prefer clear variants for optical alignment verification.
- Black:Carbon-loaded formulations provide light-blocking and aesthetic uniformity in consumer electronics assembly. Chinese smartphone manufacturers specify black masking tapes for display bezel applications.
- Blue:High-visibility pigmentation supports process control in automated dispensing and placement systems. U.S. electronics fabrication facilities use blue variants for temporary fixation during PCB assembly.
- Green:Distinctive hue enables rapid identification in multi-step masking and surface preparation sequences. European automotive paint shops specify green for primer and clearcoat separation.
Clear variants anchor the volume base while black gains share fastest on consumer electronics aesthetic requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean thermal release tape exports flow primarily into Chinese semiconductor packaging facilities and German automotive battery assembly plants, establishing East Asia-to-East Asia and East Asia-to-Europe as the dominant trade corridors.
China
Domestic electronics fabrication capacity expansion in Suzhou and Shenzhen drives procurement concentration for polyimide-based configurations. GB standards mandate halogen-free backings for domestic electronics procurement, elevating compliance costs for imported alternatives. Yangtze River Delta clustering concentrates display panel and semiconductor packaging demand in Shanghai-Jiangsu corridor facilities.
Germany
Automotive tier-one suppliers in Stuttgart and Munich specify silicone-based thermal release tapes for cell-to-pack battery architectures. REACH SVHC restrictions accelerate halogen-free chemistry development among domestic formulators. Bavaria's automotive supply chain integrates tape performance data into battery pack digital twin simulations.
United States
Aerospace OEMs in Seattle and Wichita enforce multi-year qualification protocols for fluoropolymer-adhesive masking applications. EPA volatile organic compound limits tighten adhesive manufacturing emissions standards, elevating compliance costs for solvent-based production. Pacific Northwest electronics fabrication facilities face cost pressures from environmental engineering capacity requirements.
South Korea
Battery module assemblers in Ulsan and Gyeonggi-do specify silicone thermal release tapes for thermal cycling tolerance across charge-discharge profiles. MFDS alignment with international biocompatibility standards supports medical device tape qualification pipelines. Seoul Capital Area semiconductor fabs drive polyimide procurement for lead-free solder reflow compatibility.
Japan
Polyimide film expertise concentrated in Osaka and Tokyo anchors high-temperature bonding applications for East Asian semiconductor fabs. METI industrial policy supports advanced materials R&D in thermal management adhesives. Kansai region suppliers leverage computational materials science capabilities for automotive digital twin integration requirements.
Thermal Release Tapes Market Competitive Landscape
Listed leaders compete with private specialists across qualification-locked supply agreements, creating a tiered structure where public company scale advantages confront private firm customer intimacy. The vendor base concentrates among Japanese and German incumbents with established certification portfolios alongside North American diversified materials conglomerates. Three archetypes dominate: polyimide film specialists, silicone adhesive formulators, and diversified tape converters with cross-industry qualification pipelines. Competitive moves center on M&A for geographic expansion and strategic partnerships for solid-state battery co-development specifications.
Among Japanese chemical conglomerates, Sekisui Chemical Co., Ltd. and Nitto Denko Corporation exemplify the polyimide film specialist archetype, while Tesa SE represents the German automotive-qualified tier with ISO-certified cleanroom production capabilities. These three occupy positions where established certification portfolios create specification barriers against new market entrants facing 18-36 month validation timelines.
| Leading Market Players |
|---|
| Sekisui Chemical Co., Ltd. |
| Tesa SE |
| Avery Dennison Corporation |
| 3M Company |
| Lintec Corporation |
| Nitto Denko Corporation |
| Scapa Group plc |
| Shurtape Technologies, LLC |
| Lohmann GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month qualification timelines for automotive battery applications concentrate pricing power with certified incumbents while compressing margins for converters lacking captive silicone precursor supply. This lead-time asymmetry reinforces tiered procurement structures where polyimide specialists command premium positioning against polyester commodity alternatives.
Pricing Analysis
Current-generation silicone-acrylic hybrid formulations command substantial premiums over legacy pure-silicone and pure-acrylic alternatives, while next-generation bio-based precursors remain pre-commercial. Three-tier pricing structure across aerospace-qualified, automotive-certified, and general industrial levels segments buyers by validation burden rather than volume scale. Price differentiation centers on REACH SVHC compliance certification and thermal cycling test data depth. Pricing pressure stems from laser welding substitution in battery pack assembly, with German automotive suppliers most price-sensitive and U.S. aerospace OEMs least sensitive due to qualification-locked supply agreements.
Supply Chain Analysis
Japan and South Korea anchor polyimide film production for semiconductor packaging applications, while Germany and China concentrate silicone adhesive formulation for battery module assembly. Raw material flows draw from petrochemical feedstock channels for silicone precursors, aromatic polymer resins for polyimide backings, and halogen-free flame retardants for GB-compliant variants. Single-source vulnerability concentrates in specialized monomer supply for high-temperature silicone adhesives. Distribution runs through tier-one automotive suppliers and semiconductor fabrication equipment OEMs rather than direct OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where tape performance data integration into battery pack digital twins creates interoperability dependencies between adhesive suppliers and automotive simulation ecosystems.
For Market Incumbents: Shield qualification-locked revenue streams by accelerating halogen-free chemistry certification ahead of REACH SVHC expansion timelines. Deepen backward integration into silicone precursor supply to offset petrochemical feedstock volatility. Prioritize computational materials science capabilities for digital twin integration requirements from German and Japanese automotive supply chains. For New Entrants and Emerging Players: Automotive qualification fast-tracks for silicone-acrylic hybrid formulations offer the most penetrable entry vector, particularly for South Korean battery module assemblers seeking second-source suppliers. Target India's PLI-subsidized semiconductor packaging investments where domestic tape qualification creates first-mover positioning. Lead with water-based chemistry formulations to bypass EPA solvent recovery compliance barriers facing U.S.-based competitors. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because qualification-locked supply agreements create durable moats against commodity substitution. Acquisition targets should emphasize polyimide film specialists with established East Asian semiconductor fab relationships. The signal to watch is solid-state battery thermal runaway testing protocol finalization, which will trigger specification resets across cell-to-pack adhesive interfaces.| Strategic Initiative | Industry Significance |
|---|---|
| REACH SVHC-Compliant Chemistry Development | Halogen-free formulation investment locks out uncertified competitors from European automotive procurement. |
| Silicone Precursor Backward Integration | Captive petrochemical feedstock supply insulates margins against monomer price volatility. |
| Digital Twin Performance Data Integration | Predictive debonding models concentrate procurement authority with computationally capable suppliers. |
| Solid-State Battery Co-Development Partnership | Early specification influence in next-generation cell architectures creates long-term revenue visibility. |
| India PLI Scheme Domestic Qualification | First-mover positioning in subsidized semiconductor packaging capacity builds regional market share. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with adhesive formulation chemists, automotive tier-one supplier procurement leads, semiconductor fabrication equipment OEMs, and regulatory compliance officers at tape converters. Secondary validation drew from EPA emissions filings, ECHA SVHC candidate list updates, China's GB standard publications, and SEC 10-K disclosures from listed materials conglomerates. Bottom-up demand modeling across end-use segments triangulated against top-down supply capacity assessments.
Across the analysis window, the forecasting framework modeled volume and value trajectories by backing chemistry, adhesive system, end-use industry, application function, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Key inputs included battery electric vehicle production forecasts, semiconductor packaging capacity expansion timelines, and evolving thermal runaway testing protocol adoption curves.
Underlying assumptions cover sustained electrification investment, stable petrochemical feedstock availability, and gradual REACH SVHC list expansion, with deviation risk concentrated in laser welding substitution rates and solid-state battery commercialization timing. Recalibration cycles align with material shifts in automotive safety regulator testing protocols and major semiconductor fab capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Carry Handle Tape Market
Tapes
Wire Harness Tape Market
Tapes
Building and Construction Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Paper Tapes Market
Tapes
Carbon Tapes Market
Tapes
Galley Tapes Market
Tapes
Spacer Tapes Market
Tapes
Global Electrical Tapes Market
Tapes
Tape Dispenser Market
Tapes
Tape and Label Adhesives Market
Tapes
Heat Sealing Tape Market
Tapes
Raffia Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Hand Wrappers Market
Tapes
Coding Foils and Tapes Market