
 Flocking Tape Market | 2026-2036
Flocking Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Flocking Tape Market Foresight
Specialty adhesive distribution is rewriting access patterns for flocking tape procurement. 3M leverages its direct-to-OEM channel infrastructure to sustain volume commitments with transportation suppliers in North America. Henkel AG & Co. KGaA anchors European demand through localized compounding facilities that shorten lead times for textile producers. H.B. Fuller Company competes in Asia-Pacific via technical service teams embedded with electronics manufacturers.
Flocking tape consists of a pressure-sensitive adhesive substrate coated with electrostatically applied textile fibers, typically nylon or polyester, creating a velvet-like surface with thickness tolerances between 0.5 mm and 2.0 mm. The primary industrial purpose is to deliver anti-rattle, anti-squeak, and aesthetic finishing functions in assemblies where metal-to-metal or metal-to-plastic contact occurs. Double-sided flocking tape commands the largest revenue pool due to its ubiquity in automotive door seal applications, while heat-resistant variants represent the fastest-expanding category as electric vehicle battery compartment specifications harden. Transfer flocking tape occupies a narrower but higher-margin niche among electronics manufacturers seeking ultra-thin profile damping solutions.
EPA oversees volatile organic compound limits in adhesive formulations across the United States, pushing manufacturers toward solvent-free chemistries. EMA and REACH jointly determine substance authorization requirements for rubber and silicone adhesives entering European medical and automotive supply chains. The EU Green Deal's chemical footprint protocols are tightening disclosure obligations for textile fiber sourcing. Stakeholders must monitor how cascading regulatory deadlines for perfluorinated substance restrictions reshape raw material qualification timelines and supplier certification burdens.
Market Dynamics
Automotive electrification is compressing specification cycles for interior NVH materials as OEMs redesign door seals, battery compartments, and trim assemblies around thermal management and acoustic performance requirements simultaneously.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving candidate list for SVHCs is disqualifying legacy adhesive chemistries, creating replacement demand for compliant flocking tape formulations in German automotive supply chains.
- Electric vehicle battery compartments:Heat-resistant flocking tape specifications are hardening as cell-to-pack architectures proliferate, pulling specialized damping materials into thermal barrier applications.
- Electronics miniaturization:Transfer flocking tape adoption is accelerating among smartphone and wearable manufacturers seeking sub-millimeter profile solutions for component isolation.
Market Restraints
- Polyamide 6,6 price volatility:Nylon fiber input costs swing with adipic acid and caprolactam feedstock availability, compressing margin stability for tape converters.
- Adhesive supply concentration:Solvent-free acrylic and silicone pressure-sensitive adhesive production clusters in Germany and the United States, exposing buyers to single-source qualification risks.
- Perfluorinated substance phase-outs:PFAS restrictions under EU Green Deal protocols are forcing reformulation of release liners and processing aids with uncertain performance parity timelines.
Strategic Opportunities
- Medical device damping:ISO 10993 biocompatibility certification opens surgical instrument and diagnostic equipment applications where metal-on-plastic contact requires sterile, low-outgassing surface treatments.
- India automotive component exports:PLI scheme incentives for advanced automotive parts are drawing flocking tape converters to establish compounding partnerships near Chennai and Pune manufacturing clusters.
- Solvent-free UV-curable adhesives:Convergence of radiation-curing technology with electrostatic flocking equipment is enabling inline production with near-zero VOC emissions and shortened curing cycles.
Industry Challenges
- Electrostatic process engineering talent:Specialized technicians who calibrate fiber density and adhesive coat weight tolerances remain scarce in emerging manufacturing regions.
- Dual certification timelines:Simultaneous IATF 16949 automotive and ISO 13485 medical quality system audits extend supplier qualification periods by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flocking Tape Market |
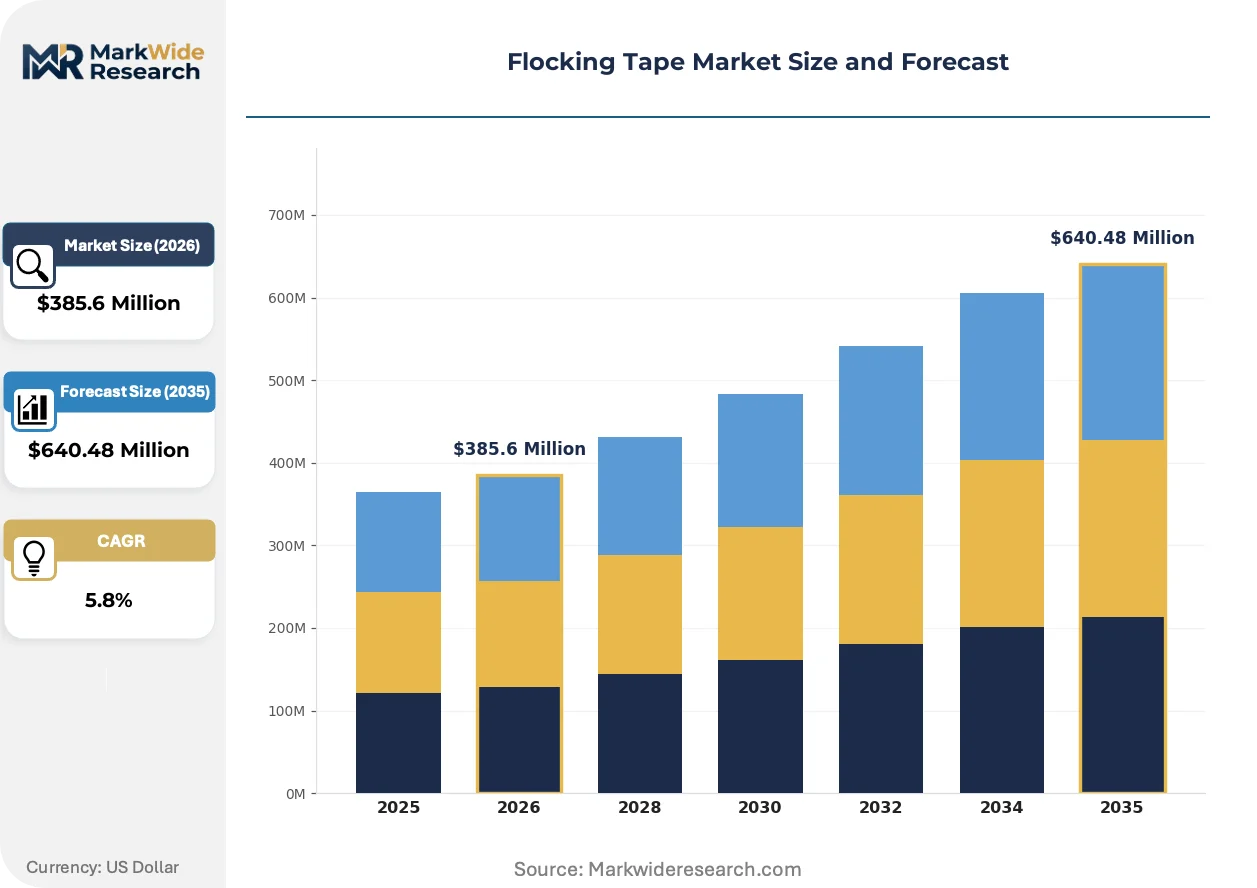
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-sided Flocking Tape, Single-sided Flocking Tape, Transfer Flocking Tape, Foam-backed Flocking Tape, Heat-resistant Flocking Tape Application: Automotive Trim, Consumer Electronics, Textile Finishing, Packaging Seals, Furniture Upholstery Material Type: Polyester Fiber, Nylon Fiber, Acrylic Adhesive, Rubber Adhesive, Silicone Adhesive End User Industry: Transportation Suppliers, Electronics Manufacturers, Textile Producers, Packaging Specialists, Furniture Artisans |
| Companies Covered | Industrias Tapla, Pro Tapes & Specialties, J.V. Converting Company, Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Stahl Holdings B.V., 3M, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flocking Tape Market Shifts & Advancements
Digital thread integration across material qualification and production traceability is compressing development cycles while hardening compliance documentation requirements for regulated end-uses.
Recycled-content nylon fiber is virtualizing raw material sourcing strategies as textile-to-textile chemical recycling achieves technical-grade purity for electrostatic flocking. Automotive seating and interior suppliers in Germany are piloting closed-loop fiber recovery from end-of-life vehicle components. This technology is virtualizing supply chain risk models by decoupling virgin petrochemical exposure from volume planning.
EPA Method 24 VOC testing protocols are tightening disclosure thresholds for adhesive formulations entering US automotive and electronics supply chains. Manufacturers must now submit complete compositional data for substances above 0.1% by mass. Medical device and aerospace tape applications face the steepest compliance burden as EPA alignment with California Air Resources Board standards spreads to other state jurisdictions.
Specification consolidation among tier-one automotive suppliers is displacing fragmented buyer networks with centralized global commodity management functions. Buyers now mandate pan-regional formulation consistency and single-source qualification across multiple assembly plants. This concentration is most visible in German and Japanese OEM supply chains where platform standardization strategies dominate component sourcing decisions.
Flocking Tape Market Segmentation
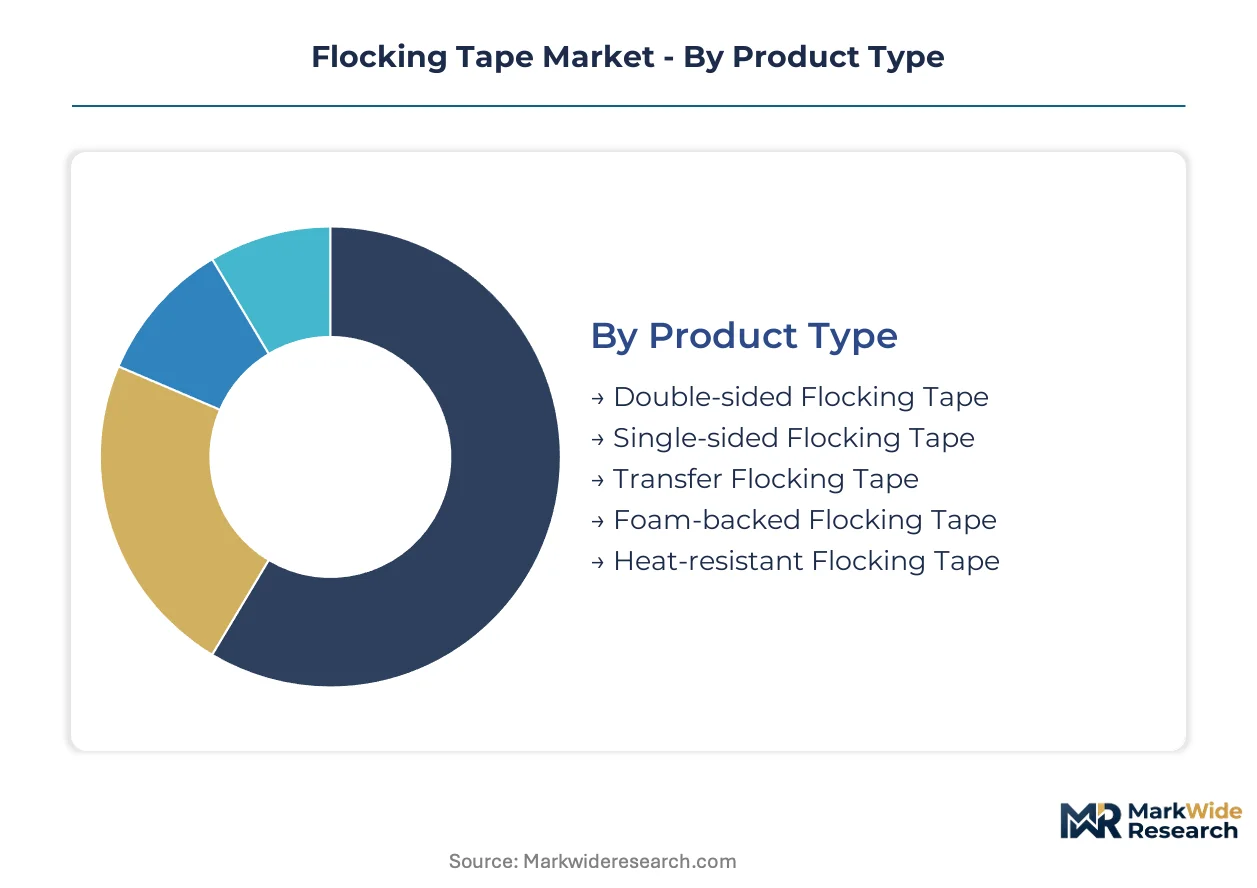
Flocking tape segmentation reveals distinct velocity profiles across product architectures. Specification cycles for automotive-grade variants compress faster than industrial grades, while material chemistry choices lock in multi-year qualification timelines with OEMs.
Product Type:
Cycle times vary dramatically—double-sided variants refresh specifications every 18-24 months alongside platform redesigns, whereas heat-resistant formulations endure 5-7 year validation windows for electric vehicle thermal applications.
- Double-sided Flocking Tape:Pressure-sensitive adhesive coats both faces with electrostatically bonded nylon or polyester fibers, creating sandwich structures for door seal assemblies. Transportation suppliers in Germany specify these for acoustic damping in premium vehicle platforms, though REACH SVHC restrictions are forcing adhesive reformulation cycles.
- Heat-resistant Flocking Tape:Silicone or acrylic adhesive matrices withstand sustained temperatures above 150°C, enabling battery compartment applications in electric vehicles. Cell-to-pack architectures are pulling these materials into thermal barrier specifications faster than qualification pipelines can absorb.
- Single-sided Flocking Tape:Velvet-fiber surface on one face with exposed adhesive backing serves furniture upholstery and textile finishing applications where one-sided aesthetic finishing suffices.
- Transfer Flocking Tape:Ultra-thin carrier-free construction delivers sub-millimeter profile damping for smartphone and wearable component isolation among electronics manufacturers.
- Foam-backed Flocking Tape:Compressible polyurethane or polyethylene foam core laminated with flocked surface provides gap-filling and rattle suppression in irregular automotive trim interfaces.
Double-sided flocking tape dominates installed base. Heat-resistant flocking tape is where expansion concentrates.
Application:
Cost tiers stratify sharply—automotive trim commands premium pricing for IATF 16949 certification, while packaging seals operate on commodity margins with minimal regulatory burden.
- Automotive Trim:Door seals, pillar garnishes, and interior trim assemblies utilize flocking tape for anti-rattle and acoustic finishing. OEM platform standardization strategies in Germany and Japan are consolidating specifications toward pan-regional formulations.
- Consumer Electronics:Smartphones, laptops, and wearables deploy transfer and single-sided variants for component isolation and tactile surface enhancement.
- Textile Finishing:Apparel and upholstery manufacturers apply flocking tape for decorative edging and seam reinforcement in high-visibility garments.
- Packaging Seals:Luxury goods and cosmetic packaging employ velvet-fiber surfaces for premium unboxing experiences with minimal technical specification overhead.
- Furniture Upholstery:Seating and panel manufacturers specify single-sided variants for edge binding and scratch protection in wood-to-metal contact points.
Automotive trim captures the highest margin pool. Consumer electronics represents the steepest expansion trajectory.
Material Type:
Supply concentration clusters geographically—polyamide feedstock for nylon fiber concentrates in Germany and the United States, while acrylic adhesive production anchors in Asian chemical manufacturing corridors.
- Nylon Fiber:Polyamide 6,6 electrostatically applied fibers deliver abrasion resistance and velvet texture for automotive and industrial applications. Adipic acid and caprolactam price volatility compress converter margins unpredictably.
- Silicone Adhesive:Heat-stable pressure-sensitive formulations serve electric vehicle battery compartments and medical device applications requiring biocompatibility certification.
- Polyester Fiber:Lower-cost polyethylene terephthalate fibers substitute for nylon in packaging and furniture applications where abrasion demands moderate.
- Acrylic Adhesive:Solvent-free and UV-curable variants dominate electronics and general industrial bonding with faster curing cycles than rubber alternatives.
- Rubber Adhesive:Natural and synthetic rubber formulations persist in legacy automotive specifications though losing share to acrylic and silicone chemistries under VOC regulations.
Nylon fiber anchors volume demand. Silicone adhesive is where specification value accumulates fastest.
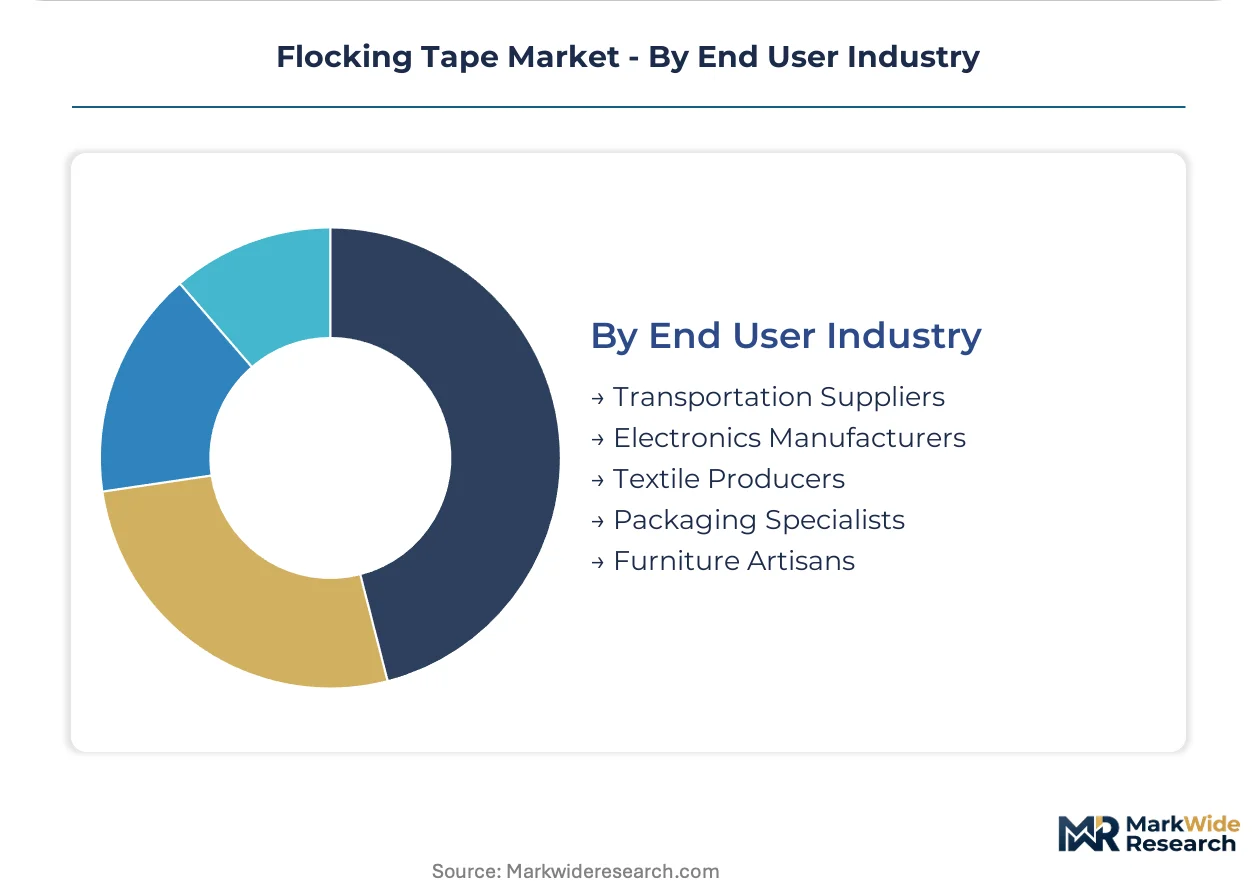
End User Industry:
Customer maturity varies—transportation suppliers maintain decade-long supplier relationships with embedded technical service, while furniture artisans purchase through distributor channels with minimal direct engagement.
- Transportation Suppliers:Tier-one and tier-two automotive component manufacturers specify flocking tape for door seals, trim assemblies, and battery compartment damping. Platform consolidation strategies are reducing qualified supplier pools.
- Electronics Manufacturers:Smartphone, laptop, and wearable OEMs drive miniaturization requirements for ultra-thin profile damping solutions with sub-millimeter tolerances.
- Textile Producers:Apparel and upholstery manufacturers integrate flocking tape into garment construction and decorative finishing workflows.
- Packaging Specialists:Luxury goods and cosmetic packaging converters specify velvet-fiber surfaces for premium positioning in consumer-facing applications.
- Furniture Artisans:Small-to-mid-scale seating and case goods manufacturers purchase through distribution for edge protection and aesthetic finishing.
Transportation suppliers command the deepest specification relationships. Electronics manufacturers are driving the fastest technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive specification power commands 15-20% pricing premiums over Indian export-grade material, while Chinese electronics demand pulls premium transfer tape volumes eastward at compressed margins.
Germany
Automotive OEM platform consolidation drives specification intensity for door seal and battery compartment applications. ECHA's REACH SVHC candidate list forces adhesive reformulation cycles every 18-24 months. Stuttgart and Wolfsburg component clusters anchor qualified supplier relationships with embedded technical service requirements.
United States
EPA Method 24 VOC disclosure thresholds tighten to 0.1% by mass for automotive and electronics supply chain entry. NHTSA safety standards intersect with state-level California Air Resources Board alignment spreading to Illinois and Michigan jurisdictions. Detroit and Southeast automotive corridors concentrate converter capacity near tier-one seating and trim suppliers.
China
Electric vehicle battery pack production scales pull heat-resistant flocking tape into thermal barrier specifications faster than qualification pipelines absorb. MIIT new energy vehicle mandates accelerate cell-to-pack architecture adoption. Shenzhen and Shanghai electronics manufacturing clusters drive sub-millimeter profile damping demand for smartphone and wearable component isolation.
India
PLI scheme incentives for advanced automotive components draw flocking tape converters toward Chennai and Pune manufacturing partnerships. BIS certification requirements extend qualification timelines for imported adhesive formulations. Tamil Nadu and Maharashtra automotive component export zones concentrate compounding facility investments from European and Japanese suppliers.
Japan
METI carbon neutrality roadmaps pressure automotive supply chains toward solvent-free adhesive chemistries with shortened curing cycles. JIS standard harmonization with IATF 16949 compresses dual-certification burdens for medical device crossover applications. Nagoya and Osaka industrial belts maintain decade-long supplier relationships with embedded process engineering talent.
Flocking Tape Market Competitive Landscape
Diversified adhesive conglomerates and specialized tape converters split the market along specification-depth versus volume-scale axes. Three archetypes dominate: integrated chemical-adhesive suppliers with direct OEM channel infrastructure, regional converters with localized compounding and technical service embedding, and niche specialists targeting medical or electronics certification tiers. Competitive moves concentrate on strategic partnerships for recycled-content fiber sourcing and capacity expansion near emerging automotive export zones.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify the integrated-adhesive-supplier archetype with direct channel infrastructure. 3M anchors the premium specification tier through embedded technical service relationships with transportation and electronics OEMs. Specialized converters including Industrias Tapla and Pro Tapes & Specialties occupy regional fabrication positions with flexibility on minimum order quantities and custom width slitting capabilities.
| Leading Market Players |
|---|
| Industrias Tapla |
| Pro Tapes & Specialties |
| J.V. Converting Company |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Stahl Holdings B.V. |
| 3M |
| Arkema |
| Others |
Supply & Pricing Matrix
Stuttgart automotive component clusters anchor European flocking tape capacity, where embedded technical service relationships and REACH compliance investments translate into 15-20% pricing premiums over export-grade material from emerging manufacturing regions. Buyers in German OEM supply chains absorb these premiums in exchange for pan-regional formulation consistency and single-source qualification across multiple assembly plants, while price-sensitive furniture and packaging segments gravitate toward standardized catalog offerings with minimal regulatory overhead.
Pricing Analysis
Configured-to-order pricing for IATF 16949-certified automotive grades commands substantial premiums over standard catalog widths, with three-tier pricing structure across premium, standard, and economy levels separating transfer tape for electronics from double-sided variants for door seals and commodity single-sided grades for furniture. Certification level and volume scale drive price differentiation, with automotive OEMs least sensitive to price and furniture artisans most responsive to per-meter fluctuations. Pricing pressure stems from polyamide 6,6 feedstock volatility, compressing converter margins unpredictably.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for European automotive suppliers sourcing heat-resistant silicone adhesive formulations. Nylon fiber production concentrates in Germany and the United States, while acrylic adhesive manufacturing clusters in Asian chemical corridors, creating single-source vulnerability for specialty pressure-sensitive formulations. Raw material dependencies on adipic acid, caprolactam, and silicone polymers tether converters to petrochemical feedstock cycles. Distribution runs through direct OEM channels for automotive volumes and distributor networks for fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
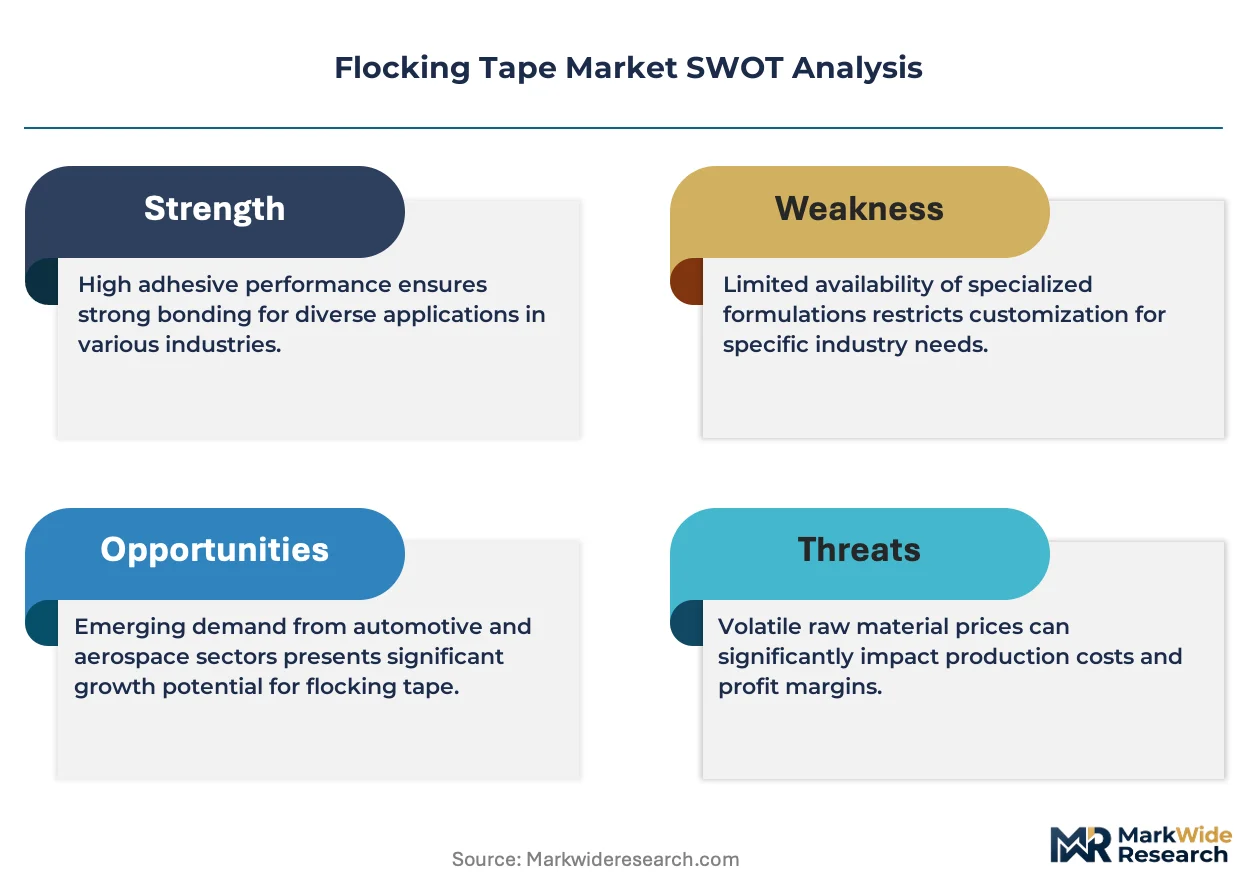
Incumbent flocking tape manufacturers face substitution pressure from molded-in velvet textures and laser-etched surface finishes that eliminate adhesive layers entirely, requiring active defense of specification relationships through embedded technical service and qualification pipeline control.
For Market Incumbents: Harden specification stickiness by embedding process engineering teams with Stuttgart and Wolfsburg automotive clusters, ensuring REACH reformulation cycles align with OEM platform redesigns. Deepen backward integration into solvent-free UV-curable adhesive production to capture margin from regulatory-driven chemistry shifts and defend against Asian chemical conglomerates with captive raw material positions.
For New Entrants and Emerging Players: Pursue medical device damping applications where ISO 10993 biocompatibility certification creates qualification barriers that favor specialized entrants over diversified adhesive suppliers. Chennai and Pune automotive export zones under India's PLI scheme offer the most penetrable geography, with local compounding partnerships as the essential go-to-market angle for European and Japanese OEM supplier qualification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional converters with localized compounding capabilities and embedded technical service relationships over pure-play fiber suppliers or undifferentiated adhesive distributors. Long-term viability hinges on recycled-content nylon fiber integration and closed-loop recovery partnerships with automotive seating suppliers. Watch cell-to-pack architecture penetration rates as the inflection signal for heat-resistant flocking tape demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Fiber Integration | Automotive OEMs in Germany pilot closed-loop recovery from end-of-life vehicle components, decoupling volume planning from virgin petrochemical exposure. |
| Solvent-Free UV-Curable Adhesive Capacity | Inline production with near-zero VOC emissions aligns with EPA Method 24 tightening and EU Green Deal chemical footprint protocols. |
| Medical Device Certification Investment | ISO 10993 biocompatibility opens surgical instrument and diagnostic equipment applications with sterile, low-outgassing requirements. |
| India Compounding Partnership Expansion | PLI scheme incentives near Chennai and Pune manufacturing clusters accelerate qualification timelines for automotive component exports. |
| Heat-Resistant Formulation Development | Silicone adhesive matrices above 150°C serve electric vehicle battery compartments as cell-to-pack architectures proliferate. |
Research Methodology
A standing panel of automotive platform engineers, adhesive procurement leads at Tier 1 suppliers, electrostatic flocking equipment technicians, and textile fiber sourcing managers provided ongoing calibration throughout the study period. Primary field engagement combined with secondary validation from customs and trade data, SEC 10-K filings, automotive production databases, and ECHA substance authorization records enabled bottom-up and top-down triangulation of volume and value estimates.
Scenario bracketing anchored the analytical framework, with projections developed across product architecture, application intensity, material chemistry, and regional manufacturing cluster dimensions throughout the forecast period. CAGRs derived from segment-level growth rate synthesis, with electric vehicle battery pack production scaling and electronics miniaturization trajectories as key demand-side inputs alongside regulatory deadline modeling for PFAS restrictions and VOC disclosure thresholds.
Sensitivities concentrate around polyamide feedstock price volatility, REACH SVHC list expansion timing, and electric vehicle architecture adoption curves beyond base-case assumptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Electrical Tapes Market
Tapes
Flatback Tapes Market
Tapes
Glue Tape Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Strapping Tapes Market
Tapes
Acetate Cloth Tape Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Adhesive Transfer Tape Market
Tapes
Differential Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Sterilization Tape Market
Tapes
Foil Tapes Market
Tapes
Silicone Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Pre-Printed Tape Market