
 Hydrocolloid Tapes Market | 2026-2036
Hydrocolloid Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocolloid Tapes Market Foresight
ISO 13485 certification for medical device quality management is unwinding the competitive landscape for hydrocolloid tape suppliers, elevating compliance costs for smaller manufacturers while rewarding established producers. 3M leverages its vertically integrated polymer science capabilities to control raw material quality from resin to finished adhesive layer. Smith & Nephew anchors its position through specialized wound care portfolios that extend across advanced dressings and securement products. Paul Hartmann competes with strong European distribution networks and deep clinical relationships in German and French hospital systems.
Hydrocolloid tapes are pressure-sensitive adhesive products composed of carboxymethylcellulose, gelatin, or pectin particles dispersed in a polyisobutylene matrix, designed to absorb exudate while maintaining a moist wound healing environment and protecting periwound skin from maceration. Wound care tapes dominate volume throughput due to chronic wound prevalence and repeat-purchase dynamics in home care settings, while surgical tapes command premium positioning through sterility requirements and operating room procurement protocols. Fabric-backed materials sustain higher margins than polymer-based alternatives because breathability and patient comfort drive preference in extended-wear applications.
The U.S. FDA regulates hydrocolloid tapes as Class II medical devices under 21 CFR 880.5245, requiring premarket notification and biocompatibility testing that shapes product development timelines and market access costs. The EU MDR and REACH frameworks impose additional substance restrictions and clinical evidence requirements that filter out non-compliant suppliers from European distribution channels. Stakeholders must monitor evolving adhesive polymer regulations and reimbursement pathways for advanced wound care to anticipate where procurement authority shifts between hospital formularies and outpatient purchasing.
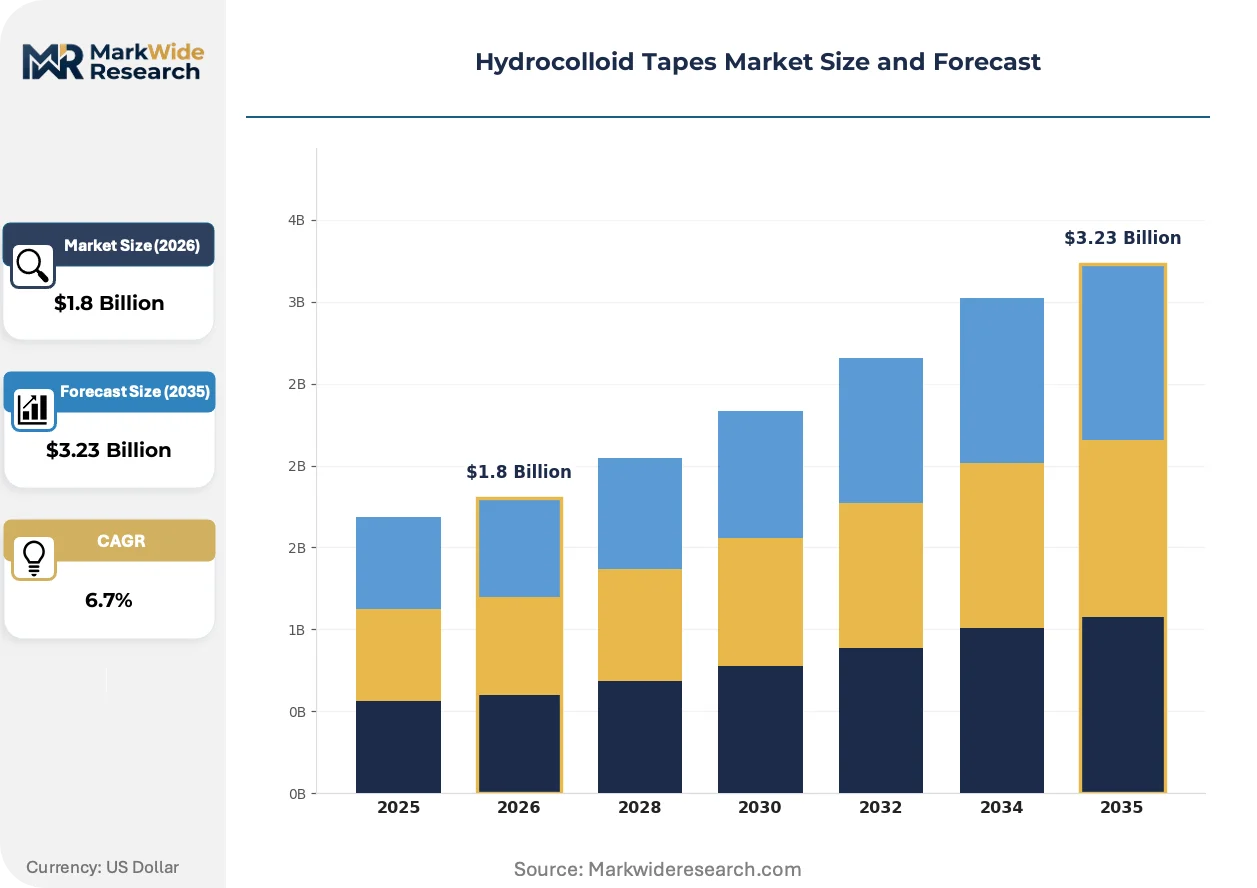
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing supplier margins through biocompatibility documentation requirements while simultaneously elevating barrier-to-entry for new entrants. This regulatory tightening intersects with raw material concentration in polymer supply chains to reshape competitive positioning across wound care procurement channels.
Growth Catalysts
- Post-operative wound protocols:Hospitals and surgical centers are expanding hydrocolloid tape procurement volumes for incision management and periwound skin protection following abdominal and orthopedic procedures.
- REACH substance restrictions:The European framework is filtering non-compliant adhesive suppliers from distribution channels, creating protected market access for certified manufacturers.
- Carboxymethylcellulose particle engineering:Advances in hydrocolloid matrix absorbency are extending wear time in exudate-heavy chronic wounds, reducing dressing change frequency for home care patients.
Market Restraints
- Polyisobutylene supply concentration:Feedstock dependency on petroleum-derived elastomers exposes margin structures to crude oil volatility and refinery output constraints.
- ISO 13485 certification timelines:Medical device quality management audits require 12-18 month implementation cycles that delay market entry for reformulated adhesive products.
- Silicone adhesive substitution:Low-trauma removal properties in silicone-based alternatives are capturing pediatric and geriatric segments with fragile periwound tissue requirements.
Strategic Opportunities
- German hospital system consolidation:Integrated purchasing networks in Bavaria and North Rhine-Westphalia are creating volume contracting opportunities for compliant suppliers with established clinical relationships.
- Home care channel expansion:Direct-to-patient distribution models are bypassing traditional wholesale intermediaries for chronic wound management supplies.
- Antimicrobial additive convergence:Silver-ion and PHMB integration with hydrocolloid matrices is opening premium positioning against standard exudate management products.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with pressure-sensitive adhesive expertise command premium compensation that strains R&D budgets at mid-scale manufacturers.
- Biocompatibility testing capex:Cytotoxicity and sensitization studies for MDR technical documentation require capital allocation to certified testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocolloid Tapes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound Care Tapes, Surgical Tapes, Stoma Tapes, Medical Adhesives Application: Surgical Procedures, Wound Management, Dressing Stabilization, Skin Protection Material: Polymer-Based, Fabric-Backed, Waterproof, Breathable End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | 3M, Avery Dennison, Smith & Nephew, Paul Hartmann, Parafix Tapes and Conversions, Covalon Technologies, Scapa Group, Medline Industries, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocolloid Tapes Market Shifts & Advancements
Adhesive layer engineering is compressing product differentiation cycles while regulatory documentation requirements are extending development timelines. These opposing pressures are forcing manufacturers to prioritize platform architectures that accommodate multiple certification jurisdictions.
Thin-film hydrocolloid composites are miniaturizing dressing profiles for ambulatory patients requiring discreet wear under clothing. Outpatient surgical centers are adopting these reduced-thickness formats for breast and facial procedure aftercare. The technology is miniaturizing inventory requirements while expanding addressable use cases beyond traditional wound care into cosmetic dermatology applications.
REACH substance restrictions on residual monomers in acrylic adhesives are forcing reformulation of standard hydrocolloid tape backings. German manufacturers are accelerating transition to pectin-based matrices to preempt regulatory non-compliance. The policy shift most acutely affects economy-tier product lines that previously relied on lower-cost synthetic polymer feedstocks.
Hospital formulary consolidation is concentrating purchasing authority at integrated delivery network headquarters rather than individual facility procurement departments. German hospital alliances are negotiating multi-year supply agreements that lock out smaller distributors. France and the Netherlands are exhibiting similar centralization patterns, though with varying degrees of clinician influence over product selection criteria.
Hydrocolloid Tapes Market Segmentation
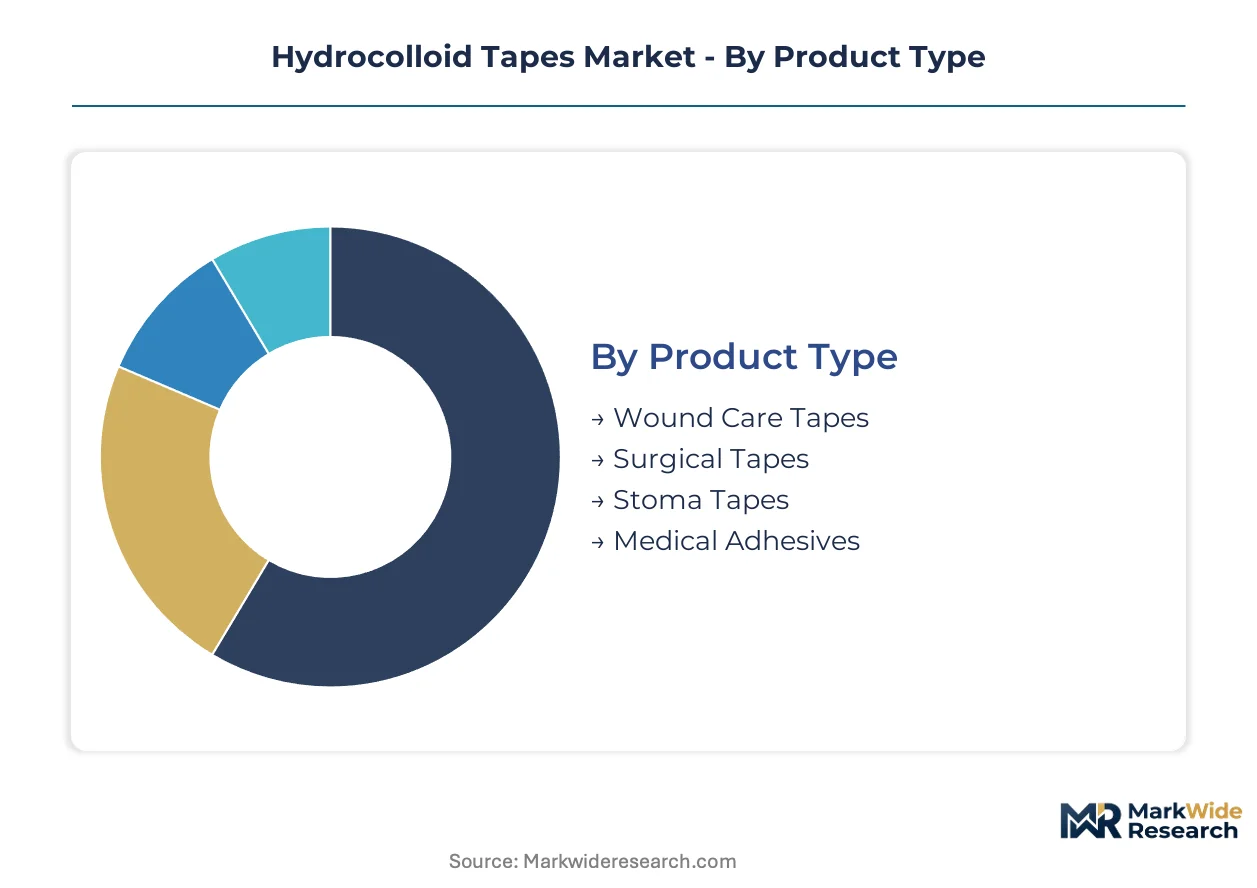
Hydrocolloid tape segmentation reveals divergent margin structures across product architectures and procurement channels. Material composition and sterility requirements create tiered pricing ladders that reshape supplier positioning in hospital formulary negotiations.
Product Type:
Margin pools concentrate in surgical and stoma applications where regulatory certification creates defendable pricing premiums against commodity wound care alternatives.
- Wound Care Tapes:These pressure-sensitive dressings combine carboxymethylcellulose particles with polyisobutylene matrices to absorb exudate while maintaining moist healing environments. Demand concentrates in German and French home care settings where aging demographics drive repeat-purchase volume for chronic venous leg ulcer management.
- Surgical Tapes:Sterile formats engineered for operating room protocols command premium positioning through biocompatibility documentation and lot-traceability requirements. Hospital procurement in Bavaria and North Rhine-Westphalia is consolidating purchasing authority around ISO 13485-certified suppliers with established clinical validation.
- Stoma Tapes:Specialized hydrocolloid barriers protect peristomal skin from enzymatic effluent in ostomy patients, requiring extended wear adhesion and flexibility around irregular abdominal contours.
- Medical Adhesives:Raw adhesive layers supplied to third-party converters for custom dressing fabrication, serving regional manufacturers without captive polymer science capabilities.
Surgical tapes hold installed capacity. Wound care tapes are rotating up the share rankings.
Application:
Volume throughput splits between acute institutional settings and distributed chronic care, with reimbursement pathways determining procurement authority concentration.
- Surgical Procedures:Incision management and periwound skin protection following abdominal and orthopedic interventions. German hospital alliances are locking in multi-year supply agreements that favor suppliers with REACH-compliant documentation and established distribution through integrated delivery networks.
- Wound Management:Chronic ulcer and pressure injury treatment in outpatient and home care environments. Direct-to-patient distribution models in France and the Netherlands are bypassing traditional wholesale intermediaries for recurring dressing replenishment.
- Dressing Stabilization:Secondary securement of primary wound dressings in high-mobility patients requiring reliable adhesion during physical rehabilitation.
- Skin Protection:Prophylactic barrier applications for fragile periwound tissue in pediatric and geriatric populations vulnerable to medical adhesive-related skin injury.
Surgical procedures anchor procurement volume. Home care wound management is climbing the fastest.
Material:
Raw material selection determines breathability profiles and wear-time performance, with natural polymer matrices gaining preference under tightening EU substance restrictions.
- Polymer-Based:Synthetic elastomer backings provide moisture resistance and dimensional stability. REACH residual monomer restrictions on acrylic adhesives are forcing reformulation timelines that compress margins for economy-tier manufacturers dependent on petroleum-derived feedstocks.
- Fabric-Backed:Woven textile carriers deliver superior breathability and patient comfort in extended-wear applications. German manufacturers are capturing premium positioning through pectin-based matrix transitions that preempt regulatory non-compliance while serving clinician preference for reduced maceration risk.
- Waterproof:Occlusive barrier films for showering and aquatic therapy compliance, requiring balanced moisture vapor transmission rates.
- Breathable:High-permeability constructions for exudate-heavy wounds where moisture management prevents periwound deterioration.
Fabric-backed materials hold installed capacity. Polymer-based formats are rotating up the share rankings.
End User:
Procurement authority is centralizing at network headquarters while clinician influence over product selection varies by national health system structure.
- Hospitals:Integrated delivery networks in Germany, France, and the Netherlands are consolidating formulary decisions at regional headquarters. EU MDR biocompatibility documentation requirements are filtering non-compliant suppliers from institutional procurement channels.
- Clinics:Outpatient surgical centers and wound care clinics require flexible inventory models with rapid replenishment for procedure-specific applications.
- Home Care:Direct-to-patient distribution is expanding for chronic wound management, with German and Dutch reimbursement pathways supporting patient-directed purchasing authority.
- Rehabilitation Centers:Extended-stay facilities requiring durable adhesion for mobile patients undergoing physical therapy protocols.
Hospitals hold installed capacity. Home care is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments concentrate purchasing authority for hydrocolloid tapes in Germany, France, the Netherlands, and the United States, with integrated delivery networks locking in multi-year supply agreements that favor REACH-compliant and ISO 13485-certified suppliers.
Germany
Bavarian and North Rhine-Westphalian hospital alliances drive volume contracting for post-operative wound management tapes. The EU MDR biocompatibility documentation requirements filter non-compliant suppliers from institutional procurement channels. Berlin-Brandenburg hosts regulatory consulting clusters that assist manufacturers with technical file preparation for notified body submissions.
France
Île-de-France wound care clinics expand direct-to-patient distribution for chronic ulcer management supplies. ANSM enforces vigilance reporting for medical device adverse events that shapes post-market surveillance obligations. The Lyon biomedical cluster concentrates converter operations serving French and Swiss hospital formulary networks.
United States
Outpatient surgical centers in Texas and Florida escalate procurement of sterile hydrocolloid formats for ambulatory procedure aftercare. The FDA regulates these products as Class II devices under 21 CFR 880.5245 with premarket notification requirements. The Minneapolis-St. Paul corridor anchors polymer science R&D facilities supporting adhesive layer innovation.
Netherlands
Dutch home care reimbursement pathways support patient-directed purchasing authority for recurring dressing replenishment. The Dutch Healthcare Authority monitors procurement transparency in hospital group purchasing organizations. The Eindhoven medical technology cluster hosts specialized coating operations for breathable fabric-backed tape constructions.
United Kingdom
NHS Integrated Care Boards in England consolidate formulary decisions for advanced wound care products at regional level. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR through retained law post-Brexit. The Cambridge life sciences corridor attracts adhesive formulation specialists serving diagnostic and wound care device manufacturers.
Hydrocolloid Tapes Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with captive polymer science capabilities and specialized wound care pure-plays with deep clinical relationships. Tiered competitive structure separates ISO 13485-certified institutional suppliers from economy-tier converters serving home care channels. Strategic archetypes include vertically integrated resin-to-adhesive manufacturers, European distribution-heavy converters, and antimicrobial-integrated format innovators. Dominant competitive moves encompass REACH-compliant reformulation acceleration and German hospital alliance volume contracting.
Among diversified conglomerates with polymer science depth, 3M exemplifies backward integration into raw material quality control from resin through finished adhesive layer. Smith & Nephew occupies a position within the specialized wound care portfolio archetype, extending across advanced dressings and securement products. Paul Hartmann anchors the European distribution-heavy tier through established clinical relationships in German and French hospital systems.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Smith & Nephew |
| Paul Hartmann |
| Parafix Tapes and Conversions |
| Covalon Technologies |
| Scapa Group |
| Medline Industries |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
EU MDR biocompatibility documentation gates both supplier qualification and price differentiation simultaneously, compressing margins for non-certified converters while elevating premium positioning for ISO 13485-validated manufacturers with established hospital formulary access.
Pricing Analysis
Cost-plus contracts with polyisobutylene feedstock indexation dominate procurement between German hospital alliances and certified adhesive suppliers. Three-tier pricing structure across premium, standard, and economy levels separates sterile surgical formats with lot-traceability from commodity wound care alternatives. Pricing pressure stems from REACH-compliant reformulation costs that economy-tier manufacturers pass through unevenly. Home care channels exhibit highest price sensitivity due to patient-directed purchasing authority, while operating room procurement prioritizes clinical validation over unit cost.
Supply Chain Analysis
Inventory cycles for carboxymethylcellulose and pectin raw materials extend lead times during agricultural harvest windows, compressing formulation flexibility for just-in-time converters. Manufacturing concentrates in Germany, the United States, and the Netherlands, with polymer science R&D anchored in the Minneapolis-St. Paul and Eindhoven corridors. Feedstock dependency draws from petroleum-derived elastomers and natural gum suppliers, exposing margin structures to crude oil volatility and crop yield variation. Single-source vulnerability concentrates in polyisobutylene resin supply. Distribution runs through integrated delivery network headquarters rather than individual facility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in direct-to-patient replenishment and clinical training subscriptions expand faster than hardware unit sales, rewarding suppliers who bundle adhesive products with wound care protocol education and remote patient monitoring integration.
For Market Incumbents: Fortify hospital formulary lock-in through multi-year volume contracting with Bavarian and North Rhine-Westphalian alliances, while accelerating pectin-based matrix transitions to preempt REACH substance restrictions. Silicone adhesive substitution in pediatric segments demands R&D investment in low-trauma removal properties. Backward integration into carboxymethylcellulose particle engineering preserves margin control against feedstock volatility. For New Entrants and Emerging Players: Differentiate on antimicrobial additive convergence by integrating silver-ion or PHMB matrices into hydrocolloid formats for exudate-heavy chronic wounds. Home care channel expansion in France and the Netherlands represents the most penetrable white space, bypassing consolidated hospital procurement through patient-directed reimbursement pathways. Target wound care clinics with flexible inventory models and rapid replenishment capabilities. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by filtering non-compliant suppliers and elevating certified manufacturers with technical file documentation. Long-term viability centers on platform architectures accommodating multiple certification jurisdictions rather than single-market exposure. Acquisition target archetype: mid-scale converters with ISO 13485 certification and established clinical relationships in German hospital systems. Monitor notified body backlog clearance rates as inflection indicator for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Acceleration | Pectin-based matrix transitions preempt regulatory non-compliance in German manufacturing. |
| Hospital Alliance Volume Contracting | Multi-year supply agreements with Bavarian networks lock out smaller distributors from institutional procurement. |
| Antimicrobial Additive Integration | Silver-ion and PHMB convergence opens premium positioning against standard exudate management products. |
| Direct-to-Patient Distribution Buildout | Home care channel expansion bypasses wholesale intermediaries for chronic wound replenishment in Dutch markets. |
| Polymer Science Talent Acquisition | Pressure-sensitive adhesive formulation expertise commands premium compensation that strains R&D budgets at mid-scale manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, wound care clinicians, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Bottom-up adhesive layer demand modeling triangulated with top-down wound care market sizing.
Variance decomposition across product type, application, material composition, and end-user channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro wound care expenditure trends. Forecast inputs incorporated chronic wound prevalence trajectories, reimbursement pathway evolution, and regulatory certification timeline assumptions.
Forecasts assume regulatory continuity in EU MDR and FDA Class II device frameworks; material policy shifts in biocompatibility documentation or adhesive substance restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Automotive Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Unsupported Single Coated Tape Market
Tapes
Foil Tapes Market
Tapes
Correction Tapes Market
Tapes
Replica Tapes Market
Tapes
Security Tape Market
Tapes
Application Tapes Market
Tapes
High Bond Tape Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Tape Backing Materials Market
Tapes
Thread Seal Tape Market
Tapes
Foam Tape Market
Tapes
Thermal Release Tapes Market
Tapes
Water Activated Tape Dispensers Market