
 Tear Tape Dispenser Market | 2026-2036
Tear Tape Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Tear Tape Dispenser Market Analytics
Aftermarket service revenue is fragmenting across the tear tape dispenser landscape as original equipment manufacturers face pressure from third-party refurbishment networks. 3M Company leverages its adhesive chemistry portfolio to sustain premium positioning in high-throughput dispensing systems. Intertape Polymer Group anchors North American supply through extensive converter relationships and private-label distribution. Tesa SE differentiates via precision-engineered tape feeding mechanisms that reduce material waste in continuous-run environments.
A tear tape dispenser is a mechanical or electromechanical device engineered to feed, cut, and apply pressure-sensitive tear tape to packaging substrates at controlled tension and alignment tolerances, typically operating at line speeds between 30 and 150 meters per minute depending on automation level. Its primary commercial purpose is to enable clean, repeatable package opening features while maintaining seal integrity during transit and shelf life. Electric and automatic dispenser categories command the dominant margin pools as logistics operators replace manual stations with servo-driven systems that integrate into Industry 4.0 packaging lines. Manual and handheld variants occupy a mature, price-sensitive tier serving small-batch converters and artisan retail packaging where capital constraints limit automation uptake. Material segmentation reveals plastic housings and components leading volume due to moldability and corrosion resistance, though metal-reinforced frames gain traction in heavy-duty industrial use where mechanical fatigue limits polymer durability.
REACH chemical restrictions in Europe and FDA food-contact substance regulations in the United States directly shape adhesive formulation choices and dispenser surface material approvals for packaging lines handling consumable goods. OSHA machine guarding standards and CE marking requirements under the EU Machinery Directive mandate interlocked safety systems on automatic dispenser installations, elevating engineering costs for market entrants. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate compatibility standards as biopolymer packaging adoption accelerates.
Market Dynamics
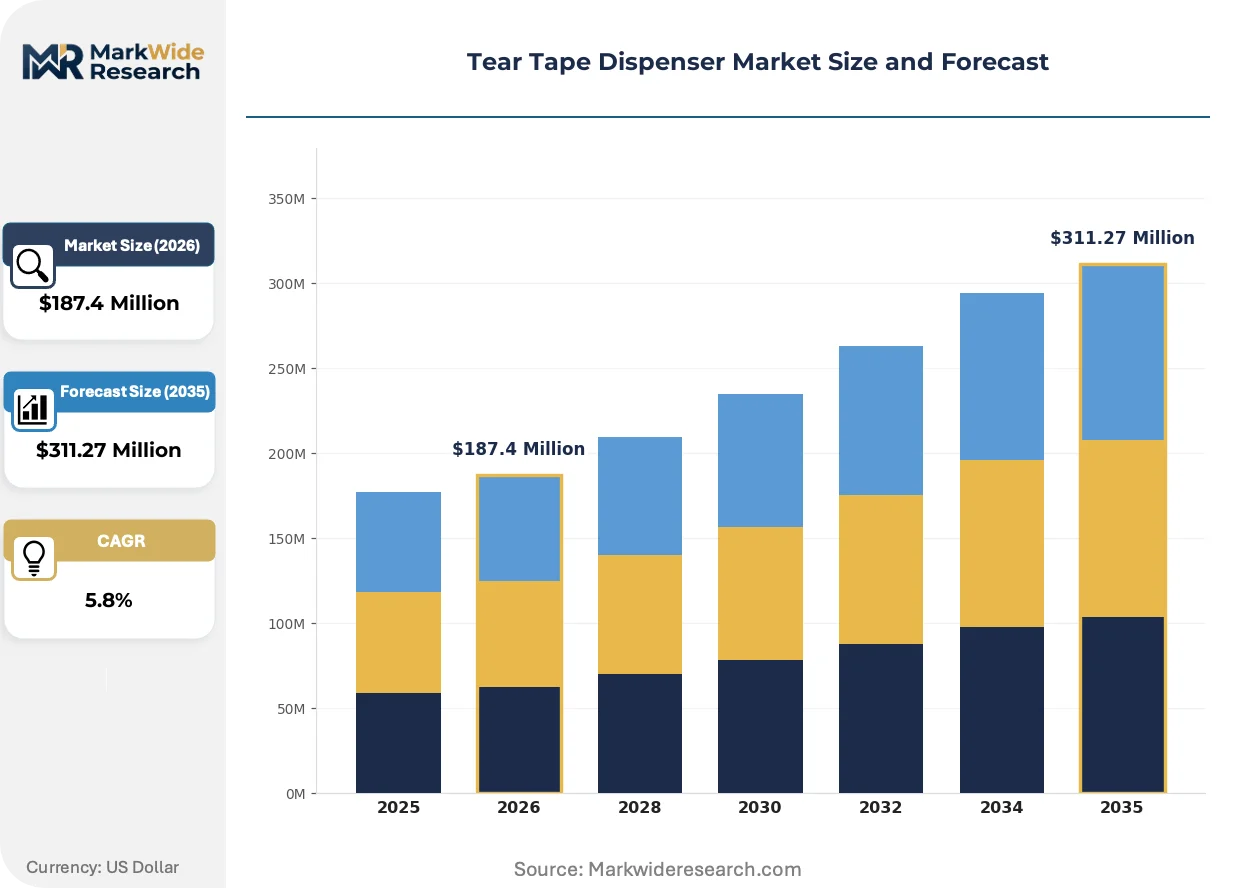
Automated packaging line integration is compressing replacement cycles for tear tape dispensers as e-commerce fulfillment centers demand servo-driven systems capable of Industry 4.0 data exchange. This technical migration is redistributing margin pools from mechanical component suppliers toward electromechanical system integrators.
Growth Catalysts
- E-commerce fulfillment automation:Logistics operators in Germany and China are retrofitting packaging lines with automatic dispensers to match throughput demands of same-day delivery networks.
- REACH adhesive compliance:European converter networks are replacing legacy tape formulations to meet ECHA substance restrictions, triggering dispenser refurbishment cycles for substrate compatibility.
- Biopolymer packaging mandates:Extended producer responsibility frameworks in France and Italy are accelerating dispenser upgrades to handle compostable film substrates without jamming or tension loss.
Market Restraints
- Steel and aluminum input volatility:Metal-reinforced dispenser frames face margin pressure from commodity price swings affecting precision-machined feeding mechanisms.
- East Asian electronics concentration:Servo motor and PLC controller supply chains cluster in China and Taiwan, exposing lead time risks for European and North American system builders.
- Mechanical speed ceilings:Pneumatic dispenser architectures top out below 80 meters per minute, capping their viability in high-throughput tobacco and pharmaceutical lines.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization mandates are driving contract packaging organizations to install track-and-trace integrated dispensers with vision verification systems.
- Refurbishment-as-a-service models:Third-party technical service networks in the United States are capturing aftermarket revenue streams previously held by original equipment manufacturers.
- AI-driven predictive maintenance:Machine learning algorithms analyzing vibration and tension sensor data are enabling uptime guarantees that differentiate premium dispenser contracts.
Industry Challenges
- Servo tuning expertise shortage:Packaging line integrators struggle to recruit controls engineers capable of calibrating multi-axis dispenser synchronization with upstream form-fill-seal equipment.
- CE marking documentation burden:EU Machinery Directive compliance requires extensive risk assessment files that extend new product introduction timelines for mid-tier dispenser manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tear Tape Dispenser Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Electric Dispensers, Automatic Dispensers, Handheld Dispensers Application: Packaging, Shipping, Retail, Industrial Use End User: E-commerce, Logistics, Manufacturing, Retailers Material: Plastic, Metal, Composite, Rubber |
| Companies Covered | 3M Company, Intertape Polymer Group, Tesa SE, Nitto Denko Corporation, Avery Dennison Corporation, Shurtape Technologies, Berry Global Inc., ULINE, IPG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tear Tape Dispenser Market Evolving Landscape
Direct-drive linear motor technology is eliminating mechanical transmission components from dispenser architectures. This electromechanical shift is compressing maintenance intervals while enabling sub-millimeter tape positioning accuracy at sustained line speeds.
Brushless linear motors with integrated encoder feedback are replacing ball-screw and belt-drive mechanisms in high-throughput pharmaceutical and tobacco packaging installations. Converter operators in Switzerland and Germany are adopting these systems to reduce mechanical wear points and extend mean time between failures. Precision tape feeding without backlash or belt stretch is rendering obsolete traditional mechanical transmission designs in continuous-run environments.
REACH Annex XIV authorization requirements are restricting phthalate-based adhesive plasticizers used in tear tape formulations across European converter networks. ECHA substance evaluations are forcing reformulation of pressure-sensitive adhesives to maintain dispenser surface compatibility and release characteristics. Food-contact packaging lines in France and Italy face the tightest compliance timelines as downstream brand owners accelerate clean-label packaging commitments.
Aftermarket service unbundling is fragmenting traditional equipment vendor revenue models as independent technical service organizations capture refurbishment and spare parts demand. Third-party maintenance networks in the United States and Germany are offering performance-based uptime contracts that displace original manufacturer service agreements. Pharmaceutical contract packagers in the Midwest and Rhine-Ruhr corridor show the highest propensity to switch to independent service providers for cost containment.
Tear Tape Dispenser Market Segmentation
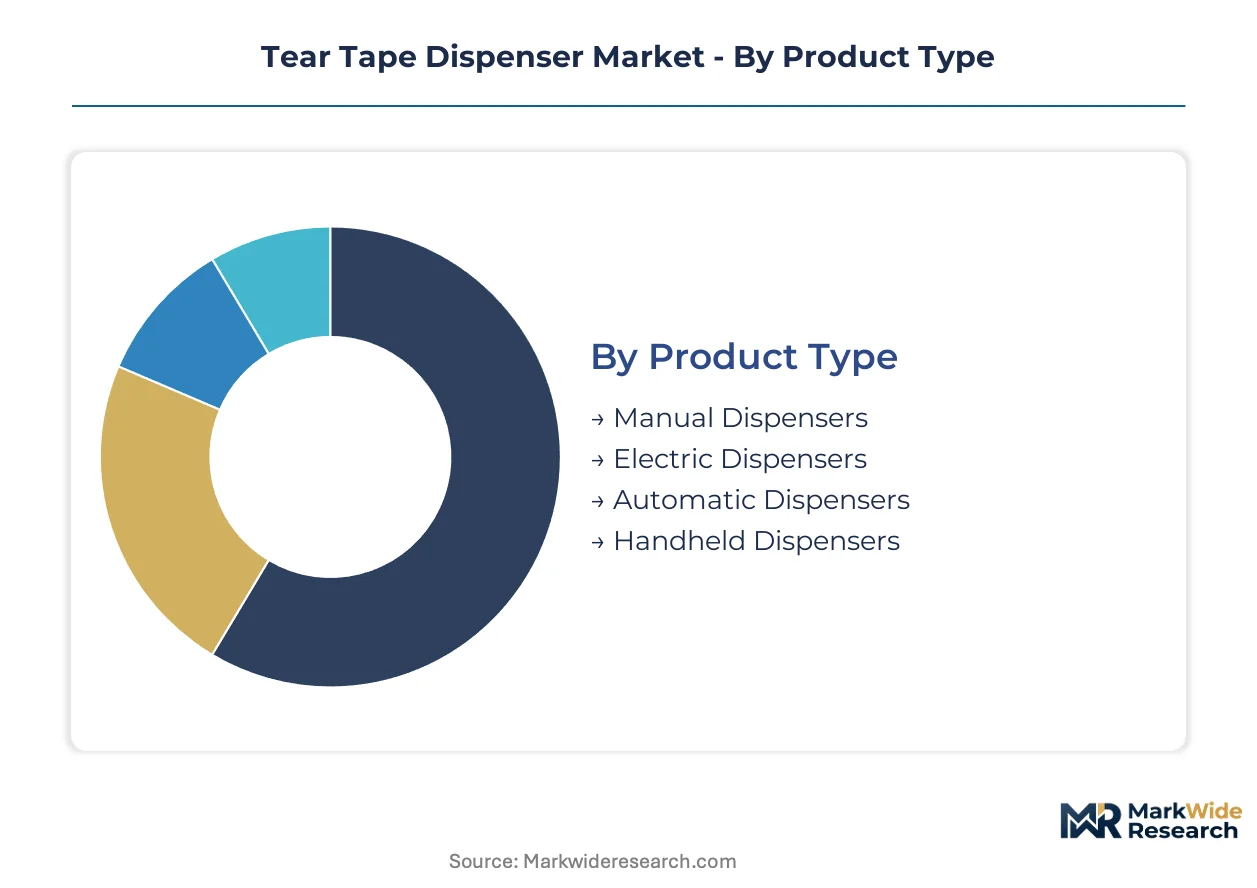
Tear tape dispenser segmentation reveals how automation intensity, substrate material, and end-use throughput requirements reshape procurement patterns. Distinct technical specifications across product tiers create divergent margin pools and service revenue opportunities.
Product Type:
Mature mechanical architectures coexist with emerging electromechanical platforms as logistics operators recalibrate capital deployment.
- Manual Dispensers:Hand-cranked tensioning mechanisms with mechanical brake systems dominate artisan packaging and small-batch converter operations. Demand concentrates in Germany's Mittelstand manufacturing sector where capital constraints limit automation uptake.
- Electric Dispensers:Motor-driven feed systems with variable speed control occupy the mid-tier automation band. Food-contact packaging lines in Italy deploy these units to meet throughput requirements without full servo integration.
- Automatic Dispensers:Servo-driven architectures with PLC integration and Industry 4.0 data exchange capabilities. E-commerce fulfillment centers in China retrofit packaging lines with these systems to match same-day delivery network demands.
- Handheld Dispensers:Portable battery-powered units for mobile retail packaging and field repair applications. Stationery retailers in Japan stock these for premium gift-wrapping services.
Automatic dispensers handle the majority of throughput; handheld dispensers are expanding most quickly on share.
Application:
Application segmentation tracks how substrate handling requirements and line speed specifications fragment demand across converter tiers.
- Packaging:Primary focus on form-fill-seal integration with tension control for flexible film and rigid carton substrates. Pharmaceutical contract packagers in Switzerland demand sub-millimeter positioning accuracy for blister pack tear tape application.
- Shipping:High-throughput carton sealing with reinforced tape dispensing at 100+ meters per minute. Logistics hubs in the United States deploy heavy-duty units for corrugated box reinforcement.
- Retail:Point-of-sale gift wrapping and premium packaging with decorative tear tape options. Department stores in France install compact benchtop units for customer-facing services.
- Industrial Use:Heavy-gauge substrate handling for pallet wrapping and bulk container sealing. Steel-reinforced frames dominate this tier due to mechanical fatigue resistance.
Packaging commands the installed base; shipping applications are climbing the fastest.
End User:
End user categories reflect divergent capital cycles and integration complexity tolerance across the value chain.
- E-commerce:Automated fulfillment centers requiring servo synchronization with robotic pick-and-place systems. Operators in Germany and China lead retrofit investments.
- Logistics:Third-party parcel networks balancing throughput scale with equipment mobility. Regional distribution centers favor electric dispenser fleets for flexibility.
- Manufacturing:In-house packaging lines for consumer goods and industrial products. Tobacco converters in Switzerland specify precision-engineered feeding mechanisms to minimize material waste.
- Retailers:Store-level packaging stations with space constraints and intermittent usage patterns. Manual and handheld variants dominate this price-sensitive tier.
Manufacturing holds the deepest installed base; e-commerce is gaining share fastest.
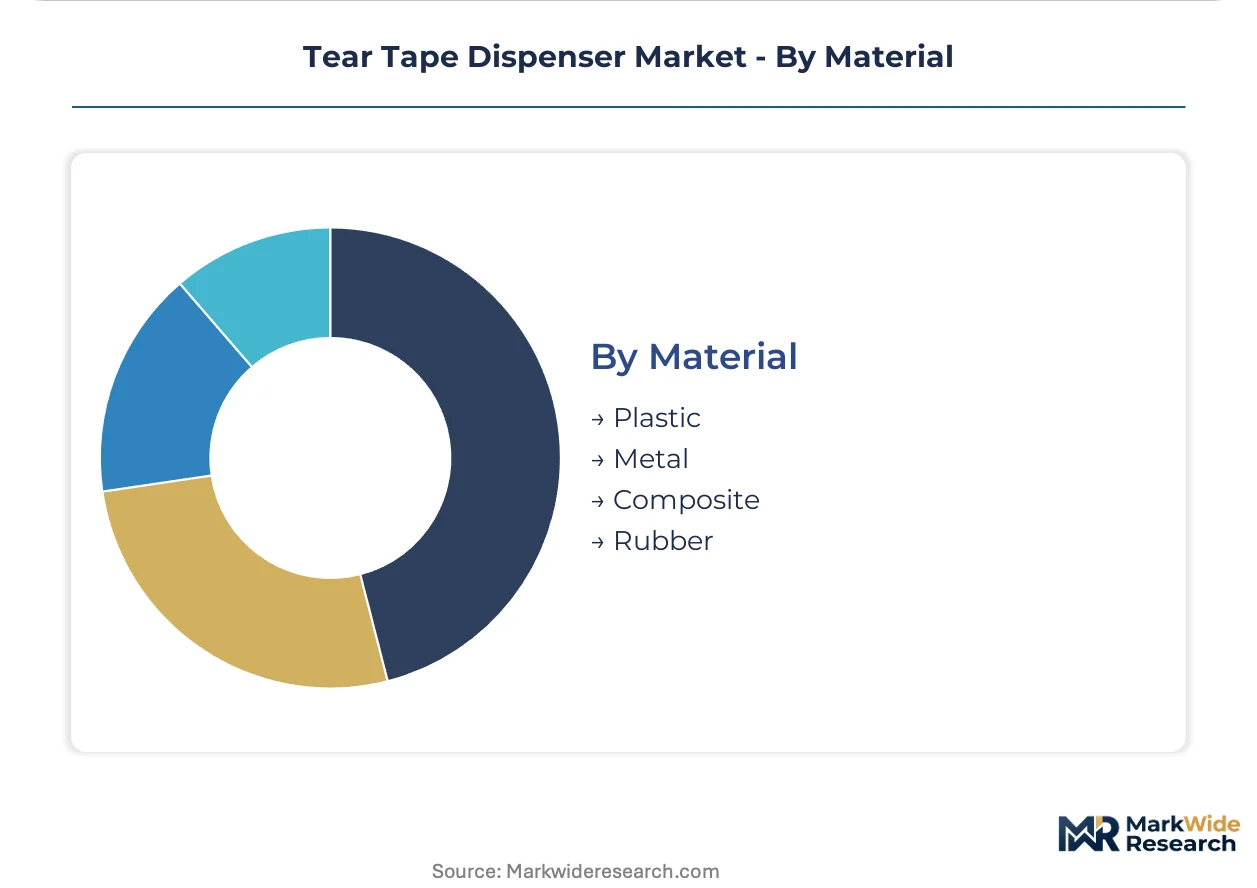
Material:
Material selection trades moldability and corrosion resistance against mechanical durability in continuous-run environments.
- Plastic:Injection-molded housings and components with chemical resistance for adhesive contact surfaces. REACH compliance drives formulation scrutiny for European converter networks.
- Metal:Aluminum and steel frames for heavy-duty industrial installations where polymer fatigue limits service life. Precision-machined feeding mechanisms in this tier face commodity price volatility.
- Composite:Hybrid constructions combining structural metal reinforcement with polymer contact surfaces. Emerging adoption in pharmaceutical lines seeking weight reduction without sacrificing rigidity.
- Rubber:Elastomer grip surfaces and tension roller coatings for substrate handling without slippage. FDA food-contact approvals constrain compound selection for North American installations.
Plastic leads volume throughput; composite materials show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland show minimal price elasticity for precision-engineered dispensing systems, while operators in India and Southeast Asia prioritize capital efficiency over feature depth. This divergence shapes how manufacturers configure regional product portfolios and service density.
United States
E-commerce fulfillment centers in the Midwest and Southeast drive automatic dispenser retrofit cycles to match same-day delivery throughput. OSHA machine guarding standards mandate interlocked safety systems on servo-driven installations, elevating engineering documentation burdens. The Chicago-Detroit corridor hosts dense clusters of contract packaging organizations upgrading track-and-trace integrated systems.
Germany
Converter networks in the Rhine-Ruhr and Bavaria regions replace legacy tape formulations to meet ECHA REACH Annex XIV substance restrictions. The EU Machinery Directive's CE marking requirements extend new product introduction timelines for mid-tier manufacturers. Stuttgart's Mittelstand manufacturing sector sustains demand for manual dispensers where capital constraints limit automation uptake.
China
Logistics operators in the Yangtze River Delta and Pearl River Delta retrofit packaging lines with automatic dispensers for cross-border e-commerce export volumes. SAMR quality certification and GB standards enforcement tighten material specifications for adhesive contact surfaces. Shenzhen's electronics manufacturing clusters concentrate servo motor and PLC controller supply chains, exposing lead time risks for system builders.
India
Pharmaceutical contract packaging organizations in Maharashtra and Gujarat install vision-verified dispensers to meet CDSCO serialization mandates. The PLI scheme for medical devices indirectly supports packaging automation investments. Mumbai-Pune industrial corridor converters show rising interest in refurbishment-as-a-service models to contain capital expenditure.
Switzerland
Tobacco and pharmaceutical converters in Basel and Zurich specify precision-engineered feeding mechanisms to minimize material waste in continuous-run environments. Swissmedic device regulations and ISO 13485 quality standards elevate documentation requirements for dispenser installations serving medical packaging. The country's precision manufacturing heritage sustains premium positioning for electromechanical system integrators.
Tear Tape Dispenser Market Competitive Landscape
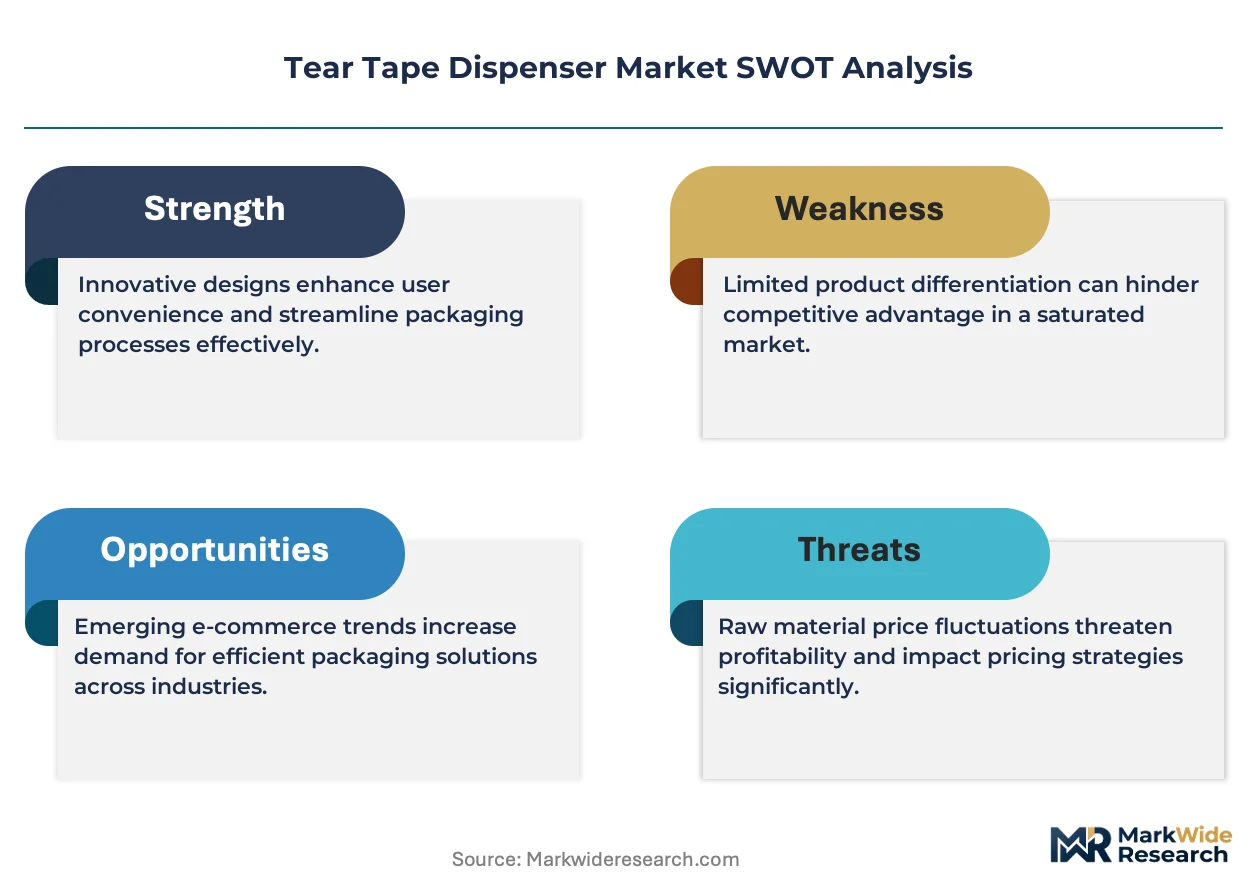
Capability concentration sits with specialized electromechanical system integrators; scale advantage sits with diversified adhesive and materials conglomerates. The market structures around three tiers: premium precision-engineered specialists, mid-tier electric dispenser fabricators, and price-competitive manual equipment suppliers. Dominant competitive moves include strategic partnerships between tape formulation specialists and dispenser OEMs, plus geographic expansion through third-party refurbishment networks capturing aftermarket revenue.
Within the diversified materials tier, 3M Company and Intertape Polymer Group occupy positions anchored by adhesive chemistry portfolios and converter relationship density. Tesa SE exemplifies the precision-engineered specialist archetype through its focus on tape feeding mechanism optimization. These three entities represent contrasting strategic postures: chemistry-driven system integration, North American supply chain anchoring, and precision mechanical differentiation respectively.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group |
| Tesa SE |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Shurtape Technologies |
| Berry Global Inc. |
| ULINE |
| IPG |
| Others |
Value Network & Pricing Analysis
Shenzhen's electronics manufacturing clusters concentrate servo motor and PLC controller production, concentrating bargaining power among electromechanical system integrators and compressing margins for mid-tier dispenser fabricators downstream.
Pricing Analysis
Aftermarket service contracts and refurbishment subscriptions now drive lifetime value capture as original equipment manufacturers face unbundling pressure from third-party technical networks. Three-tier pricing structure across premium, standard, and economy levels segments by automation intensity and integration complexity, with CE-marked servo systems commanding substantial premiums over manual alternatives. Cost compression in the electric dispenser tier is intensifying because converter procurement teams in Italy and Germany are consolidating vendor lists. Small-batch artisan packaging operations show the highest price sensitivity, while pharmaceutical contract packagers in Switzerland exhibit minimal elasticity for precision-engineered feeding mechanisms.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for North American system builders sourcing electromechanical components. Manufacturing concentration centers on China for servo motors and PLCs, Germany for precision-machined feeding mechanisms, and Taiwan for motion control electronics. Raw material dependencies span aluminum and steel for reinforced frames, engineering polymers for housings, and rare-earth magnets for brushless linear motors. Single-source vulnerability in East Asian semiconductor supply creates lead time fragility for European and North American integrators. Distribution runs through converter-direct relationships for large accounts and specialized industrial distributors for mid-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as e-commerce fulfillment automation penetrates logistics infrastructure previously served by manual packaging stations.
For Market Incumbents: Harden aftermarket revenue capture by acquiring independent refurbishment networks in the United States and Germany before third-party service providers consolidate further. Deepen in-house production of precision tape feeding mechanisms to defend against Asian electromechanical specialists encroaching on the premium tier. CE marking documentation capabilities represent a critical lever for locking out mid-tier competitors from European converter networks. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical contract packaging corridor where CDSCO serialization mandates are forcing vision-verified dispenser installations ahead of incumbent presence. Target refurbishment-as-a-service models in the Midwest United States to bypass capital-intensive manufacturing scale requirements. A go-to-market angle anchored in AI-driven predictive maintenance uptime guarantees differentiates against legacy OEM service agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical system integrators with installed base service contracts spanning pharmaceutical and tobacco converter networks. Long-term viability favors precision-engineered specialists with captive tape formulation partnerships and vertical control over feeding mechanism IP. Watch for inflection when third-party refurbishment networks in Germany achieve critical mass sufficient to force OEM acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of motion control components insulates margin from East Asian lead time volatility. |
| AI-Driven Predictive Maintenance Platform Launch | Machine learning uptime guarantees differentiate premium contracts in pharmaceutical packaging lines. |
| Refurbishment Network Acquisition | Third-party service consolidation in the United States recaptures aftermarket revenue from independents. |
| REACH-Compliant Adhesive Formulation Partnership | Joint development with tape specialists locks in European converter network switching costs. |
| India Pharmaceutical Corridor Expansion | CDSCO serialization mandates create first-mover advantage in vision-verified dispenser installations. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with packaging line engineers, aftermarket service directors, converter procurement managers, and electromechanical system integrators; and secondary validation through customs trade records, EU Machinery Directive filing databases, FDA food-contact substance registrations, and SEC filings from adhesive and materials conglomerates. Bottom-up installed base estimates triangulated against top-down e-commerce fulfillment center automation spending projections.
Forecast inputs span product type automation tiers, substrate material specifications, end-use throughput requirements, and regional regulatory compliance intensity across the projection horizon. Modeled dimensions include dispenser architecture, integration complexity, and end-user capital cycle positioning. CAGRs were derived from segment-level growth rate reconciliation against macro logistics automation spending patterns. Industry-specific inputs incorporate REACH Annex XIV substance restriction timelines and biopolymer packaging mandate enforcement trajectories.
Sensitivities concentrate around East Asian electronics supply disruptions, European extended producer responsibility framework acceleration, and servo tuning expertise scarcity affecting packaging line integration timelines. Forecasts reflect documented assumptions on e-commerce penetration rates and pharmaceutical serialization compliance deadlines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Automotive Adhesive Tapes Market
Tapes
Duct Tapes Market
Tapes
Unsupported Single Coated Tape Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Filament Tapes Market
Tapes
Galley Tapes Market
Tapes
Moisture Barrier Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Tape and Label Adhesives Market
Tapes
Invisible Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
BOPP Packaging Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
High Bond Tape Market
Tapes
Tapes Market
Tapes
Custom Printed Tape Market