
 Tape Unwinder Market | 2026-2036
Tape Unwinder Market Size, Share, and Industry Trends Forecast 2026-2036
Tape Unwinder Market Insights
Modular unwinder configurations paired with inline printing stations is consolidating buyer preference toward integrated production cells rather than standalone units. TECNOMA leverages its European manufacturing base to anchor high-precision unwinders for narrow-web flexographic lines. Fidia Macchine Grafiche specializes in servo-driven systems that compete on registration accuracy for label converters. 3M controls downstream adhesive specification influence, extending its pull on unwinder compatibility requirements across North American packaging operations.
A tape unwinder is a material handling device engineered to feed adhesive-backed substrates from master rolls at controlled tension, typically achieving web speeds between 50 and 500 meters per minute depending on drive configuration. The mechanism employs dancer rollers, load cells, or ultrasonic sensors to maintain constant tension and prevent web deformation during transfer to coating, laminating, or die-cutting stations. Fully automatic unwinders with servo drive technology are capturing margin pools in electronics manufacturing where cleanroom-grade tension control prevents particle contamination on flexible circuit substrates. Manual unwinders retain cost-sensitive positions in textile processing and small-batch packaging assembly where changeover frequency does not justify capital intensity.
CE marking under the EU Machinery Directive and ISO 13849 safety standards shape product design requirements for unwinders sold into European packaging and printing operations, forcing redundant braking systems and interlocked guards. The US OSHA lockout/tagout regulations and FDA cGMP guidelines for medical device packaging constrain unwinder material contact surfaces and documentation protocols. Stakeholders must monitor how servo drive electrification intersects with evolving IEC 61800 adjustable speed electrical power drive system standards, as efficiency and electromagnetic compatibility certifications become gatekeepers for cross-border equipment sales.
Market Dynamics
Servo drive electrification is compressing mechanical unwinder margins while ISO 13849 safety compliance becomes a non-negotiable specification gate for European packaging procurement teams.
Growth Catalysts
- E-commerce fulfillment automation:Automated case sealing lines in North American distribution centers are mandating precision tape feed systems to sustain throughput targets above 500 meters per minute.
- CE marking under EU Machinery Directive:Redundant braking and interlocked guard requirements are filtering out low-cost competitors, consolidating specification authority with certified European suppliers.
- Cleanroom-grade tension control:Electronics manufacturers in South Korea and Taiwan are specifying servo-driven unwinders to prevent particle contamination on flexible circuit substrates.
Market Restraints
- Steel and aluminum input volatility:Dancer roller and frame fabrication costs fluctuate with commodity indexes, compressing margins for mid-tier unwinder assemblers.
- Servo drive supply concentration:Precision motor and encoder sourcing clusters in Japan and Germany create lead time vulnerability for non-integrated unwinder builders.
- Mechanical system legacy lock-in:Textile processors and small-batch packaging operations retain manual unwinders due to changeover frequency below capital investment thresholds.
Strategic Opportunities
- India packaging automation:PLI scheme incentives for capital goods manufacturing are opening specification windows for servo-driven unwinders in corrugated board production.
- Inline printing integration:Modular unwinder configurations paired with flexographic stations are consolidating buyer preference toward unified production cells.
- FDA cGMP medical device packaging:Documentation protocols and material contact surface requirements are creating certified-unwinder premium tiers in North American healthcare supply chains.
Industry Challenges
- Servo commissioning expertise gap:Field engineers capable of tuning dancer roller PID loops for ultrasonic sensor feedback are scarce in secondary packaging machinery markets.
- IEC 61800 electromagnetic compatibility certification:Adjustable speed electrical power drive system testing timelines extend cross-border equipment sales cycles by four to eight months.
- Legacy mechanical integration friction:Retrofitting servo drives into existing dancer roller architectures without full line replacement creates tension calibration conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape Unwinder Market |
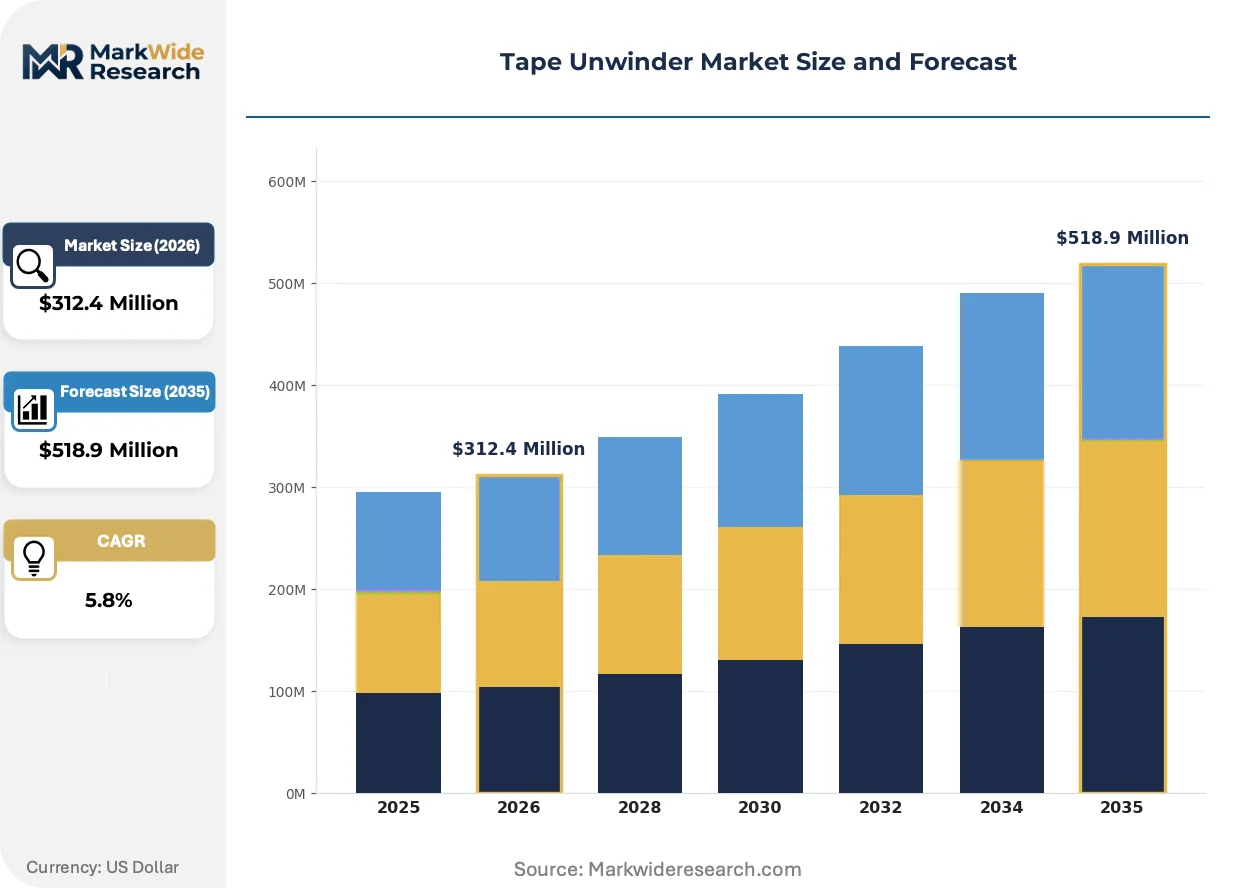
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Unwinders, Semi-Automatic Unwinders, Fully Automatic Unwinders, Motorized Unwinders Technology: Servo Drive, Mechanical Drive, Pneumatic Drive, Hydraulic Drive Application: Printing Industry, Packaging Assembly, Electronics Manufacturing, Textile Processing End User Industry: OEMs, Contract Manufacturers, Aftermarket Services, Maintenance Providers |
| Companies Covered | TECNOMA, Fidia Macchine Grafiche, Alci Group, Rubans de Normandie, 3M, Tesa SE, Nitto Denko Corporation, Shurtape Technologies, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape Unwinder Market Trends and Innovations
Active tension sensing architectures and integrated production cell designs are displacing standalone unwinder configurations across high-throughput packaging environments.
Ultrasonic web tension sensors are overtaking load cell and pneumatic dancer systems in narrow-web flexographic lines. Label converters in Germany and Italy are specifying non-contact measurement to eliminate mechanical wear and registration drift. This sensor transition is overtaking legacy dancer roller maintenance contracts and compressing aftermarket parts revenue for mechanical component suppliers.
REACH substance restrictions on adhesive backing chemistries are forcing tape manufacturers to reformulate acrylic and rubber-based pressure-sensitive adhesives. Unwinder builders must validate web transport compatibility with lower-tack formulations to prevent slippage at accelerated line speeds. European automotive OEM tape application standards in Germany are tightening adhesive precision tolerances, driving specification collaboration between unwinder vendors and 3M downstream.
Buyer consolidation toward integrated production cells is fragmenting standalone unwinder procurement. Packaging assembly lines in e-commerce fulfillment centers are specifying unwinders pre-integrated with inline printing and case sealing stations rather than retrofitting discrete units. This bundling preference is most visible in North American third-party logistics networks where throughput guarantees override component-level sourcing flexibility.
Tape Unwinder Market Segmentation
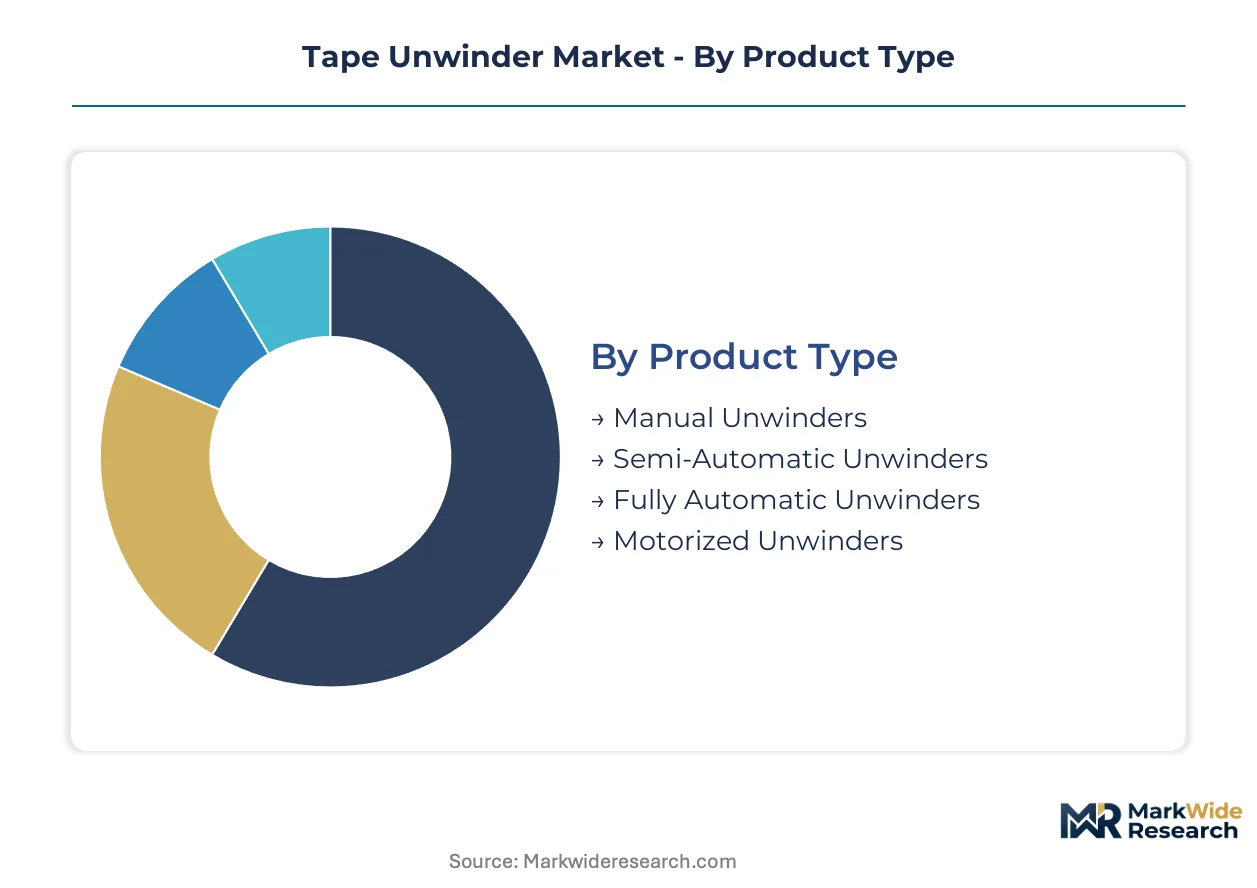
Tape unwinder procurement patterns diverge sharply across automation tiers and drive technologies, with specification authority consolidating around servo-driven configurations in precision-sensitive applications. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Automation intensity defines cost thresholds and buyer profiles across unwinder configurations, with capital deployment tolerance varying by production scale and changeover frequency.
- Fully Automatic Unwinders:Servo-driven tension control architectures achieve web speeds exceeding 500 meters per minute with closed-loop dancer roller feedback. Electronics manufacturers in South Korea specify these units for cleanroom-grade flexible circuit substrate handling where particle contamination risks override capital cost considerations.
- Manual Unwinders:Hand-cranked or brake-controlled mechanisms without powered drive systems serve small-batch textile processors and specialty packaging operations. German automotive OEM tape application standards rarely accommodate these units due to adhesive precision tolerance requirements that demand automated tension calibration.
- Semi-Automatic Unwinders:Hybrid configurations with powered unwind shafts but manual splice preparation occupy mid-tier label converting operations in Italy.
- Motorized Unwinders:Basic AC motor drives without servo feedback dominate cost-sensitive corrugated board production in India under PLI scheme capital goods incentives.
Fully automatic unwinders lead on scale; semi-automatic unwinders lead on momentum across mid-tier packaging automation upgrades.
Technology:
Drive electrification intensity separates premium specification tiers from commodity procurement, with regulatory compliance timelines accelerating technology transitions in regulated end-uses.
- Servo Drive:Closed-loop motor control with encoder feedback enables real-time tension adjustment within ±0.5% tolerance bands. CE marking under the EU Machinery Directive mandates redundant braking systems and interlocked guards that servo architectures accommodate more readily than mechanical alternatives, consolidating specification authority with certified European suppliers.
- Mechanical Drive:Friction clutch and pneumatic brake assemblies without electronic feedback retain installed base dominance in textile processing. Legacy lock-in persists where changeover frequency falls below capital investment thresholds for electronics manufacturing-grade automation.
- Pneumatic Drive:Air-actuated tension control via dancer cylinders serves narrow-web flexographic lines with moderate speed requirements.
- Hydraulic Drive:High-torque fluid power systems persist in heavy-gauge industrial tape applications with substantial roll mass inertia.
Servo drive leads on scale; pneumatic drive leads on replacement cycle momentum in cost-optimized European printing operations.
Application:
End-use precision requirements and throughput specifications create divergent technology adoption curves across industrial tape consumption verticals.
- Packaging Assembly:Automated case sealing lines in e-commerce fulfillment centers mandate precision tape feed systems sustaining throughput above 500 meters per minute. North American third-party logistics networks specify unwinders pre-integrated with inline printing stations rather than retrofitting discrete units.
- Electronics Manufacturing:Flexible circuit substrate handling demands cleanroom-grade tension control preventing particle contamination. South Korean and Taiwanese contract manufacturers specify servo-driven configurations with ultrasonic sensor feedback exclusively.
- Printing Industry:Narrow-web flexographic and label converting operations in Germany and Italy prioritize registration accuracy and non-contact tension measurement.
- Textile Processing:Fabric adhesive tape applications retain manual unwinder dominance due to batch size variability and low changeover frequency.
Packaging assembly leads on scale; electronics manufacturing leads on specification premium capture.
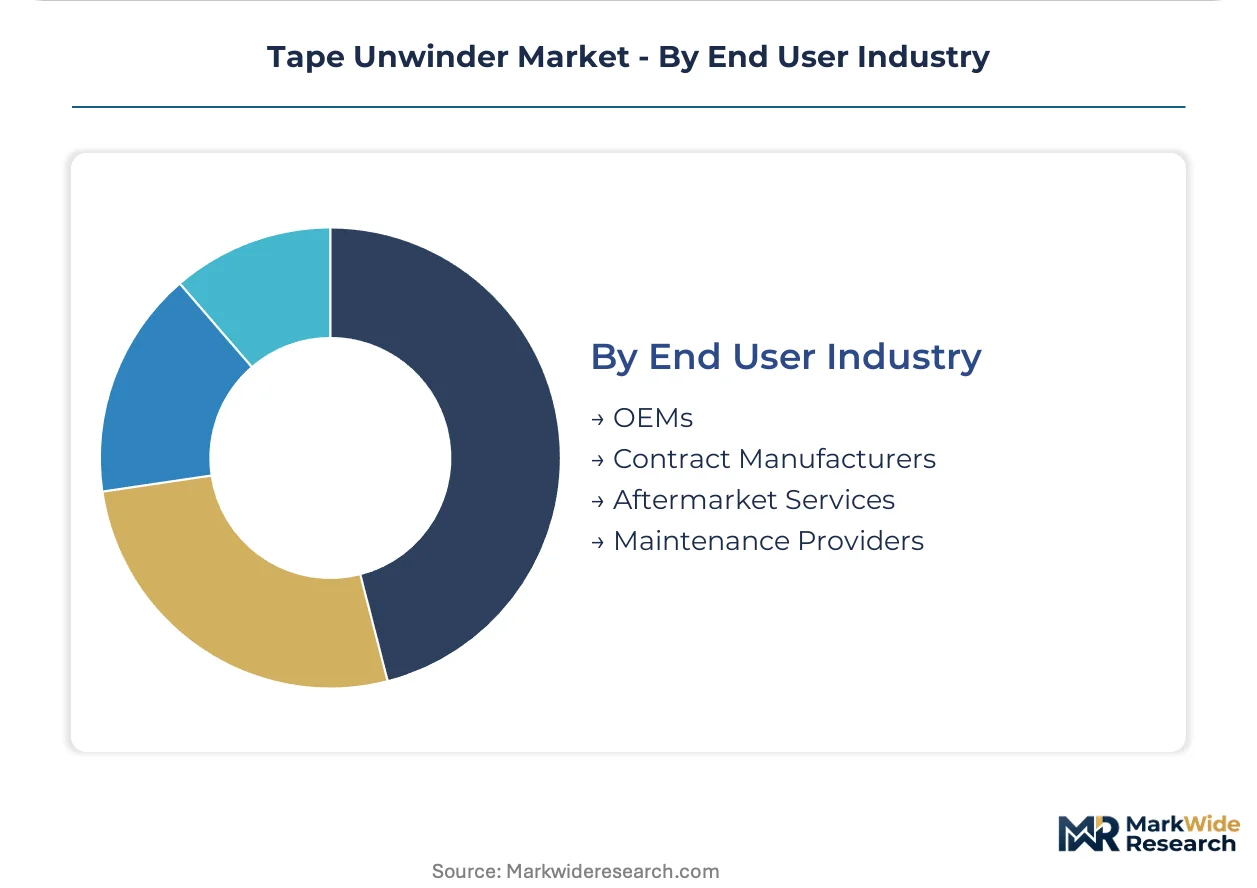
End User Industry:
Procurement authority and technical specification depth vary sharply across buyer types, with OEMs exercising disproportionate influence over downstream compatibility requirements.
- OEMs:Original equipment manufacturers integrating unwinders into complete production lines specify drive architectures and safety certifications that constrain supplier selection. German automotive OEM tape application standards tighten adhesive precision tolerances, forcing specification collaboration between unwinder vendors and downstream adhesive suppliers.
- Contract Manufacturers:Electronics assembly service providers in Taiwan and South Korea prioritize cleanroom-grade servo configurations for flexible circuit production.
- Aftermarket Services:Replacement unit procurement for installed base maintenance favors mechanical drive compatibility over technology upgrades.
- Maintenance Providers:Third-party service contracts concentrate on dancer roller and brake component replacement rather than full system replacement.
OEMs lead on scale; contract manufacturers lead on technology specification advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision tape handling machinery during post-war industrial reconstruction, establishing technical standards that persist across European packaging automation. Servo drive electrification and CE machinery safety compliance now differentiate procurement patterns across major manufacturing economies.
Germany
Automotive OEM tape application standards tighten adhesive precision tolerances, forcing unwinder vendors to validate servo-driven configurations against downstream specifications. CE marking under the EU Machinery Directive mandates redundant braking systems and interlocked guards that filter out uncertified competitors. Stuttgart and Munich industrial clusters concentrate specification authority for narrow-web flexographic lines serving label converters.
United States
E-commerce fulfillment centers mandate precision tape feed systems sustaining throughput above 500 meters per minute on automated case sealing lines. OSHA lockout/tagout regulations and FDA cGMP guidelines for medical device packaging constrain material contact surfaces and documentation protocols. Chicago and Dallas distribution corridors drive pre-integrated unwinder procurement with inline printing stations.
South Korea
Electronics manufacturers specify cleanroom-grade servo-driven unwinders to prevent particle contamination on flexible circuit substrates. METI-aligned industrial standards propagate through Korean contract manufacturing networks. Seoul and Suwon production clusters anchor demand for ultrasonic sensor feedback systems in semiconductor packaging supply chains.
India
PLI scheme incentives for capital goods manufacturing open specification windows for servo-driven unwinders in corrugated board production. BIS machinery safety standards progressively align with IEC frameworks for adjustable speed electrical power drive systems. Gujarat and Maharashtra industrial corridors concentrate mid-tier packaging automation upgrades.
Japan
Precision motor and encoder sourcing clusters create lead time vulnerability for non-integrated unwinder builders serving regional demand. JIS standards and METI industrial automation roadmaps shape servo drive adoption timelines. Nagoya and Osaka manufacturing belts retain mechanical system legacy lock-in where changeover frequency falls below capital investment thresholds.
Tape Unwinder Market Competitive Landscape
The competitive structure tilts toward European precision engineering specialists and diversified adhesive conglomerates with downstream specification influence. Three tiers crystallize: certified European machinery builders capturing CE-marked procurement, Asian component suppliers controlling drive system inputs, and tape manufacturers extending compatibility requirements upstream. Consolidation pressure intensifies through servo commissioning expertise scarcity and cross-border certification timelines.
Among European-based fabricators, TECNOMA and Fidia Macchine Grafiche occupy positions within the precision machinery tier, representing archetypes of regional manufacturing base leverage. 3M sits within the materials-science conglomerate category, exemplifying downstream adhesive specification authority that constrains unwinder compatibility requirements. These three anchors illustrate how competitive positioning fragments across machinery builders, component specialists, and tape manufacturers rather than consolidating around integrated platform providers.
| Leading Market Players |
|---|
| TECNOMA |
| Fidia Macchine Grafiche |
| Alci Group |
| Rubans de Normandie |
| 3M |
| Tesa SE |
| Nitto Denko Corporation |
| Shurtape Technologies |
| Avery Dennison |
| Others |
Pricing and Supply Chain Analysis
E-commerce fulfillment center procurement teams mandating pre-integrated production cells are compressing standalone unwinder margins and forcing suppliers to bundle servo-driven configurations with inline printing stations at compressed price points.
Pricing Analysis
Three-tier pricing structure across CE-certified servo systems, mid-tier pneumatic configurations, and manual mechanical units dominates procurement. Price differentiation hinges on ISO 13849 safety compliance tier and after-sales service bundling. Cost compression in mid-tier mechanical segments is intensifying because servo drive electrification raises buyer performance expectations without proportional budget expansion. Small-batch textile processors exhibit highest price sensitivity; electronics contract manufacturers in South Korea show lowest sensitivity due to cleanroom-grade specification requirements.
Supply Chain Analysis
Precision motor and encoder supply rests on Japanese and German component specialists, creating lead time vulnerability for non-integrated unwinder builders. Steel and aluminum for dancer roller fabrication draws from Chinese and Indian metallurgical suppliers, while servo drive controllers source from German automation specialists. Single-source vulnerability concentrates in high-precision encoder manufacturing. Distribution runs through OEM integration channels and direct sales to large packaging automation deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tape unwinder demand compounds steadily as e-commerce fulfillment automation mandates precision tape feed systems across North American distribution networks.
For Market Incumbents: Deploy CE marking certification investment as a competitive moat against uncertified Asian competitors. Deepen backward integration into servo drive controller sourcing to reduce Japanese component lead time exposure. Consolidate specification authority through pre-integrated production cell partnerships with inline printing station vendors. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for servo-driven unwinder localization in corrugated board production. Target mid-tier packaging automation upgrades in Gujarat and Maharashtra industrial corridors. Pursue go-to-market positioning as IEC 61800-compliant alternatives to European premium suppliers at 20-30% cost advantage. For Investors and Strategic Acquirers: Asymmetric upside sits with servo commissioning expertise holders in secondary packaging machinery markets. Five-to-ten year viability favors acquisition targets with certified European manufacturing bases and established automotive OEM relationships. Watch IEC 61800 electromagnetic compatibility certification timeline acceleration as inflection indicator for cross-border equipment sales velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Sourcing | Captive encoder supply from Japanese specialists reduces lead time vulnerability for mid-tier builders. |
| CE Marking Certification Investment | EU Machinery Directive compliance filters out low-cost competitors in German automotive supply chains. |
| Pre-Integrated Production Cell Partnerships | Inline printing station bundling captures e-commerce fulfillment procurement consolidation in North America. |
| PLI Scheme Localization in India | Domestic manufacturing under capital goods incentives opens specification windows in corrugated board production. |
| Servo Commissioning Expertise Development | PID loop tuning capability scarcity creates margin pools in electronics manufacturing cleanroom applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged packaging automation engineers, OEM procurement specialists, aftermarket service directors, and servo drive component suppliers. Secondary validation drew from EU Machinery Directive filings, SEC equipment manufacturer disclosures, Japanese METI industrial automation roadmaps, and Indian PLI scheme beneficiary registries. Bottom-up installation base estimates triangulated against top-down adhesive consumption proxies.
Segment-weighted modeling applied automation tier, drive technology, end-use application, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from historical equipment replacement cycles and forward capacity expansion announcements in e-commerce fulfillment. Industry-specific inputs included servo drive electrification penetration curves and CE marking compliance timeline data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility and single-source encoder supply disruption scenarios. Assumptions reflect documented procurement patterns and regulatory implementation schedules. A small set of named triggers—including IEC 61800 certification acceleration and India PLI scheme expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Unsupported Single Coated Tape Market
Tapes
Removal Strips Market
Tapes
Sterilization Indicator Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Heat Sealing Tape Market
Tapes
North America Packaging Tapes Market
Tapes
Pouch Tapes Market
Tapes
Automotive Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
BOPP Packaging Tapes Market
Tapes
Filament Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Global Acrylic Foam Tapes Market