
 Global Advanced Packaging Technologies Market | 2026-2036
Global Advanced Packaging Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Packaging Technologies Market Analysis
Automotive electronics is pivoting toward chiplet-based architectures as electric vehicles and advanced driver-assistance systems multiply silicon content per vehicle. TSMC leverages its CoWoS and InFO platforms to dominate high-bandwidth memory integration for AI training clusters. Samsung Electronics anchors its position through proprietary I-Cube and X-Cube technologies, while Intel Corporation competes via Foveros direct bonding and EMIB bridge solutions for heterogeneous integration.
Advanced packaging technologies encompass post-fabrication processes that interconnect multiple dies through interposers, through-silicon vias, or redistribution layers to achieve performance gains impossible at monolithic scale. Thermal management requirements now exceed 500W per package for AI accelerators, driving demand for liquid-cooled substrates and novel underfill materials. Flexible packaging formats are capturing margin pools in foldable electronics and medical wearables where conformal protection matters. Rigid packaging sustains its lead in server and networking applications where structural integrity protects fragile interposers under thermal cycling.
REACH and RoHS frameworks in Europe restrict hazardous substances in substrate materials and solder alloys, forcing material substitutions that raise processing complexity. The EPA in the United States enforces emissions standards for semiconductor fabrication and packaging facilities, influencing site selection for new advanced packaging plants. FDA device regulations intersect with advanced packaging where hermetic sealing protects implantable medical electronics. Stakeholders must monitor how bilateral technology controls between Washington and Beijing reroute supply chains for extreme ultraviolet lithography-dependent packaging equipment.
Market Dynamics
The advanced packaging sector is consolidating around heterogeneous integration as thermal constraints and memory bandwidth walls force semiconductor architects beyond monolithic scaling. CoWoS and similar interposer-based platforms now determine competitive positioning in AI accelerator supply chains.
Growth Catalysts
- EU Chips Act funding mechanisms:European governments are underwriting substrate fabrication facilities in Germany and France, reducing dependence on Asian interposer supply for automotive and industrial applications.
- High-bandwidth memory integration:AI training clusters require HBM3E stacking through advanced TSV processes, pulling wafer-level packaging capacity expansion across Taiwan and South Korea.
- Electric vehicle silicon content multiplication:Battery management systems and autonomous driving compute modules are driving chiplet adoption in automotive qualification environments.
Market Restraints
- Organic substrate supply concentration:Ajinomoto Build-up Film and similar core materials originate from Japanese chemical suppliers, creating single-source vulnerability for FC-BGA substrates.
- REACH substance restrictions:ECHA listings of brominated flame retardants and specific epoxy hardeners are forcing material reformulations that extend qualification timelines by 12-18 months.
- Die-to-wafer bonding yield limits:Hybrid bonding defect densities above 0.1 per square centimeter constrain 3D stacking economics for all but the highest-margin AI processors.
Strategic Opportunities
- India semiconductor ecosystem:PLI scheme incentives and Micron's Gujarat assembly and test facility are establishing advanced packaging footholds for memory products serving domestic data center demand.
- Photonics-electronics convergence:Co-packaged optics for 800G and 1.6T networking switches require novel interposer designs integrating silicon photonics with CMOS logic.
- Medical device hermetic sealing:FDA Class III implantable regulations are creating premium packaging demand for biocompatible encapsulation of neuromodulation and cardiac devices.
Industry Challenges
- Warpage control engineering:Large-format substrates exceeding 100mm square exhibit thermal expansion mismatches during reflow that demand finite element modeling expertise scarce in legacy OSAT workforces.
- Chiplets interconnect standardization:UCIe consortium specifications remain incomplete for optical and RF interfaces, forcing proprietary implementations that fragment supplier ecosystems and raise integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Packaging Technologies Market |
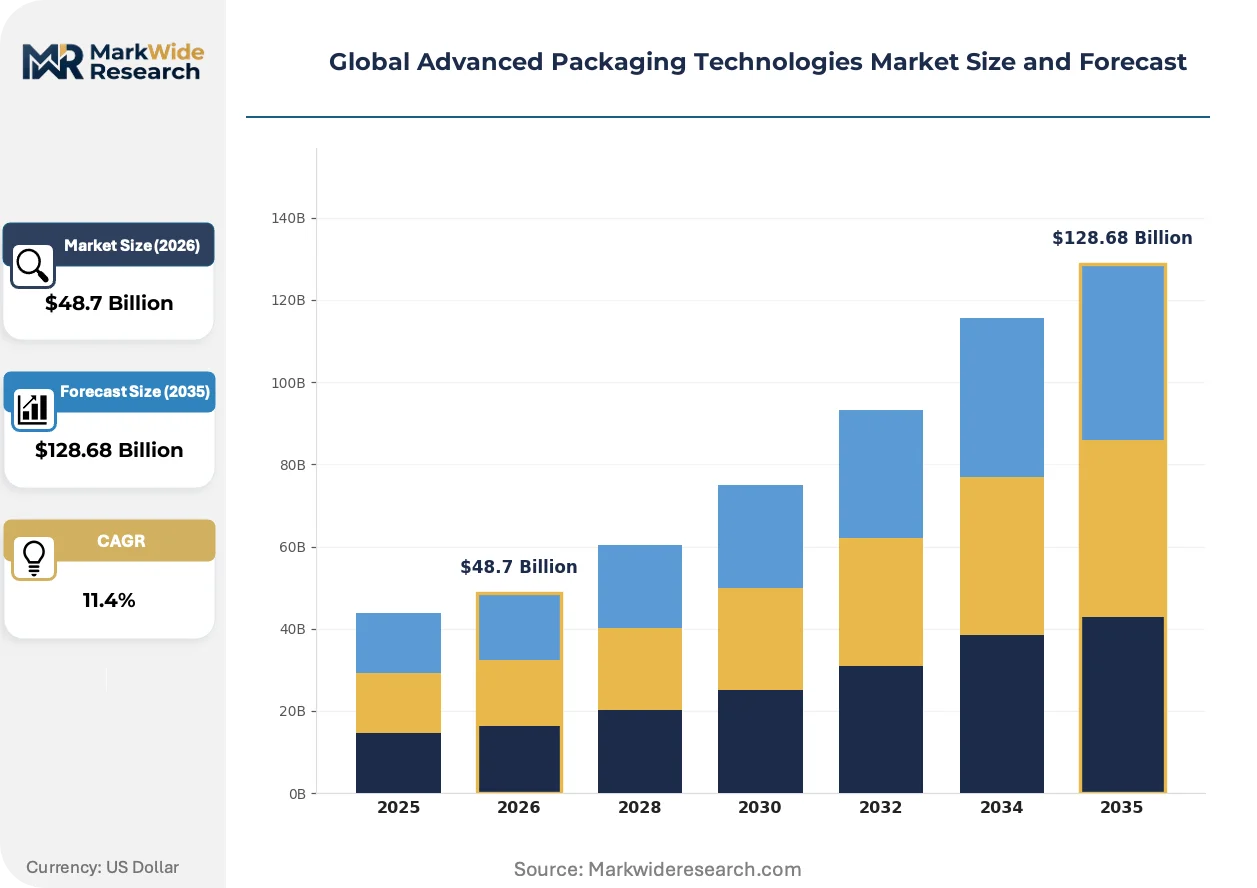
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Paper-Based Packaging Technology: Thermal Printing, Digital Printing, Flexographic Printing, Injection Molding Material: Plastic, Metal, Glass, Biodegradable Materials End User: Food & Beverage, Pharmaceuticals, Electronics, Personal Care |
| Companies Covered | Taiwan Semiconductor Manufacturing Company (TSMC), Samsung Electronics, Amkor Technology, ASE Technology Holding, Intel Corporation, JCET Group, Powertech Technology, Advanced Micro Devices (AMD), Siliconware Precision Industries (SPIL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Packaging Technologies Market Emerging Trajectories
Packaging architectures are bifurcating between power-dense AI accelerators requiring liquid cooling and mobile devices demanding ultra-thin form factors. This divergence is driving specialization in equipment platforms and material sets.
Hybrid bonding is unifying copper-to-copper interconnect pitch scaling with sub-10 micron alignment accuracy. Memory manufacturers are adopting this for HBM4 stacking to eliminate microbump parasitics. The technology is compressing traditional wirebond and flip-chip process flows into single-step wafer-to-wafer fusion, consolidating equipment supplier relationships around atomic-scale surface preparation tools.
REACH authorization requirements for SVHC substances in substrate laminates are forcing bismaleimide-triazine resin substitutions. German automotive Tier 1 suppliers now mandate full material disclosure to 100ppm thresholds for ECU substrates. Packaging houses in the Netherlands and Austria are responding with mass spectrometry-based supply chain verification protocols that add 8-12% to qualification costs.
Hyperscaler procurement of custom AI accelerators is compressing traditional 18-month packaging development cycles to 9-month windows. Cloud providers in the United States are establishing direct relationships with OSATs, bypassing traditional fabless semiconductor intermediaries. Taiwan-based packaging capacity is absorbing the majority of this direct engagement, with dedicated production lines locked under multi-year offtake agreements.
Global Advanced Packaging Technologies Market Segmentation
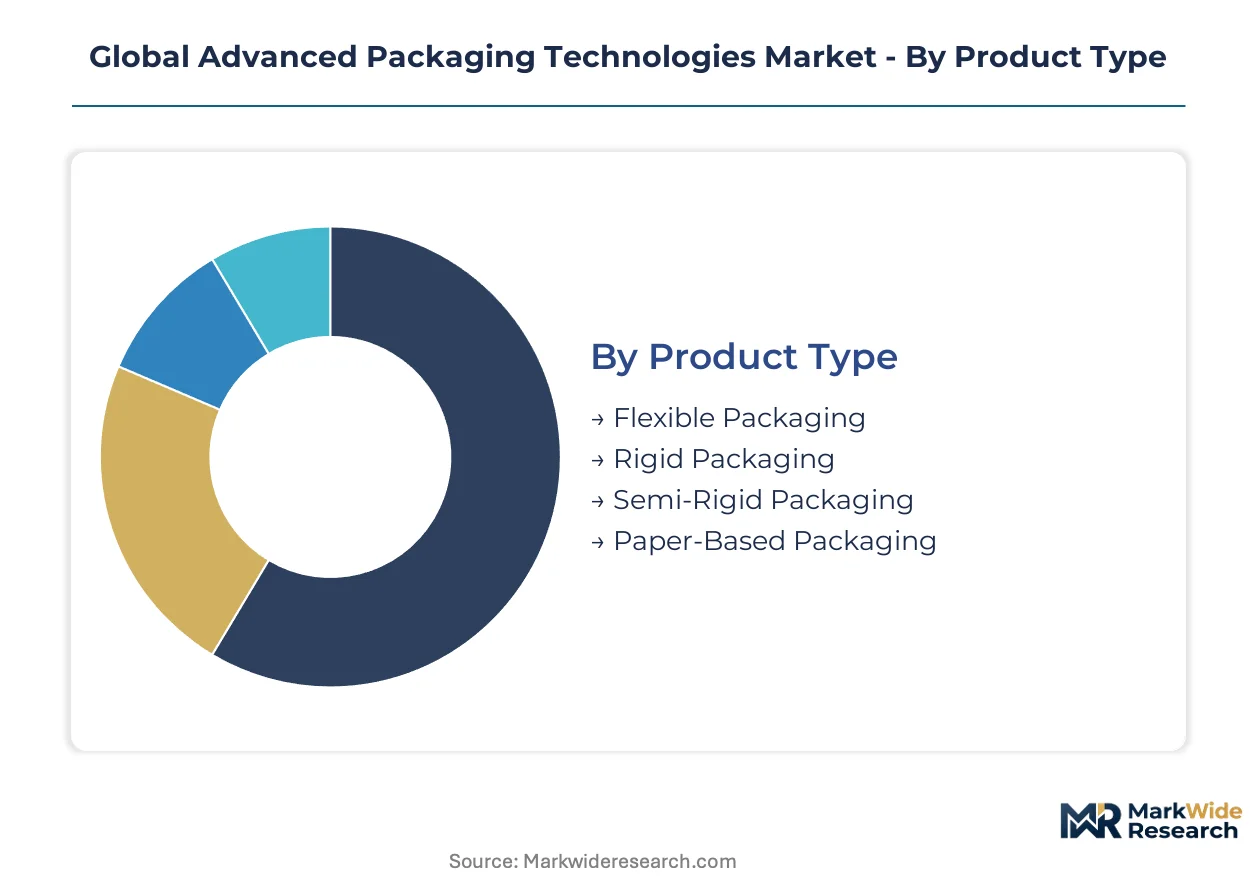
Advanced packaging technologies serve divergent thermal, mechanical, and electrical requirements across AI accelerators, automotive modules, and medical implants. Segmentation reveals how substrate materials, bonding processes, and form factor constraints map to distinct margin structures and qualification timelines.
Product Type:
Buyer selection hinges on thermal dissipation requirements and mechanical stress tolerance under cyclic loading.
- Flexible Packaging:Polyimide and liquid crystal polymer substrates enable conformal mounting on curved surfaces in foldable smartphones and implantable neuromodulation devices. Medical wearables manufacturers in Switzerland specify hermetic barrier films meeting ISO 10993 biocompatibility standards.
- Rigid Packaging:Organic laminate and ceramic substrates provide structural integrity for interposer-based AI accelerators exceeding 500W thermal design power. Hyperscale data center operators in the United States specify these formats for HBM3E memory integration.
- Semi-Rigid Packaging:Hybrid constructions combining rigid cores with flexible outer layers serve automotive radar modules requiring vibration resistance.
- Paper-Based Packaging:Emerging cellulose fiber substrates target disposable medical diagnostics with limited shelf-life requirements.
Rigid packaging leads on scale; flexible packaging leads on momentum.
Technology:
Process selection tracks alignment precision requirements and throughput economics for heterogeneous integration.
- Thermal Printing:Laser-assisted bonding enables sub-10 micron die placement accuracy for copper-to-copper hybrid bonding in HBM4 stacks. Memory manufacturers in South Korea deploy this for wafer-to-wafer fusion eliminating microbump parasitics.
- Digital Printing:Maskless patterning of redistribution layers accelerates prototyping cycles for custom AI accelerator interposers. Fabless designers in California leverage this for rapid iteration of chiplet routing architectures.
- Flexographic Printing:Roll-to-roll processing of antenna-in-package substrates serves high-volume RFID and NFC applications in retail logistics.
- Injection Molding:Transfer molding of epoxy compounds encapsulates wirebonded automotive power modules for under-hood temperature exposure.
Thermal printing commands premium pricing; digital printing expands most quickly.
Material:
Regulatory substance restrictions and thermal conductivity specifications drive material substitution patterns.
- Plastic:Bismaleimide-triazine and epoxy resins dominate organic substrates despite REACH authorization pressures on halogenated flame retardants. German automotive Tier 1 suppliers now mandate full material disclosure to 100ppm thresholds.
- Metal:Copper interposers and aluminum heat spreaders manage thermal flux in AI training clusters. Taiwan-based foundries specify oxygen-free copper for TSV plating uniformity.
- Glass:Low-CTE glass substrates enable fine-pitch redistribution layers for RF front-end modules in 5G millimeter-wave handsets.
- Biodegradable Materials:Polylactic acid and starch-based encapsulants target single-use medical sensors with controlled dissolution profiles.
Plastic retains volume leadership; biodegradable materials gain share fastest.
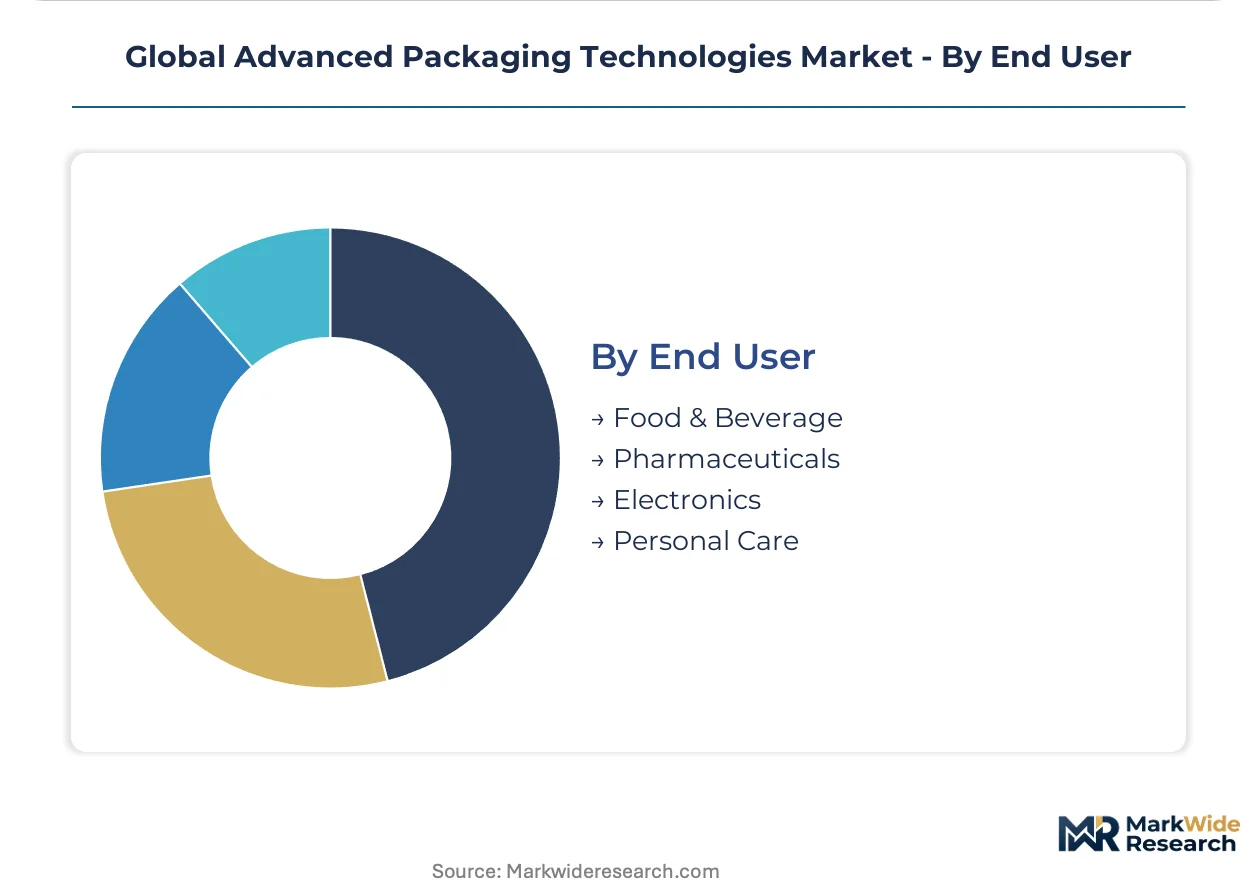
End User:
End-use qualification environments determine reliability testing protocols and supplier certification requirements.
- Food & Beverage:Aseptic filling systems and intelligent packaging with printed electronics for supply chain traceability. European packaging houses integrate NFC sensors meeting EU Food Contact Material regulations.
- Pharmaceuticals:Cold chain monitoring devices and unit-dose blister packs with tamper-evident features. FDA serialization mandates drive demand for track-and-trace enabled packaging in North American distribution.
- Electronics:Chiplet-based system-in-package modules for AI inference at the edge. Japanese consumer electronics manufacturers specify these for camera modules and sensor hubs.
- Personal Care:Airless dispensers and connected beauty devices with pressure-sensitive dispensing. Korean cosmetics brands deploy smart packaging with Bluetooth-enabled usage tracking.
Electronics leads on scale; pharmaceuticals leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing advanced packaging capacity as fabs migrate toward jurisdictions with subsidized infrastructure and streamlined permitting. The EU Chips Act and U.S. CHIPS and Science Act are creating cost-of-compliance gaps that favor greenfield investments in Germany and Arizona over legacy Asian clusters.
United States
Hyperscaler demand for AI training clusters and CHIPS Act subsidies exceeding $39 billion are accelerating domestic CoWoS-equivalent capacity buildouts. EPA emissions standards under the Clean Air Act influence site selection for new substrate fabrication plants. Intel's Arizona and New Mexico campuses anchor the domestic heterogeneous integration ecosystem.
Taiwan
TSMC's CoWoS and InFO platforms serve NVIDIA and AMD accelerator demand, absorbing 90% of global high-bandwidth memory integration volume. The National Science and Technology Council coordinates semiconductor supply chain resilience initiatives. Hsinchu Science Park concentrates wafer-level packaging capacity for 2.5D interposer production.
South Korea
Samsung Electronics and SK Hynix are scaling I-Cube and X-Cube 3D stacking for HBM4 memory dies targeting AI inference accelerators. The Ministry of Trade, Industry and Energy administers K-Semiconductor Belt tax incentives. Pyeongtaek and Yongin clusters host next-generation hybrid bonding pilot lines.
Germany
Automotive chiplet qualification for battery management systems and autonomous driving compute is driving substrate demand from Bosch and Continental. REACH substance restrictions on brominated flame retardants force material reformulations extending qualification timelines. Dresden and Regensburg host Europe's leading OSAT operations for automotive-grade FC-BGA.
Japan
Ajinomoto Build-up Film supply concentration creates single-source vulnerability for organic substrates serving AI accelerator interposers. METI's semiconductor revitalization strategy funds advanced packaging R&D consortia. Kyushu and Nagoya industrial corridors concentrate chemical precursor manufacturing for high-density redistribution layers.
Global Advanced Packaging Technologies Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with IDM-captive operations dominating AI accelerator packaging while merchant OSATs serve automotive and industrial volumes. The vendor base organizes into three tiers: foundry-integrated packaging divisions, pure-play OSATs with heterogeneous integration capabilities, and legacy wirebond houses transitioning to flip-chip. Consolidation pressure is accelerating as hybrid bonding equipment costs exceed $50 million per line, forcing M&A activity and strategic foundry-OSAT partnerships.
Within the foundry-integrated tier, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify the captive model where packaging serves as a moat for leading-edge logic customers. Among merchant OSATs, Amkor Technology and ASE Technology Holding occupy positions as scale-driven alternatives for fabless designers seeking multi-source qualification. Intel Corporation represents the IDM-revival archetype, leveraging Foveros and EMIB to reclaim packaging autonomy after years of outsourcing dependence.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Samsung Electronics |
| Amkor Technology |
| ASE Technology Holding |
| Intel Corporation |
| JCET Group |
| Powertech Technology |
| Advanced Micro Devices (AMD) |
| Siliconware Precision Industries (SPIL) |
| Others |
Supply Flow & Price Mechanics
Copper cathode pricing on the London Metal Exchange cascades through substrate fabrication into three distinct packaging tiers, with Taiwan-based interposer foundries passing alloy cost volatility to hyperscale AI accelerator buyers while automotive module suppliers absorb margin compression from fixed-price contracts with German Tier 1s.
Pricing Analysis
Direct-to-OEM discount structures dominate high-volume AI accelerator procurement, with NVIDIA and AMD securing multi-year offtake agreements that lock substrate pricing below spot-market indices. Price differentiation separates liquid-cooled CoWoS platforms from standard FC-BGA modules, with thermal management complexity commanding premium positioning. Cost compression in mid-tier flip-chip services is intensifying because Chinese OSATs are expanding capacity for mature-node packaging. Fabless semiconductor designers exhibit the highest price sensitivity, while cloud hyperscalers prioritize supply security over unit economics.
Supply Chain Analysis
Workforce availability constraints in Hsinchu, Yongin, and Dresden are compressing expansion timelines for hybrid bonding pilot lines, with Taiwan's National Science and Technology Council coordinating immigration exemptions for specialized equipment engineers. Geographic supply concentration centers on Taiwan, South Korea, and Japan, with Ajinomoto Build-up Film and Showa Denko chemical precursors drawing from petrochemical feedstocks in the Chukyo industrial corridor. Single-source vulnerability for organic substrate core materials creates supply chain risk. Distribution runs through foundry-integrated packaging divisions for leading-edge AI accelerators, while merchant OSATs serve automotive and industrial volumes through direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electric vehicle silicon content multiplication forces automotive packaging toward zero-defect qualification standards that only premium-tier suppliers can satisfy.
For Market Incumbents: To counter emerging hybrid bonding specialists in South Korea, TSMC and Intel should expand captive interposer capacity in Arizona and New Mexico, securing EPA emissions-compliant substrate fabrication ahead of CHIPS Act disbursement timelines. Certification investment in automotive AEC-Q100 Grade 0 standards creates switching costs that protect margin pools in battery management system packaging. For New Entrants and Emerging Players: The price-point gap between liquid-cooled AI accelerator substrates and air-cooled automotive modules offers entry space for mid-tier OSATs specializing in thermal interface materials for data center retrofit applications. India's PLI scheme incentives for semiconductor assembly and test establish the most penetrable geography, with Micron's Gujarat facility validating local supply chain viability. A go-to-market angle targeting European automotive chiplet qualification under REACH substance disclosure mandates bypasses direct competition with incumbent foundry packaging divisions. For Investors and Strategic Acquirers: Asymmetric upside sits with merchant OSATs possessing heterogeneous integration capabilities but lacking leading-edge logic captive relationships, as hyperscaler direct procurement trends bypass traditional fabless intermediaries. Long-term viability over the next decade hinges on hybrid bonding yield mastery and automotive qualification track records. The signal to watch is Intel's Foveros capacity utilization rates as a proxy for IDM-revival competitive intensity against foundry-integrated alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Wafer-to-wafer fusion equipment exceeding $50 million per line consolidates supplier relationships around atomic-scale surface preparation tools in South Korea and Taiwan. |
| Automotive Chiplet Qualification Investment | AEC-Q100 Grade 0 certification for battery management systems creates multi-year revenue visibility with Bosch and Continental in Dresden and Regensburg. |
| Co-Packaged Optics Integration | Silicon photonics interposer designs for 800G networking switches require novel EDA tool flows and packaging-house partnerships with Cisco and Arista. |
| Biocompatible Encapsulant Development | FDA Class III implantable regulations for neuromodulation devices drive premium pricing for hermetic sealing technologies in Swiss and German medical packaging clusters. |
| Direct Hyperscaler Relationship Building | Cloud providers establishing OSAT bypass channels compress 18-month development cycles to 9-month windows, favoring Taiwan-based packaging houses with dedicated production lines. |
Methodological Framework
Direct dialogue with packaging equipment engineers, substrate procurement leads at fabless semiconductor designers, automotive Tier 1 supplier quality directors, and EPA regulatory compliance officers grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings, ECHA SVHC authorization databases, Taiwan Stock Exchange capex disclosures, and EU Chips Act funding allocation records. Bottom-up capacity modeling across Taiwan, South Korea, and Arizona facilities triangulated against top-down AI accelerator shipment projections from hyperscaler infrastructure disclosure.
Segment-level outputs across the projection horizon reflect technology bifurcation between power-dense liquid-cooled AI substrates and conformal flexible formats for medical wearables, with material-grade substitutions under REACH frameworks modeled as qualification timeline extensions. CAGRs were derived from installed base depreciation schedules and foundry packaging capacity expansion announcements. Hybrid bonding yield curves and HBM4 stacking roadmaps from Samsung and SK Hynix served as technology adoption rate inputs.
Caveats apply where bilateral technology controls between Washington and Beijing could materially shift the outlook for EUV-dependent packaging equipment access, or where automotive chiplet standardization delays under UCIe consortium timelines fragment supplier ecosystems. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion assumptions and geographic diversification strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Gel Packs Market