
 Protective Films Tapes Market | 2026-2036
Protective Films Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Films Tapes Market Analytics
China is tilting toward expanded polyethylene and polypropylene film capacity to serve domestic electronics and automotive demand. 3M leverages its adhesive science portfolio across multiple substrate platforms. Nitto Denko Corporation anchors precision coating capabilities for display protection films in East Asian supply chains. Tesa SE competes through specialized high-adhesion formulations serving European industrial customers.
Protective films tapes are multilayer adhesive-backed substrates, typically 25-150 micrometers thick, engineered to shield surfaces from abrasion, contamination, and environmental exposure during manufacturing, transit, or end-use. Acrylic and polyethylene compositions dominate where optical clarity and clean removability are required, while PVC variants persist in construction applications demanding thicker mechanical protection. The automotive application segment leads volume consumption due to paint protection film deployment across OEM and aftermarket channels. Electronics represents the fastest-expanding application as foldable displays and mini-LED backplanes require anti-static and UV-resistant film grades. Waterproof feature categories command margin concentration in medical and outdoor construction end uses where failure carries high replacement costs.
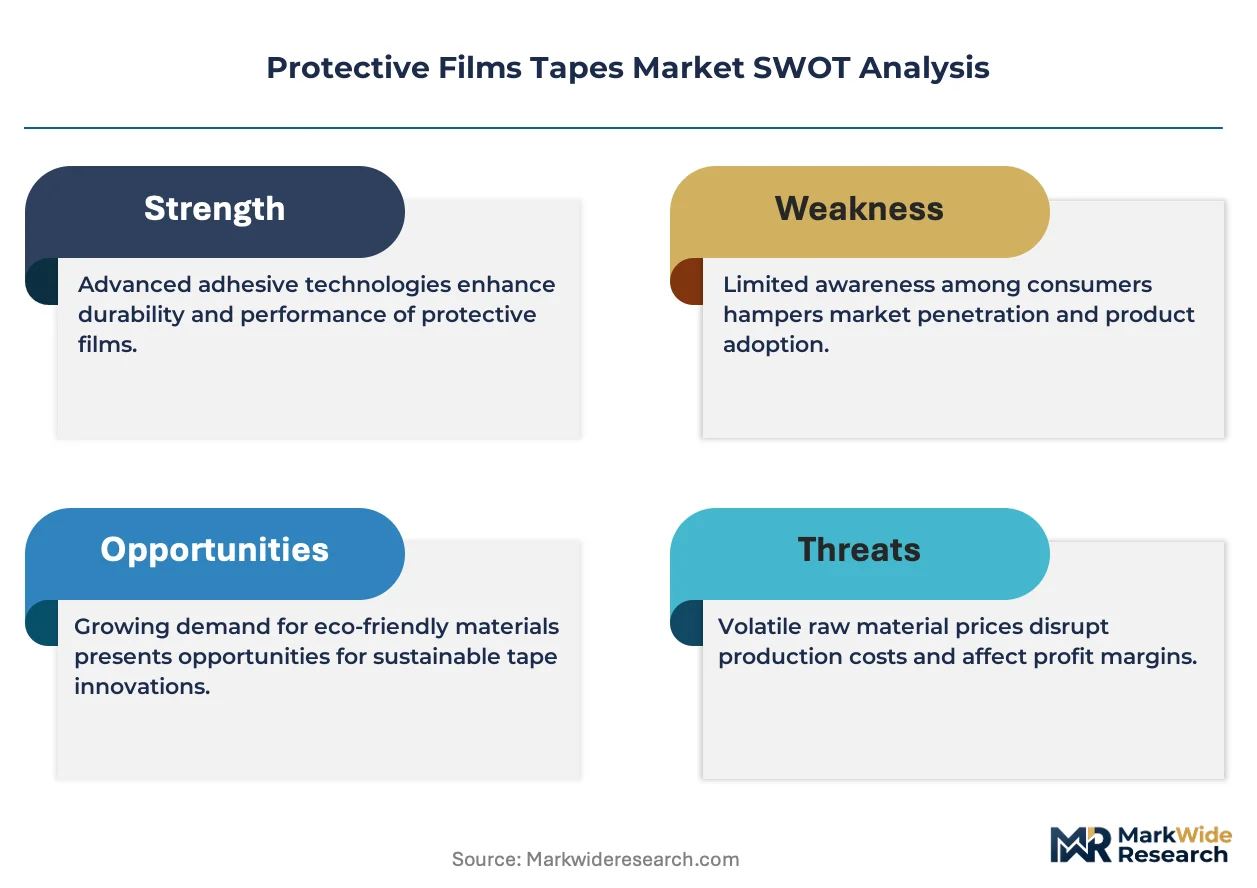
EPA guidelines in the United States restrict solvent-based adhesive emissions, pushing manufacturers toward waterborne and hot-melt coating systems. REACH and RoHS frameworks in Europe limit phthalate plasticizers in PVC films and mandate substance disclosure across supply chains. China's MEE enforces VOC reduction targets that accelerate solvent recovery investments at domestic coating facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Automotive OEMs and display manufacturers are compressing supply chains vertically, forcing film converters to co-locate coating facilities adjacent to assembly plants in China's Yangtze Delta and Germany's Baden-Württemberg corridor.
Growth Catalysts
- GB Standard 2025 Revisions:China's updated adhesive emission standards are accelerating solvent-free coating line investments at domestic film producers serving electronics OEMs.
- Mini-LED Backplane Diffusion:Precision anti-static films are penetrating display manufacturing as panel makers scale micro-LED assembly capacity in Taiwan and South Korea.
- Paint Protection Film Mandates:Luxury automotive brands now specify temporary surface protection through entire logistics chains, expanding film consumption per vehicle by 40-60% at German and Japanese OEMs.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene and polypropylene resin prices swing with naphtha-cracker economics, compressing converter margins unpredictably.
- Adhesive Supply Concentration:Acrylic pressure-sensitive adhesive production clusters among three chemical majors in the US Gulf Coast, creating single-source vulnerability for specialty grades.
- Thickness-Performance Tradeoff:Sub-50-micrometer films struggle to deliver adequate puncture resistance for construction glass protection, limiting substitution of thicker PVC alternatives.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme subsidies for smartphone and component assembly are creating first-mover advantage for film converters establishing local coating operations.
- Bio-Based Acrylic Formulations:EU Green Deal procurement preferences are opening tender access for suppliers with certified renewable content in public infrastructure projects.
- Direct-to-OEM Digital Platforms:Specialized film configurators are disintermediating distributors for standard automotive paint protection specifications at mid-volume fleet operators.
Industry Challenges
- Coating Technician Shortage:Precision slot-die and microgravure operation requires 18-24 month training pipelines that vocational programs have failed to scale.
- Dual Certification Burden:Suppliers to medical device and automotive end-uses must maintain parallel ISO 13485 and IATF 16949 quality systems, doubling audit costs.
- Legacy Inventory Stranding:Phthalate-containing PVC film stocks face accelerated obsolescence as REACH restrictions tighten across European distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Films Tapes Market |
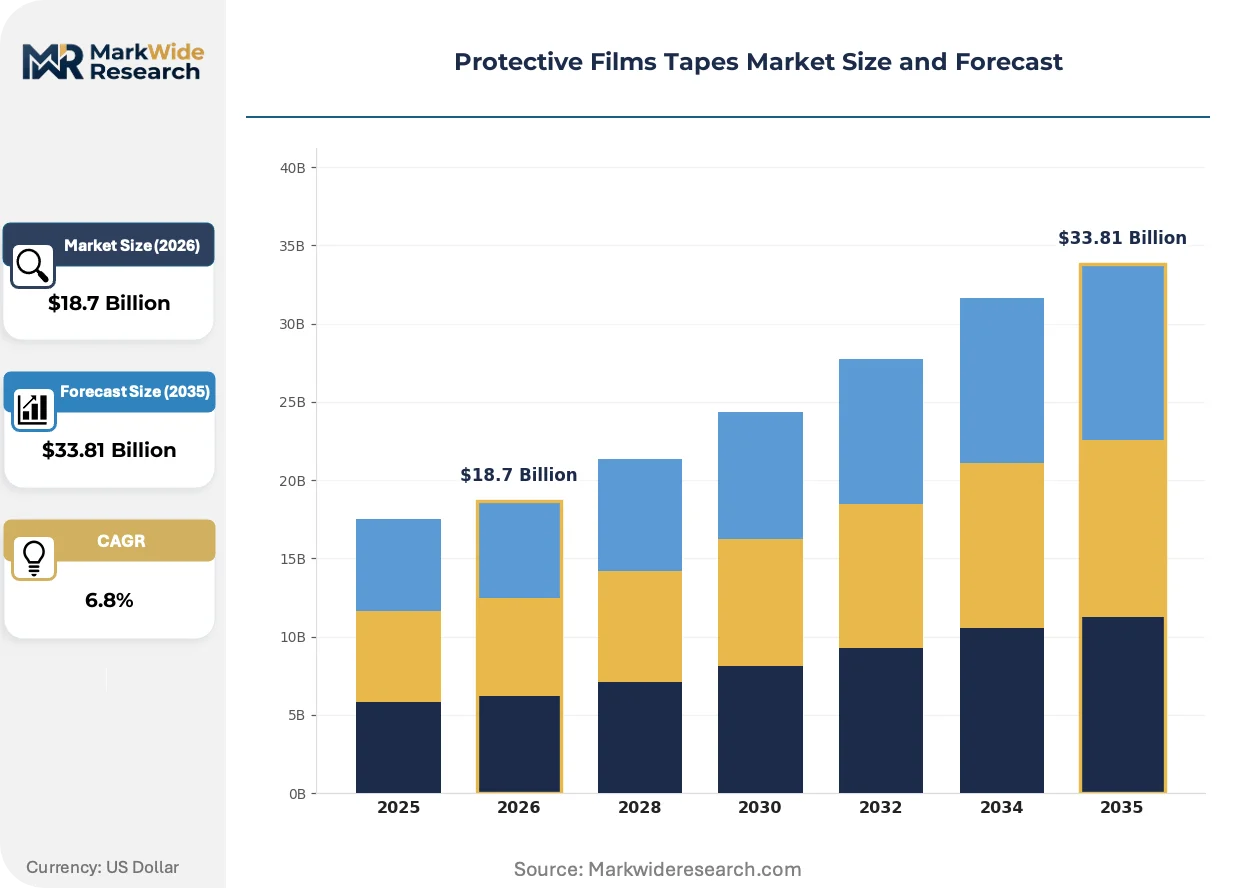
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Acrylic Application: Automotive, Electronics, Construction, Medical Feature: Waterproof, UV Resistant, Anti-static, High Adhesion End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | 3M, Nitto Denko Corporation, Avery Dennison Corporation, Tesa SE, XPEL, Saint-Gobain, Eastman Chemical Company, Lintec Corporation, Scapa Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Films Tapes Market Evolving Landscape
Smart manufacturing systems and material science advances are compressing product development cycles while regulatory pressure on chemical content forces formulation reinvention across substrate and adhesive layers.
Embedded RFID and NFC tag integration is digitizing supply chain traceability for high-value protective films used in aerospace and medical device packaging. Tier-one automotive suppliers in Stuttgart and Toyota City are piloting reel-level digital twins that track film application parameters through assembly lines. This connectivity is digitizing quality assurance workflows and enabling predictive replenishment models that reduce inventory carrying costs by 15-25%.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC film producers toward bio-based plasticizer alternatives or substrate switches to TPO formulations. German automotive OEMs now mandate substance disclosure through entire coating supply chains under SCIP database requirements. Medical packaging converters in Ireland and Switzerland are responding fastest, securing early-mover certification for phthalate-free film grades ahead of 2026 enforcement milestones.
Specification consolidation among multinational electronics assemblers is compressing approved vendor lists from 40-60 suppliers to 8-12 strategic partners per region. Procurement teams at Foxconn and Pegatron facilities now require film suppliers to maintain 48-hour stocking hubs within 100 kilometers of final assembly. This concentration is visible most acutely in China's Guangdong and Jiangsu provinces where converter margins face sustained pressure from volume-commitment pricing structures.
Protective Films Tapes Market Segmentation
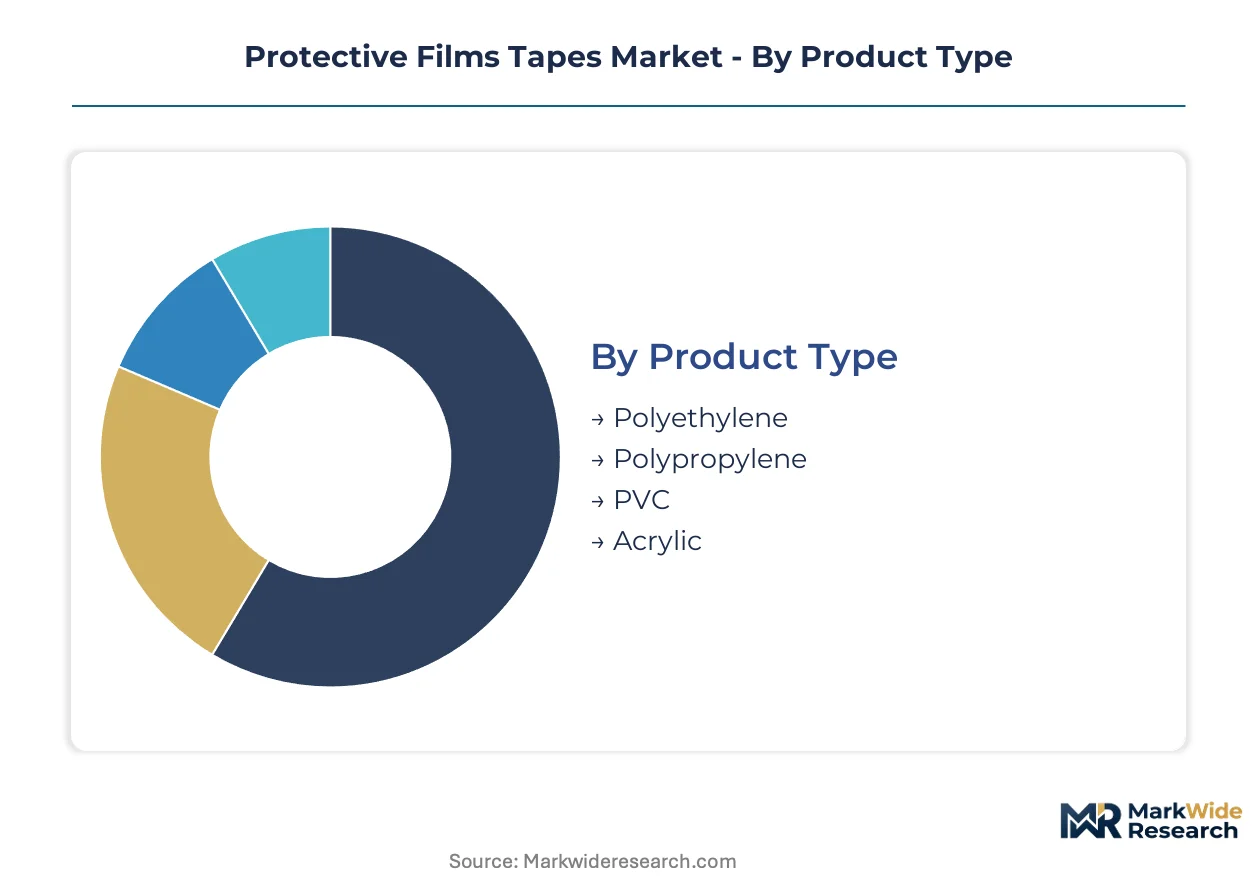
Protective films tapes serve heterogeneous demand profiles across substrate chemistry, surface protection intensity, and supply chain position. Segment boundaries blur where automotive OEMs specify medical-grade cleanliness standards or electronics assemblers adopt construction-thickness films for temporary handling protection.
Product Type:
Substrate chemistry determines optical clarity, removability, and regulatory compliance pathways across end-use specifications.
- Polyethylene:Low-density and linear low-density formulations dominate temporary surface protection for painted automotive panels and appliance finishes. China's Yangtze Delta converters are expanding blown-film extrusion capacity to serve domestic electronics OEMs demanding clean-peel characteristics without adhesive residue.
- Polypropylene:Biaxially oriented structures deliver higher temperature resistance for appliance manufacturing and powder-coating operations. German automotive suppliers specify PP-based paint protection films for bake-cycle compatibility through electrocoat ovens.
- PVC:Calendered constructions provide puncture resistance for construction glass and marble protection where thickness outweighs optical requirements. REACH Annex XVII restrictions on phthalate plasticizers are accelerating formulation switches to bio-based alternatives or TPO substitutes.
- Acrylic:Cast film structures serve premium optical applications including display laminates and lens protection where haze specifications measure below 1%. Mini-LED backplane assembly in Taiwan and South Korea consumes precision acrylic grades with anti-static surface treatments.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
Application:
End-use intensity varies sharply across protection duration, environmental exposure, and failure cost consequences.
- Automotive:Paint protection film deployment spans OEM logistics chains, dealership handling, and aftermarket installation. Japanese and German luxury brands now mandate temporary surface coverage from assembly plant through regional distribution centers, expanding linear footage per vehicle.
- Electronics:Foldable display cover windows and mini-LED diffusion plates require sub-50-micrometer films with anti-static and UV-blocking layers. Taiwan's display panel cluster consumes the highest-specification grades where particle contamination risks destroy thousand-dollar subassemblies.
- Construction:Window glass, aluminum extrusions, and stone surfaces demand thicker mechanical protection during transit and installation. Waterproof PVC variants command margin premiums in high-humidity climates where adhesive failure necessitates costly rework.
- Medical:Sterile barrier packaging and device surface protection require ISO 13485-certified manufacturing with extractables testing. Irish and Swiss converters lead phthalate-free film certification ahead of enforcement milestones.
Automotive commands volume concentration. Electronics is gaining share fastest.
Feature:
Functional coatings and substrate modifications create price-tier differentiation beyond base resin economics.
- Waterproof:Hydrophobic surface treatments and sealed-edge constructions prevent moisture ingress for outdoor construction and marine applications. Medical packaging specifications prioritize sterile barrier integrity where breach risks patient safety.
- UV Resistant:Hindered amine light stabilizers and UV absorber packages extend outdoor durability for automotive paint protection and architectural glass. China's coastal electronics manufacturers specify UV-blocking films to prevent yellowing of display adhesives during assembly.
- Anti-static:Conductive polymer coatings or ionic surfactant treatments dissipate static charges for electronics assembly environments. Taiwan's semiconductor packaging facilities require surface resistivity below 10^11 ohms per square.
- High Adhesion:Aggressive acrylic or rubber-based adhesive systems bond to low-surface-energy substrates including powder-coated metals and olefin plastics. German industrial OEMs specify high-adhesion grades for metal fabrication where mechanical fastening is impractical.
Waterproof holds specification ubiquity. Anti-static is climbing the fastest.
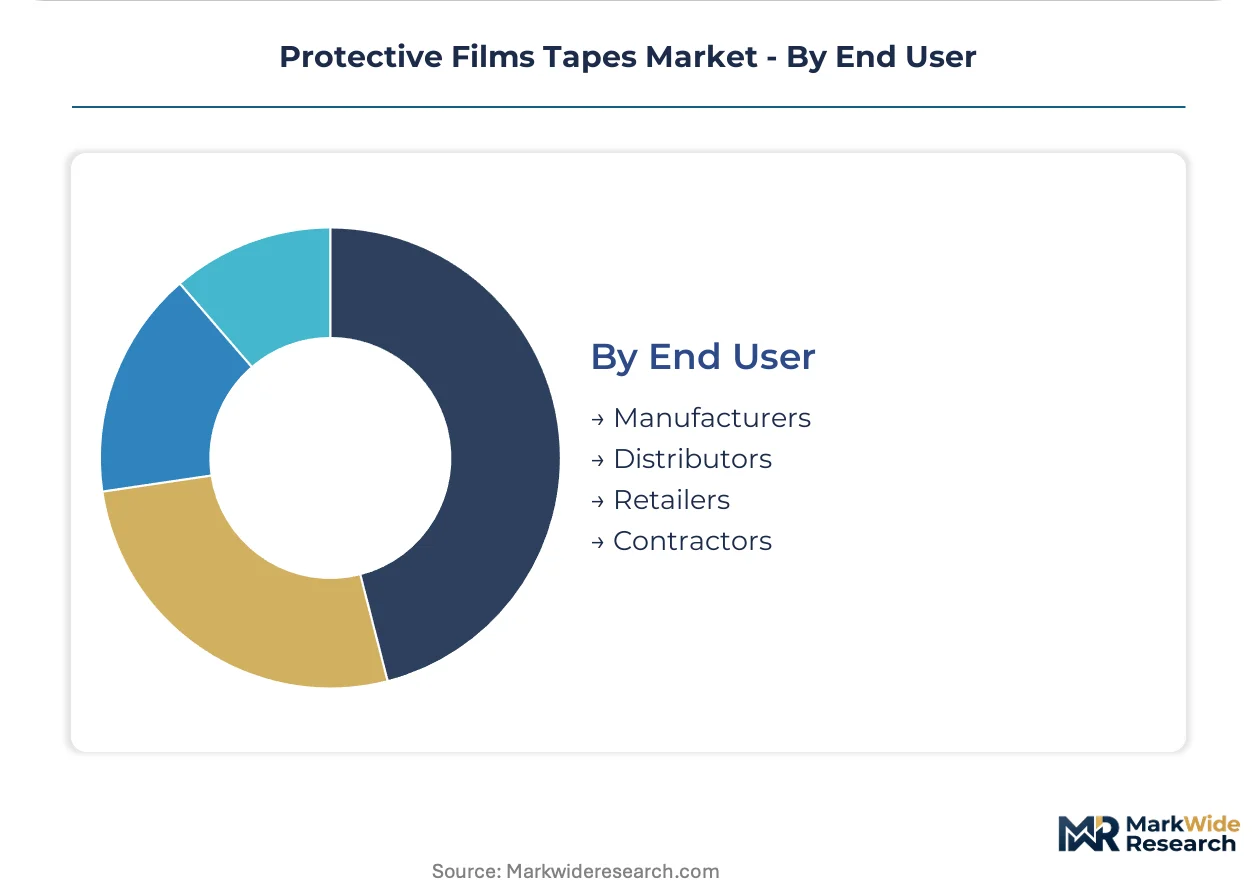
End User:
Supply chain position determines order fragmentation, technical support requirements, and inventory velocity expectations.
- Manufacturers:Direct procurement from film converters with just-in-time delivery to assembly lines. Foxconn and Pegatron facilities mandate 48-hour stocking hubs within 100 kilometers of final assembly.
- Distributors:Inventory aggregation across multiple converter sources with slitting and custom cutting services. European industrial distributors maintain buffer stocks to buffer automotive OEM demand volatility.
- Retailers:Consumer-packaged formats for DIY automotive paint protection and home improvement applications. Online channels are compressing distributor margins for standard specification rolls.
- Contractors:Job-site procurement of construction protection films with credit terms and bulk delivery logistics. Regional construction cycles drive seasonal demand spikes in China's coastal provinces.
Manufacturers anchor volume throughput. Distributors are defending position through value-added slitting services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites China's dominance in electronics-bound film exports. Germany's Rhine-Danube corridor connects automotive coating facilities to assembly plants across Central Europe. South Korea's Busan-New Airport logistics spine enables just-in-time delivery to display panel clusters.
China
Domestic electronics OEMs and automotive assemblers drive polyethylene and polypropylene film consumption along the coastal manufacturing belt. MEE-enforced VOC reduction targets are accelerating solvent recovery investments at Jiangsu and Zhejiang coating facilities. Suzhou and Dongguan host the densest converter clusters serving Foxconn and Pegatron assembly hubs with 48-hour stocking mandates.
Germany
Luxury automotive brands now specify temporary surface protection through entire logistics chains, expanding paint protection film deployment. REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC film formulation switches ahead of SCIP database enforcement. Baden-Württemberg's automotive supply corridor anchors precision coating operations for Porsche and Mercedes-Benz OEM specifications.
United States
Aftermarket automotive paint protection and medical device packaging sustain acrylic and polyethylene film demand. EPA guidelines restricting solvent-based adhesive emissions are pushing converters toward waterborne coating systems. Michigan and Ohio automotive clusters require film suppliers to maintain IATF 16949 certification for direct OEM procurement.
South Korea
Mini-LED backplane assembly and foldable display manufacturing consume precision anti-static film grades with sub-1% haze specifications. MFDS medical device regulations are elevating extractables testing requirements for sterile barrier packaging converters. Gyeonggi Province's display panel cluster sources exclusively from suppliers with 100-kilometer stocking hub commitments.
Japan
Automotive logistics protection and electronics assembly sustain high-adhesion and UV-resistant film specifications. METI industrial standards are tightening adhesive emission requirements for domestic coating operations. Toyota City's supplier ecosystem mandates reel-level digital traceability for quality assurance workflows.
Protective Films Tapes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and adhesive layers. The market structures around three to five multinational platform players with cross-substrate portfolios, mid-scale regional converters with vertical coating capabilities, and niche specialists serving single-application specifications. Consolidation pressure concentrates among electronics and automotive OEM procurement teams shrinking approved vendor lists. Strategic moves center on co-location investments adjacent to assembly plants and solvent-free coating line upgrades for regulatory compliance.
Within the multinational platform tier, 3M leverages adhesive science across multiple substrate platforms while Nitto Denko Corporation anchors precision coating capabilities for East Asian display protection supply chains. Tesa SE occupies a position serving European industrial customers through specialized high-adhesion formulations. These three represent the archetype of cross-regional platform players diversifying across automotive, electronics, and medical end-uses while maintaining captive adhesive development capabilities.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Tesa SE |
| XPEL |
| Saint-Gobain |
| Eastman Chemical Company |
| Lintec Corporation |
| Scapa Group plc |
| Others |
Value Network & Pricing Analysis
Jiangsu Province's coating facility cluster determines downstream pricing power through polyethylene and polypropylene resin conversion capacity. Foxconn and Pegatron procurement teams exploit 48-hour stocking mandates to compress converter margins across China's Yangtze Delta electronics corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified automotive grades from general industrial specifications and commodity construction films. Price differentiation hinges on certification grade and volume commitment scale, with electronics OEMs extracting 15-25% discounts through hub-and-spoke inventory arrangements. Cost compression in standard-grade polyethylene films is intensifying because of naphtha-cracker feedstock volatility. Automotive OEM procurement teams demonstrate lowest price sensitivity due to failure-cost consequences, while construction contractors exhibit highest sensitivity to per-roll pricing.
Supply Chain Analysis
Polyethylene and polypropylene resin feedstocks draw from petrochemical complexes concentrated in China, South Korea, and Saudi Arabia. Acrylic pressure-sensitive adhesive production rests on specialty monomer supplies from US Gulf Coast chemical majors. Single-source vulnerability for high-purity adhesive grades creates structural risk across precision coating operations. Distribution runs through converter-direct relationships with electronics assemblers and automotive Tier 1 suppliers, bypassing traditional industrial distributors for specification-grade films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward electronics OEMs and automotive assemblers consolidating approved vendor lists from 40-60 suppliers to 8-12 strategic partners per region. This concentration forces converters into volume-commitment pricing structures that erode margin flexibility.
For Market Incumbents: Pre-empt margin erosion by securing captive adhesive production capabilities or exclusive monomer supply agreements. Invest in solvent-free coating line upgrades ahead of MEE VOC enforcement milestones to defend position against regulatory-compliant challengers. Establish 100-kilometer stocking hubs adjacent to Foxconn and Pegatron assembly facilities to meet procurement mandates.
For New Entrants and Emerging Players: India's electronics manufacturing zones under Gujarat and Tamil Nadu PLI schemes offer first-mover advantage for local coating operations. Target medical packaging converters in Ireland and Switzerland demanding phthalate-free film certification ahead of REACH Annex XVII enforcement. Pursue direct-to-OEM digital platform strategies for standard automotive paint protection specifications at mid-volume fleet operators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision coating specialists with anti-static and UV-resistant film capabilities serving mini-LED backplane assembly. Long-term viability across the projection horizon rests on regulatory compliance infrastructure and geographic proximity to display panel clusters. Monitor GB standard revision implementation velocity as inflection indicator for domestic Chinese converter consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Line Upgrade | MEE VOC targets in Jiangsu and Zhejiang provinces accelerate capital deployment for compliant production. |
| Phthalate-Free Film Certification | REACH Annex XVII restrictions force formulation switches ahead of SCIP database enforcement milestones. |
| Regional Stocking Hub Establishment | 48-hour delivery mandates from Foxconn and Pegatron facilities require proximity-based inventory positioning. |
| Anti-Static Film Capacity Expansion | Taiwan and South Korea display panel clusters consume highest-specification grades for contamination-sensitive assembly. |
| Digital Platform Direct Sales | Online configurators disintermediate distributors for standard automotive paint protection at fleet operators. |
Research Methodology
Desk research of trade association filings, customs export records, and regulatory enforcement databases preceded structured interviews with coating line operations managers, automotive Tier 1 procurement directors, electronics OEM supply chain planners, and adhesive formulation chemists. Primary fieldwork with Jiangsu and Zhejiang converter facilities cross-checked against secondary validation from ACC and Cefic resin market reports. Bottom-up capacity modeling triangulated with top-down demand aggregation across end-use applications.
Assumptions held fixed include GB standard implementation timelines, REACH enforcement milestones, and naphtha-cracker operating rates across the analysis window. The analytical framework modeled substrate chemistry, application intensity, functional feature tier, and supply chain position segmentation dimensions. CAGRs derived from volume-demand elasticity curves calibrated to electronics assembly expansion and automotive production forecasts. Feedstock price volatility bands and regulatory compliance cost trajectories informed scenario-weighted projections.
Practitioners should monitor MEE enforcement intensity, resin futures curve movements, and OEM vendor list consolidation velocity for early signals of forecast revision. Cross-checking against IHS Markit vehicle production databases and display panel capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Aluminum Foil Tape Market
Tapes
Replica Tapes Market
Tapes
Strapping Tapes Market
Tapes
Seam Tapes Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Global Printed Tape Market
Tapes
India Reflective Tapes Market
Tapes
Differential Tapes Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
India Masking Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Duct Tapes Market