
 Aircraft Aftermarket Parts Market | 2026-2036
Aircraft Aftermarket Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Aftermarket Parts Market Intelligence
The customer base for aircraft aftermarket parts is consolidating as large airline alliances and major MRO providers centralize their procurement strategies. Raytheon Technologies Corporation leverages its extensive OEM portfolio to dominate proprietary engine and avionics components. In contrast, AAR Corp. specializes in independent parts distribution and MRO services, competing on multi-platform support. General Electric Company sustains its market position through its vast installed base of commercial jet engines, ensuring a consistent revenue stream from component replacements.
Aircraft aftermarket parts encompass all components used to maintain, repair, or modify an aircraft after its initial delivery from the manufacturer. These parts must meet strict airworthiness standards, often requiring certification such as a Parts Manufacturer Approval (PMA) from the FAA. Engine components and avionics represent the highest value segments due to their technological complexity and regular maintenance schedules. The commercial aircraft application commands the largest market share, directly linked to the operational tempo of the global passenger and cargo fleet.
The market operates under a stringent regulatory framework enforced by bodies like the US Federal Aviation Administration (FAA), the European Union Aviation Safety Agency (EASA), and the Civil Aviation Administration of China (CAAC). These agencies' certification processes for parts and repair stations directly govern market access and product standards. Stakeholders must navigate the evolving landscape of intellectual property rights versus the push for greater competition from non-OEM part suppliers.
Market Dynamics
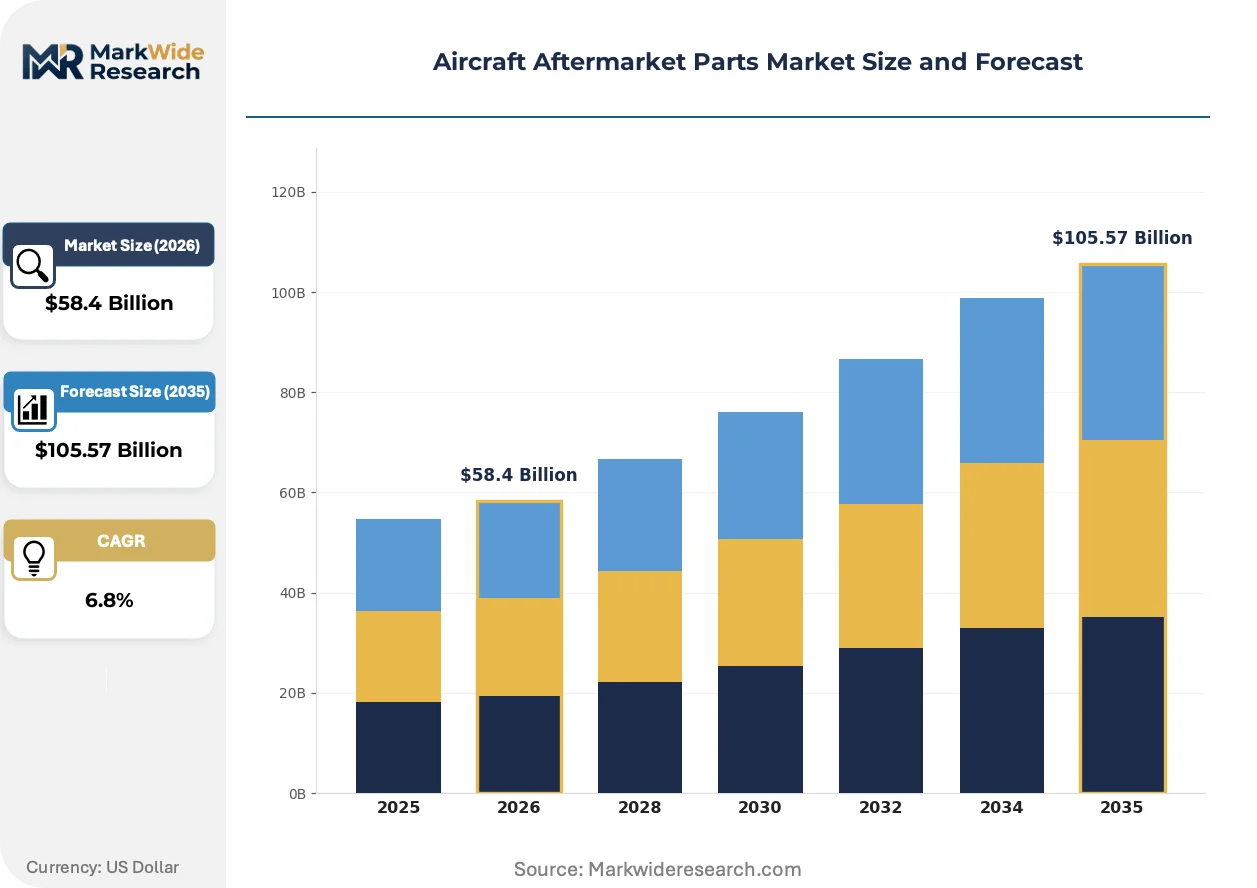
The central dynamic shaping the aircraft aftermarket is the structural tension between Original Equipment Manufacturer (OEM) control over proprietary data and the expanding regulatory acceptance of third-party Parts Manufacturer Approval (PMA) components, which alters supply chain economics.
Growth Catalysts
- Fleet Expansion:The growing global commercial and cargo aircraft fleet, particularly in Asia-Pacific and the Middle East, creates a continuous and expanding need for routine maintenance, component replacement, and overhauls, directly stimulating parts demand.
- PMA Part Acceptance:Increasing validation of PMA parts by regulators like the FAA and EASA provides airlines and MROs with cost-effective, certified alternatives to OEM components, improving part availability and reducing maintenance expenses.
- Advanced Repair Technologies:The development and approval of sophisticated repair techniques for high-value components, such as engine blades and composite structures, extend part life and reduce the need for costly new replacements.
Market Restraints
- OEM Control of Proprietary Parts:OEMs often restrict access to intellectual property and data for critical components like engines and avionics, limiting competition and keeping prices high for a significant portion of the aftermarket.
- Stringent Certification Hurdles:The lengthy and expensive certification processes mandated by bodies such as the FAA and EASA for new parts or repair stations create high barriers to entry for smaller, independent suppliers.
- Volatility in Raw Material Costs:Fluctuations in the price of specialized materials like titanium, aluminum alloys, and carbon composites directly impact the manufacturing cost of aftermarket parts, creating price instability for suppliers and buyers.
Strategic Opportunities
- Digitalization of MRO:The integration of digital twins, predictive analytics, and blockchain for parts traceability offers opportunities to optimize maintenance schedules, reduce aircraft on ground (AOG) time, and enhance supply chain transparency.
- Emerging MRO Hubs:The development of aviation infrastructure in regions like the United Arab Emirates and Singapore creates opportunities for aftermarket suppliers to establish local distribution and repair facilities to serve growing regional fleets.
- Sustainable and Recycled Parts:A growing focus on aviation sustainability opens a market for developing and certifying parts made from recycled materials or through processes with a lower carbon footprint, known as "green parts".
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of certified and experienced MRO technicians, particularly those trained on new-generation aircraft and advanced composite materials, constrains repair capacity and increases labor costs for service providers.
- Intellectual Property Conflicts:Ongoing legal and regulatory battles between OEMs and independent aftermarket suppliers over the rights to repair and produce alternative parts create uncertainty and risk for non-OEM market participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Aftermarket Parts Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Part Type: Avionics, Landing Gear, Engine Components, Hydraulic Systems, Electrical Systems, Fuel Systems Customer Type: Airlines, MRO Providers, Airframe Manufacturers, Leasing Companies, Cargo Operators Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, OEM Networks, Third-Party Sellers Application: Commercial Aircraft, Business Jets, Military Aircraft, Helicopters, Unmanned Aerial Vehicles |
| Companies Covered | General Electric Company, The Boeing Company, AAR Corp., Moog Inc., Bombardier Inc, A J Walter Aviation Limited, Raytheon Technologies Corporation, GKN Aerospace, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Aftermarket Parts Market Strategic Shifts & Innovations
Digitalization and sustainability mandates are fundamentally altering the operational and economic models of aircraft parts management. These forces compel a shift from traditional inventory-based approaches to more data-driven, on-demand service and material provisioning across the MRO ecosystem.
Additive manufacturing, or 3D printing, enables the on-demand fabrication of non-critical cabin parts and complex tooling. MRO providers and airlines are steadily adopting this for specific applications to reduce lead times. This capability is electrifying the supply chain by allowing for decentralized production, which minimizes reliance on extensive, centralized parts inventories and lengthy global logistics.
The European Union Aviation Safety Agency (EASA) is increasing its focus on lifecycle emissions and material traceability for aircraft components. This regulatory pressure necessitates more detailed documentation and verification for parts, particularly those with recycled or composite materials. The engine and structural components segments are most impacted, requiring suppliers to invest in enhanced tracking systems to ensure compliance.
Airlines are progressively adopting parts-by-the-hour (PBH) contracts and accessing shared inventory pools instead of purchasing parts outright. This model transfers inventory risk and management to OEMs or large MRO providers, disrupting traditional component distributors. The shift is most pronounced with new-generation aircraft entering service with operators in North America and Europe.
Aircraft Aftermarket Parts Market Segmentation
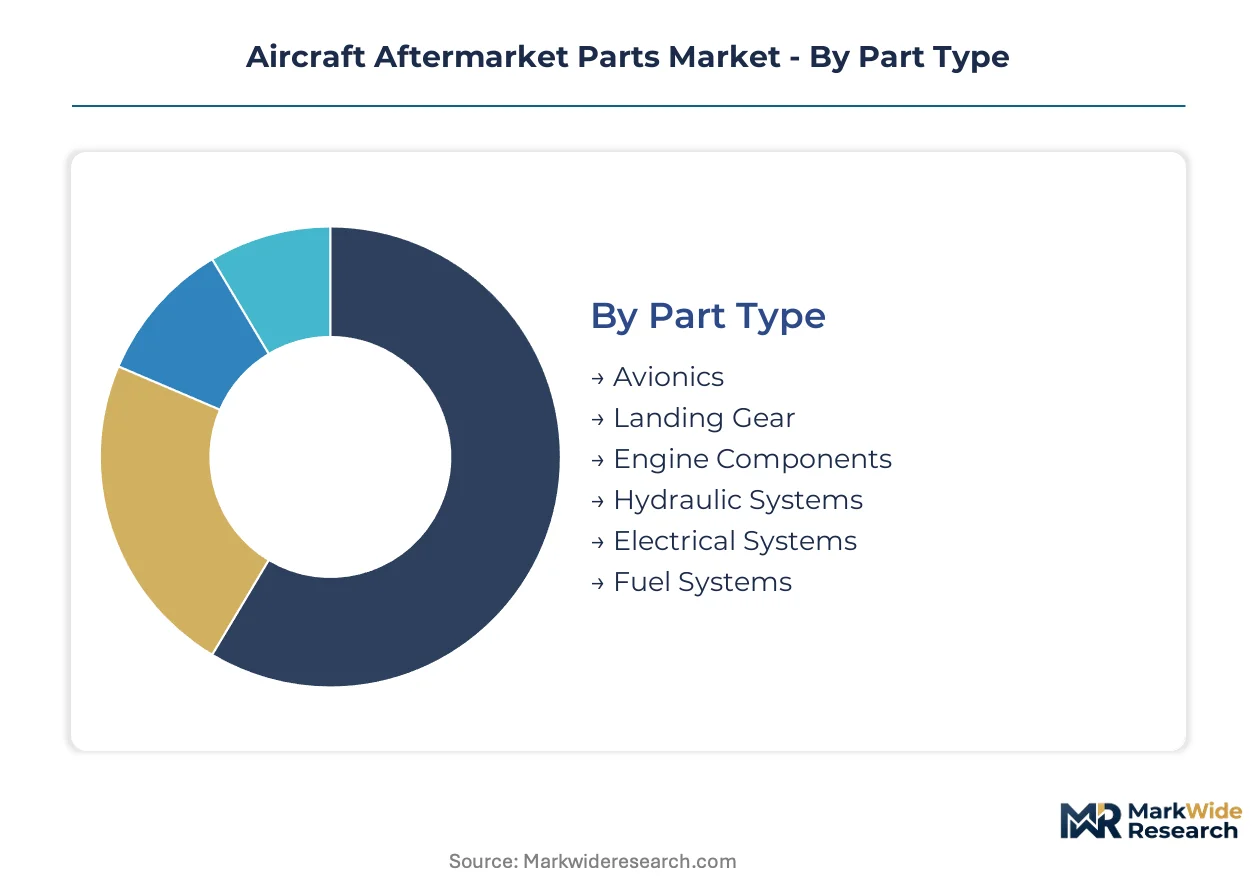
Understanding the aircraft aftermarket parts market requires a detailed segmentation across critical dimensions. This analysis dissects the market by part type, customer base, distribution channels, and application, revealing distinct value pools and operational dynamics. Each segment exhibits unique demand drivers and supply chain characteristics.
Part Type:
The replacement cycles and upgrade demands for aircraft components significantly influence aftermarket parts procurement strategies.
- Engine Components:Critical parts like blades and combustors undergo rigorous maintenance and frequent replacement due to extreme operational stresses. Demand concentrates in commercial aircraft MRO, driven by scheduled overhauls to maintain fleet airworthiness.
- Avionics:Sophisticated electronic systems for navigation, communication, and flight control require periodic software updates and hardware upgrades. Demand expands in North America and Europe, propelled by technological advancements and regulatory mandates.
- Landing Gear:Structural assemblies for takeoff and landing, requiring scheduled overhauls and component replacement.
- Hydraulic Systems:Components like pumps and actuators facilitate flight control, needing replacement due to fluid contamination.
- Electrical Systems:Wiring harnesses, generators, and circuit breakers are essential for power distribution, requiring routine inspection.
- Fuel Systems:Pumps, valves, and tanks manage fuel storage and delivery, requiring high reliability and replacement.
Volume placements concentrate in Engine Components; the faster expansion belongs to Avionics.
Customer Type:
Customer type dictates procurement scale, technical specifications, and the urgency of parts delivery across the aftermarket ecosystem.
- Airlines:Commercial air carriers operate extensive fleets, necessitating large-volume procurement of standardized and proprietary parts. Airlines in Asia-Pacific and the Middle East represent significant demand, driven by fleet expansion.
- MRO Providers:Specialized firms offer maintenance, repair, and overhaul services for various aircraft types, requiring diverse parts inventories and rapid supply chain access. Independent MROs expand capabilities in Europe and North America, leveraging multi-platform support.
- Airframe Manufacturers:OEMs procure aftermarket parts for warranty repairs and service bulletins, provisioning spare parts.
- Leasing Companies:Require parts for aircraft returning off-lease or for modifications, focusing on cost-effective components.
- Cargo Operators:Dedicated freight carriers prioritize parts availability to minimize downtime, sourcing components for older airframes.
Procurement patterns vary significantly across Airlines and MRO Providers, reflecting their distinct operational models.
Distribution Channel:
Supply concentration within the distribution channels influences pricing power and the availability of certified aftermarket components.
- OEM Networks:Original Equipment Manufacturers distribute proprietary parts through authorized channels, providing direct support and technical documentation. This channel controls critical engine and avionics components for new-generation aircraft platforms in North America.
- Distributors:Independent distributors stock and supply a wide array of parts from multiple manufacturers, serving MROs and smaller airlines. These distributors manage logistics for regional operators across Europe and emerging markets.
- Direct Sales:Manufacturers or MROs sell parts directly to end-users, often for high-value components or specialized kits.
- E-Commerce Platforms:Online marketplaces facilitate buying and selling non-critical parts and tooling, improving transparency and accessibility.
- Third-Party Sellers:Independent entities source and resell parts, including surplus or overhauled components, contributing to market liquidity.
Channel efficiency is paramount for Distributors, while OEM Networks emphasize direct relationships and proprietary offerings.
Application:
The operational volume and mission profiles of different aircraft applications drive specific demand patterns for aftermarket parts.
- Commercial Aircraft:Passenger and cargo planes represent the largest market share due to high flight frequencies and extensive global fleets. Demand is particularly strong in the Asia-Pacific region, fueled by fleet expansion and rising air travel.
- Military Aircraft:Fighters, bombers, and transport planes are characterized by specialized, high-performance parts and long operational lifespans. Procurement is driven by defense budgets and fleet readiness requirements, especially in the United States and European NATO countries.
- Business Jets:Private and corporate jets require specialized parts for lower-volume fleets, focusing on reliability and rapid turnaround.
- Helicopters:Rotorcraft parts demand is influenced by diverse applications like emergency services and offshore transport.
- Unmanned Aerial Vehicles:The emerging UAV segment requires lightweight, high-performance parts for drones in surveillance and defense.
The operational tempo of Commercial Aircraft drives consistent demand, whereas Military Aircraft represents specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the aircraft aftermarket parts market is particularly evident in regions with expanding fleets and robust MRO infrastructure. This surge is driven by continuous maintenance needs and the increasing acceptance of cost-effective certified alternatives. Aviation hubs globally are becoming focal points for parts procurement and service delivery.
United States
The United States drives significant aftermarket demand from its vast commercial and military aircraft fleets. The US Federal Aviation Administration (FAA) mandates rigorous certification for all aftermarket parts and repair stations. Major MRO operations in places like Dallas-Fort Worth support extensive aircraft maintenance and component replacement.
United Arab Emirates
The United Arab Emirates shows strong demand for aftermarket parts, fueled by its strategic position as an aviation hub. The country's General Civil Aviation Authority (GCAA) ensures compliance with international airworthiness standards. Dubai's Al Maktoum International Airport develops advanced MRO facilities to serve regional and global fleets.
China
China's expanding commercial aircraft fleet generates substantial demand for engine components and avionics. The Civil Aviation Administration of China (CAAC) rigorously certifies parts and repair organizations. Major MRO centers in Shanghai support the rapid growth of domestic and international air traffic.
Germany
Germany represents a significant European hub for advanced MRO services and high-value component replacements. European Union Aviation Safety Agency (EASA) regulations influence part certification and repair station approvals across the country. Frankfurt Airport's extensive MRO facilities cater to a large volume of commercial aircraft operations.
Singapore
Singapore maintains a robust aftermarket parts demand, driven by its established MRO ecosystem and regional connectivity. The Civil Aviation Authority of Singapore (CAAS) ensures stringent airworthiness and maintenance standards. Seletar Aerospace Park hosts numerous MRO providers, attracting significant investment in repair technologies.
Aircraft Aftermarket Parts Market Key Industry Players
North American original equipment manufacturers (OEMs) anchor one tier, leveraging their extensive proprietary portfolios; European and Asian independent MROs hold another, focusing on multi-platform support. The market exhibits a tiered structure, with OEMs controlling critical parts and independent aftermarket suppliers offering certified alternatives. These archetypes include integrated OEM service providers, specialized independent MROs, and global parts distributors. Companies pursue portfolio diversification and strategic partnerships to enhance market reach and service capabilities.
Within the integrated OEM service provider archetype, the United States-based General Electric Company exemplifies sustained market position through its vast installed base of commercial jet engines. Similarly, Raytheon Technologies Corporation, also from the United States, leverages its extensive OEM portfolio to dominate proprietary engine and avionics components. In contrast, AAR Corp., another United States entity, sits within the specialized independent MRO and parts distribution segment, competing on multi-platform support and rapid supply chain access. These companies represent distinct approaches to capturing value in the aftermarket.
| Leading Market Players |
|---|
| General Electric Company |
| The Boeing Company |
| AAR Corp. |
| Moog Inc. |
| Bombardier Inc |
| A J Walter Aviation Limited |
| Raytheon Technologies Corporation |
| GKN Aerospace |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
European Union Aviation Safety Agency (EASA) mandates for lifecycle emissions and material traceability gate qualified supply and influence premium pricing for certified green parts. This regulatory push forces suppliers to invest in enhanced tracking systems, impacting overall supply chain costs.
Pricing Analysis
Volume placements in engine components often operate on lower margins compared to high-margin, specialized avionics components. Pricing for proprietary OEM parts remains premium, driven by brand value and integrated service bundles. Cost compression for standardized components intensifies due to increasing Parts Manufacturer Approval (PMA) acceptance by regulators. Airlines demonstrate higher price sensitivity for routine maintenance parts, while airframe manufacturers prioritize certified OEM components for warranty repairs.
Supply Chain Analysis
The supply of critical raw materials like titanium and aluminum alloys draws from a concentrated global base, including key producers in Russia and China. Component manufacturing for complex systems like avionics relies heavily on specialized facilities in the United States and Europe. OEM control over intellectual property for critical parts presents a structural risk, limiting independent supplier access. Distribution runs primarily through OEM networks for proprietary items and independent distributors for multi-platform support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft aftermarket parts market is becoming a vertical-integration race, with players actively pursuing deeper control over MRO services and parts manufacturing.
For Market Incumbents: Extend proprietary data access to authorized MRO partners, reinforcing OEM network control against independent PMA suppliers. Invest heavily in advanced repair technologies and certification processes for high-value components, mitigating raw material cost volatility. Consolidate market share by acquiring smaller, specialized MRO providers with unique capabilities in emerging regions. Leverage existing customer relationships to offer comprehensive parts-by-the-hour contracts.
For New Entrants and Emerging Players: Launch through specialized distribution channels targeting cost-sensitive airlines in emerging MRO hubs like the United Arab Emirates. Focus on developing certified "green parts" or components manufactured via additive manufacturing for non-critical cabin parts, leveraging sustainability mandates. Penetrate the market by offering multi-platform support for older aircraft fleets, where OEM support may be limited. Develop digital platforms for transparent parts traceability and efficient inventory management.
For Investors and Strategic Acquirers: Regulatory approval of new additive manufacturing processes for critical engine components is the leading indicator that market dynamics are shifting towards decentralized production. Long-term viability remains strong due to continuous fleet expansion and stringent airworthiness standards. Target independent MROs with strong technical expertise in complex component repairs or companies specializing in predictive analytics for maintenance optimization. Evaluate firms with strong intellectual property in sustainable materials or advanced repair technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand PMA part certification | Improves cost-effectiveness for airlines, enhancing competition against OEM components. |
| Invest in digital twin technology | Optimizes maintenance schedules for MRO providers, reducing aircraft on ground time. |
| Develop sustainable aviation parts | Addresses EASA lifecycle emissions mandates, opening new market segments for green components. |
| Establish regional distribution centers | Accelerates parts delivery for MROs in emerging hubs like Singapore. |
| Acquire specialized MRO providers | Broadens multi-platform support capabilities for OEMs, securing aftermarket revenue streams. |
Research Approach
FAA airworthiness directives, EASA certification documents, and IATA reports formed the secondary backbone, validated through primary interviews with MRO executives and airline procurement managers. Discussions also included regulatory officials from the Civil Aviation Administration of China and independent distributors. This approach enabled bottom-up and top-down triangulation of market data.
Historical trendline analysis across the modeling period informed the forecast framework, segmenting the market by part type, customer type, and regional MRO infrastructure development. Forecasts also considered the impact of advanced repair technologies and PMA part acceptance. Compound annual growth rates were derived from regression analysis of historical data and projected global fleet expansion.
Geopolitical instability affecting air travel, unforeseen regulatory changes, and major technological disruptions are the dominant revision risks to these forecasts. All projections reflect assumptions documented within the analytical framework. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Aerostructures Market