
 Guns and Accessories Market | 2026-2036
Guns and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Guns and Accessories Market Intelligence
The fragmentation of the buyer base across specialized sport shooting disciplines is decoupling purchasing decisions from traditional brand loyalties. In this environment, GLOCK, Inc. leverages its reputation for reliability in the law enforcement handgun segment. SIG SAUER, Inc. competes on modularity and system-level contracts with military clients. Sturm, Ruger & Co., Inc. sustains its market presence through a diverse portfolio targeting the civilian personal defense and hunting markets.
Guns and accessories encompass firearms designed to expel a projectile via combustion and the auxiliary equipment that enhances their function, safety, or accuracy. This includes devices with specific rifling twist rates, such as 1:7 or 1:9, to stabilize different bullet weights for optimal performance in military operations or sport shooting. The handgun product type continues to dominate sales volumes for personal defense, while rifles see strong demand from sport shooting and hunting applications. Within accessories, high-margin growth is found in advanced optics like scopes and laser sights, outpacing mature categories such as standard holsters.
Market access is governed by a complex web of national laws, with bodies like the US firearms regulator setting domestic sales standards and the German KBA influencing export criteria for European manufacturers. International frameworks, including firearms marking protocols promoted by organizations like the WHO to aid in trafficking studies, also shape manufacturing and traceability requirements. Future competitive advantage depends on navigating divergent state-level and national regulations on product features and sales channels.
Market Dynamics
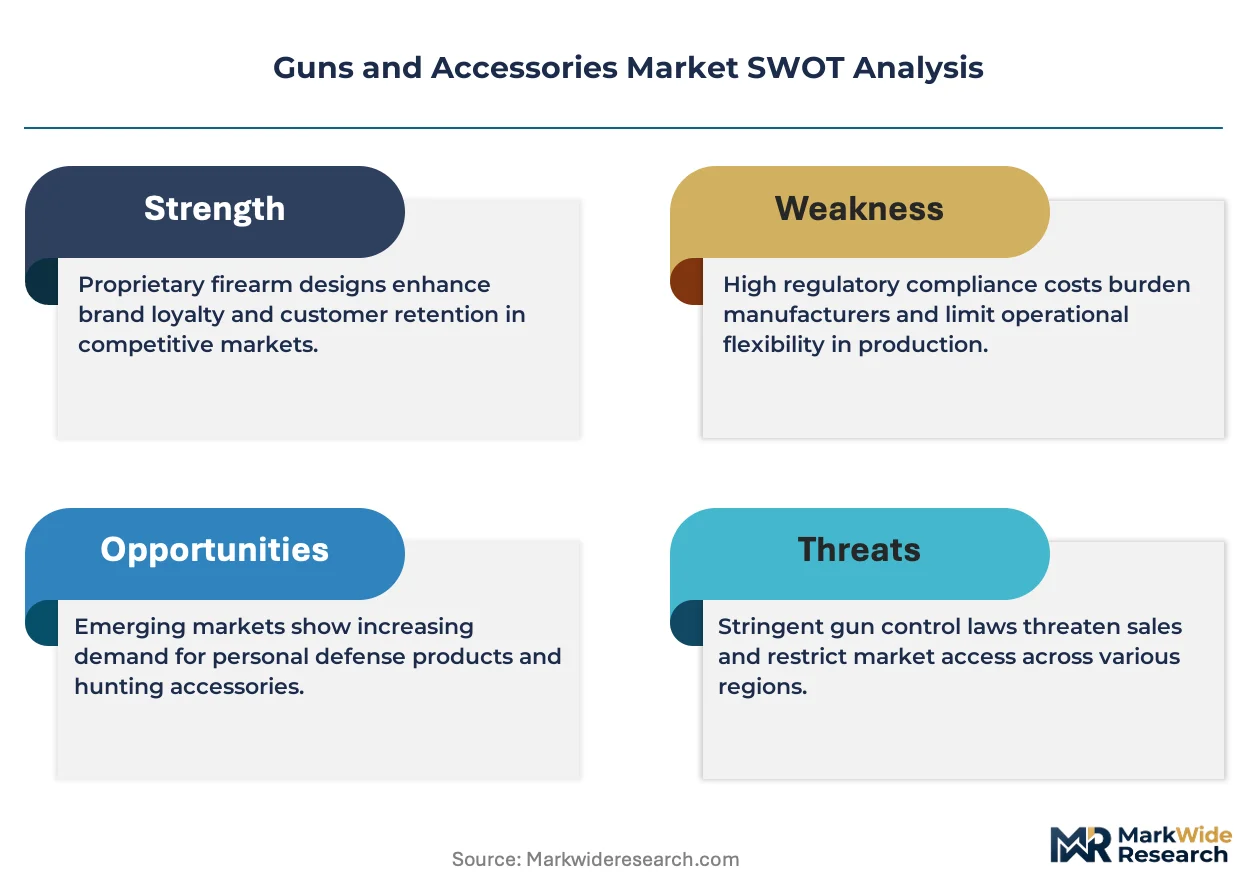
The market's central dynamic is the tension between a growing user demand for modular, highly customizable firearm systems and an increasingly complex and fragmented regulatory landscape. This conflict shapes product development, market access, and competitive strategy across all segments.
Growth Catalysts
- Modular Platforms:The proliferation of modular chassis systems for rifles and handguns allows the sport shooting community to tailor platforms for specific disciplines, driving sales of both core firearms and aftermarket components.
- Personal Defense Demand:Civilian demand for personal defense, particularly for compact handguns in the United States, remains a primary volume driver, supporting consistent sales in the market's largest geographic segment.
- Advanced Accessories:High-margin growth is found in advanced accessories, especially electronic optics and laser sights, which offer significant performance enhancements for recreational, competitive, and tactical users alike.
Market Restraints
- Import and Export Controls:Stringent regulations, such as criteria enforced by Germany's KBA on firearm exports or specific import restrictions in other nations, create significant compliance costs and limit market access for manufacturers.
- Divergent State-Level Laws:In key markets like the United States, a patchwork of inconsistent state and local laws regarding firearm features, magazine capacity, and sales processes creates complexity for national distribution.
- International Protocols:Frameworks promoted by bodies like the WHO to improve firearm marking and tracing for trafficking studies add manufacturing and logistical burdens, increasing the cost of compliance for global producers.
Strategic Opportunities
- Smart Accessories Integration:The convergence of firearms with digital technology presents opportunities in smart accessories, such as electronic triggers, shot counters, and integrated training systems for military and law enforcement clients.
- Emerging Sport Shooting Markets:Cultivating sport shooting communities in regions outside of North America, particularly in parts of Eastern Europe and Asia, represents a key vector for long-term expansion.
- Polymer and Composite Innovation:Continued material science advancements in polymers and composites offer pathways to develop lighter, more durable, and cost-effective firearm components, appealing to both civilian and professional end-users.
Industry Challenges
- Supply Chain Traceability:Implementing robust serialization and tracking systems to comply with diverse international marking protocols demands significant capital investment in manufacturing and data management infrastructure.
- Navigating Public Perception:Manufacturers must manage intense public and political scrutiny, which can lead to sudden shifts in market access, banking relationships, and advertising platform availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guns and Accessories Market |
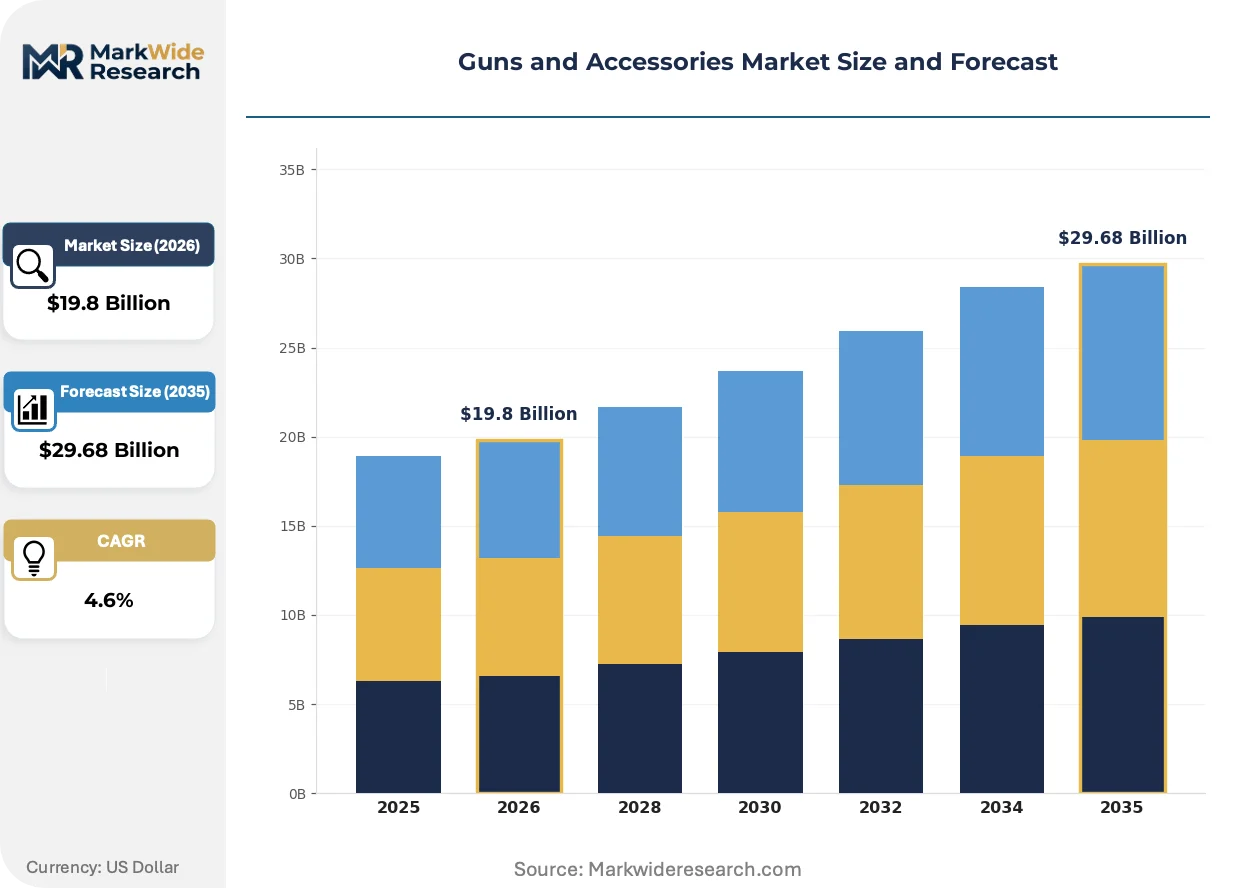
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handguns, Rifles, Shotguns, Air Guns, Submachine Guns Accessory Type: Scopes, Holsters, Magazines, Grips, Laser Sights Application: Hunting, Sport Shooting, Law Enforcement, Personal Defense, Military Operations End User: Security Agencies, Law Enforcement Units, Recreational Shooters, Licensed Dealers, Military Personnel |
| Companies Covered | Fabbrica D'Armi Pietro Beretta S.p.A., GLOCK, Inc., SIG SAUER, Inc., American Outdoor Brands Inc., Remington Ammunition, Smith & Wesson, Heckler & Koch, FN Herstal, Sturm, Ruger & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guns and Accessories Market Strategic Shifts & Innovations
Product evolution is defined by a push toward lighter materials and system-level modularity. This innovation occurs within a difficult environment where international regulatory frameworks and divergent national laws create significant operational and compliance hurdles for manufacturers.
Platform Modularity
Advanced polymer-frame construction and modular chassis systems provide a foundational platform for extensive user customization. These technologies are rapidly being adopted by both civilian sport shooters seeking performance advantages and law enforcement agencies looking for adaptable service weapons. The ability to easily swap components like barrels, grips, and slides is overtaking the market for traditional, fixed-configuration firearms, especially in the handgun and modern rifle segments.
Traceability Mandates
International firearms marking protocols, encouraged by organizations like the WHO, are formalizing traceability requirements. This shift compels manufacturers to implement more sophisticated serialization on major components, increasing production complexity and data retention obligations. Companies targeting global military and law enforcement contracts are most affected, investing in laser-marking technologies and secure databases to meet evolving procurement standards.
Specialization in Buying Behavior
A fragmentation of the buyer base is occurring, driven by the growth of specialized sport shooting disciplines. This trend disrupts the generalized inventory models of traditional big-box retailers, favoring specialist dealers and direct-to-consumer e-commerce channels that cater to niche component demands. This behavioral shift is most pronounced in the United States, where a large and diverse civilian market actively seeks out specific parts for custom builds.
Guns and Accessories Market Segmentation
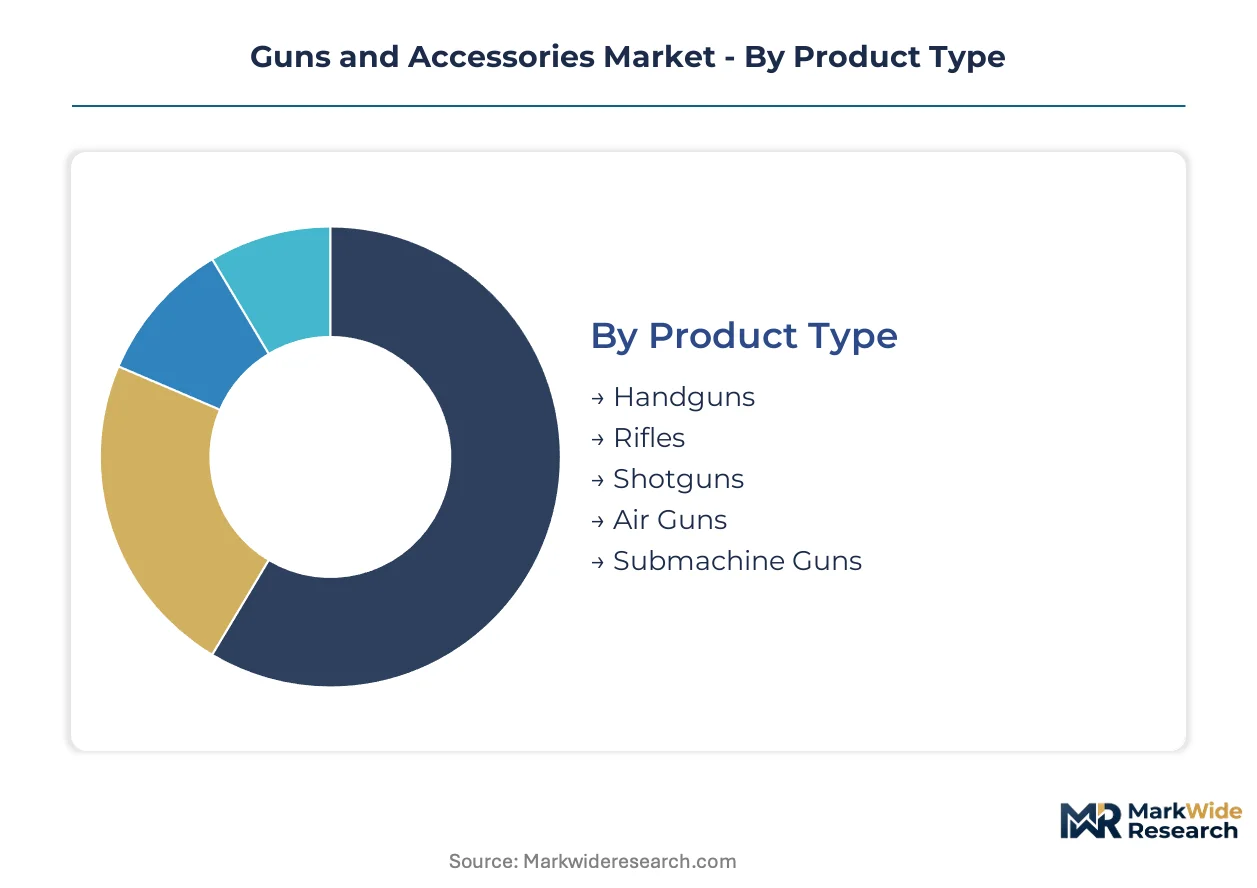
Market segmentation clarifies the distinct product preferences and operational demands driving the guns and accessories sector. Understanding these specialized segments enables manufacturers to align product development with specific user requirements, from ballistic performance to tactical utility. This differentiation is critical for competitive advantage.
Product Type:
Product differentiation centers on inherent design mechanics and intended operational specifications. These distinctions dictate material choices, manufacturing, and regulatory classifications.
- Handguns:Compact firearms for single-hand operation, often with polymer frames for reduced weight. Demand concentrates in the United States for personal defense and concealed carry, driven by portability.
- Rifles:Characterized by rifled barrels and two-handed operation, offering enhanced accuracy and range. Sport shooting communities and hunters value modular rifle platforms for adaptability and precision.
- Shotguns:Smoothbore firearms primarily used for firing multiple pellets, valued for hunting small game and home defense.
- Air Guns:Propel projectiles using compressed air or gas, widely used for recreational shooting, pest control, and competitive target sports.
- Submachine Guns:Automatic or select-fire carbines firing pistol cartridges, primarily deployed by military and law enforcement for close-quarters combat.
Mature deployment sits with traditional rifles. Newer deployment is concentrated in advanced polymer-frame handguns.
Accessory Type:
Accessory types are defined by their specific function in enhancing firearm performance, user comfort, or operational safety. These auxiliary components cater to diverse tactical and recreational needs.
- Scopes:Optical sighting devices to magnify targets, improving accuracy at longer ranges for hunting and precision shooting. Advanced electronic optics represent high-margin growth for competitive and tactical users.
- Laser Sights:Devices projecting a laser beam onto a target, aiding rapid target acquisition and aiming, especially in low-light conditions. Integration with modern handguns for personal defense shows significant demand.
- Holsters:Carried on the body or in vehicles, these secure firearm retention devices ensure safe transport and quick access.
- Magazines:Detachable or fixed containers holding ammunition, critical for firearm capacity and rapid reloading.
- Grips:Ergonomic components attached to the firearm frame, improving handling, stability, and shooter comfort.
Growth in accessory type is expanding most quickly within advanced optics. Standard holsters represent a more mature market segment.
Application:
Market applications delineate the primary purpose for which firearms and accessories are acquired. Each application carries distinct performance requirements and regulatory considerations.
- Personal Defense:Firearms used for self-protection against threats, driving demand for compact, reliable handguns. Civilian demand in the United States remains a primary volume driver.
- Sport Shooting:Encompasses competitive and recreational target practice across disciplines, fostering demand for customizable firearm platforms and specialized accessories. Modular chassis systems fuel this segment's expansion.
- Hunting:Involves firearms for harvesting game animals, requiring specific calibers and rifle types for diverse environments.
- Law Enforcement:Equips police and security forces with service weapons and specialized accessories for public order and threat response.
- Military Operations:Involves procurement of advanced weapon systems and tactical gear for national defense and combat scenarios.
Personal defense applications exert significant influence on handgun sales. Military operations dictate specifications for advanced weapon systems.
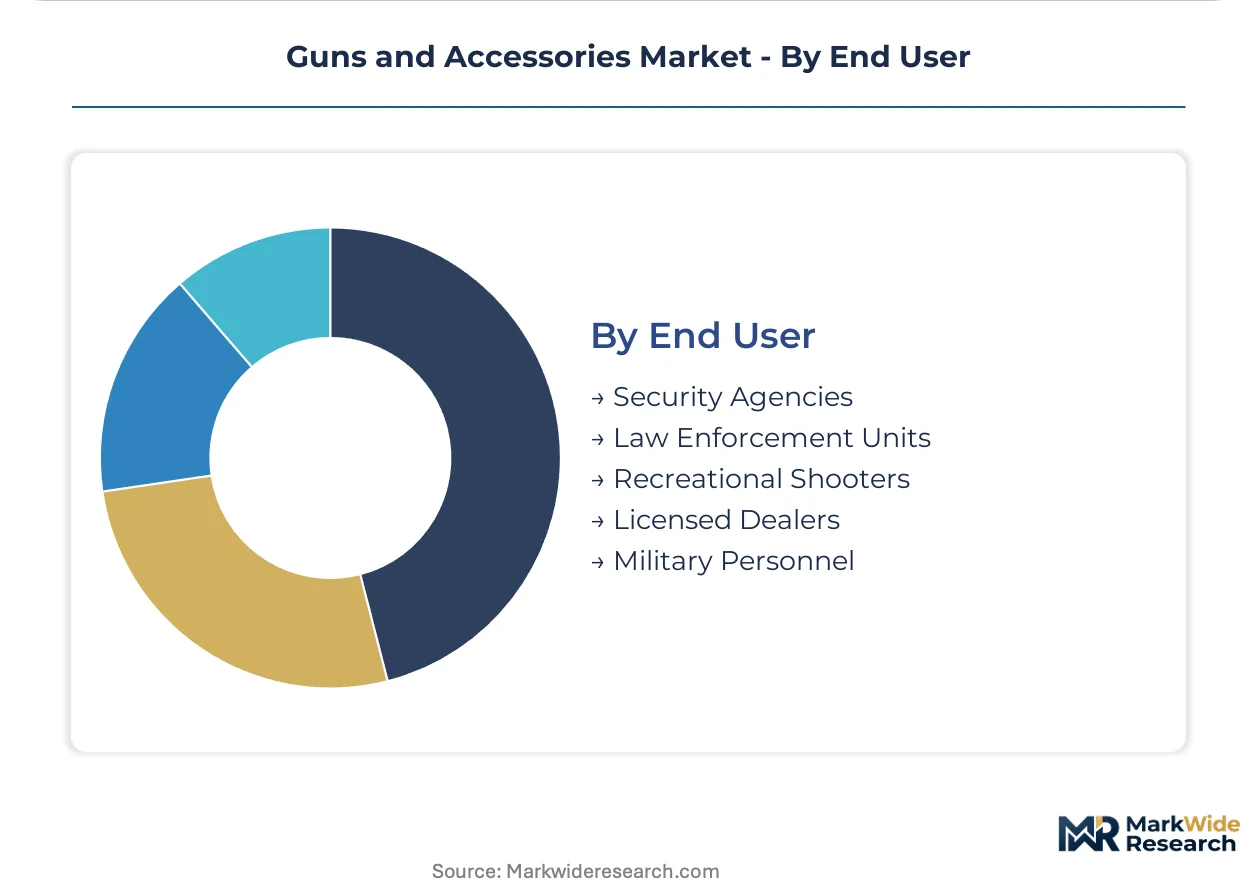
End User:
End-user segmentation categorizes consumers by institutional affiliation or individual purchasing intent, influencing product features and procurement channels. Each group presents unique compliance needs.
- Recreational Shooters:This broad category includes individuals participating in sport shooting, target practice, and hobbyist collecting. Their specialized buying behavior drives demand for customizable components.
- Military Personnel:Armed forces members require robust, reliable, and specialized weapon systems and accessories for combat and training. Procurement involves large-scale, system-level contracts.
- Law Enforcement Units:Police departments and government agencies acquire firearms and tactical gear for public safety and operational duties.
- Security Agencies:Private and public security firms procure specialized equipment for protection services, prioritizing reliability and ease of use.
- Licensed Dealers:Businesses authorized to sell firearms and accessories, serving as primary distribution channels for civilian and professional users.
The segment of recreational shooters represents the largest volume. Military personnel procurement represents the fastest-growing trajectory for advanced systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for guns and accessories remains particularly strong in the United States, driving significant market activity across various applications. This market's global footprint extends to other key nations where civilian ownership, law enforcement procurement, and sport shooting communities shape local dynamics. Regulatory environments vary significantly, impacting product availability and market access for manufacturers.
United States
Civilian demand for personal defense handguns and customizable rifle platforms for sport shooting drives significant sales volumes. The US firearms regulator sets domestic sales standards, influencing product features and distribution channels. Manufacturing clusters in states like Arizona and Texas continue to innovate in polymer-frame designs and modular firearm systems.
Germany
Stricter import controls and export criteria enforced by the KBA significantly influence product availability for European manufacturers. Law enforcement and military contracts represent a stable demand segment, alongside a niche market for precision sport shooting equipment. The industrial region of Baden-Württemberg hosts several prominent firearm and accessory manufacturers, focusing on quality and engineering.
Brazil
Growing civilian demand for personal defense and increasing investment in law enforcement capabilities are expanding the market. National regulations govern firearm ownership and sales, with recent policy shifts impacting market accessibility. Manufacturing facilities in São Paulo and Rio Grande do Sul contribute to domestic supply and regional exports.
Australia
Sport shooting and hunting applications drive consistent demand for rifles and specialized accessories within a highly regulated environment. State and federal firearm laws dictate licensing, storage, and permissible firearm types. Local manufacturers and distributors in New South Wales and Victoria cater to the specific needs of licensed firearm owners.
Guns and Accessories Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced accessory integration and niche modular components. The competitive structure is tiered, reflecting diverse operational scales and specialization levels. Strategic archetypes include legacy firearm manufacturers, specialized accessory providers, and system integrators. Portfolio diversification into advanced optics and strategic partnerships with material science firms represent dominant competitive moves.
On the premium-tier vector, GLOCK, Inc. and SIG SAUER, Inc. exemplify manufacturers known for their robust firearm platforms. Sturm, Ruger & Co., Inc. anchors a segment focused on a broad civilian market, offering diverse product lines. These companies often leverage their brand reputation and established distribution networks to maintain market presence across various end-user segments.
| Leading Market Players |
|---|
| Fabbrica D'Armi Pietro Beretta S.p.A. |
| GLOCK, Inc. |
| SIG SAUER, Inc. |
| American Outdoor Brands Inc. |
| Remington Ammunition |
| Smith & Wesson |
| Heckler & Koch |
| FN Herstal |
| Sturm, Ruger & Co., Inc. |
| Others |
Cost & Logistics Intelligence
Industrial metal prices, particularly for high-grade steel and specialized alloys, cascade through the manufacturing supply chain directly influencing the final pricing tiers of firearms and accessories. This impact is most pronounced in premium-tier weapon systems and advanced optical components, where material purity and precision machining are critical cost drivers.
Pricing Analysis
High-volume civilian sales for personal defense applications often prioritize affordability, while specialized sport shooting and military procurement focus on performance and customization, commanding higher margins. The dominant pricing model is per-unit transactional, with long-term contracts for institutional buyers. Brand reputation and the level of customization offered drive significant price differentiation. Pricing pressure stems from the rising costs of regulatory compliance, including traceability mandates and divergent state-level requirements. Recreational shooters represent the most price-sensitive segment, whereas military personnel prioritize performance specifications over initial cost.
Supply Chain Analysis
Regional distribution centers facilitate efficient delivery to licensed dealers and specialized retailers, forming a hub-and-spoke distribution pattern across key markets. Geographic supply concentration for manufacturing resides significantly in the United States, Germany, and Brazil. The supply chain relies heavily on specialized alloys, polymer composites, and advanced optical components. A structural risk involves regulatory restrictions on the cross-border movement of firearms and their major components, creating logistical hurdles. Distribution runs through a hybrid model of established licensed dealer networks and specialized e-commerce platforms for aftermarket accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant cost-of-compliance story, where adherence to international firearms marking protocols, encouraged by organizations like the WHO, creates a barrier-to-entry moat for compliant players capable of robust serialization and tracking.
For Market Incumbents:Lock in existing market share by investing in advanced polymer R&D and acquiring niche accessory manufacturers to counter the fragmentation of the buyer base. Leverage established brand reputation and channel control through existing dealer networks to mitigate the impact of regulatory shifts. Diversify product lines to address both high-volume personal defense and high-margin specialized sport shooting segments, ensuring sustained revenue streams.
For New Entrants and Emerging Players:Specialized sport shooting enthusiasts represent an underserved buyer archetype, offering white-space opportunities in modular component ecosystems and smart accessory integration. Focus on developing aftermarket components for popular platforms in the United States, as this segment is highly active and receptive to customization. A direct-to-consumer e-commerce model, coupled with strong community engagement, provides an effective go-to-market angle for niche products.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers with proven compliance expertise and a focus on long-term viability, driven by sustained demand for personal defense and sport shooting. Target companies specializing in advanced optics or polymer manufacturing, as these segments offer high-margin growth and technological innovation. The harmonization of international traceability standards will serve as a key signal to watch for significant market consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Optics R&D | Enhance accuracy and user experience for competitive shooters and tactical operators. |
| Modular Platform Development | Cater to customization demand from sport shooting communities and law enforcement agencies. |
| Polymer Material Science Investment | Develop lighter, more durable firearm components for civilian and professional end-users. |
| International Compliance Infrastructure | Meet evolving traceability mandates for global military and law enforcement contracts. |
| Direct-to-Consumer Channel Expansion | Capture niche component sales from specialized buyers and hobbyist collectors. |
Research Approach
Document review covered national firearms regulator reports, German KBA export data, WHO firearms marking guidelines, and industry trade publications, complemented by interviews with firearm design engineers, law enforcement procurement officers, licensed firearm dealers, and sport shooting association representatives. This approach combined primary insights with secondary validation, utilizing both bottom-up and top-down triangulation methods.
The analytical framework cross-referenced historical market trends with expert panel input to project future dynamics across the analysis window. Segmentation dimensions modeled included product type, accessory type, application, end-user, and regional market. Compound Annual Growth Rates were derived from a comprehensive analysis of historical growth patterns and anticipated shifts in civilian handgun sales volumes and military procurement budgets.
Revisions become necessary when significant shifts in national firearms legislation or international trade agreements materialize. Forecasts reflect assumptions regarding economic stability and regulatory continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
Cluster Munitions Market