
 Aircraft Weapons Market | 2026-2036
Aircraft Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Weapons Market Outlook
Platform lifecycle sustainment revenue is reshaping profitability structures across the aircraft weapons value chain. Lockheed Martin leverages its hypersonic program portfolio to anchor long-term service contracts with the US Air Force. RTX Corporation sustains dominance in guided munitions through vertical integration of seeker manufacturing and propulsion systems. BAE Systems competes on electronic warfare integration, positioning its precision-strike packages for NATO interoperability requirements.
Aircraft weapons comprise ordnance systems designed for aerial delivery against ground, maritime, or airborne targets, typically incorporating guidance packages with sub-meter accuracy thresholds, hardened electronics for high-g maneuvering, and compatibility with MIL-STD-1760 aircraft interface standards. Missiles command the largest value share within weapon type segmentation due to recurring precision-guided munitions replenishment cycles following sustained operational tempo. Drones represent the fastest-expanding platform type as armed unmanned systems displace manned strike missions in contested airspace environments. The production stage captures disproportionate margin pools relative to design or testing phases because of multi-year fixed-price contracting structures and lot-based economies of scale.
The US Department of Defense's National Defense Authorization Act shapes contractor investment priorities through directed energy and hypersonic weapons funding mandates, while NATO's STANAG interoperability standards dictate seeker and datalink compatibility requirements for cross-alliance operational integration. The US State Department's International Traffic in Arms Regulations constrains technology transfer pathways, limiting foreign market access for sensitive guidance and propulsion subsystems. Stakeholders must monitor congressional appropriations committee markups for munitions procurement line items and allied nation joint development program commitments to anticipate demand inflection points.
Market Dynamics
The Pentagon's National Defense Authorization Act funding mandates are redirecting contractor R&D priorities toward hypersonic propulsion and autonomous targeting architectures, compressing traditional munitions development cycles while extending platform lifecycle sustainment obligations.
Growth Catalysts
- Hypersonic weapons acceleration:The US Department of Defense's directed energy and hypersonic funding lines under successive National Defense Authorization Acts are pulling prime contractors into multi-year development commitments with guaranteed production options.
- NATO STANAG interoperability mandates:Cross-alliance operational integration requirements are standardizing seeker and datalink specifications, creating captive demand for certified subsystem suppliers across member air forces.
- Armed unmanned platform proliferation:Military operators are displacing manned strike missions with armed drone sorties in contested airspace, expanding precision-guided munitions replenishment cycles for unmanned combat air vehicles.
Market Restraints
- Seeker component supply concentration:Advanced infrared and millimeter-wave seeker manufacturing remains captive to a limited supplier base in the United States and select allied nations, creating single-source vulnerability for guided munitions integrators.
- International Traffic in Arms Regulations friction:The US State Department's ITAR constraints on guidance and propulsion technology transfers limit foreign market access for sensitive subsystem exports, compressing addressable market scope for domestic primes.
- Tungsten and rare earth input volatility:Penetrator warhead fabrication and high-performance magnet production depend on concentrated rare earth supply chains, exposing cost structures to geopolitical supply disruptions.
Strategic Opportunities
- Indigenous European missile autonomy:France, Germany, and Italy are accelerating joint development programs for sovereign precision-strike capabilities, creating white space for European subsystem suppliers outside US technology transfer pathways.
- Dual-use autonomous targeting convergence:Machine vision and edge computing advances from commercial autonomous vehicle development are migrating into military target recognition architectures, lowering algorithm development costs for mid-tier contractors.
- Allied joint procurement platforms:NATO's evolving framework for pooled munitions acquisition is opening new channel structures for standardized precision-guided weapon lots across multiple member air forces.
Industry Challenges
- MIL-STD-1760 integration complexity:Legacy aircraft interface standard compliance for new munitions requires extensive airworthiness recertification, extending fielding timelines for modified weapon packages on operational fighter fleets.
- Hypersonic thermal protection engineering scarcity:The specialized materials science and aerothermal modeling expertise required for maneuvering reentry vehicle development remains concentrated within a narrow talent pool, constraining program staffing scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Weapons Market |
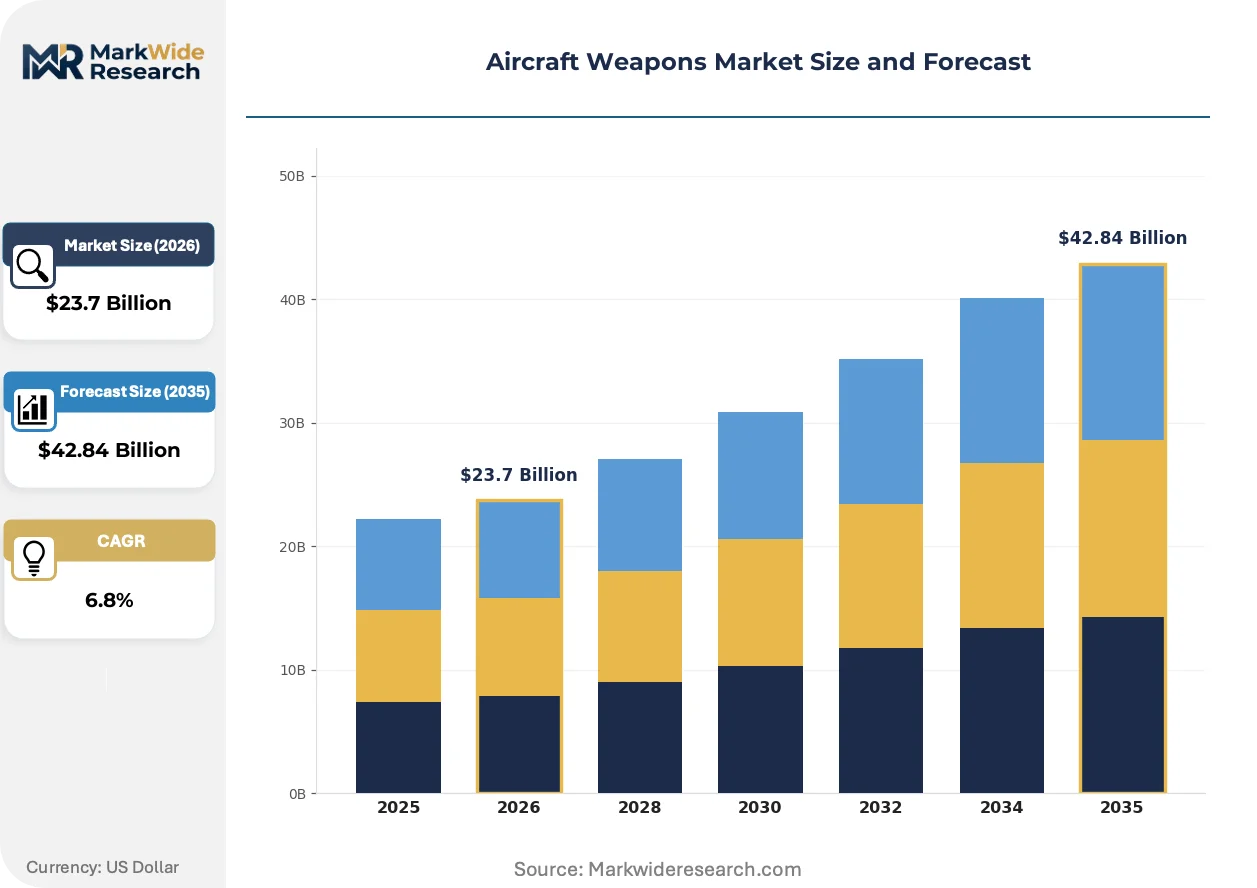
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Missiles, Bombs, Guns, Rockets Platform Type: Fighters, Bombers, Drones, Helicopters Manufacturing Stage: Design, Development, Production, Testing Application: Tactical Operations, Strategic Bombing, Reconnaissance, Training |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Boeing Defense, Space & Security, General Dynamics Corporation, Northrop Grumman Corporation, MBDA Inc., Thales Group, BAE Systems, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Weapons Market Strategic Shifts
Active electronically scanned array seeker architectures and additive manufacturing of propulsion components are compressing development cycles while reshaping contractor specialization boundaries across the precision-strike value chain.
Multi-mode seeker technology is migrating from single-sensor infrared or radar homing to fused electro-optical and millimeter-wave guidance packages. The US Air Force and Navy are fielding these architectures on next-generation air-to-surface munitions with compressed acquisition timelines. This convergence is enabling engagement of relocatable targets under degraded visibility conditions while reducing weapon inventory diversity burdens.
The European Union's proposed Munitions Production Act and associated defense procurement directives are accelerating cross-border joint contracting mechanisms for standardized precision-guided munitions. Industrial consequence includes mandatory European content thresholds and security of supply certifications for critical subcomponents. NATO's eastern flank members are responding fastest, restructuring national armaments procurement to align with EU-wide framework contracts.
Air force procurement offices are consolidating precision-guided munitions acquisition under multi-year indefinite-delivery contracts with performance-based logistics riders. Traditional transactional lot purchases are yielding to availability-guaranteed arrangements where contractors assume inventory and obsolescence risk. This behavioral shift is most visible in US Air Force Air Combat Command contracting for standoff weapon families, where sustainment revenue now exceeds production margin pools.
Aircraft Weapons Market Segmentation
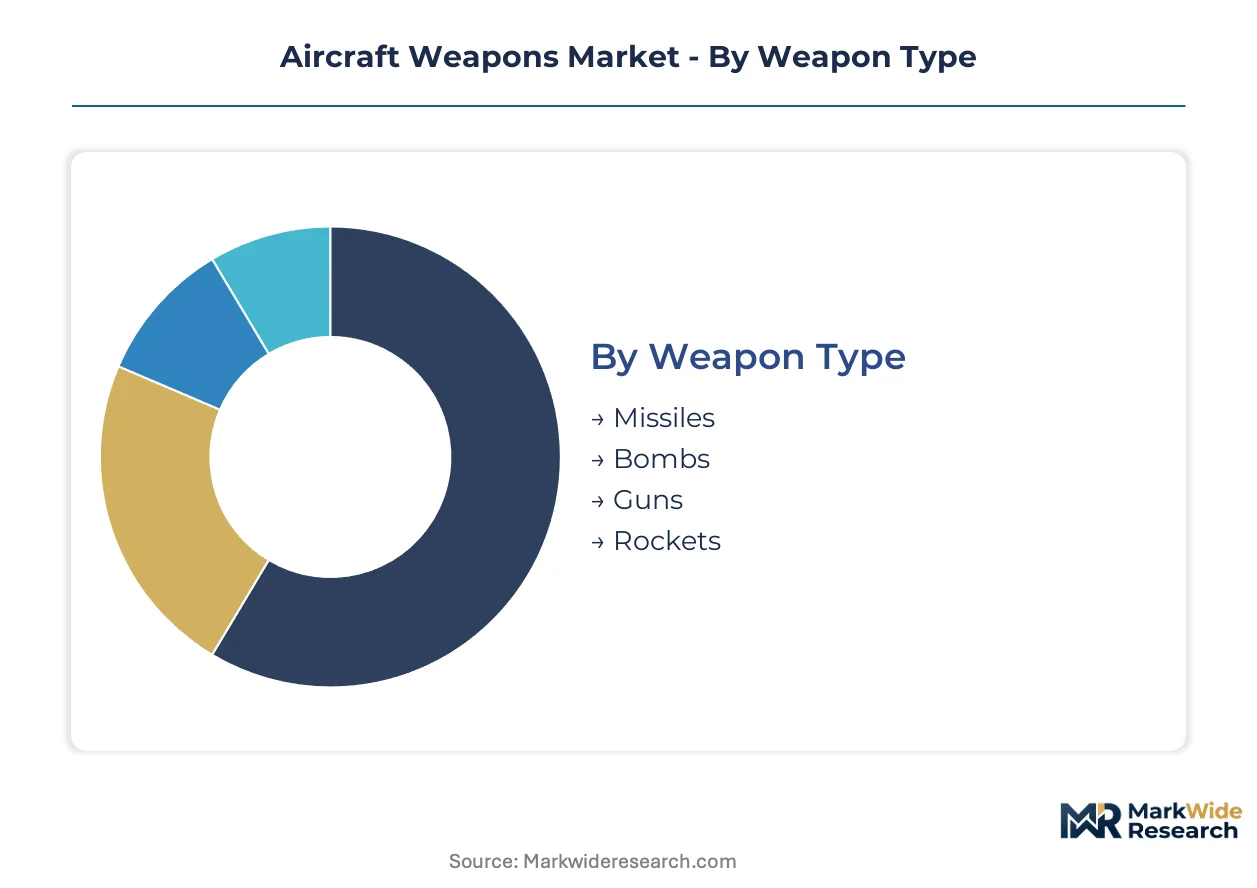
Weapon categorization in aircraft ordnance determines procurement cycles, platform compatibility requirements, and contractor specialization boundaries. Segmentation clarity enables prime contractors to align development roadmaps with operator mission profiles and regulatory compliance frameworks.
Weapon Type:
Mature precision-guided architectures dominate military procurement budgets, while emerging directed-energy and hypersonic categories reshape long-term capability planning.
- Missiles:Self-propelled guided munitions incorporating active or semi-active seeker architectures for beyond-visual-range engagement. The US Air Force and Navy concentrate replenishment orders here following sustained operational tempo in Indo-Pacific theater rotations. NATO STANAG interoperability mandates standardize datalink protocols across member inventories.
- Bombs:Unguided and precision-guided gravity munitions with JDAM or Paveway kit integration for meter-accuracy delivery. Demand clusters in allied European air forces modernizing legacy stockpiles under EU Munitions Production Act directives. Fixed-price multi-year contracts compress margin variability for integrators.
- Guns:Aircraft-mounted automatic cannons and rotary systems firing 20-30mm ammunition for close air support missions. Rotary-wing and light attack platforms drive procurement in Middle Eastern and North African operator fleets.
- Rockets:Unguided and guided rocket artillery systems for area suppression and light vehicle engagement. Helicopter and drone platform integration expands addressable volume for lightweight precision variants.
Missiles retain volume leadership; rockets hold the steepest expansion curve.
Platform Type:
Application context spans contested airspace penetration, standoff strike, and persistent surveillance-with-lethality missions across manned and unmanned architectures.
- Fighters:Multirole and air-superiority aircraft carrying internal and external precision-strike payloads. The US Air Force Air Combat Command and allied NATO operators prioritize beyond-visual-range missile integration for Pacific deterrence postures.
- Bombers:Long-range strategic platforms delivering heavy payload masses against fixed and relocatable targets. US Air Force Global Strike Command modernization programs drive hypersonic weapon carriage requirements.
- Drones:Armed unmanned systems displacing manned sorties in high-threat environments. US Central Command operational patterns and allied reconnaissance-strike integration programs accelerate precision-guided munitions consumption per sortie.
- Helicopters:Rotary-wing gunships and utility platforms for close air support and anti-armor missions. European and Asia-Pacific land force aviation commands sustain rocket and gun ammunition replenishment cycles.
Fighters anchor procurement value; drones are climbing the fastest.
Manufacturing Stage:
Margin distribution concentrates in production and sustainment phases, with design and testing phases capturing lower absolute returns despite higher technical barriers.
- Design:Conceptual and detailed engineering activities establishing weapon performance specifications and interface standards. US Department of Defense milestone decision authority governs funding release for new-start programs.
- Development:Prototype fabrication, subsystem integration, and flight testing prior to production authorization. Hypersonic and autonomous targeting programs extend development timelines through multiple test article iterations.
- Production:Lot-based manufacturing with economies of scale and multi-year fixed-price contracting structures. Prime contractors assume inventory risk under performance-based logistics arrangements with US Air Force Material Command.
- Testing:Qualification, reliability verification, and operational assessment activities. Range access constraints and environmental clearance requirements create scheduling bottlenecks for new weapon fielding.
Production captures margin leadership; testing presents the steepest resource intensity curve.
Application:
Mission profiles determine weapon packaging, seeker configuration, and rules-of-engagement compliance requirements across combat and non-combat employment.
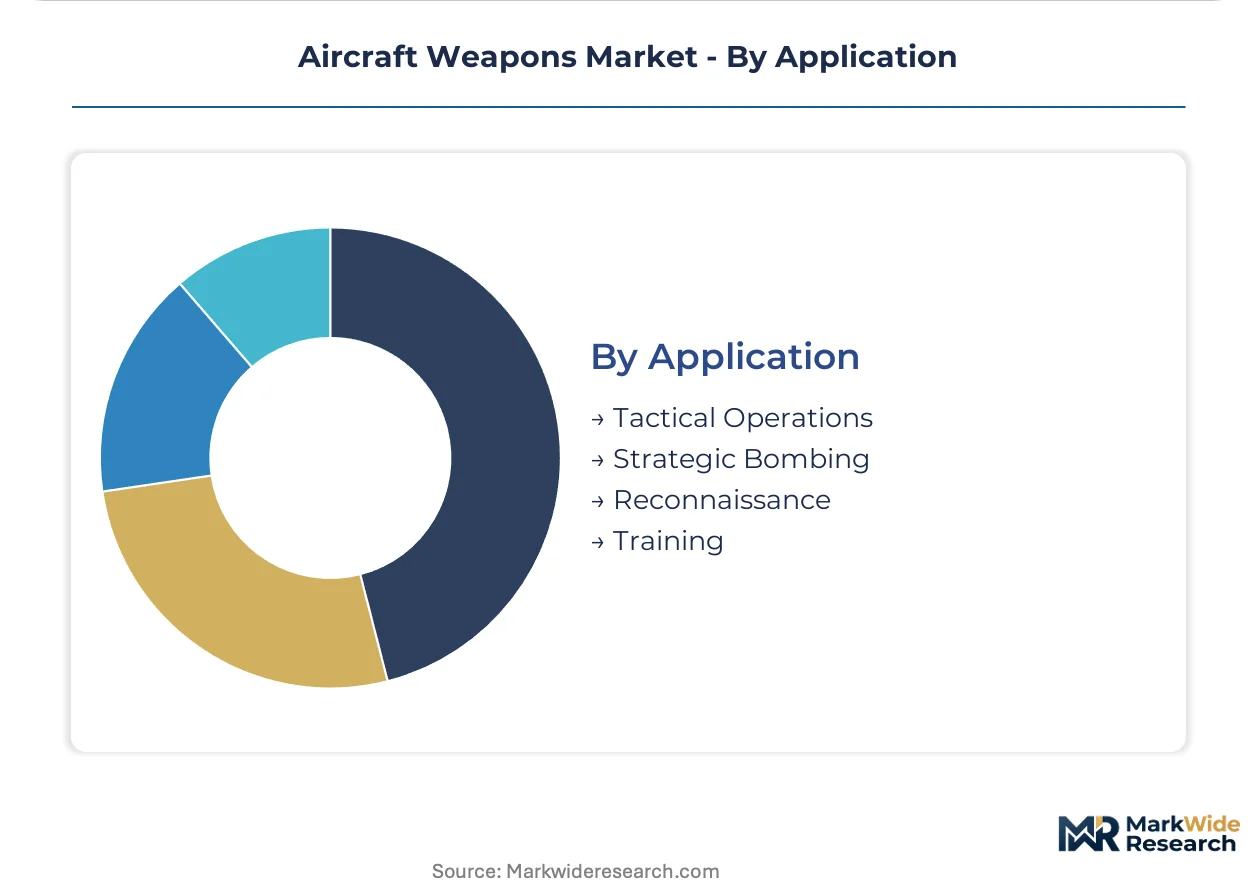
- Tactical Operations:Time-sensitive targeting and close air support against mobile and concealed objectives. US joint terminal attack controller integration demands precise collateral damage estimation capabilities.
- Strategic Bombing:Deep strike against fixed infrastructure and hardened facilities. Penetrator warhead and fuzing specialization concentrates in Air Force Global Strike Command requirements.
- Reconnaissance:Sensor-equipped platforms with defensive or deterrent armament for contested environment survival. Intelligence-surveillance-reconnaissance community procurement prioritizes endurance over payload mass.
- Training:Inert and reduced-range practice munitions for pilot proficiency and logistics rehearsal. Allied NATO air forces consolidate acquisition under pooled procurement frameworks.
Tactical operations retain sortie volume leadership; reconnaissance gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes hypersonic propulsion and autonomous targeting architectures, while European allies emphasize NATO STANAG interoperability and sovereign precision-strike capabilities, and Indo-Pacific operators concentrate on standoff munitions for maritime strike missions.
United States
The Pentagon's National Defense Authorization Act directs multi-year funding toward hypersonic weapons and directed-energy programs, compressing traditional munitions development cycles. FAA and State Department ITAR constraints govern technology transfer pathways for sensitive guidance subsystems. Defense industrial concentration clusters in California's aerospace corridor and Texas, where prime contractors anchor long-term sustainment contracts with Air Force Material Command.
United Kingdom
Royal Air Force procurement prioritizes beyond-visual-range missile integration for carrier strike and NATO collective defense missions. Ministry of Defence acquisition frameworks emphasize sovereign capability preservation through BAE Systems-led development programs. Industrial activity concentrates in Lancashire and the Home Counties, where electronic warfare and precision-strike packaging capabilities support NATO interoperability requirements.
Germany
Bundeswehr modernization drives demand for precision-guided munitions compatible with Eurofighter Typhoon and Tornado fleets, with emphasis on penetrator warheads for hardened target engagement. KBA and federal defense procurement offices coordinate joint development programs with France and Italy under EU Munitions Production Act directives. Defense manufacturing concentrates in Bavaria and Baden-Württemberg, where subsystem suppliers align with NATO STANAG standardization mandates.
France
Direction Générale de l'Armement accelerates sovereign missile autonomy through MBDA-led programs for air-launched nuclear and conventional strike capabilities. ANSM and defense export control frameworks govern technology transfer for seeker and propulsion subsystems. Industrial capability clusters in Île-de-France and Provence-Alpes-Côte d'Azur, where Dassault Aviation integration demands drive precision-strike packaging requirements.
Israel
Israeli Air Force operational tempo in contested airspace sustains precision-guided munitions replenishment cycles, with emphasis on compact seeker architectures for fighter and drone integration. Ministry of Defense procurement prioritizes indigenous development of electro-optical and millimeter-wave guidance packages. Defense technology concentration in Haifa and the Central District supports autonomous targeting algorithm development for export-oriented subsystem suppliers.
Aircraft Weapons Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The aircraft weapons market structures around prime contractors with multi-decade platform relationships and mid-tier specialists with captive subsystem expertise. Three archetypes dominate: vertically integrated primes controlling seeker-to-airframe integration, component specialists with MIL-STD-1760 certification authority, and sustainment-focused service providers assuming inventory risk under performance-based logistics arrangements. Competitive moves center on multi-year indefinite-delivery contract capture and strategic positioning for NATO joint procurement frameworks.
Among US-based defense primes, Lockheed Martin Corporation and RTX Corporation exemplify the integrated-systems archetype, anchoring hypersonic and precision-guided munitions portfolios respectively. BAE Systems occupies a position within the European sovereign-capability tier, representing the cross-border interoperability specialist model. These three entities collectively illustrate how geographic origin and corporate structure map to divergent competitive positioning across the Atlantic defense procurement divide.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Boeing Defense, Space & Security |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| MBDA Inc. |
| Thales Group |
| BAE Systems |
| Raytheon Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
California's aerospace corridor dominates precision-guided munitions manufacturing, where concentrated prime contractor capacity translates directly into pricing leverage over NATO allied procurement offices seeking MIL-STD-1760 certified weapon systems. Long-term fixed-price contracting structures at Lockheed Martin and RTX facilities compress margin volatility for high-volume production lots while amplifying cost pass-through power for specialized seeker subsystems.
Pricing Analysis
Multi-year indefinite-delivery contracts with performance-based logistics riders dominate procurement structures, replacing transactional spot purchases across US Air Force Material Command programs. Price differentiation rests on seeker sophistication tiers—infrared homing packages command substantial premiums over unguided gravity munitions—and volume scale thresholds for allied joint procurement frameworks. Cost compression in standard precision-guided bomb categories intensifies as European suppliers enter NATO pooled acquisition channels, while prime contractors retain pricing power in hypersonic and autonomous targeting architectures. Allied air forces exhibit highest price sensitivity for replenishment munitions, whereas US Strategic Command programs demonstrate lowest elasticity for next-generation standoff weapons.
Supply Chain Analysis
RTX Corporation and Northrop Grumman hold captive capacity for advanced millimeter-wave seeker fabrication, concentrating specialized manufacturing in Arizona and Massachusetts facilities. The aircraft weapons supply chain draws from concentrated rare earth processing in China for high-performance magnet production, tungsten supply from Vietnam and Russia for penetrator warheads, and semiconductor-grade gallium arsenide from US and Japanese foundries. Single-source vulnerability for infrared detector arrays creates structural risk exposure, as ITAR constraints block alternative sourcing pathways. Distribution runs through defense prime contractor direct channels to national armaments procurement offices, with limited aftermarket or third-party logistics penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypersonic propulsion maturation and autonomous targeting algorithm deployment are compressing traditional munitions development cycles, creating asymmetric opportunity windows across defense industrial tiers. The National Defense Authorization Act's directed energy funding mandates accelerate capability discontinuities that favor contractors with established Air Force platform relationships.
For Market Incumbents: Harden seeker manufacturing supply chains through backward integration into gallium arsenide wafer processing or long-term offtake agreements with sole-source detector suppliers. Expand Air Force sustainment contract capture to anchor lifecycle revenue against hypersonic program development cost overruns. Lockheed Martin's hypersonic portfolio demonstrates how multi-decade platform relationships translate into captive production slots.
For New Entrants and Emerging Players: Build out machine vision algorithm capabilities targeting drone-integrated precision-strike applications, where commercial autonomous vehicle technology migration lowers barrier thresholds. European sovereign missile autonomy programs under EU Munitions Production Act directives represent the most penetrable geography, with France-Germany-Italy joint development creating white space outside US technology transfer pathways. Pursue subsystem certification authority for NATO STANAG datalink compatibility as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-tier specialists with captive MIL-STD-1760 certification authority and established Air Force testing range access. Long-term viability hinges on sustainment revenue exposure exceeding production dependency. Acquisition targets should demonstrate performance-based logistics contract tenure with Air Force Material Command. Congressional appropriations committee markups for munitions procurement line items serve as the critical signal for demand inflection detection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hypersonic Thermal Protection Development | Captures Air Force Global Strike Command modernization funding under successive NDAA authorizations. |
| Multi-Mode Seeker Integration | Enables engagement of relocatable targets under degraded visibility for Indo-Pacific theater requirements. |
| Performance-Based Logistics Expansion | Shifts inventory and obsolescence risk to contractors while securing multi-year revenue visibility. |
| NATO STANAG Certification Investment | Unlocks pooled procurement frameworks across eastern flank member air forces. |
| Autonomous Targeting Algorithm Development | Leverages commercial machine vision advances for reduced military algorithm development costs. |
Study Parameters
Operator-level perspectives from Air Force program executives, defense procurement officers at NATO member ministries, prime contractor business development leads, and seeker subsystem engineering directors anchored the qualitative base. Secondary validation drew from Department of Defense budget justification materials, Congressional Research Service munitions procurement reports, EU defense procurement directive filings, and NATO STANAG standardization documentation. Bottom-up segment sizing triangulated against top-down defense expenditure macro models.
Scenario-bracketing around hypersonic program acceleration timelines and autonomous targeting fielding schedules structured the analytical framework across the projection horizon. Segmentation dimensions modeled include weapon type, platform architecture, manufacturing stage, and mission application profile. CAGRs derived from production lot forecast trajectories, allied joint procurement commitment schedules, and replenishment cycle frequency assumptions for sustained operational tempo environments.
Sensitivities concentrate around Congressional appropriations markups, rare earth supply disruption events, and ITAR regulatory reinterpretations affecting technology transfer pathways. Forecasts embed assumptions regarding Air Force modernization program continuity and NATO collective defense spending commitments. Quarterly review of NDAA funding line item adjustments, EU Munitions Production Act implementation progress, and seeker component supplier financial disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Space Weapons Market