
 Supersonic and Hypersonic Weapons Market | 2026-2036
Supersonic and Hypersonic Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Supersonic and Hypersonic Weapons Market Analytics
Aerospace engineering talent scarcity is redrawing competitive boundaries across the supersonic and hypersonic weapons landscape. Lockheed Martin Corporation leverages decades of hypersonic test-flight experience to sustain technology leadership in boost-glide architectures. Raytheon Technologies Corporation anchors its position through intensive R&D spending on scramjet propulsion systems. BAE Systems competes by specializing in European defense integration and thermal management solutions for extreme-velocity platforms.
Supersonic and hypersonic weapons are munitions and delivery systems engineered to exceed Mach 5, incorporating ceramic-matrix composite thermal shields, precision inertial navigation, and scramjet or rocket-based combined-cycle propulsion for penetration of advanced integrated air defense networks. The technology dimension separates mature rocket-propulsion segments from emerging scramjet platforms where margin pools concentrate around propulsion integration and aerothermal testing infrastructure. Missiles dominate current procurement volumes, while glide vehicles attract disproportionate investment as strategic bombardment applications expand among nuclear-capable powers.
The US Department of Defense and China's MIIT impose stringent export controls and classification frameworks that restrict technology transfer and shape supplier eligibility across national programs. NATO standardization efforts through STANAG agreements influence interoperability requirements for European consortium members including MBDA and ArianeGroup. Stakeholders must monitor how evolving ITAR thresholds and emerging dual-use technology classifications reshape cross-border supply relationships without triggering compliance breaches.
Market Dynamics
The supersonic and hypersonic weapons market is being fundamentally restructured by the migration from rocket-boosted systems to air-breathing scramjet architectures, a shift that compresses development timelines while demanding entirely new testing infrastructure and supplier capabilities.
Growth Catalysts
- Integrated Air Defense Penetration Requirements:Military end users in the United States, China, and Russia are prioritizing weapons capable of defeating layered missile defense networks, directly accelerating scramjet platform procurement.
- ITAR Modernization:The US Department of Defense has streamlined classification review processes for dual-use thermal protection materials, reducing technology transfer bottlenecks for qualified suppliers.
- Ceramic-Matrix Composite Maturation:Advances in CMC manufacturing are extending operational temperature thresholds beyond 1,650°C, enabling sustained hypersonic flight without active cooling systems.
Market Restraints
- Wind Tunnel Infrastructure Scarcity:Only three operational facilities worldwide—Arnold Engineering Development Complex in Tennessee, TsAGI in Russia, and the Chinese Academy of Aerospace Aerodynamics—can simulate sustained Mach 8+ conditions, creating testing bottlenecks.
- Tantalum and Hafnium Supply Concentration:Over 80% of refractory metal feedstock for thermal protection systems originates from Chinese and Russian mining operations, exposing Western programs to geopolitical supply disruption.
- Guidance System Thermal Degradation:Inertial measurement units experience drift rates exceeding mission tolerances when exposed to aerodynamic heating above Mach 6, limiting precision strike applicability.
Strategic Opportunities
- Underpenetrated European Procurement:France, Germany, and Italy lack operational hypersonic strike capabilities, creating entry points for consortium-based development through NATO STANAG interoperability frameworks.
- Conventional Prompt Strike Expansion:The US Navy's CPS program is validating sea-launched hypersonic architectures, opening analogous requirements from Japan and Australia for maritime strike applications.
- Additive Manufacturing Integration:Directed energy deposition of refractory alloys is converging with topology optimization software, enabling single-piece thrust chamber geometries previously impossible through conventional machining.
Industry Challenges
- Aerothermal Engineering Talent Gap:Universities in the United States and Europe produce fewer than 200 specialists annually with combined expertise in high-speed aerodynamics and thermal-structural analysis, constraining program staffing.
- Flight Test Certification Timelines:Each full-scale hypersonic flight test requires 18-24 months of regulatory coordination with the FAA and range safety authorities, compressing iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supersonic and Hypersonic Weapons Market |
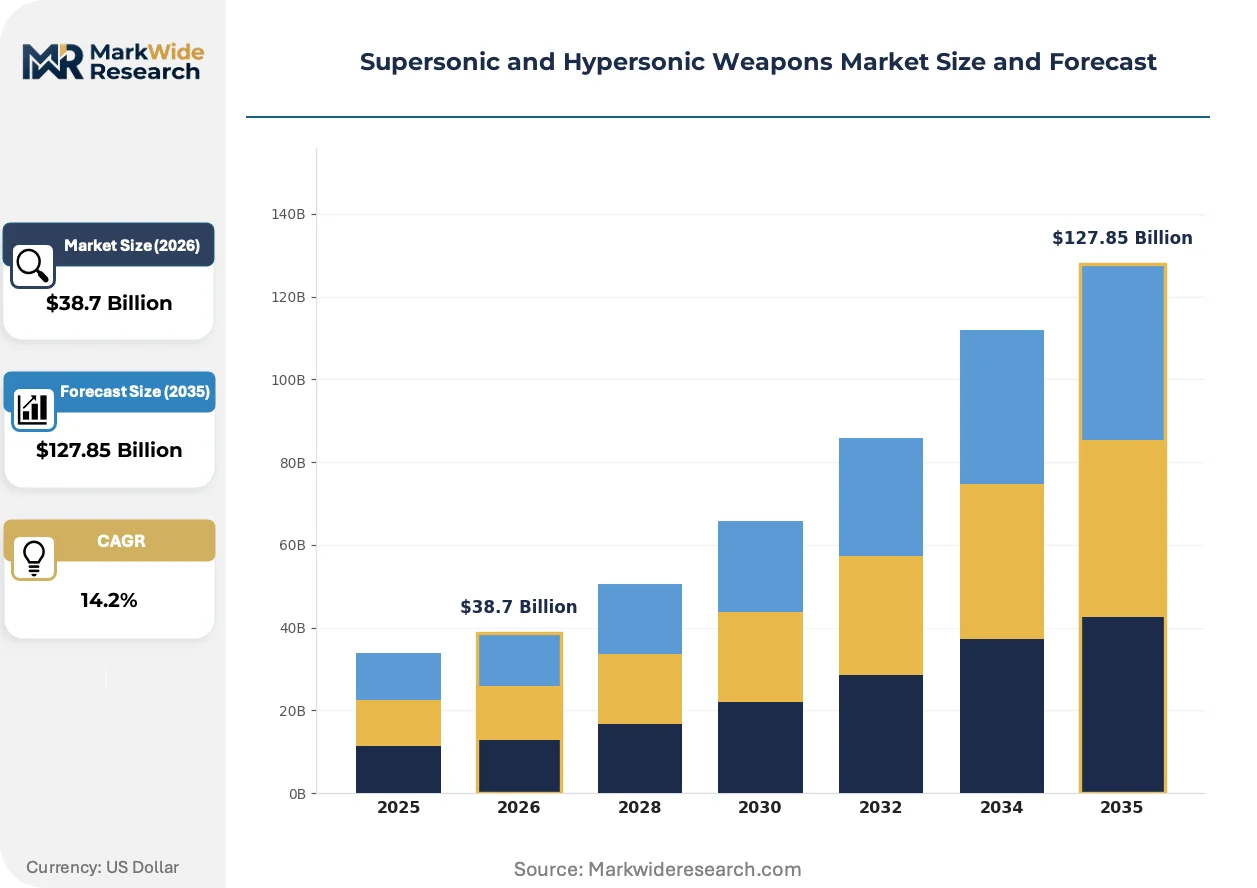
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Missiles, Projectiles, Unmanned Aerial Vehicles, Glide Vehicles End User: Military, Defense Contractors, Government Agencies, Research Institutions Application: Strategic Bombardment, Tactical Strikes, Defense, Intelligence Gathering Technology: Air-Breathing, Rocket Propulsion, Scramjet, Boost-Glide |
| Companies Covered | The Boeing Company, BAE Systems, Lockheed Martin Corporation, Tactical Missiles Corporation, General Dynamics Corporation, Raytheon Technologies Corporation, MBDA, ArianeGroup, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supersonic and Hypersonic Weapons Market Evolving Landscape
Scramjet propulsion architectures are fragmenting the competitive landscape by rewarding specialized subsystem suppliers over integrated prime contractors, while thermal management and guidance technologies undergo parallel disruptive evolution.
Carbon-carbon composite leading edges with silicon carbide coatings are fragmenting the thermal protection market by replacing monolithic refractory metal assemblies in boost-glide vehicles. The US Air Force and DARPA are accelerating transition from test articles to operational prototypes, compressing supplier qualification timelines from seven years to under four. This materials shift is fragmenting established supply relationships as new entrants with additive manufacturing capabilities capture subsystem contracts previously held by traditional forging houses.
The EU Green Deal's emerging defense industrial carbon accounting requirements are beginning to shape supplier selection criteria for European hypersonic development programs. MBDA and ArianeGroup must now document embodied carbon in propellant production and thermal protection fabrication, favoring domestic European supply chains over transatlantic alternatives. This regulatory pressure is most acute in France and Germany, where national procurement guidelines now incorporate lifecycle emissions thresholds for strategic weapons platforms.
Defense agencies are consolidating prime contractor relationships around fixed-price milestone contracts that transfer development risk from government laboratories to private industry. The traditional cost-plus-fee model for advanced technology demonstration is yielding to competitive down-selection at technology readiness level 6, forcing suppliers to self-fund early-stage propulsion integration. This behavioral shift is most visible in the United States, where the Department of Defense has eliminated sole-source hypersonic development awards since 2022.
Supersonic and Hypersonic Weapons Market Segmentation
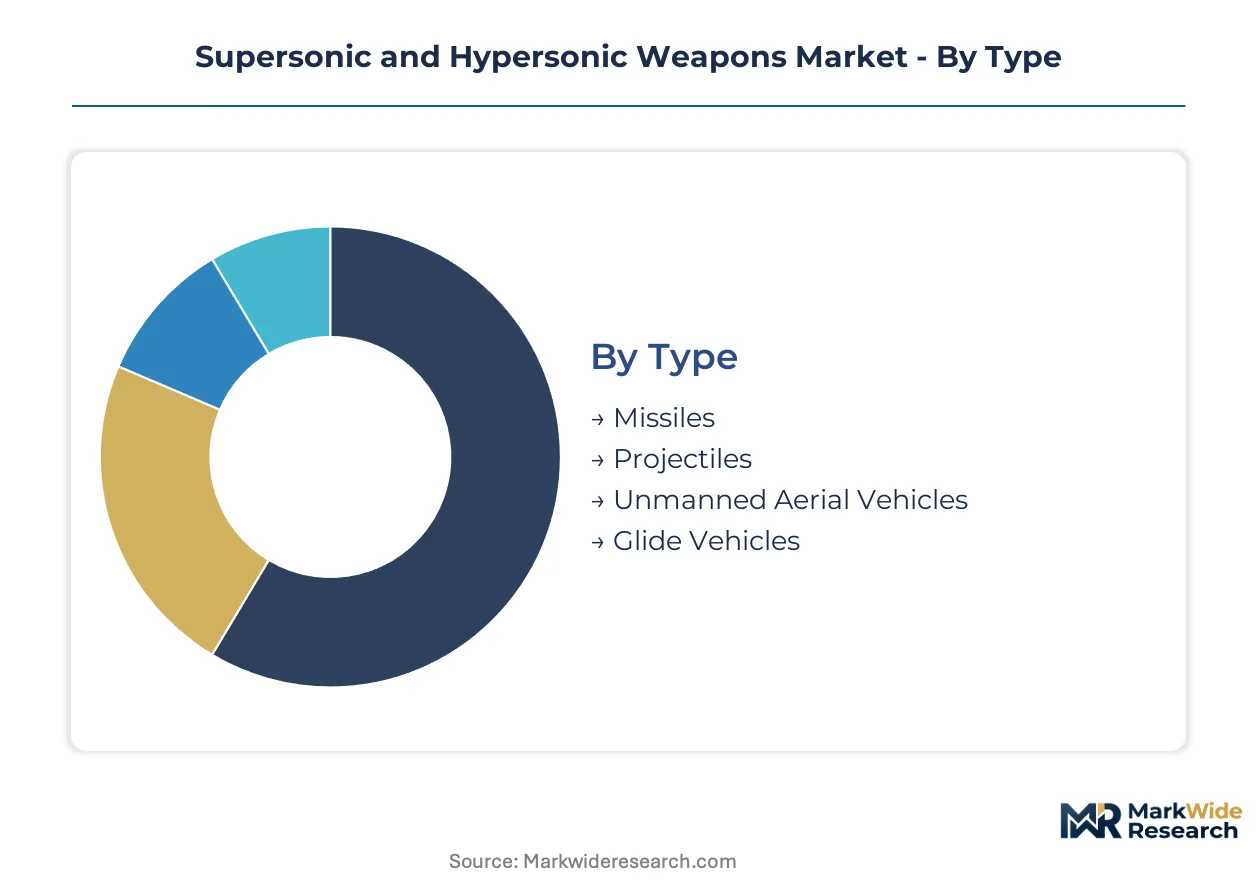
Segmentation in the supersonic and hypersonic weapons market reveals how procurement concentration varies sharply across weapon architectures and institutional buyers. Understanding these divides exposes where technology maturation outpaces operational deployment.
Type:
Domestic military programs in the United States, China, and Russia absorb the majority of missile and glide vehicle output, while unmanned aerial vehicles draw cross-border interest from NATO allies seeking interoperable platforms.
- Missiles:Rocket-boosted and air-breathing variants incorporate ceramic-matrix composite nose cones and precision inertial guidance for penetration of integrated air defense networks. Procurement concentrates in the United States and China, where strategic bombardment requirements accelerate scramjet-powered cruise missile development despite thermal protection bottlenecks.
- Glide Vehicles:Boost-glide architectures employ non-powered atmospheric reentry trajectories with maneuverable flight profiles above Mach 5. Demand clusters in Russia and China for nuclear delivery applications, constrained by limited ground-based radar tracking infrastructure for terminal guidance validation.
- Projectiles:Gun-launched hypervelocity rounds utilize sabot-discarding penetrators for naval railgun applications.
- Unmanned Aerial Vehicles:Reusable hypersonic drones are emerging for intelligence collection and target verification missions.
Missiles command the established base. The steepest expansion runs through Glide Vehicles.
End User:
Cost tier stratification separates fully funded national military programs from research institutions dependent on grant cycles and prototype-to-production transition gaps.
- Military:Naval and air force branches in the United States, China, and Russia drive operational procurement with dedicated budget lines for scramjet platform fielding. The US Navy's Conventional Prompt Strike program validates sea-launched architectures, while China's Rocket Force accelerates DF-ZF glide vehicle deployment despite guidance system thermal degradation above Mach 6.
- Defense Contractors:Prime contractors and subsystem suppliers absorb fixed-price development risk under streamlined ITAR classification reviews for qualified thermal protection material vendors.
- Government Agencies:DARPA and national defense laboratories fund technology readiness level advancement for propulsion integration.
- Research Institutions:University-affiliated centers produce fewer than 200 aerothermal engineering specialists annually, constraining workforce pipeline expansion.
Military end users anchor procurement volume. Research institutions face the widest funding volatility.
Application:
Volume concentration favors strategic bombardment platforms with nuclear delivery missions, while tactical strike applications lag due to precision guidance limitations under sustained aerodynamic heating.
- Strategic Bombardment:Intercontinental-range glide vehicles and hypersonic cruise missiles prioritize warhead delivery speed over circular error probable minimization. Deployment focuses on Chinese and Russian strategic forces, where mission profiles tolerate guidance drift in exchange for defense penetration certainty.
- Tactical Strikes:Theater-range systems target time-sensitive mobile assets with conventional warheads. Development concentrates in the United States, where the Army's Long-Range Hypersonic Weapon program confronts inertial measurement unit thermal tolerance barriers that degrade strike accuracy.
- Defense:Counter-hypersonic interceptors remain in early technology demonstration phases.
- Intelligence Gathering:Reusable platforms for high-speed reconnaissance attract DARPA funding for rapid turnaround missions.
Strategic Bombardment absorbs the dominant funding share. Tactical Strikes are climbing the fastest as precision guidance matures.
Technology:
Margin concentration shifts from mature rocket propulsion toward scramjet and boost-glide architectures requiring specialized aerothermal testing infrastructure.
- Scramjet:Supersonic combustion ramjet engines sustain air-breathing propulsion above Mach 5 without moving parts, demanding advanced thermal protection for combustion chamber walls. Development centers in the United States and Australia through the Hypersonic International Flight Research Experimentation program, constrained by Arnold Engineering Development Complex testing queue bottlenecks.
- Boost-Glide:Rocket-boosted atmospheric reentry vehicles execute high-lift maneuvers during unpowered descent. China's Academy of Aerospace Aerodynamics and Russia's TsAGI operate the only Mach 8+ wind tunnels validating these trajectories, creating geographic capability concentration.
- Air-Breathing:Combined-cycle engines transition from turbojet to ramjet operation for reusable platforms.
- Rocket Propulsion:Solid and liquid rocket boosters remain the baseline for existing tactical missile inventories.
Rocket Propulsion commands the installed base. Scramjet platforms are gaining share fastest through defense agency risk-transfer contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Defense anchors procurement volume through classified budget lines for scramjet platform development. National programs concentrate investment in three sovereign territories where export control regimes restrict technology diffusion.
United States
The US Navy's Conventional Prompt Strike program and Air Force AGM-183A development drive scramjet procurement. The Department of Defense streamlined ITAR classification reviews for qualified thermal protection material suppliers. Arnold Engineering Development Complex in Tennessee operates the sole Western facility capable of sustained Mach 8+ wind tunnel simulation.
China
The Rocket Force accelerates DF-ZF boost-glide vehicle deployment for strategic bombardment missions. MIIT imposes stringent export controls and classification frameworks that restrict technology transfer. The Chinese Academy of Aerospace Aerodynamics in Beijing maintains one of three global Mach 8+ wind tunnel facilities.
Russia
Tactical Missiles Corporation and national defense laboratories prioritize Avangard glide vehicle and Tsirkon scramjet cruise missile fielding. TsAGI in Zhukovsky operates Russia's hypersonic testing infrastructure alongside restricted technology export policies. Moscow's aerospace cluster concentrates thermal protection system development.
United Kingdom
BAE Systems leads European consortium participation in NATO STANAG interoperability frameworks for hypersonic strike. UK defense procurement guidelines incorporate emerging lifecycle emissions thresholds under EU Green Deal influence. The Farnborough aerospace corridor hosts thermal management subsystem development.
Australia
The Hypersonic International Flight Research Experimentation program with the United States drives scramjet propulsion collaboration. Australian defense procurement prioritizes maritime strike applications aligned with AUKUS security frameworks. Queensland's research corridor concentrates hypersonic flight test coordination.
Supersonic and Hypersonic Weapons Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Prime contractors absorb fixed-price development risk under defense agency milestone contracts while subsystem suppliers capture margin pools around propulsion integration and aerothermal testing. Three archetypes dominate: vertically integrated aerospace conglomerates with captive test infrastructure, specialized thermal protection material vendors with additive manufacturing capabilities, and consortium-based European integrators leveraging NATO interoperability requirements. Competitive moves center on M&A targeting aerothermal engineering talent and strategic partnerships securing wind tunnel access.
Among US-based integrated primes, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the vertically integrated archetype with decades of hypersonic test-flight experience. BAE Systems occupies a position representing European consortium specialization through defense integration and thermal management solutions. These three anchors illustrate how geographic concentration of testing infrastructure and export control regimes stratify competitive positioning across national program boundaries.
| Leading Market Players |
|---|
| The Boeing Company |
| BAE Systems |
| Lockheed Martin Corporation |
| Tactical Missiles Corporation |
| General Dynamics Corporation |
| Raytheon Technologies Corporation |
| MBDA |
| ArianeGroup |
| Northrop Grumman Corporation |
| Others |
Value Network & Pricing Analysis
Twenty-four-month flight test certification timelines compress supplier cash conversion cycles and amplify pricing power for wind tunnel operators with Arnold Engineering Development Complex queue positions. Procurement officers at the US Department of Defense and China's MIIT absorb fixed-price milestone contract structures that transfer development risk downstream to subsystem vendors lacking captive test infrastructure.
Pricing Analysis
North American scramjet platform contracts command 40-60% premiums over comparable Russian and Chinese program awards due to ITAR compliance overhead and domestic thermal protection material sourcing mandates. Three-tier pricing structure across development, prototype, and production phases separates qualified subsystem suppliers from prime contractors absorbing fixed-price risk. Cost compression in prototype-phase thermal management subsystems is intensifying because additive manufacturing entrants are undercutting traditional forging houses on lead-edge fabrication. Defense contractors with captive wind tunnel access exhibit lowest price sensitivity; research institutions dependent on grant cycles face highest procurement volatility.
Supply Chain Analysis
Inbound logistics costs for tantalum and hafnium feedstock from Chinese and Russian mining operations expose Western thermal protection programs to geopolitical disruption without alternative sourcing corridors. Supply concentrates in China, Russia, and Australia for refractory metal extraction, with ceramic-matrix composite preform manufacturing anchored in the United States and France. Component dependencies include hafnium carbide coatings, carbon-carbon composite substrates, and precision inertial measurement units. Single-source vulnerability runs through the three global Mach 8+ wind tunnel facilities. Distribution runs through defense agency prime contractor networks with classified procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where aerothermal testing infrastructure access and sustainment engineering contracts expand faster than hardware platform deliveries. Recurring revenue layers around flight test coordination and thermal protection system refurbishment outpace one-time glide vehicle procurement cycles.
For Market Incumbents: Compound technology leadership through backward integration into ceramic-matrix composite manufacturing and captive acquisition of Arnold Engineering Development Complex testing slots. Lockheed Martin Corporation and Raytheon Technologies Corporation face emerging threat from additive manufacturing specialists capturing subsystem contracts previously held by traditional forging houses. Vertical integration into thermal protection material production represents the critical defensive lever against margin compression. For New Entrants and Emerging Players: Lead with underpenetrated European procurement channels in France, Germany, and Italy where NATO STANAG interoperability frameworks create consortium entry points without sole-source incumbent relationships. The most penetrable segment sits in maritime strike applications aligned with AUKUS security frameworks and Japanese defense modernization. Go-to-market execution should emphasize directed energy deposition capabilities for single-piece thrust chamber geometries that bypass conventional machining bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because aerothermal testing facility scarcity and engineering talent concentration create durable moats around qualified subsystem suppliers. Acquisition targets should profile as specialized thermal protection material vendors with additive manufacturing capabilities and established ITAR qualification. The signal to watch is queue depth at Arnold Engineering Development Complex and TsAGI facilities as real-time demand indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Wind Tunnel Capacity Expansion | Arnold Engineering Development Complex queue bottlenecks constrain scramjet platform iteration cycles for US primes. |
| Ceramic-Matrix Composite Backward Integration | BAE Systems and ArianeGroup secure thermal protection supply chains against Chinese hafnium export restrictions. |
| Additive Manufacturing Specialist Acquisition | Directed energy deposition capabilities enable single-piece thrust chamber geometries previously impossible through machining. |
| European Consortium Formation | MBDA leverages NATO STANAG interoperability frameworks to penetrate French and German hypersonic procurement gaps. |
| ITAR Qualification Investment | Streamlined US Department of Defense classification reviews reduce technology transfer bottlenecks for qualified thermal protection vendors. |
Research Methodology
A spread of perspectives from scramjet propulsion engineers, thermal protection material procurement leads, defense agency program managers, wind tunnel operations directors, and aerothermal testing specialists converged on the working assumptions around development timeline compression and supplier qualification bottlenecks. Primary fieldwork combined structured interviews with subsystem vendors and prime contractor engineering directors against secondary validation through US Department of Defense budget justification documents, MIIT export control filings, NATO STANAG agreement texts, and wind tunnel facility utilization disclosures. Bottom-up platform deployment forecasts triangulated against top-down defense expenditure allocation patterns.
Segmentation dimensions modeled span propulsion architecture, thermal protection material class, end-user branch affiliation, and application mission profile across the projection horizon. Analytical framework approach deployed multivariate regression against defense agency procurement cycle data and supplier qualification timeline observations. CAGRs derived from technology readiness level advancement curves and fixed-price contract adoption rates. Industry-specific forecast inputs incorporated ceramic-matrix composite manufacturing yield improvements and scramjet combustion chamber wall thermal tolerance thresholds.
The analysis sits within stated boundaries; outcomes outside sustained Mach 5+ operational requirement validation or ITAR classification threshold modifications would require recalibration. Forecasts reflect assumptions around continued refractory metal supply chain concentration and wind tunnel infrastructure scarcity. Specific risk factors that could revise projections include Chinese export restriction escalation on hafnium feedstock, FAA range safety coordination timeline extensions, or European Green Deal defense industrial carbon accounting threshold adjustments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Ammunition Belt Market