
 Automatic Train Operation System Market | 2026-2036
Automatic Train Operation System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Train Operation System Market Analysis
China's massive rail infrastructure expansion is reshaping competitive dynamics in automatic train control. Siemens Mobility GmbH leverages its European signaling heritage to compete for ERTMS-compliant contracts across Belt and Road corridors. CRRC Corporation Limited anchors domestic supply through in-house production of integrated onboard and trackside packages. Alstom SA specializes in driverless metro platforms, positioning its Urbalis suite for Asian and Middle Eastern urban transit tenders.
Automatic train operation systems integrate onboard computers, wayside controllers, and continuous communication links to manage train movement without direct human intervention, typically achieving headways below 90 seconds in urban environments. Communication-Based Train Control dominates technology deployment, though Driverless Operation commands premium pricing due to integration complexity and safety certification requirements. Urban Transit leads application demand, while High-Speed Rail represents a concentrated margin pool where national procurement cycles create lumpy revenue.
ERTMS/ETCS standards, enforced by national safety regulators including Germany's KBA and France's ANSM, mandate interoperable signaling across European corridors and shape vendor qualification requirements. China's NMPA and MIIT enforce GB standards and dual carbon goals that localize procurement toward domestic system integrators. Stakeholders must monitor regulatory divergence between European interoperability mandates and China's indigenous standardization push, as this tension will determine which technology platforms achieve cross-border traction.
Market Dynamics
ERTMS deployment mandates across European rail corridors are forcing control system upgrades while China's GB standards and dual carbon goals localize procurement toward domestic integrators, creating divergent qualification requirements that reshape vendor competitive positioning.
Growth Catalysts
- ERTMS Level 3 Mandates:Germany's KBA and France's ANSM enforce interoperable signaling standards across trans-European corridors, requiring automatic train control upgrades on cross-border routes.
- Urban Transit Expansion:Singapore and Dubai are extending driverless metro networks, creating concentrated demand for Communication-Based Train Control platforms in high-density environments.
- Dual Carbon Policy Framework:China's MIIT ties rail electrification targets to domestic procurement preferences, accelerating adoption of integrated onboard and trackside packages in Tier-1 city metro build-outs.
Market Restraints
- Safety Certification Burden:Driverless Operation platforms require multi-year SIL 4 certification cycles with Germany's TÜV or France's ANSM, extending time-to-revenue for new entrants.
- Semiconductor Supply Concentration:Wayside controllers and onboard computers depend on specialized industrial chip supply concentrated in East Asian foundries, creating input vulnerability.
- Legacy System Interoperability:Existing fixed-block signaling infrastructure in mature networks resists seamless integration with moving-block CBTC architectures, fragmenting upgrade paths.
Strategic Opportunities
- Belt and Road Signaling Corridors:ERTMS-compliant contracts across Central Asian and Southeast Asian rail links offer expansion paths for European-heritage control system vendors.
- Convergence of AI and Predictive Maintenance:Machine learning integration with train control diagnostics enables condition-based wayside equipment servicing, unbundling traditional maintenance contracts.
- High-Speed Rail Margin Pool:National procurement cycles for 350 km/h lines concentrate system value in concentrated tender windows with extended service attachment potential.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time safety-critical code development for SIL 4 systems requires specialized engineers, constraining vendor delivery capacity.
- Multi-Standard Certification Parallelism:Vendors must simultaneously satisfy ERTMS/ETCS interoperability mandates and China's GB standards, duplicating validation expenditure.
- Integration Complexity with Legacy Interlockings:Existing relay-based interlocking systems in older networks resist seamless interface with modern CBTC architectures, requiring costly transitional architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Train Operation System Market |
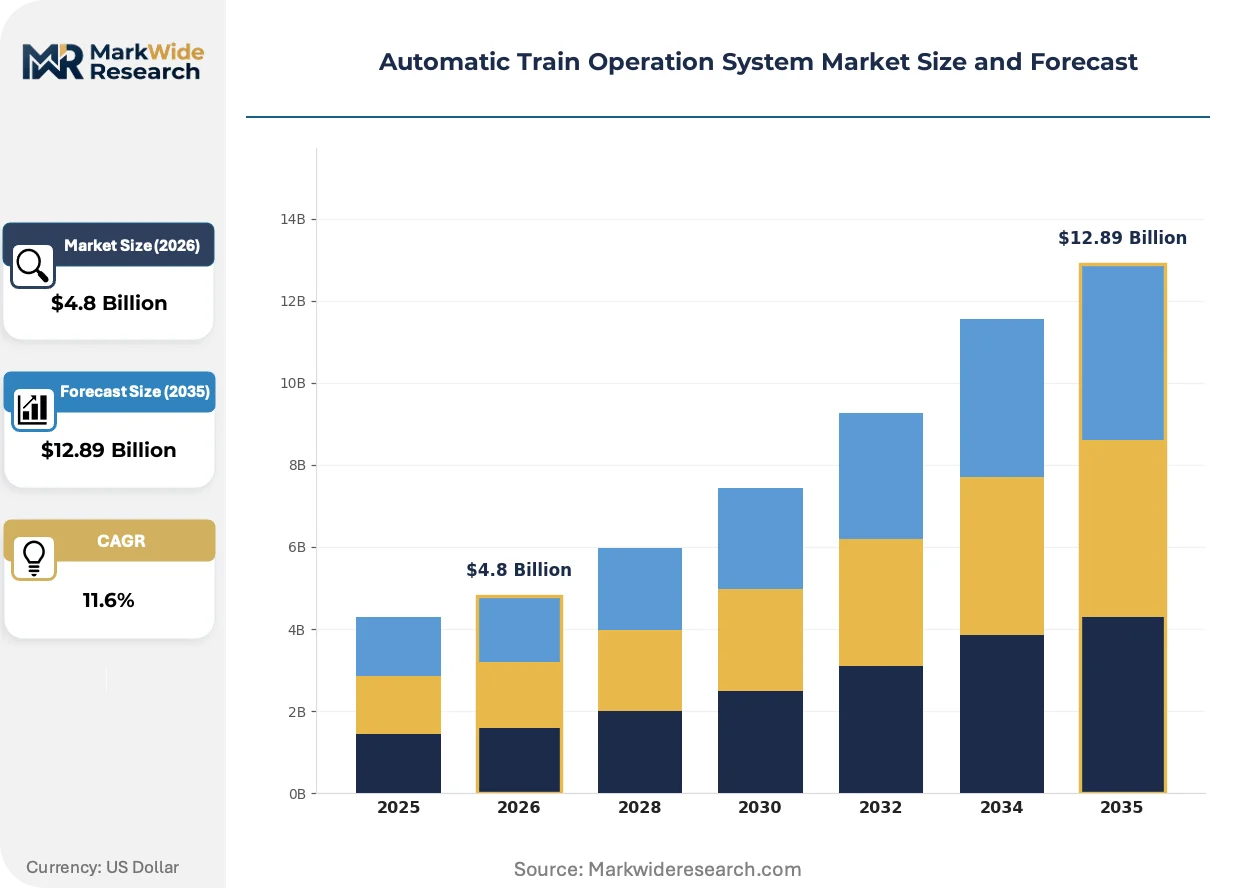
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Communication-Based Train Control, Automatic Train Protection, Driverless Operation, Advanced Signaling Systems End User: Railway Operators, Governments, Transport Authorities, Infrastructure Providers Application: Freight Transportation, Urban Transit, Intercity Travel, High-Speed Rail Component: Onboard Systems, Control Centers, Track Equipment, Safety Devices |
| Companies Covered | Hitachi Rail S.p.A., Mitsubishi Electric Corporation, Siemens Mobility GmbH, Construcciones y Auxiliar de Ferrocarriles, Wabtec Corporation, Alstom SA, CRRC Corporation Limited, Toshiba Infrastructure Systems & Solutions Corporation, Thales S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Train Operation System Market Emerging Trajectories
Digital signaling architectures are displacing electromechanical systems while regulatory divergence between European interoperability mandates and indigenous standardization pushes reshapes vendor qualification requirements across procurement geographies.
Moving-block signaling is virtualizing fixed-block infrastructure by replacing physical track circuits with continuous wireless train-to-wayside communication. Urban transit operators in Singapore and Dubai are adopting this architecture aggressively. The technology is virtualizing headway constraints, enabling sub-90-second intervals that compress line capacity expansion timelines.
France's ANSM and Germany's KBA are tightening ERTMS Level 3 certification timelines for GoA 4 unattended operation, accelerating safety case documentation requirements. This regulatory compression favors vendors with established European heritage and existing SIL 4 portfolios. High-Speed Rail tenders across trans-Alpine corridors are most affected, with bidders pre-qualifying based on prior Level 2 deployment track records.
Service unbundling is disrupting traditional turnkey contracting patterns in urban transit procurement. Municipal operators in Dubai and Singapore are separating control system supply from long-term maintenance obligations, forcing vendors to compete on discrete performance metrics. This pattern is most visible in Asian metro tenders where public-private partnership structures predominate and asset-light operational models gain preference over bundled lifecycle contracts.
Automatic Train Operation System Market Segmentation
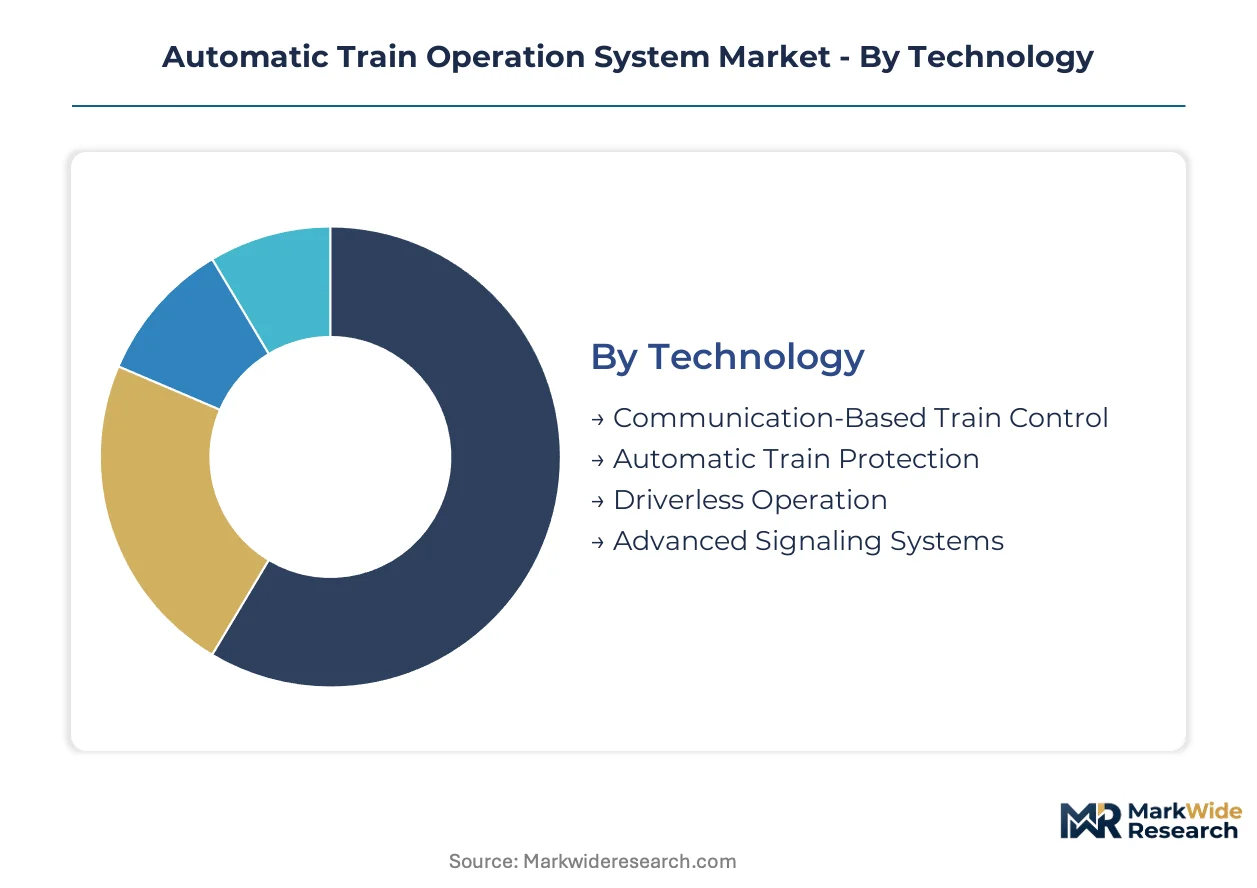
Automatic train operation systems fragment across technology generations, operator types, and infrastructure maturity levels. Each segment carries distinct service attachment profiles and certification burdens that reshape vendor economics.
Technology:
After-sales-service intensity varies sharply across technology tiers, with driverless platforms demanding continuous safety monitoring and legacy systems requiring phased modernization support.
- Communication-Based Train Control:Continuous wireless train-to-wayside communication replaces fixed-block track circuits. Demand concentrates in Singapore and Dubai metro expansions where sub-90-second headways compress capacity timelines.
- Driverless Operation:GoA 4 unattended systems integrate onboard computers, platform screen doors, and centralized traffic management. France's ANSM and Germany's KBA enforce multi-year SIL 4 certification cycles that extend vendor revenue recognition timelines.
- Automatic Train Protection:Speed supervision and emergency braking enforcement for legacy interoperability.
- Advanced Signaling Systems:ERTMS/ETCS-compliant platforms for trans-European corridor mandates.
By volume, Communication-Based Train Control leads. By growth pace, Driverless Operation is climbing the fastest.
End User:
Procurement authority shapes contract structure, with government tenders favoring bundled lifecycle agreements and infrastructure providers seeking discrete equipment supply.
- Railway Operators:Integrated network owners specifying control systems across mixed-traffic corridors. China's national railway operator anchors demand through Tier-1 city metro build-outs tied to MIIT dual carbon procurement preferences.
- Transport Authorities:Municipal bodies in Singapore and Dubai separating control system supply from maintenance obligations under public-private partnership frameworks.
- Governments:National procurement for ERTMS-mandated cross-border corridors.
- Infrastructure Providers:Trackside equipment specialists bidding on discrete wayside controller packages.
Railway Operators command the largest contract values. Transport Authorities are gaining share fastest through unbundled service models.
Application:
Margin concentration diverges between high-volume urban installations and premium high-speed tenders with extended service attachment potential.
- Urban Transit:High-density metro networks with frequent station spacing and stringent headway requirements. Singapore and Dubai operators are extending driverless lines aggressively.
- High-Speed Rail:350 km/h lines requiring redundant signaling architectures and centralized traffic management. National procurement cycles in China concentrate system value in lumpy tender windows.
- Freight Transportation:Heavy-haul corridors with mixed-traffic interoperability demands.
- Intercity Travel:Regional networks bridging urban and long-distance service profiles.
Urban Transit dominates installation counts. High-Speed Rail shows the steepest expansion trajectory in system value per kilometer.
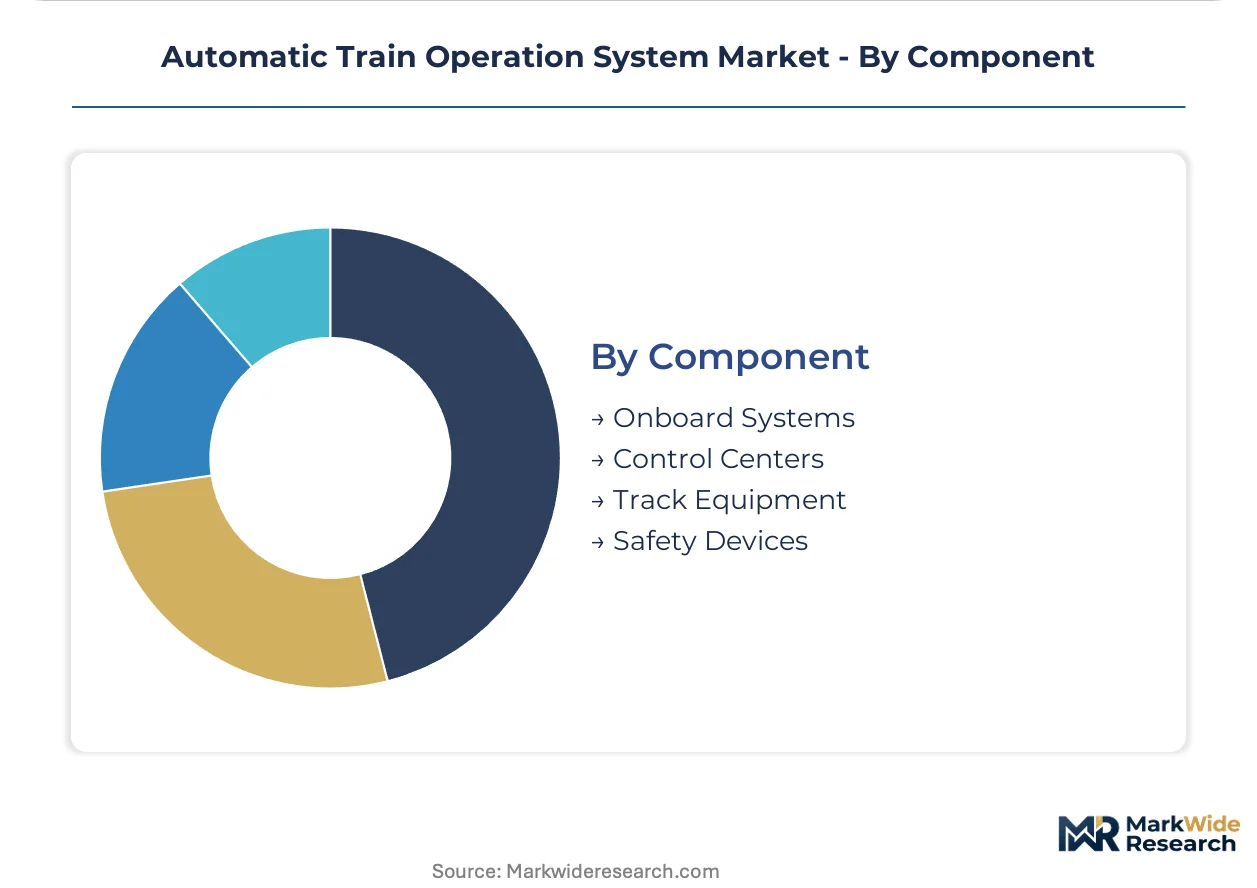
Component:
Supply chain concentration in East Asian foundries creates input vulnerability for semiconductor-dependent onboard and wayside electronics.
- Onboard Systems:Train-borne computers, antennas, and human-machine interfaces. China's CRRC Corporation anchors domestic supply through in-house production of integrated packages.
- Control Centers:Centralized traffic management platforms with redundant server architectures. European heritage vendors leverage ERTMS deployment track records for trans-Alpine corridor pre-qualification.
- Track Equipment:Wayside controllers and balise transmission modules.
- Safety Devices:Platform screen doors and obstacle detection systems for GoA 4 operation.
Onboard Systems represent the largest procurement category by unit volume. Control Centers are expanding most quickly as centralized traffic management displaces distributed architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT anchors procurement gravity through dual carbon procurement preferences and GB standard enforcement. Tier-1 city metro build-outs concentrate system demand while ERTMS mandates across trans-European corridors reshape vendor qualification requirements elsewhere.
China
CRRC Corporation anchors domestic supply through in-house production of integrated onboard and trackside packages. MIIT ties rail electrification targets to localization preferences, concentrating procurement toward domestic system integrators. Tier-1 cities including Beijing, Shanghai, and Shenzhen are extending driverless metro networks aggressively.
Germany
KBA enforces ERTMS Level 3 certification timelines for GoA 4 unattended operation across trans-European corridors. Siemens Mobility leverages its European signaling heritage to compete for ERTMS-compliant contracts. The Rhine-Ruhr and Munich metropolitan clusters concentrate high-speed rail tender activity.
Singapore
The Land Transport Authority separates control system supply from maintenance obligations under public-private partnership frameworks. Sub-90-second headway requirements compress capacity expansion timelines for Communication-Based Train Control platforms. The island-wide metro network extension drives concentrated demand for driverless operation systems.
France
ANSM tightens safety case documentation requirements for unattended operation platforms. Alstom SA positions its Urbalis suite for Asian and Middle Eastern urban transit tenders from its domestic engineering base. The Paris metropolitan region anchors high-speed rail signaling demand through trans-Alpine corridor upgrades.
United Arab Emirates
Dubai's Roads and Transport Authority extends driverless metro networks across new corridor phases. MOHAP-equivalent transport safety frameworks govern platform screen door integration and centralized traffic management procurement. The Dubai Metro Red Line expansion concentrates premium-tier system demand.
Automatic Train Operation System Market Vendor Landscape
Capability concentration sits with European-heritage signaling specialists; scale advantage sits with integrated Chinese rail conglomerates. The vendor base stratifies across three tiers: ERTMS-certified platform providers, domestic turnkey suppliers, and component specialists. Two strategic archetypes dominate: full-system integrators bidding turnkey urban transit packages, and technology licensors extracting recurring revenue from signaling IP. Competitive moves center on Belt and Road corridor pre-qualification and AI-enabled predictive maintenance unbundling.
Within the European-heritage tier, Siemens Mobility GmbH and Alstom SA exemplify ERTMS-compliant platform providers competing for trans-European and export corridor contracts. CRRC Corporation Limited anchors the integrated domestic supplier archetype, representing the scale-driven model through captive supply of onboard and trackside packages. These three entities occupy positions across divergent procurement geographies shaped by regulatory divergence between European interoperability mandates and China's indigenous standardization push.
| Leading Market Players |
|---|
| Hitachi Rail S.p.A. |
| Mitsubishi Electric Corporation |
| Siemens Mobility GmbH |
| Construcciones y Auxiliar de Ferrocarriles |
| Wabtec Corporation |
| Alstom SA |
| CRRC Corporation Limited |
| Toshiba Infrastructure Systems & Solutions Corporation |
| Thales S.A. |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's cost dynamics expose how East Asian semiconductor concentration shapes both upstream component pricing and downstream system tier differentiation across automatic train operation procurement.
Pricing Analysis
Geographic price spreads between European ERTMS-certified platforms and Chinese GB-standard systems exceed threefold at the control center tier. Project-based contracting dominates, with pricing stratifying across SIL 4 driverless, Level 2 ERTMS, and legacy ATP retrofit tiers. Certification burden from Germany's TÜV and France's ANSM compresses margins for new entrants while insulating incumbents. Transport authorities in Singapore and Dubai exhibit highest price sensitivity through unbundled procurement, whereas China's national railway operator prioritizes localization over unit cost.
Supply Chain Analysis
Extended payment terms from Tier-1 city metro operators in China now stretch to 180 days, forcing component suppliers into supply-chain finance facilities. Manufacturing concentrates in China, Germany, and Japan for onboard computers, wayside controllers, and balise transmission modules respectively. Specialized industrial semiconductors, high-reliability antennas, and safety-critical relays anchor input dependencies. Single-source vulnerability in East Asian foundries threatens delivery timelines. Distribution runs through system integrators bidding turnkey packages to railway operators and transport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Driverless operation technology is disrupting control system procurement as ERTMS Level 3 mandates compress certification timelines and urban transit operators unbundle service contracts.
For Market Incumbents: Harden SIL 4 certification portfolios against regulatory compression from France's ANSM and Germany's KBA. Deepen backward integration into safety-critical semiconductor sourcing to offset East Asian foundry concentration. Lock in long-term maintenance attachments with Dubai's Roads and Transport Authority and Singapore's Land Transport Authority before unbundling spreads to European tenders.
For New Entrants and Emerging Players: Build out predictive maintenance software layers that interface with existing CBTC architectures without requiring full system replacement. Target freight transportation corridors in Central Asia where ERTMS deployment lags and procurement favors cost-optimized Level 2 solutions. Lead with AI-enabled condition monitoring to bypass capital-intensive hardware certification barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors embedded software specialists with existing safety-critical codebases over hardware-dependent component vendors. Long-term viability hinges on regulatory pre-qualification depth across multiple jurisdictions. Monitor Belt and Road tender pre-qualification announcements as the signal for which platform standards achieve cross-border traction.
| Strategic Initiative | Industry Significance |
|---|---|
| ERTMS Level 3 Certification Investment | France's ANSM and Germany's KBA tightening timelines favor incumbents with existing safety case documentation. |
| AI-Enabled Predictive Maintenance Platform | Machine learning integration with train control diagnostics unbundles traditional lifecycle contracts for Singapore and Dubai operators. |
| Backward Integration into Industrial Semiconductors | Captive supply of safety-critical chips reduces vulnerability to East Asian foundry concentration and extends margin capture. |
| Belt and Road Corridor Pre-Qualification | ERTMS-compliant track records unlock Central Asian and Southeast Asian rail link tenders for European-heritage vendors. |
| Public-Private Partnership Structuring | Unbundled service models in Asian metro procurement separate control system supply from long-term maintenance obligations. |
Methodological Framework
Desk research of regulatory filings from Germany's KBA and France's ANSM, customs data on rail signaling equipment trade flows, and ERTMS deployment databases preceded structured interviews with control system engineering directors, urban transit procurement managers, and safety certification specialists. Primary fieldwork with railway operators in China, Singapore, and the UAE validated secondary estimates of installed base and upgrade cycles. Bottom-up segmentation modeling triangulated against top-down market sizing from national rail investment disclosures.
Assumptions held ERTMS mandate enforcement timelines and China's dual carbon procurement preferences constant across the projection horizon. The analytical framework modeled technology generation, application type, and component category as primary segmentation dimensions, with regional regulatory cluster as a cross-cutting variable. CAGRs derived from fitting logistic adoption curves to documented deployment histories and announced tender pipelines. High-speed rail national procurement cycles and urban transit headway compression requirements served as volume drivers.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese system integrators or accelerated ERTMS timeline compression by European regulators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Overhead Catenary System Market
Railway
Railroad Tie Market
Railway
Automatic Train Control Market
Railway
Railway Window Market
Railway
Rail Composites Market
Railway
Railway Horn Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Train Exterior Lighting Market
Railway
Global High-Speed Train Seat Market
Railway
Rolling Stock Management Market
Railway
Railroad Brake Shoe Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Locomotive Parking Brake Market
Railway
Europe Intermodal Terminals Market
Railway
40-Foot Platform Wagons Market
Railway
Freight Wagon Market