
 Railway Overhead Catenary System Market | 2026-2036
Railway Overhead Catenary System Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Overhead Catenary System Market Analytics
Procurement channels for railway electrification hardware are fragmenting as state rail authorities diversify supplier bases beyond legacy incumbents. Siemens leverages its integrated signaling-catenary portfolio to anchor premium contracts across European corridors. CRRC competes on manufacturing scale, sustaining cost advantages in copper contact wire and messenger cable production. Alstom differentiates through digital asset management overlays that extend hardware lifecycles.
A railway overhead catenary system comprises tensioned messenger wires, contact wires, droppers, and supporting structures that deliver continuous electrical power to locomotives through pantograph contact at voltages typically between 15 kV and 25 kV AC. The system eliminates onboard fuel storage, enabling sustained speeds above 300 km/h on dedicated high-speed lines. Flexible catenary configurations dominate mature networks where thermal expansion compensation and dynamic load distribution prove critical, while rigid overhead installations capture share in metro tunnels and space-constrained urban environments. Composite materials represent the fastest-growing material category as operators seek weight reduction and corrosion resistance against traditional copper and aluminum standards.
EU Green Deal targets and F-Gas Regulation phase-outs shape electrification timelines across European member states, compelling infrastructure managers to accelerate overhead system deployment. China's MIIT enforces GB standards for catenary component interoperability across its expanding high-speed grid. India's CEA mandates progressive railway electrification under national carbon reduction commitments. Stakeholders must monitor regulatory divergence between harmonized European norms and country-specific technical specifications as project complexity escalates.
Market Dynamics
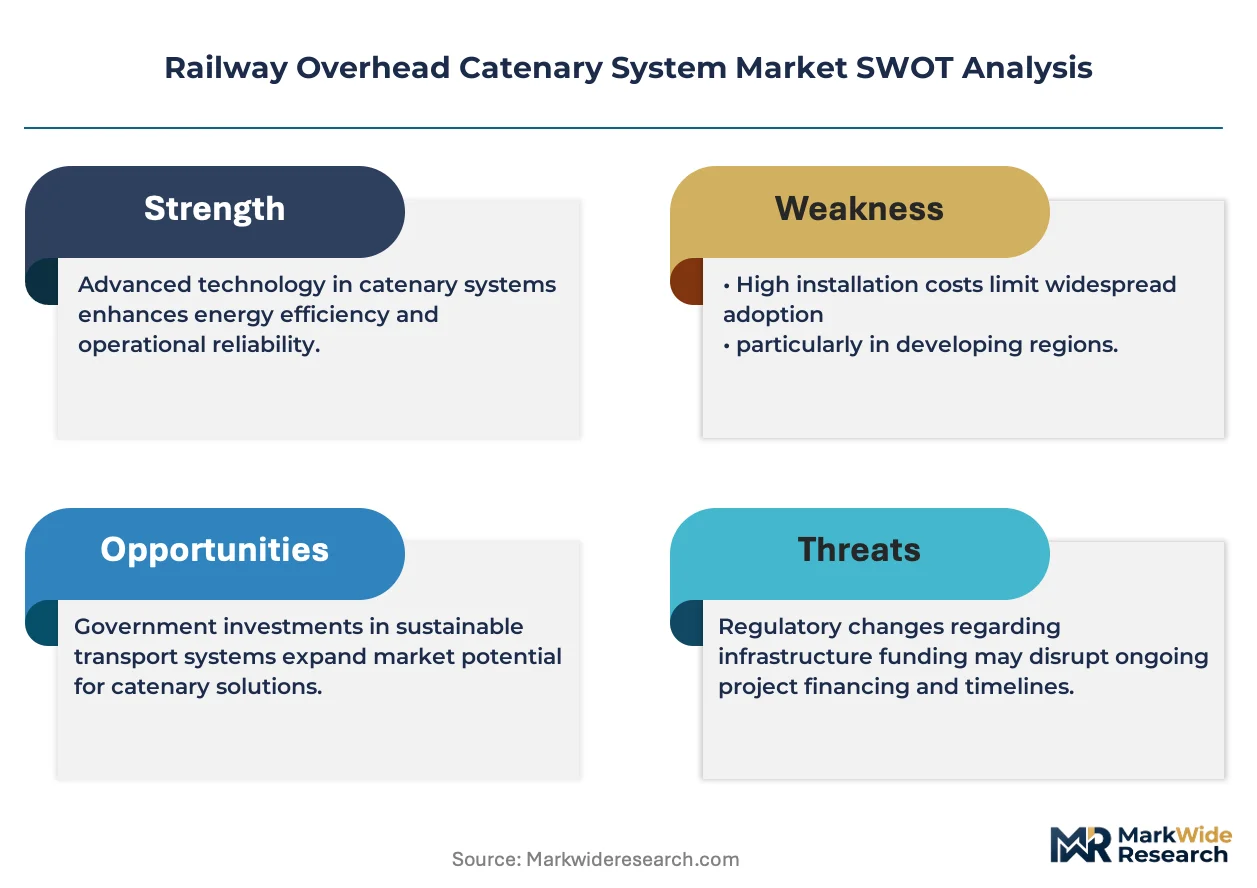
Copper price volatility and supply chain reconfiguration around critical raw materials constitute the dominant structural force reshaping procurement strategies and contract structures across railway electrification infrastructure.
Growth Catalysts
- EU Green Deal modal shift mandates:Binding targets for freight transfer from road to rail compel infrastructure managers in Germany, France, and Poland to accelerate overhead catenary deployment on priority corridors.
- Composite contact wire materials:Carbon-fiber reinforced aluminum conductors deliver 30% weight reduction and superior corrosion resistance, extending maintenance intervals on coastal and high-humidity routes.
- India's CEA electrification directives:National carbon commitments drive progressive conversion of diesel-operated broad-gauge lines to 25 kV AC overhead systems across the subcontinent.
Market Restraints
- Copper concentrate supply concentration:Chilean and Peruvian mine output disruptions transmit directly to messenger wire and contact wire pricing volatility, squeezing contractor margins on fixed-price EPC contracts.
- Technical interoperability constraints:Legacy 15 kV 16.7 Hz systems in Germany, Austria, and Switzerland resist seamless integration with standard 25 kV 50 Hz equipment, fragmenting supplier qualification requirements.
- SF6 gas phase-out timelines:EU F-Gas Regulation restrictions on sulfur hexafluoride use in switchgear compresses available supplier pools for integrated catenary-substation packages.
Strategic Opportunities
- Vietnam and Indonesia high-speed corridors:Greenfield rail electrification projects in Southeast Asia bypass legacy infrastructure constraints, enabling direct adoption of rigid overhead conductor rail systems in tunnels.
- Digital twin and predictive maintenance convergence:Integration of LiDAR pantograph monitoring with AI-driven wear prediction creates recurring revenue streams for hardware suppliers.
- US IRA clean transportation credits:Federal tax incentives for rail infrastructure modernization accelerate catenary system procurement for Northeast Corridor capacity expansion.
Industry Challenges
- Specialized installation technician scarcity:Tensioning and alignment of high-speed catenary systems requires certified rigging crews with overhead electrical work credentials, creating bottlenecks on concurrent project schedules.
- GB standard and EN 50149 harmonization delays:Divergent fatigue testing protocols for droppers and cantilever assemblies complicate cross-border certification for suppliers serving both Chinese and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Overhead Catenary System Market |
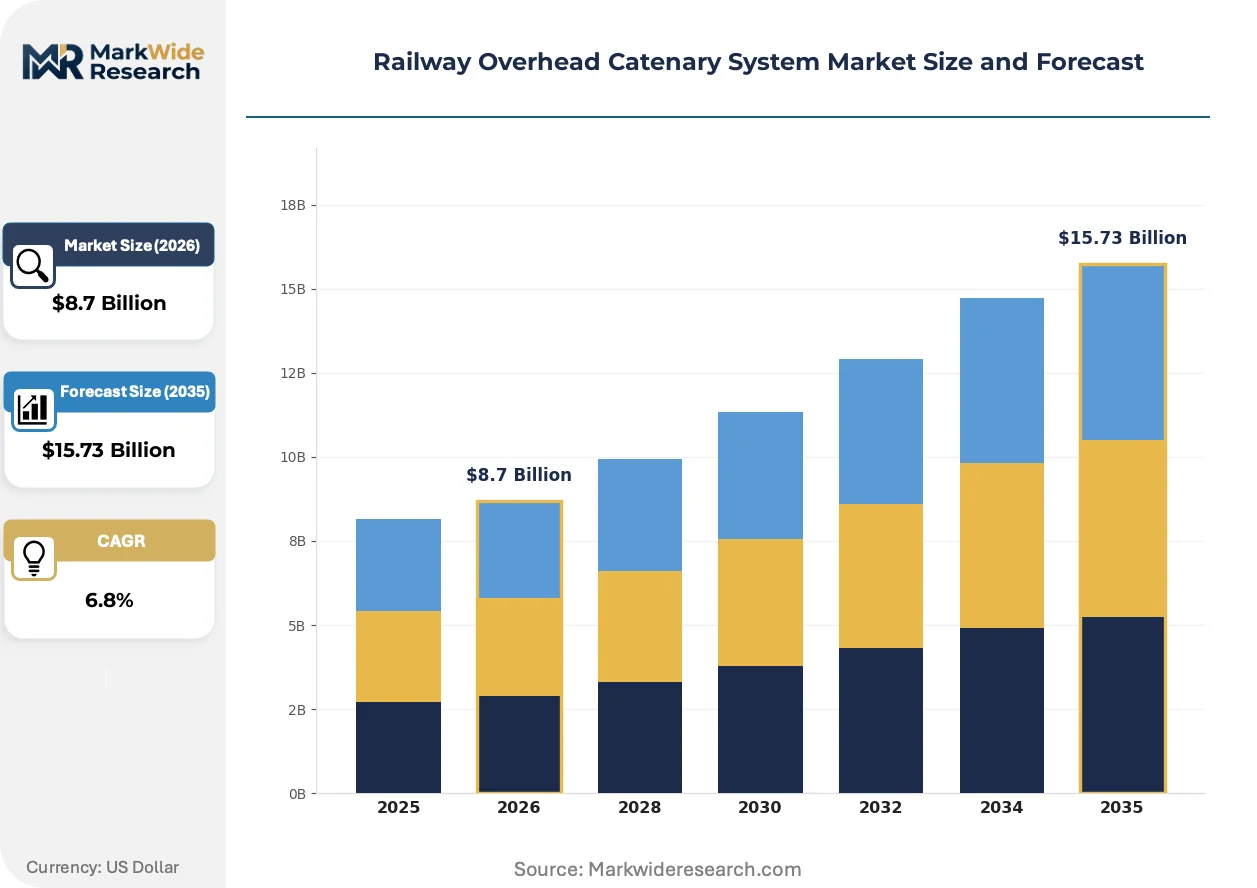
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Flexible, Lightweight, Rigid Installation Type: Overhead, Underground, Combination, Elevated Material: Aluminum, Copper, Steel, Composite End User: Public Transport, Freight Services, Private Operators, Infrastructure Developers |
| Companies Covered | Alstom, Siemens, CRRC, ABB, Nexans, NKT, Strukton, TE Connectivity, Wabtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Overhead Catenary System Market Evolving Landscape
Active current collection monitoring and automated tension adjustment systems are displacing passive mechanical designs, while regulatory pressure on embodied carbon in infrastructure materials redirects specification priorities.
Continuous in-line annealing of copper-magnesium alloy contact wires produces uniform grain structure and superior conductivity. Deutsche Bahn and SNCF Réseau have adopted these conductors for new 320 km/h lines. Traditional cold-drawn copper standards are rendering obsolete across premium corridor specifications.
EU F-Gas Regulation phase-down schedules force substitution of SF6-insulated switchgear in traction substations. Infrastructure managers in Spain and Italy now require vacuum-interrupter alternatives in integrated catenary power supply contracts. Component suppliers must requalify arc-extinguishing chamber designs under compressed timelines.
Performance-based availability contracts displace conventional hardware-procurement models for major renewals. British Network Rail and Australian ARTC now compensate contractors against pantograph-catenary interaction quality metrics. This shift concentrates risk with system integrators and filters down to component warranty terms.
Railway Overhead Catenary System Market Segmentation
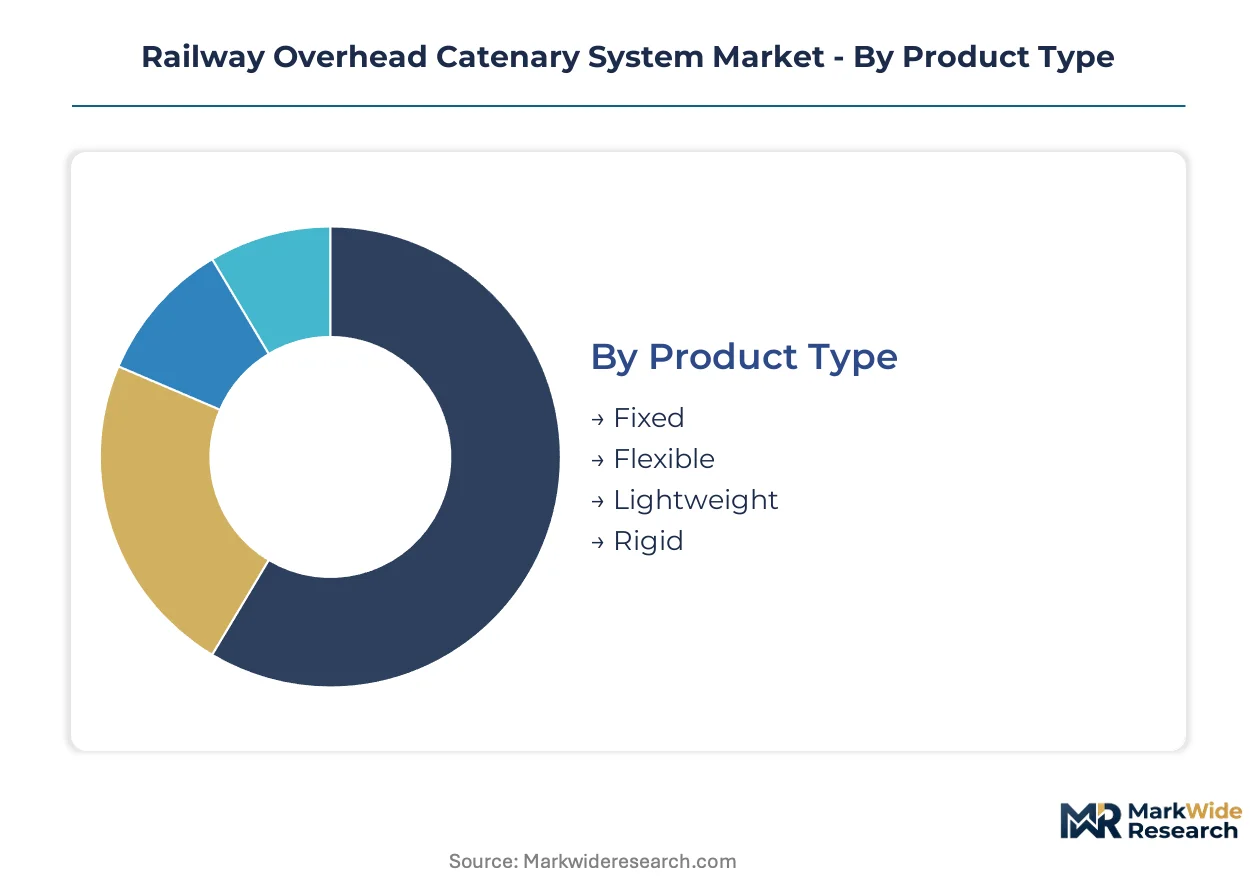
Segmentation in railway overhead catenary systems determines procurement specifications, maintenance protocols, and lifecycle cost structures. Each dimension carries distinct after-sales-service intensity implications, from tensioning adjustments in flexible systems to predictive monitoring in composite materials.
Product Type:
After-sales-service intensity varies sharply across catenary architectures, with dynamic systems demanding continuous tension calibration and static configurations requiring periodic structural inspection.
- Flexible:Tensioned messenger wire and contact wire assemblies accommodate thermal expansion through dynamic sag compensation. Deutsche Bahn specifications for 300 km/h corridors concentrate demand in Germany, where pantograph-catenary interaction quality mandates drive premium service contracts.
- Fixed:Rigid overhead conductor rails eliminate droppers and tensioning mechanisms, reducing maintenance intervals. Metro tunnel installations in Barcelona and Copenhagen favor this configuration where clearance constraints override speed requirements.
- Lightweight:Reduced-mass aluminum and composite assemblies suit temporary installations and heritage line retrofits where structural load limits apply.
- Rigid:Solid conductor bar systems with integrated insulation serve space-constrained environments including underground stations and maintenance depots.
Flexible configurations hold the largest share; momentum sits with lightweight variants as composite materials gain specification share.
Installation Type:
Cost tier differentiation separates turnkey underground deployments from modular overhead retrofits, with combination systems commanding premium engineering margins.
- Overhead:Conventional catenary masts and cantilever assemblies dominate intercity and high-speed corridors. India's CEA electrification mandates concentrate procurement across broad-gauge trunk routes where 25 kV AC standardization simplifies contractor qualification.
- Underground:Rigid conductor rail and compact catenary systems address tunnel clearance limits. Vienna U-Bahn and Stockholm Tunnelbana specifications drive adoption across Alpine and Nordic urban networks.
- Combination:Hybrid overhead-rigid transitions accommodate mixed-profile corridors with frequent tunnel portals.
- Elevated:Structural integration with viaduct infrastructure characterizes metro extensions in dense Asian urban corridors.
Overhead installations retain dominant volume; underground segments are climbing the fastest as urban rail tunneling accelerates.
Material:
Supply concentration in copper concentrate markets shapes procurement risk allocation, while composite qualification timelines filter supplier pools.
- Copper:Cold-drawn and continuous-annealed copper-magnesium alloys deliver superior conductivity and wear resistance. SNCF Réseau specifications for new 320 km/h lines in France concentrate premium-grade demand.
- Composite:Carbon-fiber reinforced aluminum conductors achieve 30% weight reduction with enhanced corrosion immunity. Coastal routes in Italy and humid environments in Vietnam drive specification shifts.
- Aluminum:Pure and alloyed aluminum standards serve cost-sensitive secondary lines and freight corridors where conductivity trade-offs are acceptable.
- Steel:Galvanized structural components and legacy messenger wire applications persist in maintenance-intensive heritage networks.
Copper maintains incumbent position; composite materials show steepest expansion trajectory on corrosion-critical routes.
End User:
Customer type determines contract structure, with public transport authorities favoring availability-based models and freight operators prioritizing capital efficiency.
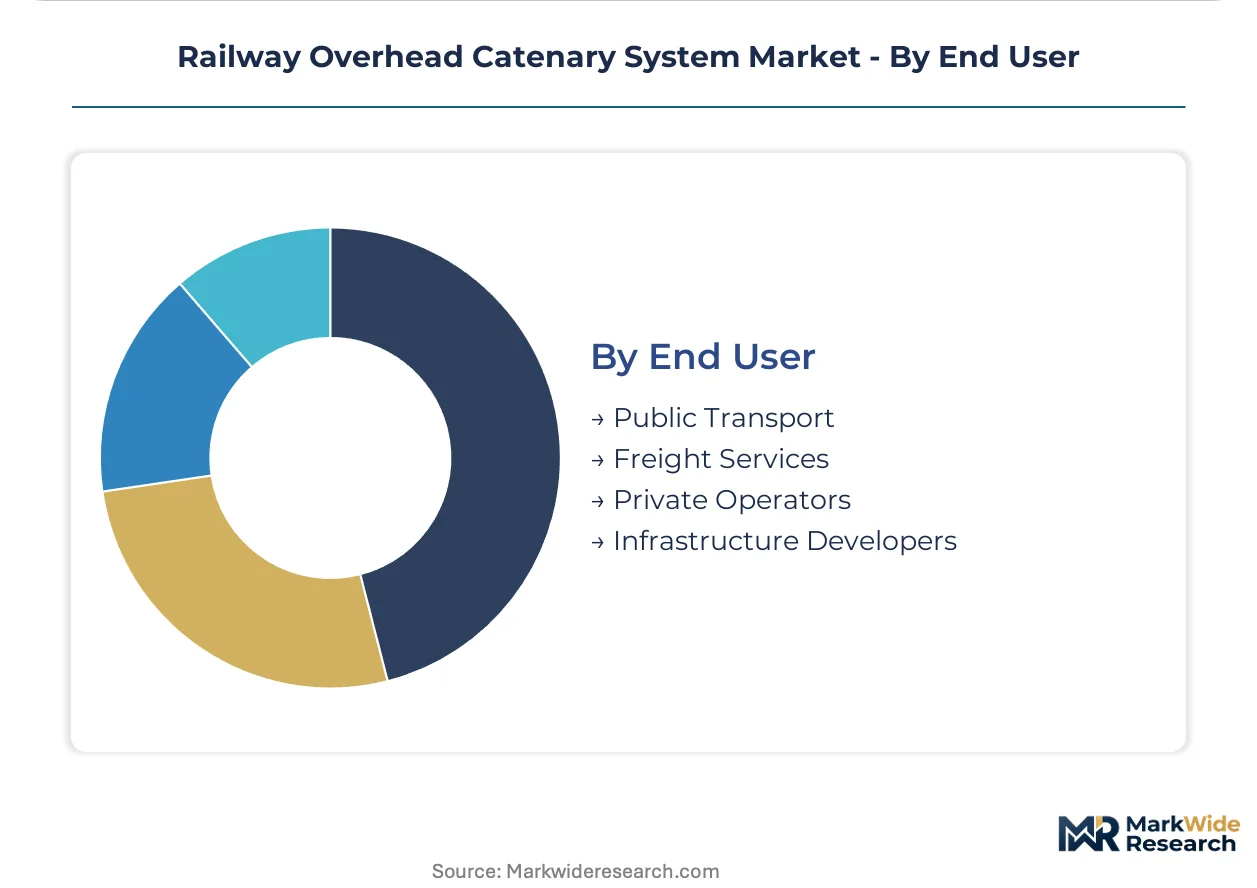
- Public Transport:State rail authorities and municipal operators specify integrated signaling-catenary packages with performance guarantees. EU Green Deal modal shift targets in Germany and Poland accelerate corridor deployment.
- Freight Services:Private freight operators and logistics consortia prioritize electrification of heavy-haul corridors serving port hinterlands. India's Dedicated Freight Corporation drives procurement across eastern coal and container routes.
- Private Operators:Concession-based open-access operators in Sweden and the UK procure catenary maintenance as bundled service contracts.
- Infrastructure Developers:Greenfield high-speed project companies in Indonesia and Vietnam specify rigid tunnel systems bypassing legacy interoperability constraints.
Public transport commands largest procurement volume; freight services are gaining share fastest as port electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal modal shift mandates and India's CEA electrification directives are reshaping procurement volumes across national rail networks. China MIIT enforces GB standards for component interoperability on expanding high-speed corridors. Regulatory divergence between harmonized European norms and country-specific technical specifications complicates cross-border supplier qualification.
China
High-speed rail electrification drives catenary system deployment across the Yangtze River Delta and Pearl River Delta corridors. MIIT enforces GB standards for catenary component interoperability across the expanding high-speed grid. CRRC leverages manufacturing scale in copper contact wire production to anchor domestic supply chains serving Beijing-Tianjin-Hebei expansion projects.
Germany
Deutsche Bahn specifications for 300 km/h corridors concentrate premium demand for pantograph-catenary interaction quality. EU Green Deal binding targets for freight transfer from road to rail compel accelerated overhead catenary deployment on priority corridors through Bavaria and North Rhine-Westphalia. Siemens anchors integrated signaling-catenary contracts across European corridors from its domestic base.
India
National carbon commitments under CEA directives drive progressive conversion of diesel-operated broad-gauge lines to 25 kV AC overhead systems. The Dedicated Freight Corporation electrifies eastern coal and container routes across Maharashtra and Gujarat. State rail authorities diversify supplier bases beyond legacy incumbents as procurement channels fragment.
France
SNCF Réseau specifications for new 320 km/h lines concentrate premium-grade copper-magnesium alloy demand. EU F-Gas Regulation phase-down schedules force substitution of SF6-insulated switchgear in traction substations across Île-de-France and Auvergne-Rhône-Alpes. Alstom differentiates through digital asset management overlays that extend hardware lifecycles on domestic corridors.
United States
Federal IRA clean transportation credits accelerate catenary system procurement for Northeast Corridor capacity expansion. Amtrak and regional authorities specify integrated packages for Boston-Washington electrification upgrades. Wabtec occupies a position among domestic suppliers serving freight corridor modernization programs.
Railway Overhead Catenary System Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system providers with signaling-catenary portfolios and scale-driven component manufacturers. Tiered competition separates premium integrators, mid-scale material specialists, and regional installation contractors. Dominant competitive moves include strategic partnerships for digital twin integration and capacity expansion in composite contact wire production.
Within the integrated systems tier, Alstom and Siemens exemplify archetypes combining hardware supply with predictive maintenance overlays. CRRC occupies a position among scale-driven manufacturers leveraging captive copper processing capacity. These three anchors illustrate how competitive positioning fragments across technology-integrated, manufacturing-scale, and service-augmented vectors.
| Leading Market Players |
|---|
| Alstom |
| Siemens |
| CRRC |
| ABB |
| Nexans |
| NKT |
| Strukton |
| TE Connectivity |
| Wabtec |
| Others |
Value Network & Pricing Analysis
Copper concentrate supply concentration in Chile and Peru determines both pricing tier spreads and supply chain shape across railway electrification infrastructure. Procurement managers face margin compression when fixed-price EPC contracts encounter concentrate market disruptions, forcing risk reallocation toward commodity-linked pricing clauses and dual-sourcing mandates.
Pricing Analysis
Certification level under EN 50149 and GB standards creates the primary spread between premium European corridor contracts and cost-optimized Asian deployments. Three-tier pricing structure across premium, standard, and economy levels reflects pantograph-catenary interaction quality guarantees, with Deutsche Bahn and SNCF Réseau specifications commanding 40-60% uplifts over Indian CEA-mandated trunk routes. Cost compression in the economy tier is intensifying because Chinese manufacturers leverage captive copper processing capacity. Freight operators and infrastructure developers exhibit highest price sensitivity; integrated system providers with predictive maintenance overlays demonstrate lowest.
Supply Chain Analysis
Nexans and NKT hold contract-manufacturing concentration for high-voltage cable assemblies serving traction substation integration. Geographic supply concentration centers on China for copper contact wire and messenger cable production, Germany for precision tensioning equipment, and India for galvanized structural components. Raw material dependencies draw from Chilean copper concentrate, Chinese rare earth processing for composite additives, and European specialty steel for cantilever assemblies. Single-source vulnerability pervades continuous-annealed copper-magnesium alloy supply qualified to SNCF Réseau specifications. Distribution runs through EPC contractors and state rail authority tender processes with extended qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as state rail authorities consolidate procurement through framework agreements, fragmenting legacy supplier relationships and compressing margins for non-integrated component vendors.
For Market Incumbents: Entrench integrated signaling-catenary positions through predictive maintenance overlay investments that extend hardware lifecycle guarantees. Anchor premium corridor specifications by deepening backward integration into composite contact wire production, countering CRRC scale advantages. Defend against digital-native entrants by embedding LiDAR pantograph monitoring into availability-based contracts with British Network Rail and Australian ARTC. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia greenfield high-speed corridors where rigid overhead conductor rail specifications bypass legacy 15 kV 16.7 Hz interoperability constraints. Target composite material qualification for coastal and high-humidity routes where carbon-fiber reinforced aluminum conductors command specification premiums. Pursue joint-venture structures with domestic installation contractors to overcome certified rigging crew scarcity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated system providers with captive digital asset management capabilities. Long-term viability rests on positioning across electrification infrastructure cycles spanning 5-10 year national carbon commitment windows. Acquisition target archetype: mid-scale composite material specialists with EN 50149 qualification progress and Southeast Asian project references. Monitor copper concentrate supply disruption frequency as inflection indicator for pricing model shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Processing | Captive supply of continuous-annealed alloys secures Deutsche Bahn qualification and margin protection. |
| Digital Twin Platform Deployment | AI-driven wear prediction creates recurring revenue streams with SNCF Réseau and Network Rail. |
| Composite Material Certification Investment | Carbon-fiber reinforced aluminum qualification opens coastal route specifications in Italy and Vietnam. |
| Southeast Asian Joint Venture Formation | Local installation capacity addresses certified rigging crew scarcity on concurrent project schedules. |
| SF6-Free Switchgear Requalification | Vacuum-interrupter alternatives meet EU F-Gas Regulation timelines for Spanish and Italian tenders. |
Research Methodology
Desk research of customs trade data, railway infrastructure tender databases, and regulatory filing precedents preceded structured interviews with procurement directors at state rail authorities, EPC contract managers, catenary system engineering leads, and aftermarket service heads. Secondary validation drew from Deutsche Bahn technical specifications, Indian CEA electrification directives, EU F-Gas Regulation implementation guidance, and MIIT GB standard documentation. Bottom-up project pipeline assessment triangulated against top-down national electrification commitment aggregation.
Assumptions held copper price volatility within historical bands, regulatory phase-out timelines per published EU and Indian schedules, and high-speed rail construction cadence per disclosed national plans. Segmentation dimensions modeled encompass product architecture, installation environment, material grade, and end-user contract structure. CAGRs were derived from volume-weighted corridor deployment projections. Industry-specific forecast inputs included pantograph-catenary interaction quality thresholds and composite material qualification timelines.
Stress conditions across copper concentrate supply disruption severity, regulatory harmonization delays between EN and GB standards, and certified installation technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions with acknowledgment that unmodeled commodity price spikes or accelerated modal shift mandates could revise trajectory. Quarterly review of tender award volumes and qualification standard update frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Latin America Connected Rail Market
Railway
Locomotive Doors Market
Railway
Railway Buffer Stops Market
Railway
Rail Brace Market
Railway
Maglev Train Market
Railway
Asia Pacific Rail Freight Transport Market
Railway
Railway Window Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Rail Maintenance Management System Market
Railway
Locomotive Parking Brake Market
Railway
Rail Brake Frame Market
Railway
Trams Market
Railway
40-Foot Platform Wagons Market
Railway
Railway Horn Market
Railway
Gearbox for Rail Vehicles Market
Railway
Rail Transit Traction Converter Market