
 Electro-Pneumatic Train Brakes Market | 2026-2036
Electro-Pneumatic Train Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Pneumatic Train Brakes Market Analysis
China's rail manufacturing belt is fragmenting as domestic capacity for electro-pneumatic brake systems expands beyond state-owned locomotive builders. Wabtec Corporation leverages its North American service network to sustain aftermarket revenue streams for freight brake retrofits. Knorr Brake Company anchors European high-speed passenger contracts through its specialization in electronically controlled pneumatic architectures. Nabtesco Corporation competes in precision valve and control module supply for Japanese Shinkansen derivatives exported to Southeast Asia.
Electro-pneumatic train brakes integrate electrically signaled control commands with pneumatic actuation pressure, typically operating at 5 bar service pressure with emergency escalation to 8.5 bar within two seconds for freight consist protection. Their primary purpose is to eliminate the propagation delay inherent in pure pneumatic brake pipes across long train formations, enabling synchronized braking response. Service brakes dominate current revenue across freight and passenger installations, while data acquisition systems represent the fastest-growing technology segment as predictive maintenance mandates spread. Retrofit systems command premium pricing relative to new installations due to integration complexity with legacy pneumatic infrastructure.
The Federal Railroad Administration enforces brake performance standards under 49 CFR Part 232, compelling US freight operators toward electronically controlled pneumatic conversions for unit coal and intermodal trains. The European Union Agency for Railways coordinates interoperability standards through TSIs that mandate brake control compatibility across transnational corridors. China's National Railway Administration implements GB standards for high-speed train braking that incorporate electro-pneumatic redundancy requirements. Stakeholders must monitor regulatory divergence between North American precision train control mandates and European interoperability frameworks when allocating R&D budgets across product platforms.
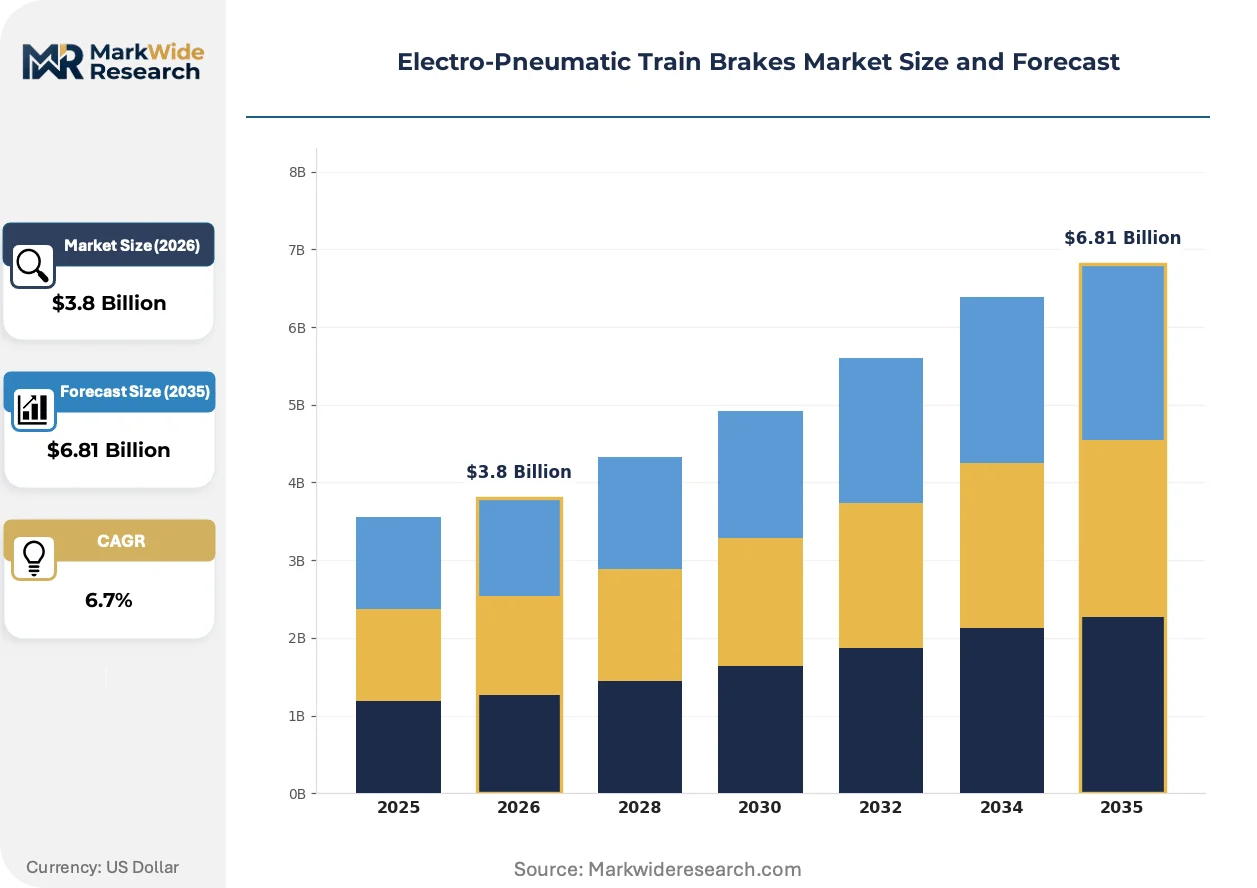
Market Dynamics
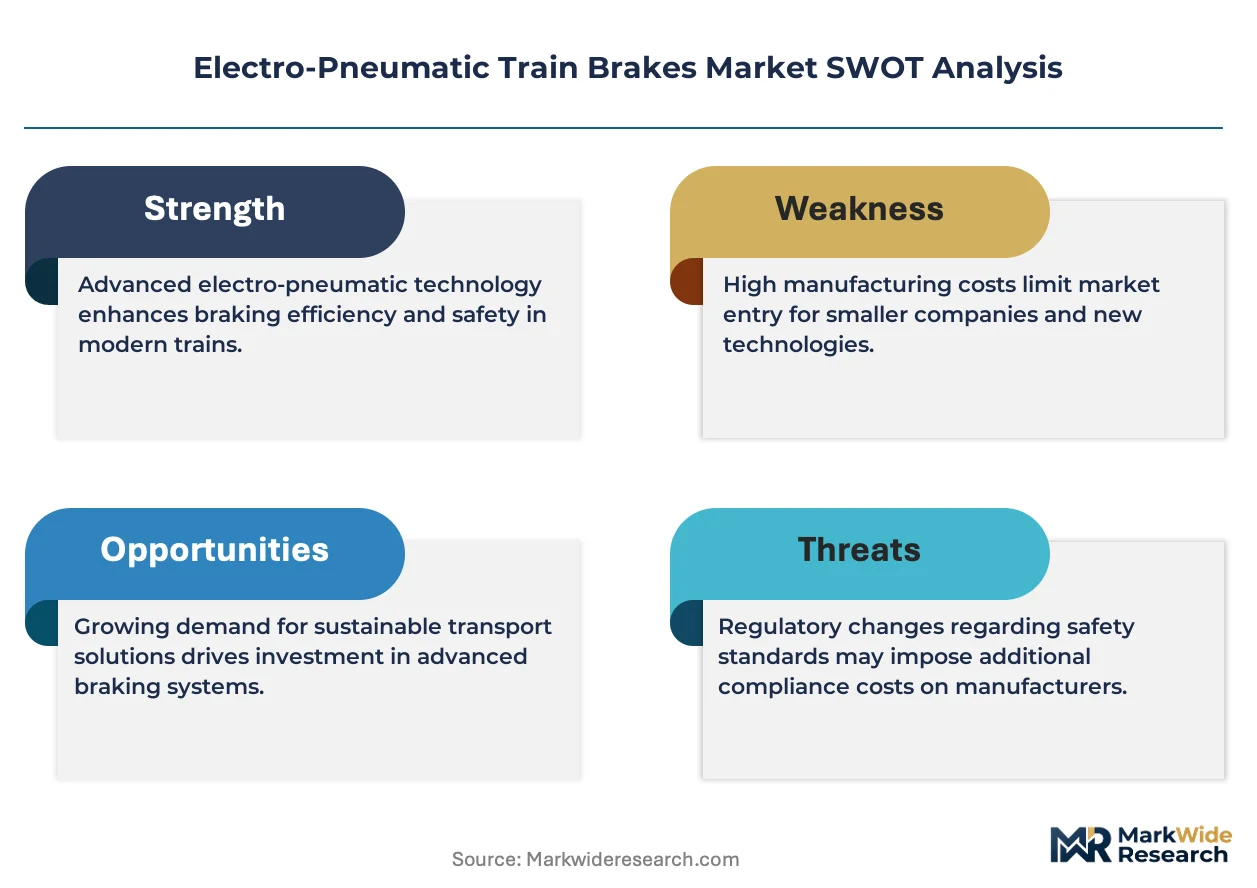
Freight operators face mounting pressure to eliminate propagation delays across kilometer-long consist formations, compelling wholesale replacement of pure pneumatic brake pipes with electronically controlled architectures that synchronize braking response across all cars.
Growth Catalysts
- EU F-Gas Regulation:Mandates under the F-Gas Regulation and MDR pressure rail OEMs toward electronically controlled brake architectures with reduced refrigerant dependency in auxiliary systems.
- High-speed freight corridors:China's state-backed rail modernization programs prioritize electro-pneumatic braking for new dedicated freight lines capable of sustained speeds.
- Precision train control:US freight operators convert unit coal and intermodal trains to meet Federal Railroad Administration performance standards under 49 CFR Part 232.
Market Restraints
- Copper and semiconductor input costs:Control module production depends on copper windings and automotive-grade semiconductors subject to price volatility and allocation constraints.
- Legacy infrastructure lock-in:Existing pneumatic brake pipe networks in North American freight yards create path dependency that slows full-system replacement cycles.
- Compressed air substitution risk:Hydraulic brake actuation for very heavy haul mining applications threatens electro-pneumatic penetration in the highest-tonnage segments.
Strategic Opportunities
- Southeast Asian export corridors:Japanese Shinkansen derivative exports to Thailand, Malaysia, and Indonesia create demand for precision valve and control module supply.
- Predictive maintenance mandates:Data acquisition systems integration with electro-pneumatic architectures opens recurring revenue streams through condition-based monitoring contracts.
- Interoperability standardization:EU Agency for Railways coordination of TSIs across transnational corridors favors suppliers with certified multi-system compatibility.
Industry Challenges
- Mechatronics engineering scarcity:The specialized workforce bridging pneumatic actuation and electronic control system design commands premium compensation and extended recruitment timelines.
- Retrofit integration complexity:Legacy pneumatic infrastructure in existing freight consists demands custom engineering for electro-pneumatic overlay without full car rebuilds.
- Multi-jurisdiction certification:Brake control systems require sequential approval under GB standards, TSIs, and FRA regulations before cross-border deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Pneumatic Train Brakes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Brakes, Emergency Brakes, Parking Brakes, Dynamic Brakes End User: Freight Operators, Passenger Transport, Rail Infrastructure, Urban Transit Installation Type: Trailer-mounted, Locomotive-integrated, Retrofit Systems, New Installations Technology: Electro-Hydraulic, Fully Electronic, Pneumatic Control, Data Acquisition Systems |
| Companies Covered | Mitsubishi Heavy Industries Ltd., Akebono Brake Industry Co. Ltd., Knorr Brake Company, Voith Gmbh & Co. KGaA, Parker Hannifin Corporation, Wabtec Corporation, Nabtesco Corporation, Schaltbau GmbH, DAKO-CZ A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Pneumatic Train Brakes Market Emerging Trajectories
Electronically controlled pneumatic architectures are compressing the competitive window for suppliers as freight operators demand synchronized braking across longer train formations with embedded diagnostic capabilities.
Digital brake control units with integrated wheel slide protection and load-compensated pressure modulation are rendering obsolete standalone pneumatic distributors that lack real-time feedback loops. European high-speed passenger operators now specify these architectures as baseline requirements. The technology is compressing supplier margins on legacy pneumatic-only product lines.
The European Union Agency for Railways is tightening TSI interoperability mandates for brake control compatibility across transnational freight corridors. This regulatory pressure forces component suppliers to engineer multi-protocol control software rather than single-standard architectures. North American precision train control mandates are diverging from European frameworks, complicating platform development budgets.
Freight operators now unbundle after-sales service contracts from initial system procurement, selecting specialized maintainers based on diagnostic data access rather than OEM affiliation. This procurement pattern disrupts traditional captive service relationships. The shift is most visible in US Class I railroads and Australian bulk commodity haulers seeking to reduce lifecycle costs through competitive tendering of brake system maintenance.
Electro-Pneumatic Train Brakes Market Segmentation
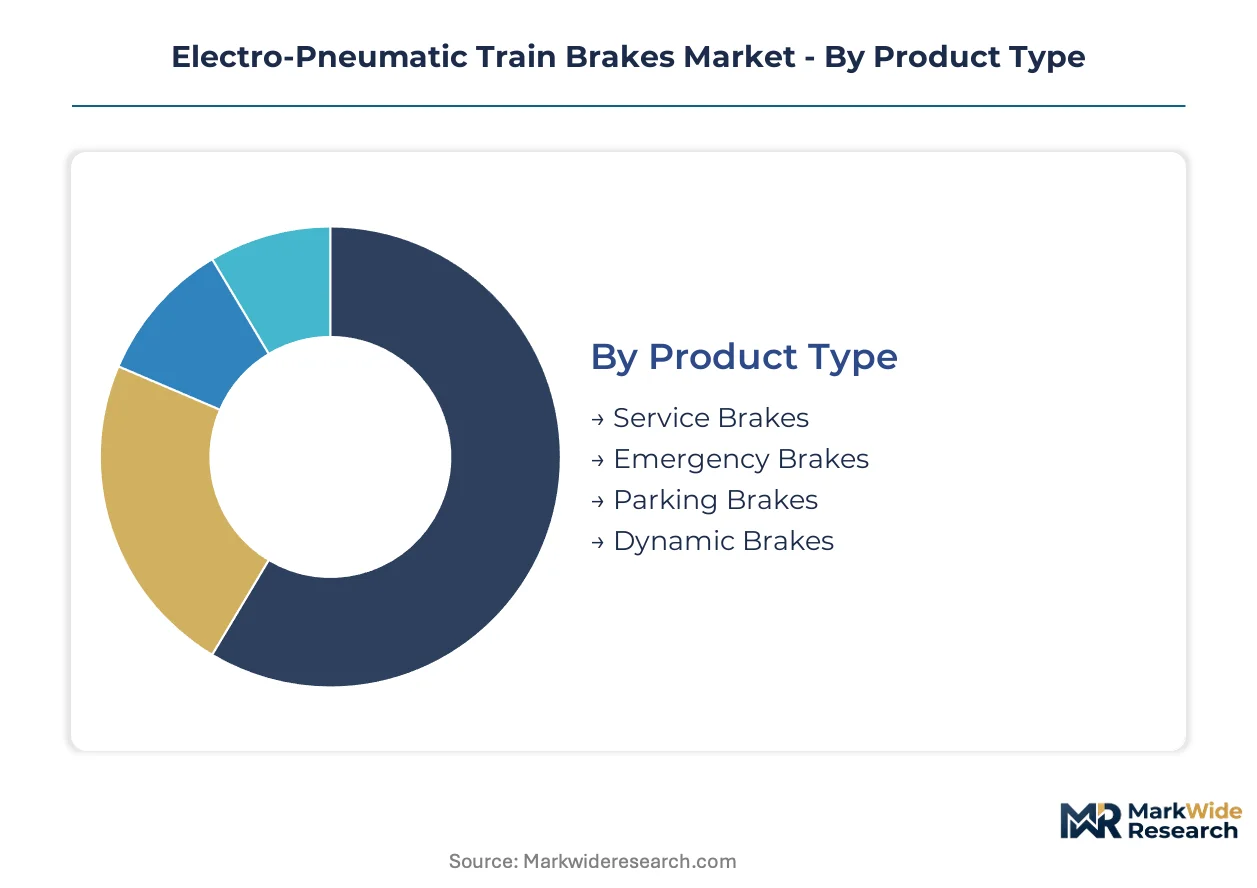
Electro-pneumatic train brake procurement diverges sharply across operational contexts, with freight operators prioritizing propagation speed over passenger systems emphasizing ride comfort. Installation decisions hinge on legacy infrastructure age, creating distinct retrofit versus new-build economics that reshape supplier pricing power.
Product Type:
Cost tier differentiation separates maintenance-critical service applications from emergency-only systems with minimal duty cycles.
- Service Brakes:These systems modulate pressure through electronically controlled pneumatic valves for routine deceleration, typically cycling thousands of times per route. Chinese freight corridors on the Beijing-Guangzhou dedicated heavy-haul line specify these for synchronized braking across 100-plus car formations, driven by state mandates for reduced stopping distances on high-speed freight.
- Emergency Brakes:Architectures escalate to 8.5 bar pressure within two seconds when electrical command signals trigger full pneumatic dump. European high-speed passenger operators under EU Agency for Railways TSI mandates require redundant emergency paths independent of service brake electronics, constraining design flexibility but ensuring fail-safe performance.
- Parking Brakes:Spring-applied pneumatic release mechanisms secure stationary rolling stock on graded track.
- Dynamic Brakes:Rheostatic or regenerative electric braking supplements pneumatic friction systems during routine operations.
Service brakes command the established base. The steepest expansion runs through data-integrated dynamic brake architectures.
End User:
Customer type determines specification intensity, with freight operators accepting higher maintenance burdens than passenger systems demanding flawless reliability.
- Freight Operators:US Class I railroads convert unit coal and intermodal trains under Federal Railroad Administration 49 CFR Part 232 enforcement, prioritizing propagation delay elimination over energy recovery. The segment tolerates higher lifecycle costs in exchange for consist integrity across kilometer-long formations.
- Passenger Transport:Shinkansen derivatives exported to Thailand and Malaysia require precision valve response for ride comfort metrics, with Japanese specifications limiting jerk rates during brake application. Operators specify integrated wheel slide protection as baseline, not optional.
- Rail Infrastructure:Maintenance-of-way equipment and work trains carry lighter braking requirements than revenue service.
- Urban Transit:Metro operators prioritize rapid cycling capability for short station spacing.
Freight operators anchor procurement volume. Passenger systems generate the highest margin per installation.
Installation Type:
Volume concentration shifts toward retrofit as North American and European railcar fleets age beyond original design life.
- Retrofit Systems:Overlay architectures integrate electronic control modules with existing pneumatic pipe networks, demanding custom engineering for each car series. Australian bulk commodity haulers competitively tender these conversions to extend fleet life without full rebuilds, creating aftermarket revenue concentration for diagnostic-capable suppliers.
- New Installations:Factory-integrated electro-pneumatic architectures specify matched control software and valve trains from single-source suppliers, common on Chinese-built export locomotives for Belt and Road corridor deployment.
- Trailer-mounted:Distributed control modules on individual freight cars enable synchronized response.
- Locomotive-integrated:Centralized brake control computers manage entire consist pressure from lead unit.
New installations retain specification authority. Retrofit demand is climbing fastest as fleet age thresholds trigger replacement cycles.
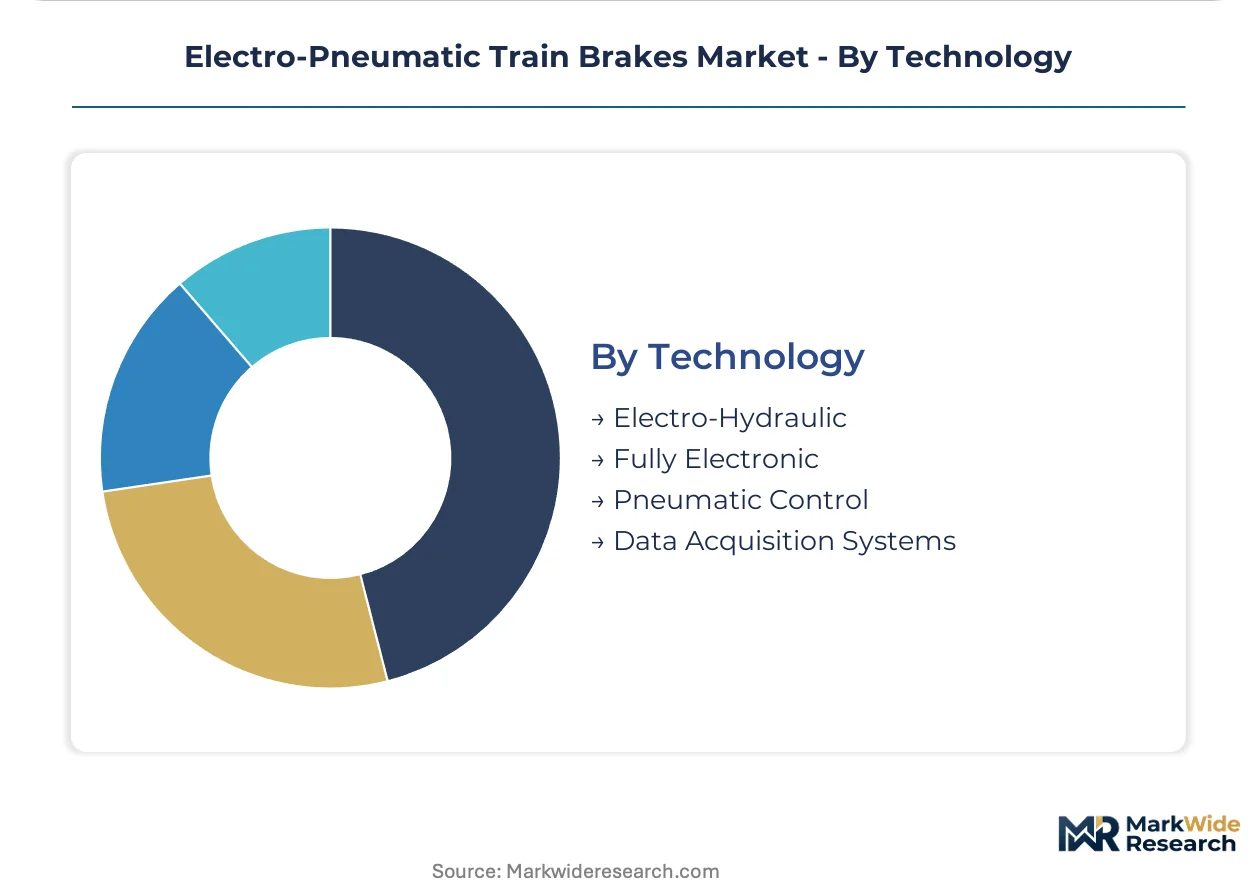
Technology:
Maturity gradients separate proven pneumatic-electronic hybrids from emerging fully electronic architectures still seeking regulatory acceptance.
- Data Acquisition Systems:Embedded sensors monitor brake cylinder pressure, pad wear, and valve response timing for predictive maintenance contracts. US Class I railroads unbundle service procurement from initial system purchase based on diagnostic data access, disrupting traditional OEM captive relationships.
- Fully Electronic:Brake-by-wire architectures eliminate pneumatic actuation entirely, with electromechanical calipers responding to digital commands. European high-speed trials under EU Agency for Railways supervision test these for eventual TSI inclusion, though current mandates still require pneumatic backup.
- Electro-Hydraulic:Fluid actuation serves very heavy haul mining applications where pneumatic pressure proves insufficient.
- Pneumatic Control:Legacy architectures without electronic signaling persist in older consist formations.
Pneumatic control retains the installed base. Data acquisition systems are expanding most quickly as predictive maintenance mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Guangzhou dedicated heavy-haul line underwrites China's central role in electro-pneumatic brake deployment, while transcontinental freight corridors in North America and Europe's high-speed passenger networks shape distinct procurement patterns across major rail jurisdictions.
China
State-backed modernization of dedicated freight corridors drives electro-pneumatic adoption across 100-plus car formations on the Beijing-Guangzhou line. The National Railway Administration enforces GB standards incorporating electro-pneumatic redundancy requirements for high-speed train braking. Manufacturing capacity concentrates in the Yangtze River Delta as domestic suppliers expand beyond state-owned locomotive builders.
United States
Class I railroads convert unit coal and intermodal trains to eliminate propagation delays across kilometer-long consists. The Federal Railroad Administration enforces brake performance standards under 49 CFR Part 232, compelling electronically controlled pneumatic conversions. Aftermarket service networks cluster around Chicago and Omaha as operators unbundle maintenance contracts from initial procurement.
Germany
High-speed passenger operators under EU Agency for Railways jurisdiction specify integrated wheel slide protection as baseline requirements. The F-Gas Regulation and MDR pressure rail OEMs toward electronically controlled brake architectures with reduced refrigerant dependency. Engineering competence concentrates in Baden-Württemberg and Bavaria, where precision valve specialists serve transnational corridor contracts.
Japan
Shinkansen derivative exports to Thailand, Malaysia, and Indonesia generate demand for precision valve and control module supply. METI coordinates domestic standards with overseas project requirements for Southeast Asian deployment. Manufacturing clusters in the Kansai and Chubu regions supply brake systems for export locomotives deployed on Belt and Road corridors.
Australia
Bulk commodity haulers competitively tender electro-pneumatic retrofits to extend fleet life without full rebuilds of aging pneumatic infrastructure. The national rail safety regulator mandates brake performance benchmarks for heavy-haul iron ore and coal operations. Maintenance providers concentrate in Perth and Brisbane, serving Pilbara mining routes and Queensland coal networks with diagnostic-capable aftermarket services.
Electro-Pneumatic Train Brakes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision valves, control modules, and electronic units to multiple OEMs. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive rail divisions, pure-play brake system specialists, and precision component suppliers serving multiple vehicle platforms. Competitive dynamics center on diagnostic data access rights and multi-jurisdiction certification speed rather than manufacturing scale alone. Consolidation pressure operates through technology licensing partnerships and geographic expansion into aftermarket service territories.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd. and Voith GmbH & Co. KGaA occupy positions spanning complete brake system integration through precision component supply. Wabtec Corporation exemplifies the aftermarket-focused archetype, leveraging North American service density for retrofit revenue concentration. Knorr Brake Company and Nabtesco Corporation represent pure-play specialists anchoring regional high-speed passenger and precision valve segments respectively.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd. |
| Akebono Brake Industry Co. Ltd. |
| Knorr Brake Company |
| Voith Gmbh & Co. KGaA |
| Parker Hannifin Corporation |
| Wabtec Corporation |
| Nabtesco Corporation |
| Schaltbau GmbH |
| DAKO-CZ A.S. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese brake valve manufacturing is compressing margins for commodity pneumatic components while tightening supply for automotive-grade semiconductors. This utilization divergence forces suppliers to absorb copper winding cost volatility on standard products while extracting premiums for control modules with embedded diagnostic capability.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European procurement, with refrigerant-compliant architectures commanding certification premiums over legacy systems. Three-tier pricing structure across premium, standard, and economy levels separates TSI-certified multi-protocol systems from single-standard domestic configurations. Cost compression in standard valve trains is intensifying because Chinese state-owned locomotive builders are internalizing capacity. Freight operators in North America exhibit highest price sensitivity due to unbundled service procurement, while Japanese Shinkansen derivative projects show lowest sensitivity given embedded wheel slide protection mandates.
Supply Chain Analysis
Contract manufacturing for control module assembly concentrates in Malaysia and Thailand, with precision valve machining anchored in Germany and Japan. Copper windings for electromagnetic valves draw from Chilean and Zambian concentrate, while automotive-grade semiconductors rest on Taiwanese foundry output. Single-source vulnerability runs through specialty pressure sensor supply. Distribution runs through OEM captive channels for new installations and competitive tender networks for retrofit aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-pneumatic train brake procurement is restructuring around diagnostic data access rights, with predictive maintenance contracts expanding faster than hardware shipments across US Class I railroads and Australian bulk haulers.
For Market Incumbents: Build switching-cost moats through proprietary brake health data platforms that lock operators into recurring analytics subscriptions. Capture backward integration into copper winding supply to hedge commodity volatility. Defend against hydraulic brake substitution in mining applications by embedding load-compensated pressure modulation as standard. For New Entrants and Emerging Players: Pursue Southeast Asian export corridors for Japanese Shinkansen derivatives, where precision valve supply remains fragmented among component specialists. Target Australian retrofit tenders where diagnostic capability outweighs OEM affiliation in procurement scoring. Enter through condition-based monitoring software partnerships with established maintenance providers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across data acquisition system sub-segments as sensor commoditization reduces hardware content. Five-to-ten year viability favors suppliers with certified multi-jurisdiction platforms over single-standard specialists. Prioritize acquisition targets with GB standards and TSI approvals already secured. Monitor US Class I railroad unbundling trends as inflection signal for aftermarket revenue concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Integration | Embedded brake health analytics lock operators into recurring service contracts beyond hardware procurement. |
| Multi-Jurisdiction Certification | Simultaneous GB standards, TSI, and FRA approvals enable cross-border deployment without sequential delays. |
| Copper Supply Backward Integration | In-house winding production hedges commodity volatility pressuring control module margins. |
| Predictive Maintenance Partnership | Software alliances with maintenance providers bypass OEM captive relationships in retrofit tenders. |
| Hydraulic Substitution Defense | Load-compensated pressure modulation features protect electro-pneumatic position in heavy-haul mining. |
Methodological Framework
A spread of perspectives from brake system procurement directors, fleet maintenance managers, regulatory compliance officers, and precision valve engineering heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FRA enforcement records, EU Agency for Railways TSI documentation, and Chinese National Railway Administration GB standard filings. Bottom-up car-level installation estimates and top-down OEM revenue triangulation anchored volume figures.
Demand-supply balance modeling across the projection horizon incorporated freight operator conversion timelines, passenger fleet replacement cycles, and mining sector hydraulic substitution risk. Segmentation dimensions covered product architecture, end-use operational context, installation type, and technology maturity tier. CAGRs derived from fitted growth curves against regulatory mandate deadlines and fleet age distribution analysis. Industry-specific inputs included propagation delay tolerance thresholds and diagnostic mandate adoption curves.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility and semiconductor allocation constraints would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and state-backed rail modernization commitment levels. Quarterly review of Class I railroad unbundling announcements and EU TSI revision timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Railway Bearing Market
Railway
Rail Glazing Market
Railway
Railway Horn Market
Railway
Automatic Train Operation System Market
Railway
Global Hyperloop Train Market
Railway
Global Train Brake Market
Railway
France Rail Freight Transport Market
Railway
Train Locomotive Suspension Market
Railway
Global Smart Locomotive Market
Railway
Rolling Stocks Market
Railway
Rail Transit Traction Converter Market
Railway
Railroad Tie Market
Railway
40-Foot Platform Wagons Market
Railway
Train Suspension System Market
Railway
Railway System Market