
 Europe Intermodal Terminals Market | 2026-2036
Europe Intermodal Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intermodal Terminals Market Foresight
Multi-source terminal partnerships is broadening across European freight corridors. DP World Logistics Europe leverages its pan-European network to integrate maritime and rail flows. TX Logistik anchors cross-border rail connections between Germany, Italy, and Scandinavia. Maersk competes through controlled inland access points that extend ocean carrier reach into continental supply chains.
Europe intermodal terminals are integrated transport nodes where cargo transfers between rail, road, and waterway modes using standardized containers with TEU capacities ranging from twenty-foot to forty-foot equivalents. These facilities employ gantry cranes, reach stackers, and automated gate systems to minimize dwell times and maximize throughput for continental supply chains. Container terminals dominate volume throughput due to deep-sea shipping integration, while rail terminals capture structural growth from EU modal shift policies targeting road-to-rail conversion. Automation systems within the technology segment concentrate investment returns where labor costs and throughput density justify capital deployment.
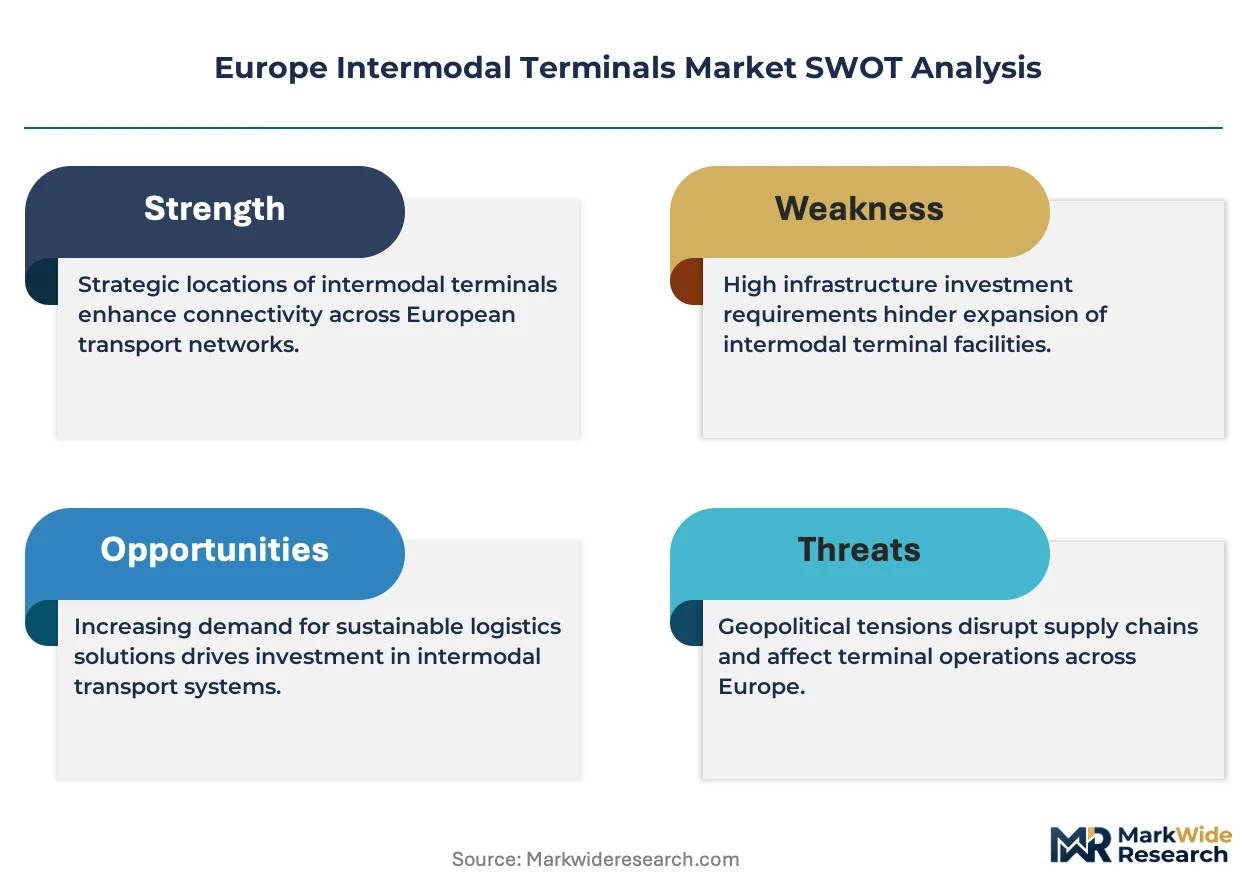
The EU Green Deal and F-Gas Regulation shape infrastructure investment priorities by penalizing carbon-intensive road haulage and channeling public funds toward electrified rail corridors. ECHA chemical handling standards and national workplace safety regulators enforce equipment specifications and operational protocols at hazardous cargo terminals. Stakeholders must monitor how the EU AI Act and forthcoming automated vehicle frameworks redefine terminal gate operations and yard management liability.
Market Dynamics
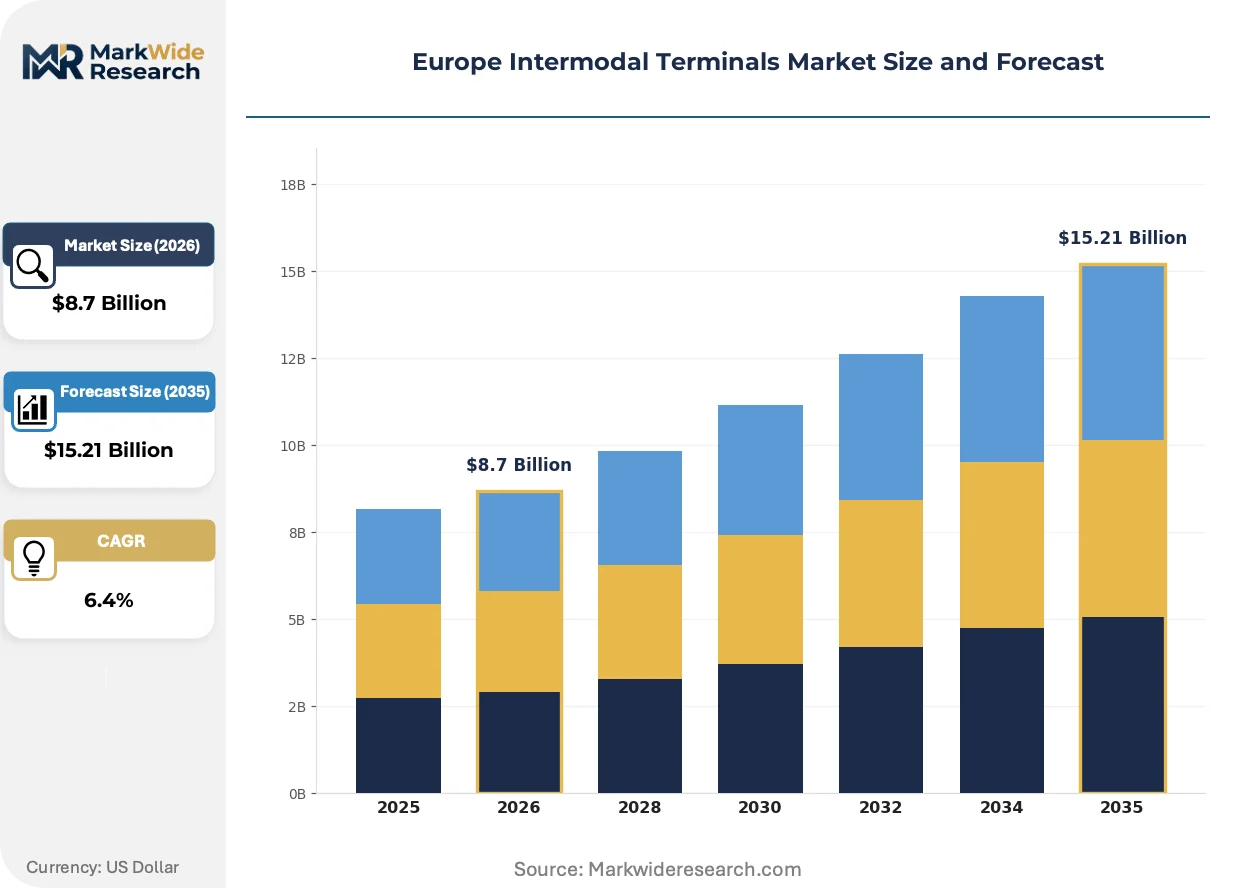
The EU Green Deal's modal shift mandates are restructuring freight flows across continental corridors, forcing terminal operators to reconfigure yard layouts for electrified rail handling while public funding redirects toward intermodal infrastructure.
Growth Catalysts
- Rail Electrification Mandates:The EU Green Deal targets 75% rail freight growth by 2030, channeling infrastructure investment toward intermodal nodes with electrified crane systems and zero-emission yard equipment.
- Retailer Cost Optimization:German and Dutch retail distribution networks are consolidating inland logistics through Rhine-Ruhr corridor terminals to bypass road toll escalations and fuel price volatility.
- Container Standardization:TEU and FEU container uniformity across deep-sea and continental rail networks reduces transshipment friction at Rotterdam, Hamburg, and Antwerp gateway facilities.
Market Restraints
- Land Scarcity at Port Hinterlands:Terminal expansion faces zoning restrictions in the Netherlands and Belgium where port-adjacent industrial land commands premium lease rates.
- Crane Electrification Capex Burden:Conversion from diesel to electric gantry systems requires capital outlays that strain mid-sized terminal operators without public co-financing.
- Rail Infrastructure Bottlenecks:Single-track corridors in Eastern European member states limit throughput capacity for container trains originating from Baltic Sea ports.
Strategic Opportunities
- Danube Waterway Integration:Austrian and Hungarian terminals along the Rhine-Main-Danube corridor can capture agricultural and bulk chemical flows currently moving by road from Black Sea ports.
- EU AI Act Automation Pathways:Automated gate systems and AI-driven yard management qualify for green transition subsidies while reducing labor dependency in high-wage Nordic markets.
- Cross-Border Consolidation:Poland and Czech Republic inland terminals can function as consolidation hubs for Ukrainian grain and industrial exports rerouted from Black Sea blockages.
Industry Challenges
- Crane Operator Certification Delays:National workplace safety regulators in France and Germany enforce extended training periods for automated equipment, constraining workforce scalability.
- Legacy Track Gauge Discontinuities:Iberian Peninsula terminals must maintain dual-gauge handling capability, complicating rolling stock allocation and increasing maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intermodal Terminals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Rail Terminals, Container Terminals, Freight Terminals, Mixed Use Terminals Service Type: Terminal Operations, Maintenance Services, Cargo Handling, Freight Forwarding End User: Logistics Providers, Freight Forwarders, Shipping Companies, Retailers Technology: Automation Systems, Tracking Solutions, Cargo Management Software, Loading Equipment |
| Companies Covered | DP World Logistics Europe, TX Logistik, Container Terminal Dortmund GmbH, Maersk, EP Logistics International, COSCO SHIPPING Ports (Spain) Terminals, Rail Hub Transylvania, MSC Medway, DP World Southampton, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intermodal Terminals Market Shifts & Advancements
Terminal automation and digital freight matching are compressing dwell times while regulatory pressure on emissions intensifies equipment replacement cycles across European corridors.
Automated stacking cranes with AI-powered container positioning are absorbing labor cost pressures in high-throughput facilities. Dutch and Belgian terminal operators deploy these systems fastest, driven by union density and wage escalation. The technology is absorbing volume from manually operated yards as throughput per hectare becomes the decisive competitive metric.
The EU F-Gas Regulation is accelerating phase-out of diesel-powered reach stackers and refrigerated container gensets. Terminal operators face equipment replacement deadlines that compress capital planning horizons. Scandinavian and German facilities lead compliance adoption due to stricter national implementation timelines.
Shipper consolidation of procurement through freight exchanges is fragmenting traditional forwarder relationships. Large retail and automotive manufacturers now contract directly with terminal operators for block train capacity, bypassing intermediaries. This pattern concentrates most visibly in Germany's automotive supply corridors where just-in-time rail contracts displace road haulage agreements.
Europe Intermodal Terminals Market Segmentation
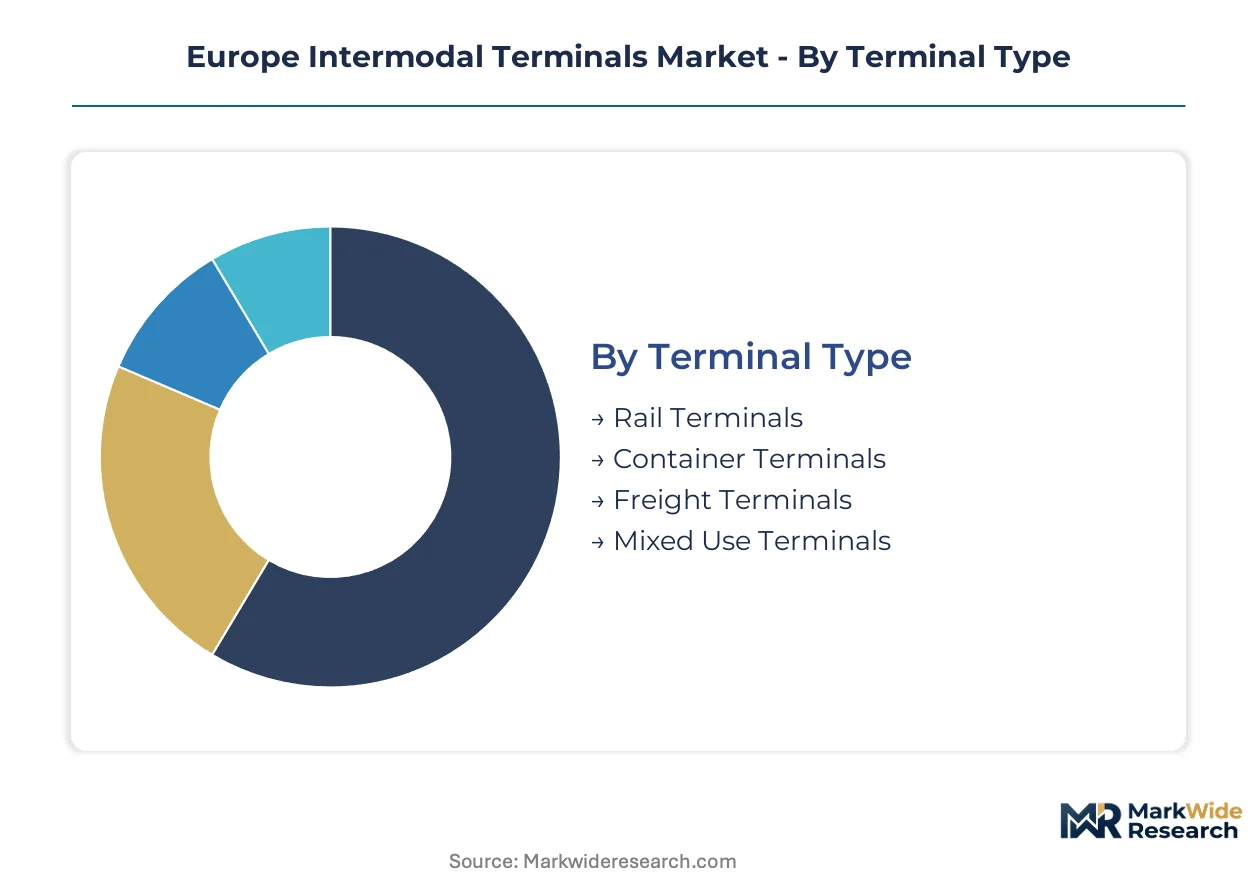
Terminal configuration across Europe varies sharply by cargo flow density and modal integration depth. Understanding how segments cluster around electrified corridors versus maritime gateways shapes infrastructure investment decisions and regulatory compliance pathways.
Terminal Type:
ECHA chemical handling standards and national workplace safety regulators enforce equipment specifications most stringently at freight terminals processing hazardous materials, while container terminals face EU F-Gas Regulation deadlines for diesel equipment phase-out.
- Container Terminals:These facilities handle deep-sea shipping integration with standardized TEU and FEU containers, employing gantry cranes and automated gate systems. Demand concentrates at Rotterdam, Hamburg, and Antwerp gateway facilities where transshipment friction reduction drives throughput optimization under EU Green Deal modal shift mandates.
- Rail Terminals:Dedicated rail-to-rail and rail-to-road transfer points with electrified crane systems and zero-emission yard equipment. Growth accelerates along Germany's Rhine-Ruhr corridor where retailer distribution networks consolidate inland logistics to bypass road toll escalations.
- Freight Terminals:Multi-commodity facilities handling breakbulk and project cargo with specialized handling protocols.
- Mixed Use Terminals:Flexible infrastructure accommodating container, bulk, and breakbulk flows with reconfigurable yard layouts.
Leading the category by volume: Container Terminals. Growing fastest: Rail Terminals.
Service Type:
Service tiers stratify by capital intensity, with terminal operations commanding premium pricing where automation density justifies labor substitution.
- Terminal Operations:Core yard management, gate processing, and container storage services with electrified equipment deployment. Demand clusters at Dutch and Belgian facilities where union density and wage escalation accelerate automated stacking crane adoption.
- Cargo Handling:Physical container movement using reach stackers, straddle carriers, and gantry systems with AI-powered positioning. Scandinavian and German facilities lead compliance-driven equipment replacement under stricter national F-Gas implementation timelines.
- Maintenance Services:Preventive and corrective equipment servicing with certified technician requirements.
- Freight Forwarding:Documentation, customs clearance, and multimodal booking coordination with diminishing forwarder margins.
Highest margin capture: Terminal Operations. Steepest expansion trajectory: Cargo Handling.
End User:
Procurement consolidation through freight exchanges fragments traditional intermediary relationships most visibly among large-volume shippers.
- Logistics Providers:Integrated supply chain operators contracting directly for block train capacity across continental corridors. German automotive supply corridors show just-in-time rail contracts displacing road haulage agreements.
- Retailers:German and Dutch distribution networks consolidating inland logistics through Rhine-Ruhr corridor terminals to reduce fuel price exposure.
- Freight Forwarders:Traditional intermediaries facing margin compression from shipper direct contracting.
- Shipping Companies:Ocean carriers extending controlled inland access points into continental supply chains.
Dominant procurement volume: Logistics Providers. Gaining share fastest: Retailers.
Technology:
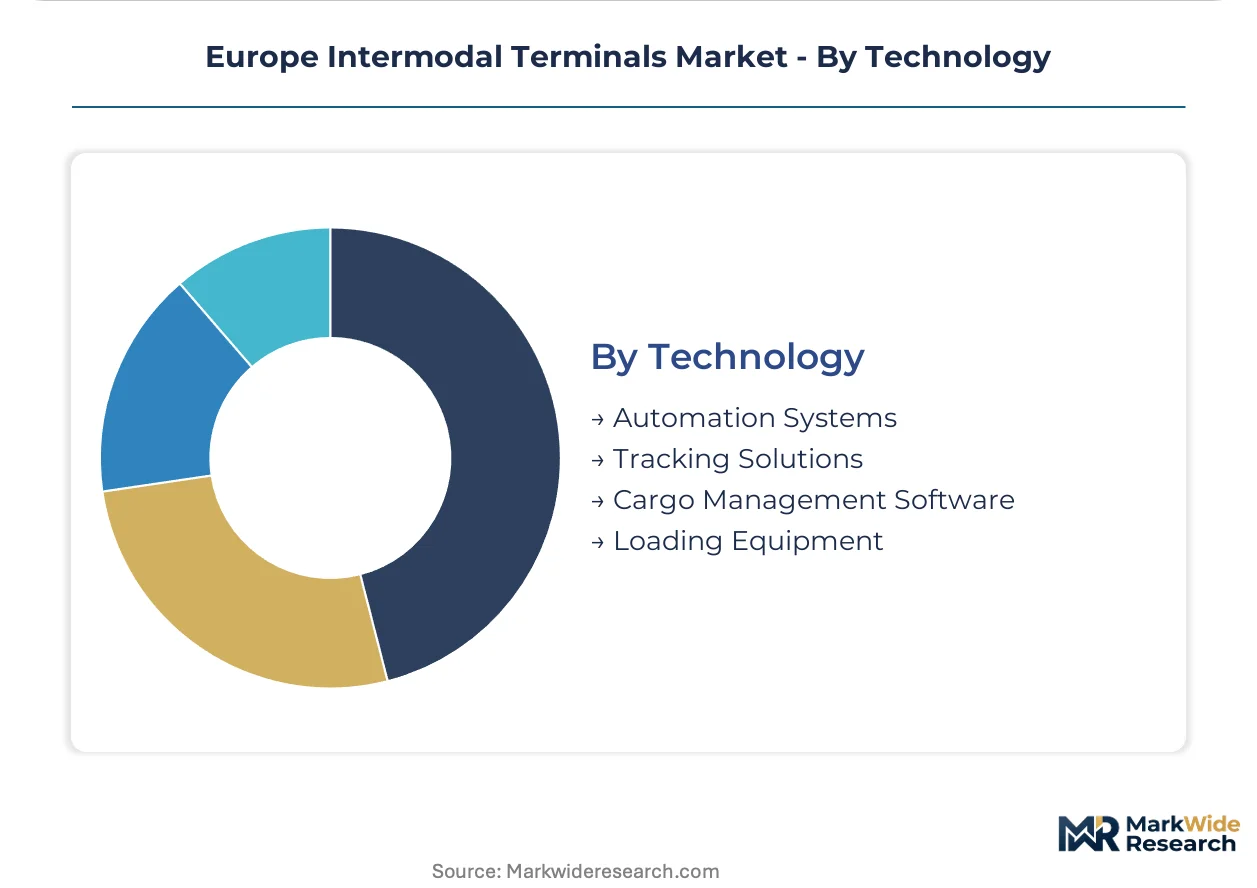
Technology adoption concentrates where throughput density and labor costs justify capital deployment, with EU AI Act frameworks redefining liability for automated operations.
- Automation Systems:Automated stacking cranes, robotic container positioning, and AI-driven yard management qualifying for green transition subsidies. Dutch and Belgian operators deploy these systems fastest.
- Tracking Solutions:Real-time container location and condition monitoring with sensor network integration.
- Cargo Management Software:Terminal operating systems with predictive analytics for dwell time reduction.
- Loading Equipment:Electrified reach stackers and gantry cranes with diesel phase-out deadlines compressing replacement cycles.
Investment concentration: Automation Systems. Compliance-driven replacement: Loading Equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's industrial density anchors European intermodal terminal demand, with coal and steel heritage infrastructure repurposed for containerized freight flows across the continent's north-south axis.
Germany
Automotive manufacturers and chemical producers drive block train contracting through Rhine-Ruhr corridor terminals. The EU Green Deal's rail electrification mandates accelerate gantry crane conversions at Dortmund and Duisburg facilities. North Rhine-Westphalia's terminal operators capture retailer consolidation demand as Dutch and German distribution networks bypass road toll escalations.
Netherlands
Rotterdam port hinterland terminals absorb deep-sea transshipment volumes from Asia-Pacific trade lanes. The F-Gas Regulation compresses diesel equipment replacement timelines for reach stackers and refrigerated container gensets. Randstad logistics clusters deploy automated stacking cranes fastest, driven by union density and wage pressures around Amsterdam and Rotterdam.
Belgium
Antwerp gateway terminals handle petrochemical and container flows between maritime and continental rail networks. Land scarcity at port-adjacent industrial zones constrains yard expansion, elevating throughput-per-hectare optimization. Flemish terminals lead EU AI Act compliance pathways for automated gate systems and AI-driven yard management.
Poland
Ukrainian grain and industrial export rerouting from Black Sea blockages concentrates at Silesian and Łódź inland terminals. National workplace safety regulators enforce extended crane operator certification periods, constraining workforce scalability. Polish rail terminals function as consolidation hubs for east-west corridor capacity.
Austria
Rhine-Main-Danube waterway integration captures agricultural and bulk chemical flows from Black Sea ports previously moving by road. ECHA chemical handling standards enforce equipment specifications at Linz and Vienna hazardous cargo terminals. Austrian operators exploit Danube navigation improvements to displace road haulage on north-south corridors.
Europe Intermodal Terminals Market Competitive Landscape
Global maritime carriers compete with regional rail specialists across terminal access and inland network control. The vendor base clusters around three strategic archetypes: ocean carrier-controlled inland extensions, independent rail terminal operators, and port authority-linked logistics platforms. Consolidation pressure intensifies as shipper procurement consolidation fragments traditional forwarder relationships. Competitive moves concentrate on cross-border terminal partnerships and automation system deployment to capture EU green transition subsidies.
Within the maritime carrier extension tier, Maersk and MSC Medway exemplify ocean-line vertical integration into continental supply chains. Among independent rail specialists, TX Logistik occupies a position anchoring cross-border connections between Germany, Italy, and Scandinavia. DP World Logistics Europe sits within the port-linked platform category, leveraging pan-European network integration across maritime and rail flows. These three archetypes represent the dominant competitive positioning vectors reshaping terminal operator relationships with large-volume retail and automotive shippers.
| Leading Market Players |
|---|
| DP World Logistics Europe |
| TX Logistik |
| Container Terminal Dortmund GmbH |
| Maersk |
| EP Logistics International |
| COSCO SHIPPING Ports (Spain) Terminals |
| Rail Hub Transylvania |
| MSC Medway |
| DP World Southampton |
| Others |
Supply & Pricing Matrix
Horizontal terminal network integration across maritime and rail corridors anchors both supply positioning and pricing power for European intermodal operators. DP World Logistics Europe and Maersk leverage captive inland access points to bundle terminal handling with ocean freight contracts, compressing third-party margins.
Pricing Analysis
Service bundling separates equipment-heavy terminal operations from unbundled cargo handling tariffs. Three-tier pricing structure across premium, standard, and economy levels reflects automation density and electrified crane deployment. Price differentiation hinges on throughput guarantees and EU Green Deal compliance certification. Cost compression in standard-tier handling is intensifying because retailer procurement consolidation fragments forwarder intermediation. Freight forwarders exhibit highest price sensitivity; automotive OEMs with just-in-time contracts show lowest.
Supply Chain Analysis
Direct-to-shipper channels handle hyperscale retailer demand bypassing traditional forwarder networks. Manufacturing of gantry cranes and reach stackers concentrates in Germany, China, and Italy. Electrified yard equipment and AI-driven gate systems draw from specialized component suppliers in the Netherlands and Scandinavia. Single-source vulnerability in crane control software creates chokepoint exposure. Distribution runs through port-linked platforms and independent rail specialists serving continental corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land scarcity at Rotterdam and Antwerp port hinterlands props terminal lease pricing, constraining yard expansion and elevating throughput-per-hectare optimization as the decisive competitive metric.
For Market Incumbents: Acquire electrified crane systems and automated gate infrastructure to defend against automation-lagging mid-tier operators. Secure long-term land leases in Rhine-Ruhr corridor zones before zoning restrictions tighten. Backward integration into renewable power supply for yard electrification reduces EU F-Gas Regulation compliance cost exposure.
For New Entrants and Emerging Players: AI-powered yard management systems offer technology-first entry into Polish and Czech consolidation hubs serving Ukrainian rerouted cargo. Target Danube waterway terminals in Austria and Hungary where agricultural and bulk chemical flows displace road haulage. Partner with rail infrastructure operators for cross-border track access rather than building greenfield facilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in port-linked platform acquisitions by ocean carriers seeking captive inland control. Long-term viability favors operators with electrified equipment deployed and EU AI Act compliance pathways established. Watch German automotive production volumes as inflection indicator for Rhine-Ruhr corridor throughput demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Crane Electrification Deployment | EU Green Deal subsidies offset capital outlays for zero-emission gantry systems at Dutch terminals. |
| AI-Driven Yard Management | EU AI Act compliance pathways reduce labor dependency in high-wage Belgian facilities. |
| Cross-Border Terminal Partnership | TX Logistik anchors Germany-Italy-Scandinavia connections capturing modal shift cargo flows. |
| Danube Waterway Integration | Rhine-Main-Danube corridor terminals capture Black Sea agricultural flows displacing road haulage. |
| Shipper Direct Contracting | Automotive OEMs bypass forwarders for block train capacity in Germany's just-in-time supply corridors. |
Research Methodology
Multi-period observation of terminal throughput volumes, electrification investment flows, and modal shift cargo migrations anchored the trend analysis, supplemented by interviews with terminal operations directors, rail infrastructure planners, EU regulatory affairs specialists, and shipper procurement leads. Secondary validation drew from EU transport statistics, ECHA chemical handling compliance filings, national workplace safety regulator protocols, and customs trade data. Bottom-up facility-level capacity assessments and top-down corridor demand modeling enabled triangulation.
Segment-weighting across terminal type, service tier, technology adoption intensity, and end-user procurement pattern shaped the analytical framework across the analysis window. CAGRs derived from facility expansion pipelines, public infrastructure investment commitments, and shipper contract tenors. Forecast inputs incorporated EU Green Deal modal shift targets and F-Gas Regulation equipment replacement deadlines.
Several conditions sit outside the modeled scope, including geopolitical disruption to Black Sea trade routes, abrupt EU AI Act liability reinterpretation, and unilateral national rail infrastructure spending cuts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Sanitary Systems for Rail Transit Market
Railway
Locomotive Market
Railway
Automatic Train Control Market
Railway
Rail Glazing Market
Railway
Railroad Brake Shoe Market
Railway
Rolling Stocks Market
Railway
Railway Track Market
Railway
Maglev Train Market
Railway
Hydrogen Trains Market
Railway
Railway Braking System Market
Railway
India Rail Freight Transport Market
Railway
Rail Brace Market
Railway
Bullet Train Market
Railway
Global Hyperloop Train Market
Railway
Gearbox for Rail Vehicles Market
Railway
Rail Freight Slot and Path Optimization Platforms Market