
 Zero Gravity Seat Market | 2026-2036
Zero Gravity Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Gravity Seat Market Insights
ISO 26262 functional safety certification is bifurcating the competitive landscape between qualified automotive seat suppliers and uncertified furniture manufacturers. Lear Corporation leverages its vertical integration into frame stamping and mechanism assembly to sustain cost advantages across North American OEM programs. Faurecia anchors its position through dedicated R&D centers in France and China that specialize in electromechanical actuator integration for premium vehicle platforms. Toyota Boshoku dominates the Japanese domestic market with long-term supply agreements tied to Lexus and Toyota flagship models.
A zero gravity seat is a reclined seating mechanism engineered to distribute body weight across multiple contact points, typically achieving a torso-to-thigh angle between 120 and 130 degrees through motorized or manual linkage systems. The design reduces spinal compression and improves circulation, serving therapeutic, ergonomic, and luxury comfort applications in automotive, aviation, healthcare, and consumer furniture settings. Massage chair configurations command the highest margin pools due to embedded heating function and Bluetooth connectivity modules that extend average selling prices. Gaming chair demand is accelerating fastest among retail customers, driven by ergonomic design requirements for extended session use. Fabric and mesh materials lead volume in corporate office deployments where breathability and cost efficiency outweigh leather's premium positioning.
FAA seat certification standards and NHTSA crashworthiness requirements govern aviation and automotive applications respectively, creating dual compliance burdens for cross-sector suppliers. The EU Machinery Directive and CE marking obligations further constrain market access for non-European manufacturers seeking European distribution. Japan's METI ergonomic guidelines and JIS standards shape product specifications for domestic healthcare facility procurement. Stakeholders must monitor divergence between automotive functional safety mandates and consumer furniture liability frameworks as product categories blur across end user segments.
Market Dynamics
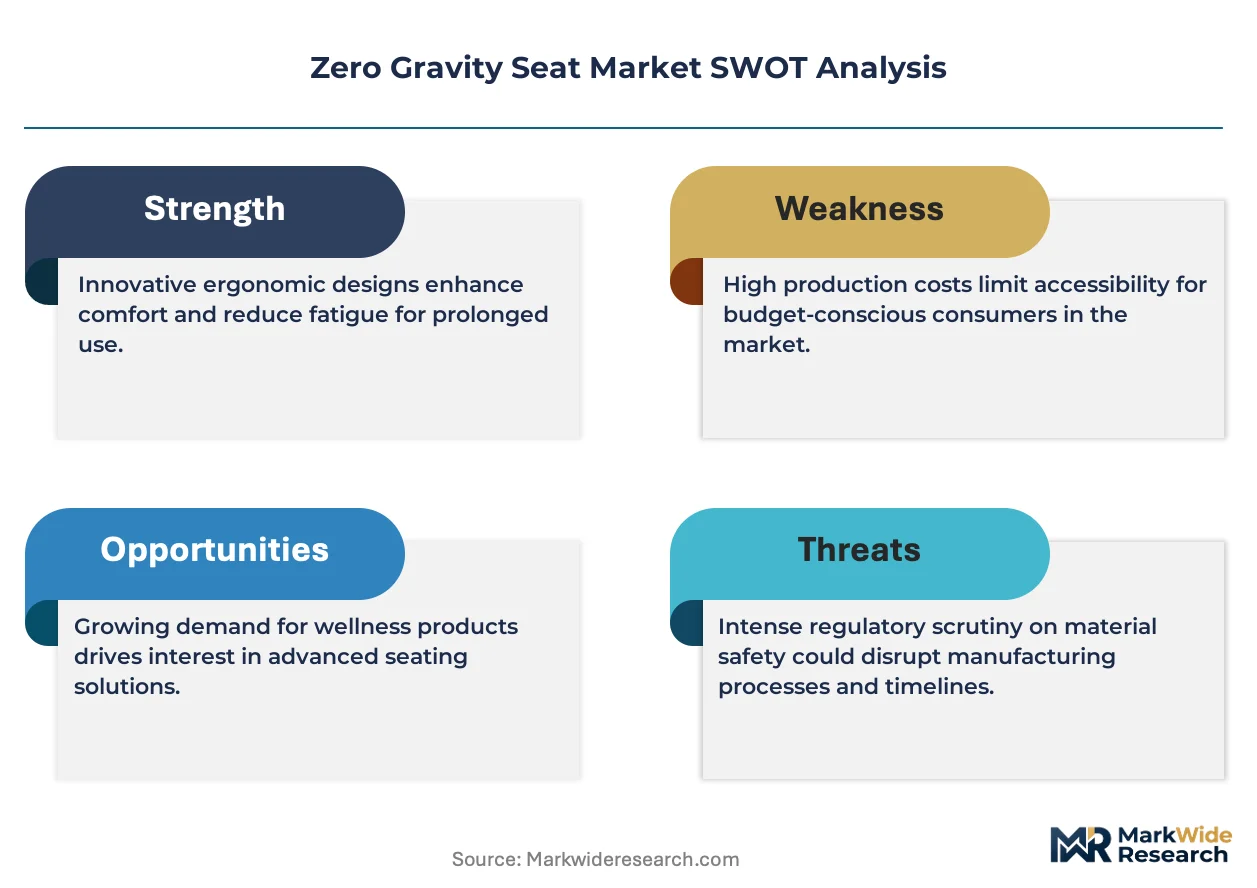
The zero gravity seat market is bifurcating around ISO 26262 functional safety certification, separating qualified automotive suppliers from uncertified furniture manufacturers and reshaping competitive positioning across all segments.
Growth Catalysts
- EU Machinery Directive:CE marking obligations are forcing non-European manufacturers to upgrade production lines for European market access, accelerating consolidation among certified suppliers.
- Aviation cabin retrofits:FAA certification standards for seat crashworthiness are driving replacement cycles in aging commercial fleets across the United States.
- Electromechanical actuator integration:Precision motor systems are enabling smoother position transitions in premium automotive seating programs.
Market Restraints
- Dual compliance burdens:Cross-sector suppliers serving aviation and automotive must simultaneously satisfy FAA seat certification and NHTSA crashworthiness requirements, doubling testing costs.
- Raw material concentration:High-grade steel for frame stamping concentrates in Chinese tier-one manufacturing clusters, creating supply vulnerability.
- Massage chair substitution:Embedded heating and Bluetooth connectivity in consumer massage chairs pulls buyers away from institutional healthcare seating.
Strategic Opportunities
- Japan's METI ergonomic guidelines:New workplace mandates are opening procurement channels for certified zero gravity mechanisms in domestic healthcare facilities.
- Gaming chair retail expansion:Extended session ergonomic requirements are creating a new consumer channel distinct from traditional furniture distribution.
- Mesh material convergence:Breathable fabric technologies from corporate office deployments are transferring to automotive and aviation applications.
Industry Challenges
- ISO 26262 certification timelines:Functional safety validation for automotive programs extends development cycles by 18-24 months.
- Actuator integration complexity:Legacy seat frames require structural redesign to accommodate motorized linkage systems.
- Cross-sector talent scarcity:Engineers with simultaneous expertise in FAA aviation standards and NHTSA automotive requirements command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Gravity Seat Market |
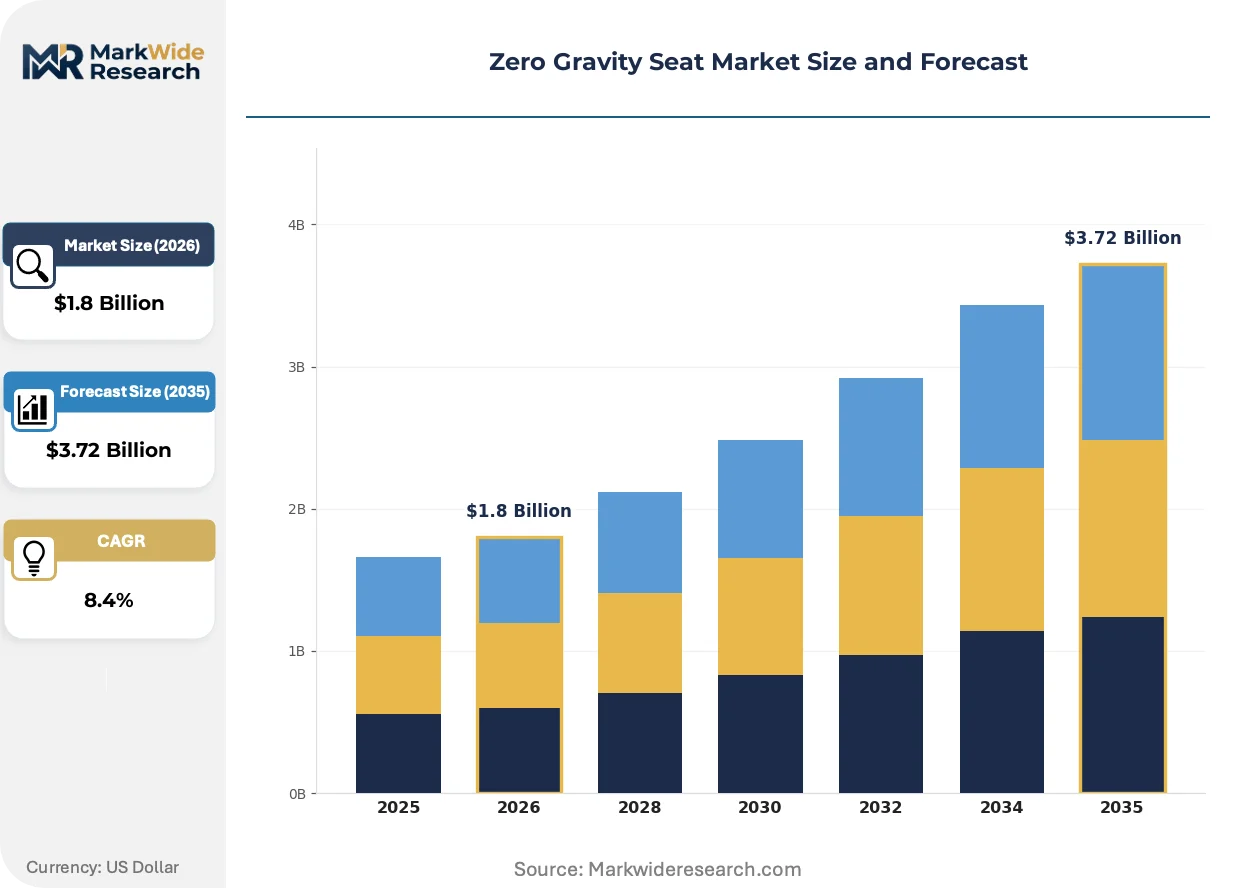
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recliner, Massage Chair, Office Chair, Gaming Chair End User: Retail Customers, Corporate Offices, Healthcare Facilities, Aviation Industry Material: Fabric, Leather, Mesh, Foam Feature: Adjustable Settings, Heating Function, Ergonomic Design, Bluetooth Connectivity |
| Companies Covered | Lear Corporation, Faurecia, Magna International, Yanfeng Adient, Tachi-S, Guanghua Rongchang, Tiancheng Controls, Hongli Zhixin, Toyota Boshoku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Gravity Seat Market Trends and Innovations
Electromechanical systems and regulatory divergence are compressing product development cycles while fragmenting certification pathways across automotive, aviation, and consumer furniture segments.
Brushless DC motor arrays with integrated position sensors are replacing hydraulic actuation in premium seating platforms. Tier-one automotive suppliers in Germany and Japan are adopting these systems for flagship vehicle programs. The technology is miniaturizing mechanism envelopes, allowing zero gravity positioning within compact cabin architectures previously reserved for conventional recliners.
NHTSA is tightening FMVSS 302 flammability testing protocols for automotive interior materials, adding validation stages for multi-layer seat constructions. This regulatory friction is compressing supplier margins and extending homologation timelines. Upholstery manufacturers serving the United States market are responding by consolidating testing partnerships with certified third-party laboratories.
Healthcare facilities are unbundling after-sales service contracts from initial equipment purchases, treating seat mechanisms as consumable assets with finite service lives. This procurement model shift is disrupting traditional manufacturer-distributor relationships in Japan and Germany. Hospital procurement departments now prioritize modular actuator replacement over comprehensive warranty coverage.
Zero Gravity Seat Market Segmentation
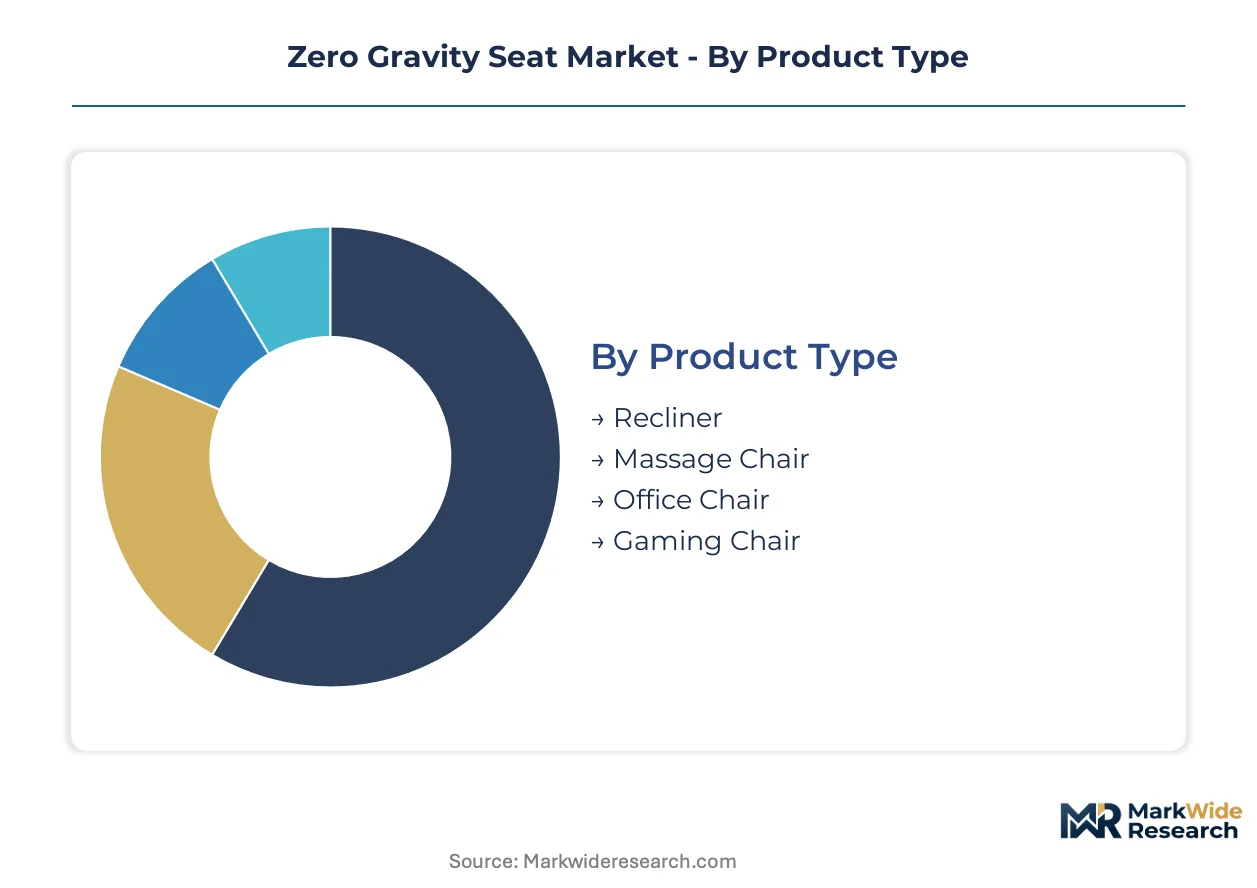
Zero gravity seat procurement patterns diverge sharply across end-use contexts, with automotive and aviation programs demanding certified mechanisms while consumer furniture prioritizes feature density and price accessibility. Manufacturers must configure production lines for dual compliance tracks or accept market exclusion from premium segments.
Product Type:
Domestic assembly dominates recliner and office chair output in North American and European factories, while massage and gaming chair production concentrates in Chinese export hubs serving international retail channels.
- Recliner:Manual linkage systems with motorized upgrades anchor residential living room deployments. Demand concentrates in the United States and Germany where aging demographics prioritize therapeutic positioning for home healthcare.
- Massage Chair:Embedded heating modules and multi-node roller arrays command the highest margin pools across all product categories. Japanese domestic procurement through METI-certified channels sustains premium pricing for therapeutic configurations.
- Office Chair:Breathable mesh variants with synchronous tilt mechanisms dominate corporate fleet purchases. Volume scales through B2B contract furniture distributors in tier-one Chinese manufacturing clusters.
- Gaming Chair:Extended session ergonomic requirements drive retail expansion through direct-to-consumer e-commerce. RGB lighting integration and Bluetooth audio connectivity differentiate premium SKUs from entry-level competitors.
Massage chair configurations hold the largest share; momentum sits with gaming chair demand acceleration.
End User:
Procurement sophistication stratifies sharply, with aviation and healthcare buyers imposing certification burdens that retail channels ignore entirely.
- Retail Customers:E-commerce platforms and big-box furniture chains drive volume through price-transparent comparison shopping. Feature density—heating, massage nodes, connectivity modules—determines purchase decisions more than mechanism durability.
- Corporate Offices:Ergonomic workplace mandates in Japan and Germany are reshaping fleet procurement specifications. Breathable mesh materials and adjustable lumbar support dominate RFP requirements for open-plan workstation deployments.
- Healthcare Facilities:Modular actuator replacement contracts are displacing comprehensive warranty coverage in hospital procurement. Japanese METI guidelines and JIS standards govern therapeutic seating specifications for patient recovery rooms.
- Aviation Industry:FAA crashworthiness certification and flammability testing under FMVSS 302 protocols create insurmountable barriers for uncertified suppliers. Cabin retrofit programs in aging United States commercial fleets accelerate replacement cycle demand.
Aviation and healthcare segments command premium pricing; retail channels expand most quickly through gaming chair crossover appeal.
Material:
Cost tier differentiation separates automotive and aviation leather specifications from corporate office mesh deployments and consumer fabric alternatives.
- Fabric:Polyester-nylon blends with stain-resistant coatings dominate entry-level residential recliners. Volume production scales through Vietnamese and Bangladeshi textile integration.
- Leather:Full-grain hides with multi-layer fire-blocking constructions satisfy NHTSA and FAA flammability protocols. Italian and German tanneries anchor supply for premium automotive flagship programs.
- Mesh:Suspension knit technologies from corporate office seating are transferring to automotive and aviation applications. Breathability and weight reduction drive adoption in German OEM summer comfort packages.
- Foam:High-resilience polyurethane cores with viscoelastic toppers shape pressure distribution in therapeutic configurations. Density grading separates premium healthcare seating from mass-market alternatives.
Leather commands margin leadership; mesh materials gain share fastest through cross-segment technology transfer.
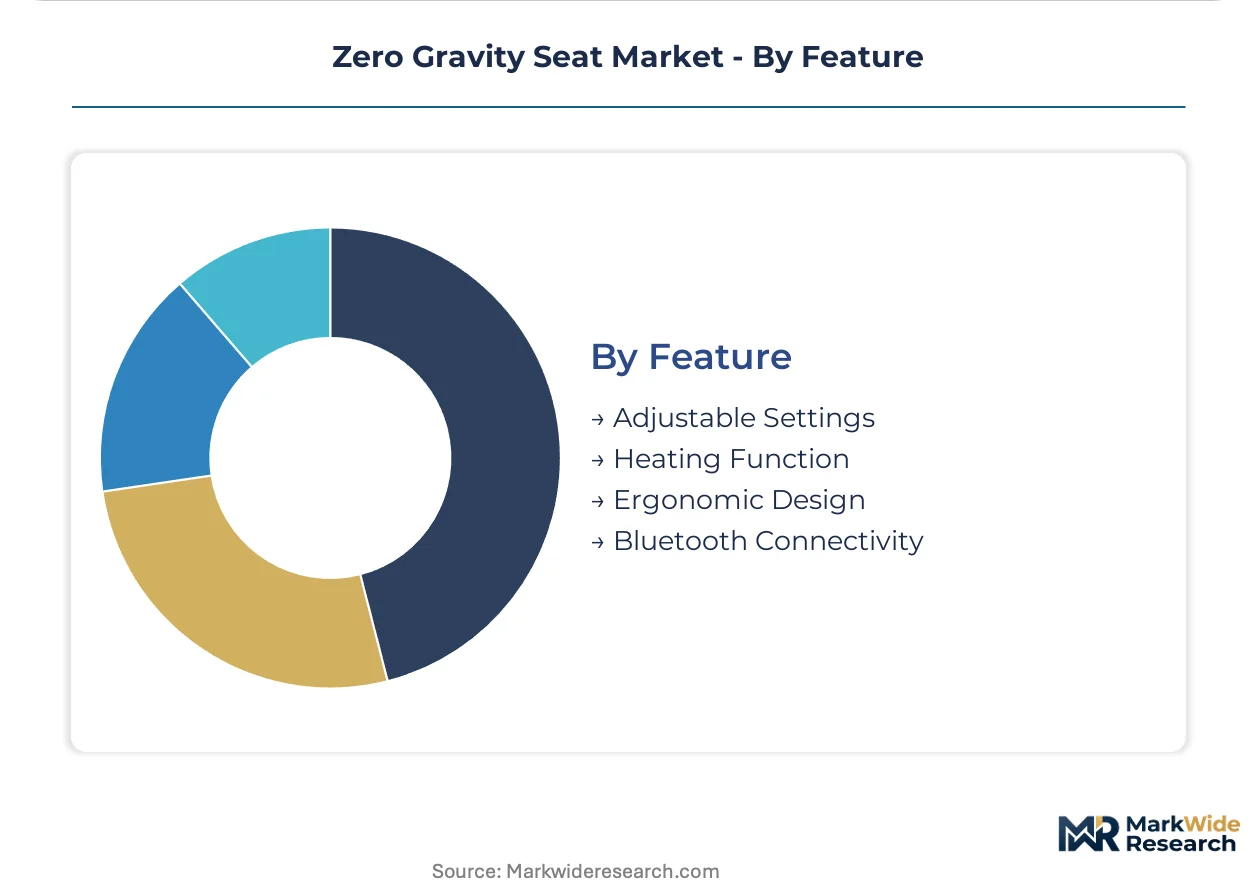
Feature:
Feature bundling intensity correlates inversely with institutional procurement rigor—healthcare and aviation buyers prioritize mechanism reliability over connectivity additions.
- Adjustable Settings:Precision electromechanical actuators with position memory enable 120-130 degree torso-thigh angles. German and Japanese tier-one suppliers dominate integration for flagship vehicle platforms.
- Heating Function:Carbon fiber or wire-element systems embedded in lumbar and seat pan regions extend therapeutic applications. Japanese massage chair manufacturers lead thermal module miniaturization.
- Ergonomic Design:Biomechanical research from Scandinavian occupational health institutes shapes corporate office specifications. Adjustable armrest span and seat depth accommodate workforce anthropometric diversity.
- Bluetooth Connectivity:Audio streaming and mobile app control integration differentiates consumer gaming and massage chair SKUs. Firmware update capabilities extend product lifecycles in retail channels.
Adjustable settings anchor institutional procurement; Bluetooth connectivity expands most quickly through gaming chair retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation cabin retrofits and premium automotive seating programs concentrate procurement among certified mechanism suppliers in the United States, Germany, and Japan. China's tier-one manufacturing clusters scale precision actuator production for export markets.
United States
FAA certification standards for seat crashworthiness accelerate replacement cycles in aging commercial fleets. NHTSA crashworthiness requirements govern automotive applications, creating dual compliance burdens for cross-sector suppliers. Detroit-area stamping facilities anchor frame production for North American OEM programs.
Germany
EU Machinery Directive CE marking obligations force production line upgrades for European market access. KBA type-approval processes for automotive seating extend homologation timelines for mechanism integrators. Stuttgart and Munich R&D centers specialize in electromechanical actuator development for flagship vehicle platforms.
Japan
METI ergonomic guidelines reshape procurement specifications for domestic healthcare facilities. JIS standards govern therapeutic seating requirements in patient recovery rooms. Toyota City and Nagoya production bases sustain long-term supply agreements for Lexus and Toyota flagship models.
China
GB standards and MIIT industrial policy guide precision actuator scaling in tier-one manufacturing clusters. SAMR market access rules constrain uncertified furniture manufacturers from automotive supply chains. Shanghai and Guangzhou export hubs concentrate massage and gaming chair production for international retail channels.
South Korea
MFDS medical device classifications extend to therapeutic seating in healthcare procurement. Seoul Capital Area electronics suppliers integrate position sensors with brushless DC motor arrays. Busan-Ulsan automotive clusters feed component supply into German and Japanese tier-one seating programs.
Zero Gravity Seat Market Competitive Landscape
Player mix skews toward vertically integrated automotive suppliers and specialized mechanism fabricators serving distinct certification tracks. Consolidation pressure intensifies around ISO 26262 functional safety validation, separating qualified automotive seat suppliers from uncertified furniture manufacturers. Strategic archetypes include frame-and-mechanism integrators, electromechanical actuator specialists, and regional healthcare seating providers. Dominant competitive moves encompass backward integration into precision stamping capacity and geographic expansion through dedicated R&D centers in China and Europe.
Within the automotive-tier supplier group, Lear Corporation and Faurecia exemplify vertically integrated positioning through captive frame stamping and mechanism assembly operations. Toyota Boshoku anchors the Japanese domestic market archetype through concentrated supply relationships with flagship vehicle programs. These three companies represent the certification-bifurcated structure where functional safety qualification determines market access rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Lear Corporation |
| Faurecia |
| Magna International |
| Yanfeng Adient |
| Tachi-S |
| Guanghua Rongchang |
| Tiancheng Controls |
| Hongli Zhixin |
| Toyota Boshoku |
| Others |
Pricing and Supply Chain Analysis
Ninety-day actuator inventory cycles in Chinese tier-one clusters concentrate pricing power among frame-stamping specialists serving automotive OEM programs. This lead-time band tightens when FAA certification backlogs extend aviation procurement timelines, forcing dual-track suppliers to prioritize premium-tier contracts.
Pricing Analysis
Cost-plus contracts with steel indexation dominate long-term automotive supply agreements. Price differentiation hinges on ISO 26262 certification tier and after-sales service bundling intensity. Margins are tightening in consumer massage chair segments as Bluetooth module commoditization accelerates. Retail gaming chair buyers exhibit highest price sensitivity; aviation retrofit programs show least.
Supply Chain Analysis
Inventory cycles stretching to ninety days reflect electromechanical actuator concentration in China, Germany, and Japan. High-grade steel for frame stamping, precision motors from South Korea, and Italian full-grain leather feed production. Single-source vulnerability concentrates in Chinese precision actuator foundries. Distribution runs through tier-one automotive seating integrators and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification fragmentation across automotive, aviation, and healthcare segments creates structurally defensible niches for specialized suppliers. The divergence between ISO 26262 functional safety mandates and consumer furniture liability frameworks multiplies addressable entry points.
For Market Incumbents: Fortify certification moats by accelerating backward integration into precision stamping capacity in Detroit-area and Stuttgart production bases. Uncertified furniture manufacturers from Chinese export hubs pose substitution threats in retail channels; counter through exclusive long-term supply agreements with Toyota and Lexus flagship programs.
For New Entrants and Emerging Players: Differentiate on METI-compliant therapeutic configurations for Japanese healthcare facilities, where procurement unbundling creates modular actuator replacement opportunities. Gaming chair retail expansion through direct-to-consumer e-commerce represents the most penetrable white-space; lead with RGB-integrated ergonomic designs for extended session use.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because functional safety validation timelines extend competitive protection for qualified automotive suppliers. Target vertically integrated mechanism fabricators with captive R&D centers in France and China. Monitor NHTSA FMVSS 302 flammability protocol tightening as inflection signal for upholstery testing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Functional safety validation separates qualified automotive suppliers from furniture manufacturers in procurement decisions. |
| Electromechanical Actuator Integration | Brushless DC motor arrays with position sensors enable compact cabin architectures for flagship vehicle platforms. |
| Backward Integration into Frame Stamping | Captive steel forming capacity insulates margin pressure from raw material volatility in Chinese tier-one clusters. |
| Aviation Retrofit Program Capture | FAA crashworthiness certification requirements accelerate replacement cycles in aging United States commercial fleets. |
| Mesh Material Technology Transfer | Breathable suspension knit from corporate office seating reduces weight in German OEM summer comfort packages. |
Research Methodology
The analysis maps automotive seating programs, aviation cabin retrofits, healthcare therapeutic configurations, and consumer furniture segments, each validated through procurement managers at hospital systems, fleet buyers at commercial airlines, platform engineers at German OEMs, and category directors at e-commerce retailers. Primary fieldwork combined with regulatory filings from FAA, NHTSA, METI, and EU Machinery Directive databases, customs trade records, and SEC supplier disclosures enabled bottom-up and top-down triangulation.
Consistency checks against vehicle production databases and aviation fleet age registries validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user procurement sophistication, material cost tier, and feature bundling intensity. CAGRs derived from mechanism shipment volumes, content-per-vehicle trajectories, and retrofit cycle frequencies.
The analysis sits within stated boundaries; outcomes outside sustained aviation travel recovery or automotive production stability would require recalibration. Forecasts reflect documented assumptions regarding certification timeline standardization and actuator cost curves. Raw material concentration in Chinese manufacturing clusters and regulatory divergence between sectors constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market