
 Rail Freight Slot and Path Optimization Platforms Market | 2026-2036
Rail Freight Slot and Path Optimization Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Freight Slot and Path Optimization Platforms Market Insights
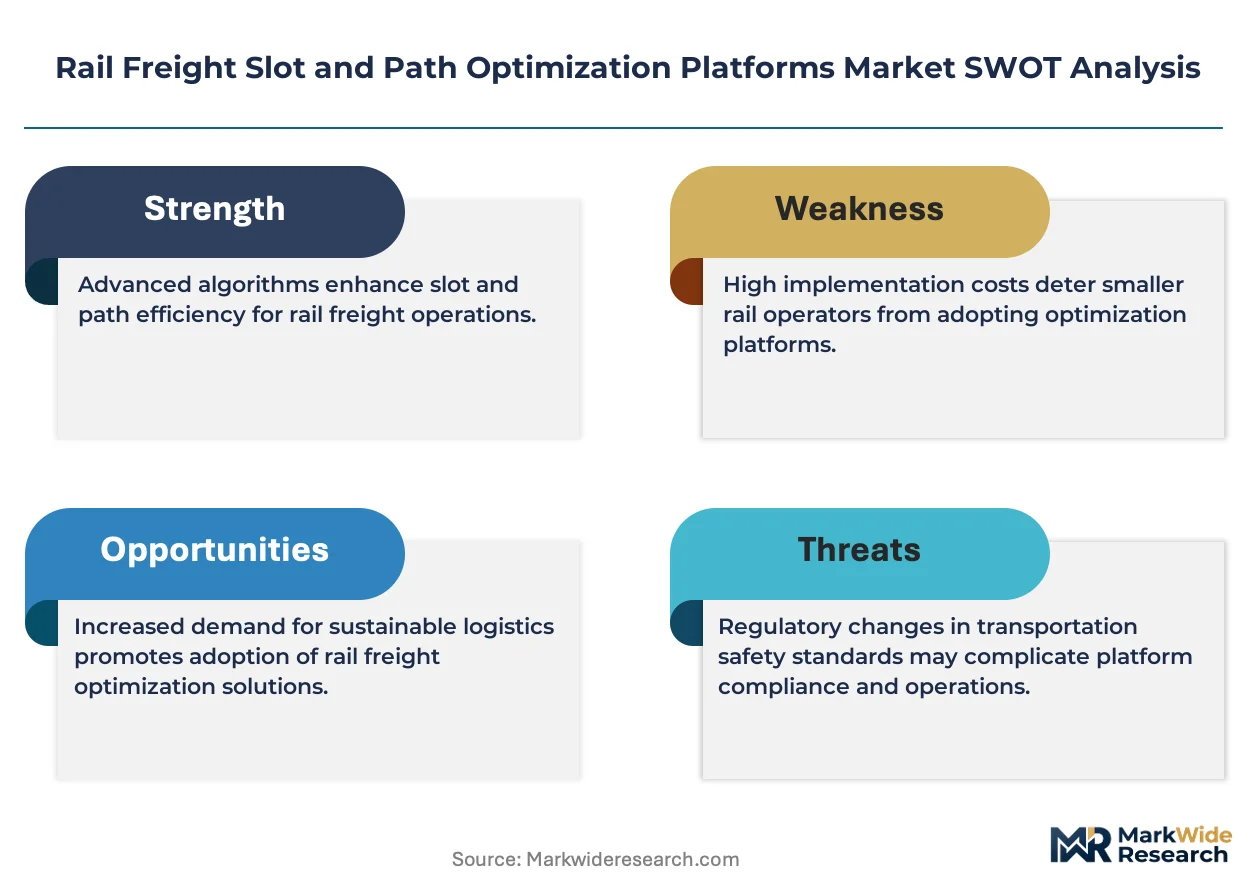
The divergence between premium cloud-native platforms and legacy on-premise systems is shifting procurement criteria across European rail networks. Deutsche Bahn leverages its captive infrastructure data to anchor proprietary optimization layers. SNCF Réseau competes through heuristic algorithm specialization on trans-Alpine corridors. RailNetEurope extends interoperability standards that allow smaller freight carriers to access centralized path allocation.
Rail freight slot and path optimization platforms are software systems that apply machine learning models and combinatorial optimization engines to allocate train paths across shared infrastructure, typically processing capacity constraints, priority hierarchies, and real-time disruption signals within sub-second computational windows to maximize network throughput. Their primary commercial purpose is reducing dwell times and conflicts in saturated corridors where manual scheduling creates cascading delays. Cloud-based solutions now capture the fastest-expanding deployment segment as infrastructure managers seek elastic compute for seasonal volume spikes. Optimization engines built on hybrid heuristic-mathematical frameworks command the deepest margin pools where latency requirements preclude pure SaaS architectures. On-premise systems retain dominance in countries with stringent data sovereignty mandates.
EU Green Deal targets and the F-Gas Regulation are compressing allowable emissions intensities for diesel-hauled freight, creating direct demand for path optimization that electrifies corridor utilization. ECHA chemical transport rules and national safety frameworks in Germany and France mandate granular cargo tracking, which slot platforms integrate as standard data layers. Stakeholders must weigh whether to build captive algorithm stacks or absorb vendor roadmaps as cloud providers deepen rail-specific module development.
Market Dynamics
Algorithmic scheduling engines are displacing manual dispatch protocols across European rail corridors, compressing path allocation cycles from hours to seconds while forcing infrastructure managers to re-architect data governance frameworks.
Growth Catalysts
- EU Green Deal emission benchmarks:Tightening carbon intensity mandates for freight logistics are electrifying corridor demand and requiring algorithmic load balancing to maximize electrified track utilization.
- Combinatorial optimization engines:Hybrid heuristic-mathematical frameworks now process real-time disruption signals within sub-second windows, eliminating cascading delay propagation in saturated networks.
- Central and Eastern Europe corridor congestion:Freight carriers across Poland, Czechia, and Slovakia are accelerating platform procurement to resolve path allocation bottlenecks on east-west freight corridors.
Market Restraints
- Data sovereignty mandates:National security frameworks in Germany and France require on-premise deployment, blocking cloud-native elasticity and inflating total cost of ownership by infrastructure lock-in.
- Legacy system integration friction:Decades-old train control systems lack API standardization, forcing expensive middleware layers that delay optimization engine deployment by 18-24 months.
- Specialized talent scarcity:Rail operations research expertise concentrates in academic institutions and incumbent operators, constraining vendor scaling and implementation velocity.
Strategic Opportunities
- RailNetEurope interoperability standards:Centralized path allocation protocols are opening corridor access for smaller freight carriers previously excluded from infrastructure bidding.
- ECHA chemical transport tracking mandates:Granular cargo visibility requirements are creating integrated data layers that slot platforms can monetize as compliance-as-a-service modules.
- Edge computing convergence with 5G rail networks:Low-latency trackside infrastructure is enabling distributed optimization nodes that reduce dependency on centralized cloud architectures.
Industry Challenges
- ISO 55000 asset management certification timelines:Infrastructure managers face 12-18 month compliance windows to align path allocation algorithms with international infrastructure integrity standards.
- Multi-stakeholder governance complexity:Path allocation disputes between passenger and freight operators require arbitration protocols that optimization engines must embed as configurable rule sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Freight Slot and Path Optimization Platforms Market |
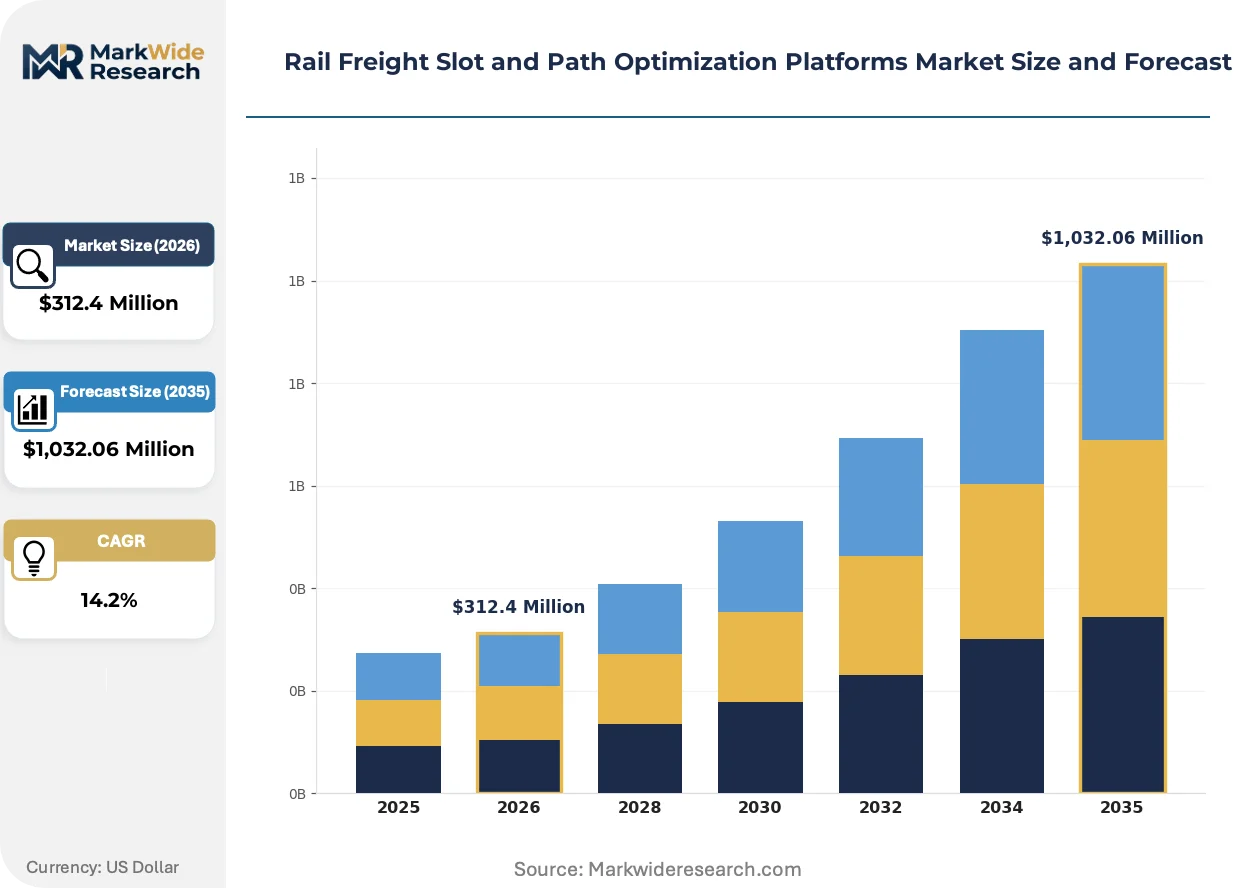
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,032.06 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based Solutions, On-Premise Systems, Hybrid Platforms, SaaS Offerings Technology: Machine Learning, Heuristic Algorithms, Simulation Models, Optimization Engines Application: Slot Allocation, Path Scheduling, Capacity Planning, Traffic Management End User: Rail Operators, Freight Carriers, Logistics Providers, Infrastructure Managers |
| Companies Covered | DB InfraGO, SNCF Réseau, RFI, ProRail, Network Rail, Banedanmark, OEBB Infrastruktur, Deutsche Bahn, RailNetEurope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Freight Slot and Path Optimization Platforms Market Trends and Innovations
Machine learning inference at the network edge is redistributing computational architecture across European rail infrastructure, fragmenting the centralized cloud model that dominated early platform generations.
Hybrid heuristic-mathematical optimization frameworks are absorbing latency-sensitive path allocation decisions previously reserved for human dispatchers. Infrastructure managers in Germany and Austria are deploying these engines on trackside edge nodes to process real-time disruption signals without round-trip cloud latency. The technology is absorbing margin pools from pure SaaS architectures where sub-second response requirements preclude centralized processing.
The EU F-Gas Regulation is compressing allowable emissions intensities for diesel-hauled freight corridors, mandating algorithmic scheduling that maximizes electrified path utilization. Infrastructure managers must now weight carbon intensity as a primary optimization variable alongside traditional throughput metrics. German operators are responding by integrating real-time grid carbon data into path allocation engines, prioritizing slots on electrified corridors during low-carbon intensity periods.
Freight carriers are consolidating procurement around outcome-based performance contracts that tie vendor compensation to measurable dwell time reductions and conflict resolution rates. Traditional software licensing models are yielding to gain-sharing arrangements where optimization vendors participate in operational savings. This shift is most visible in trans-Alpine corridors where Swiss and Italian operators have pioneered contractual frameworks linking platform fees to network throughput improvements.
Rail Freight Slot and Path Optimization Platforms Market Segmentation
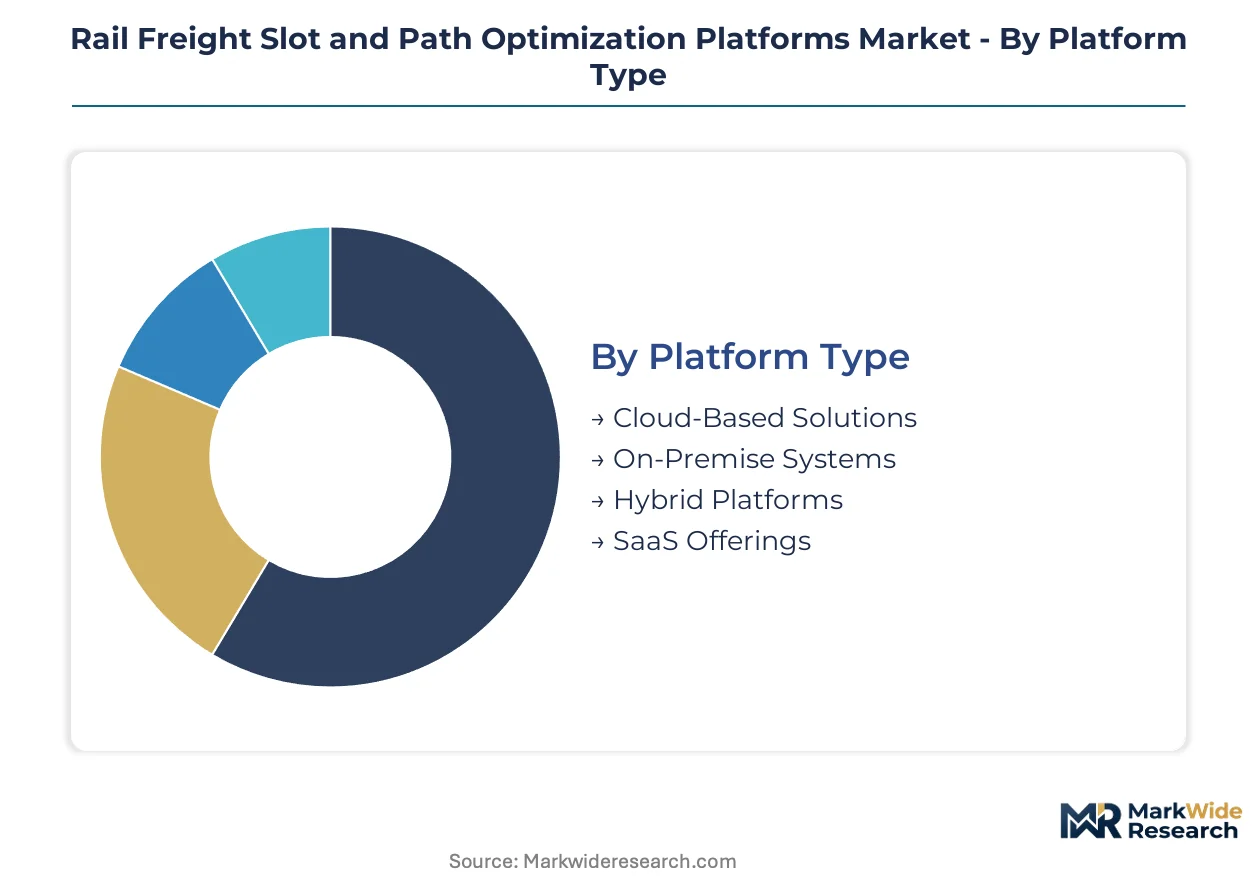
Segmentation in rail freight slot and path optimization platforms reveals where computational architecture decisions lock in competitive position. Platform type determines data governance flexibility, while technology choice dictates latency tolerance and disruption response speed.
Platform Type:
Integration depth varies sharply across deployment architectures, with standalone cloud stacks offering elastic scaling and embedded on-premise systems enforcing sovereign data boundaries.
- Cloud-Based Solutions:Elastic compute architectures process seasonal volume spikes through distributed infrastructure. Deutsche Bahn and SNCF Réseau pilot these systems for trans-Alpine corridors where demand fluctuates with agricultural export cycles.
- On-Premise Systems:Captive server installations satisfy Germany's data sovereignty mandates under national security frameworks. KBA certification requirements and BSI IT-Grundschutz standards compel infrastructure managers to absorb higher capital intensity for compliance certainty.
- Hybrid Platforms:Split architectures retain sensitive dispatch data locally while pushing non-critical analytics to cloud nodes.
- SaaS Offerings:Subscription models lower entry barriers for Polish and Czech freight carriers with limited capital budgets.
On-Premise Systems lead volumes today; Cloud-Based Solutions are gaining share fastest.
Technology:
Cost tier stratification separates algorithmic approaches, with premium optimization engines commanding implementation budgets fivefold above heuristic alternatives.
- Machine Learning:Neural network architectures trained on historical disruption patterns predict conflict propagation before human dispatchers detect anomalies. Austrian Federal Railways deploys these models on edge nodes along the Brenner corridor.
- Heuristic Algorithms:Rule-based systems prioritize computational speed over theoretical optimality. SNCF Réseau specializes these frameworks for Alpine path allocation where sub-second decisions prevent cascading delays.
- Simulation Models:Digital twin environments test schedule modifications without operational risk.
- Optimization Engines:Hybrid mathematical frameworks combine integer programming with metaheuristics for corridor saturation management.
Heuristic Algorithms anchor current procurement; Machine Learning shows steepest expansion trajectory.
Application:
Customer type concentration shapes functional requirements, with infrastructure managers demanding network-wide visibility that freight carriers sacrifice for operational simplicity.
- Slot Allocation:Real-time bidding mechanisms assign train paths through combinatorial auctions. RailNetEurope's centralized platform enables smaller carriers to access capacity previously captured by incumbents.
- Path Scheduling:Temporal sequencing engines resolve conflicts between passenger and freight priority hierarchies. DB InfraGO embeds these systems directly into Germany's densest freight network operations.
- Capacity Planning:Long-horizon forecasting tools align infrastructure investment with projected demand curves.
- Traffic Management:Real-time flow control responds to disruption signals from track sensors and weather stations.
Path Scheduling dominates current deployments; Slot Allocation is climbing the fastest.
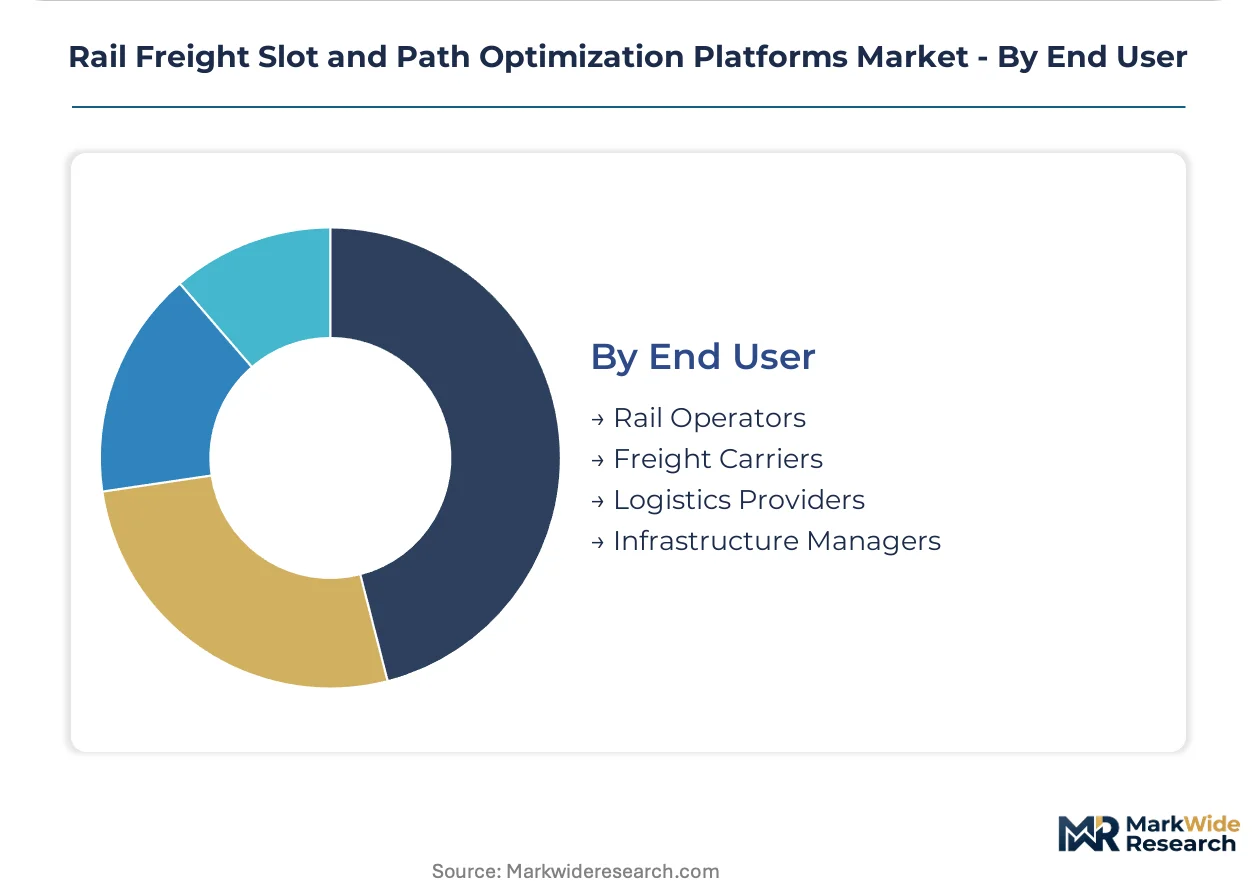
End User:
Maturity gradients separate adoption phases, with state-owned infrastructure managers leading algorithmic deployment and private logistics providers trailing by three to five years.
- Rail Operators:Integrated path-to-train control systems synchronize scheduling with rolling stock positioning. ÖBB and SBB combine these platforms with automated train operation pilots.
- Freight Carriers:Commercial optimization focuses on cost-per-ton-kilometer reduction through dwell time compression. Polish carriers PKP Cargo and CTL Logistics prioritize these metrics on east-west corridors.
- Logistics Providers:Multi-modal orchestrators demand API bridges to slot platforms for seamless truck-rail handoffs.
- Infrastructure Managers:Network stewards balance competing operator claims through configurable arbitration rule sets.
Rail Operators lead volumes today; Logistics Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's infrastructure density contrasts with Poland's corridor expansion urgency, yet both drive algorithmic scheduling procurement across European rail networks.
Germany
DB InfraGO and Deutsche Bahn operate Europe's densest freight network, creating captive demand for proprietary optimization layers. KBA certification requirements and BSI IT-Grundschutz standards enforce on-premise deployment for data sovereignty compliance. The Rhine-Alpine corridor through North Rhine-Westphalia anchors continental freight routing algorithms.
France
SNCF Réseau specializes heuristic frameworks for trans-Alpine corridors where sub-second dispatch decisions prevent cascading delays. ANSM and CNIL data governance rules shape platform architecture choices for cross-border operations. The Lyon-Turin freight axis exemplifies priority arbitration between passenger and freight hierarchies.
Poland
PKP Cargo and CTL Logistics accelerate platform procurement to resolve east-west corridor congestion at Polish-German border nodes. EU Green Deal emission benchmarks compress allowable diesel intensities, electrifying algorithmic load balancing demand. The Silesian freight cluster concentrates path allocation bottlenecks requiring real-time disruption response.
Switzerland
SBB and BLS navigate Alpine tunnel saturation through outcome-based performance contracts tying vendor fees to dwell time reductions. Swissmedic-equivalent rail safety frameworks mandate granular cargo tracking integration. The Gotthard Base Tunnel corridor pioneers gain-sharing arrangements between infrastructure managers and optimization vendors.
Italy
RFI manages Brenner corridor capacity conflicts between Austrian and Italian freight flows through simulation-model arbitration. ECHA chemical transport rules require integrated cargo visibility layers within slot platforms. The Verona Quadrante Europa terminal cluster anchors multimodal optimization for Mediterranean-continental freight interchange.
Rail Freight Slot and Path Optimization Platforms Market Competitive Landscape
Top-tier vendors anchor state-owned infrastructure manager relationships, while mid-tier specialists compete through heuristic algorithm specialization on saturated corridors. The market structures around three archetypes: captive algorithm stacks built by incumbent rail operators, cloud-native platform vendors serving smaller freight carriers, and hybrid heuristic-mathematical engine providers commanding premium implementation budgets. Dominant competitive moves include strategic partnerships between infrastructure managers and technology vendors, plus geographic expansion into Central and Eastern European corridor markets.
Among state-owned infrastructure specialists, DB InfraGO and SNCF Réseau exemplify the captive-stack archetype, integrating proprietary optimization layers directly into national network operations. RailNetEurope occupies a distinct interoperability position, extending centralized path allocation standards that enable smaller freight carriers to access capacity bidding systems previously captured by incumbents.
| Leading Market Players |
|---|
| DB InfraGO |
| SNCF Réseau |
| RFI |
| ProRail |
| Network Rail |
| Banedanmark |
| OEBB Infrastruktur |
| Deutsche Bahn |
| RailNetEurope |
| Others |
Pricing and Supply Chain Analysis
Cloud-native elasticity premiums diverge sharply from on-premise compliance premiums, with the former commanding subscription multiples tied to seasonal compute spikes and the latter absorbing sovereign-data certification costs that inflate capital intensity by infrastructure lock-in. This bifurcation concentrates vendor margin pools in hybrid architectures that split sensitive dispatch data from non-critical analytics, while procurement patterns in Germany and France tilt toward captive server installations under KBA and BSI IT-Grundschutz mandates.
Pricing Analysis
Capacity additions in Central and Eastern Europe are reshaping price floors for SaaS offerings as Polish and Czech freight carriers accelerate platform procurement. Three-tier pricing structure across premium optimization engines, standard heuristic frameworks, and economy simulation models dominates vendor catalogs, with premium tiers anchored in hybrid heuristic-mathematical frameworks and economy tiers limited to rule-based dispatch tools. Price differentiation hinges on latency tolerance and certification grade, with sub-second response requirements commanding fivefold implementation budgets above heuristic alternatives. Pricing pressure stems from outcome-based performance contracts that tie vendor compensation to dwell time reductions, compressing traditional licensing margins. Freight carriers with limited capital budgets exhibit highest price sensitivity; state-owned infrastructure managers absorb premium tiers for compliance certainty.
Supply Chain Analysis
ISO 55000 asset management certification and BSI IT-Grundschutz compliance gating concentrate software development and systems integration capacity in Germany, Austria, and Switzerland, with edge computing hardware sourcing extending to Taiwan and South Korea for low-latency trackside nodes. Algorithm development draws from academic operations research pipelines in German and French technical universities, while cloud infrastructure rests on hyperscaler data centers in Ireland, the Netherlands, and Frankfurt. Single-source vulnerability in specialized rail operations research talent constrains vendor scaling velocity. Distribution runs through direct infrastructure manager contracts for on-premise deployments and channel partnerships with regional systems integrators for SaaS offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rail freight slot and path optimization platforms rests on algorithmic efficiency gains that compress implementation timelines and outcome-based contracts that capture operational savings as recurring revenue streams.
For Market Incumbents: Acquire specialized heuristic algorithm teams from Alpine corridor specialists to anchor trans-Alpine optimization dominance. Defensive consolidation must address cloud-native entrants threatening SaaS market share through elastic compute pricing. Prioritize backward integration into edge computing hardware to reduce hyperscaler dependency and lock in latency advantages for sub-second dispatch decisions.
For New Entrants and Emerging Players: API-first integration layers offer the most penetrable entry vector for mid-tier freight carriers seeking seamless truck-rail handoffs without legacy system replacement. White-space concentration sits in Polish and Czech east-west corridors where corridor congestion outpaces incumbent platform deployment capacity. Target logistics providers trailing state-owned rail operators by three to five years in algorithmic adoption, offering subscription models that bypass capital budget constraints.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized rail operations research expertise concentrates in academic institutions and incumbent operators, constraining vendor scaling. Long-term viability favors hybrid architecture providers that bridge sovereign-data mandates with cloud elasticity. Acquisition target archetype: mid-tier heuristic specialists with proven Alpine corridor deployments and RailNetEurope interoperability certification. Signal to watch: EU Green Deal emission benchmark tightening that accelerates electrified path utilization demand and expands addressable market for carbon-integrated optimization engines.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Deployment | Trackside nodes in Germany and Austria process disruption signals without cloud round-trip latency. |
| Outcome-Based Performance Contracting | Swiss and Italian operators pioneered gain-sharing frameworks linking vendor fees to throughput improvements. |
| RailNetEurope Interoperability Certification | Centralized path allocation standards open corridor access for smaller freight carriers previously excluded. |
| Carbon-Integrated Optimization Engine Development | Real-time grid carbon data prioritizes electrified corridor slots during low-intensity periods. |
| Heuristic Algorithm Specialization Acquisition | Alpine corridor expertise anchors trans-Alpine dispatch decisions preventing cascading delays. |
Research Methodology
Coverage spans Germany, France, Poland, Switzerland, and Italy, with primary inputs from each market's infrastructure managers and freight operators. The research combines structured interviews with DB InfraGO dispatch directors, SNCF Réseau corridor planners, PKP Cargo operations heads, SBB asset managers, and RFI traffic control specialists with secondary validation from EU Green Deal implementation reports, RailNetEurope path allocation databases, ECHA chemical transport filings, and national rail safety authority certifications. Bottom-up triangulation aggregates carrier-level platform procurement data while top-down validation cross-checks against infrastructure manager capex disclosures and vendor implementation announcements.
Granularity-level modeling segments the market by platform type, technology approach, application function, and end-user archetype, with additional dimensioning by deployment latency requirement and carbon-integration capability across the projection horizon. CAGRs derive from algorithmic adoption curve analysis and corridor congestion elasticity estimates, incorporating EU F-Gas Regulation compliance timelines and electrified track expansion forecasts as rail-specific inputs.
Regulatory enforcement delays, legacy system integration friction, and specialized talent scarcity are the dominant revision risks that could compress or extend adoption trajectories. Forecasts reflect assumptions on interoperability standard adoption rates and cloud sovereignty framework evolution. A model refresh is warranted upon material change in EU Green Deal emission benchmark implementation schedules or RailNetEurope centralized allocation protocol deployment velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Automatic Train Operation System Market
Railway
India Rail Freight Transport Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Railcar Vehicle Toilet Market
Railway
Rail Transit Traction Converter Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Gangway for Railway Vehicles Market
Railway
Rail Brake Frame Market
Railway
Railway Braking System Market
Railway
Train Suspension System Market
Railway
Latin America Connected Rail Market
Railway
France Connected Rail Market
Railway
Check Rails Market
Railway
Train HVAC Market
Railway
Locomotive Doors Market
Railway
Rail Maintenance Management System Market