
 Locomotive Parking Brake Market | 2026-2036
Locomotive Parking Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Parking Brake Market Analytics
Freight rail operator demand for reliable yard and terminal braking is hardening as intermodal volumes expand across North American corridors. Wabtec Corporation leverages its integrated brake platform to capture retrofit cycles on legacy locomotive fleets. Knorr-Bremse AG anchors European supply through specialized pneumatic parking brake modules designed for high-axle-load freight configurations. CRRC Corporation Limited dominates procurement pipelines within China's state-directed rail renewal programs.
A locomotive parking brake is a mechanically or pneumatically actuated holding device that secures stationary rail vehicles against unintended movement on graded track, typically generating clamping forces exceeding 50 kN per axle through spring-applied or air-released mechanisms. The system serves as the final safety layer during crew changes, fueling stops, and overnight staging in classification yards. Disc brake configurations now lead new installations owing to superior thermal dissipation and reduced maintenance intervals compared with drum alternatives. Electromechanical technology represents the fastest-expanding segment as rail operators pursue brake-by-wire architectures that eliminate pneumatic line complexity. Aftermarket providers capture substantial margin pools through certified rebuild programs for brake calipers and actuator cylinders.
The Federal Railroad Administration enforces minimum parking brake holding force standards under 49 CFR Part 232, while the European Union Agency for Railways mandates interoperability compliance through the CCS TSI specification for braking performance. China's National Railway Administration imposes GB/T standards that align brake component testing with domestic high-altitude and temperature extremes. Stakeholders must monitor evolving cybersecurity requirements for electromechanical brake controllers and assess supplier readiness for dual-carbon compliance in steel and friction material sourcing.
Market Dynamics
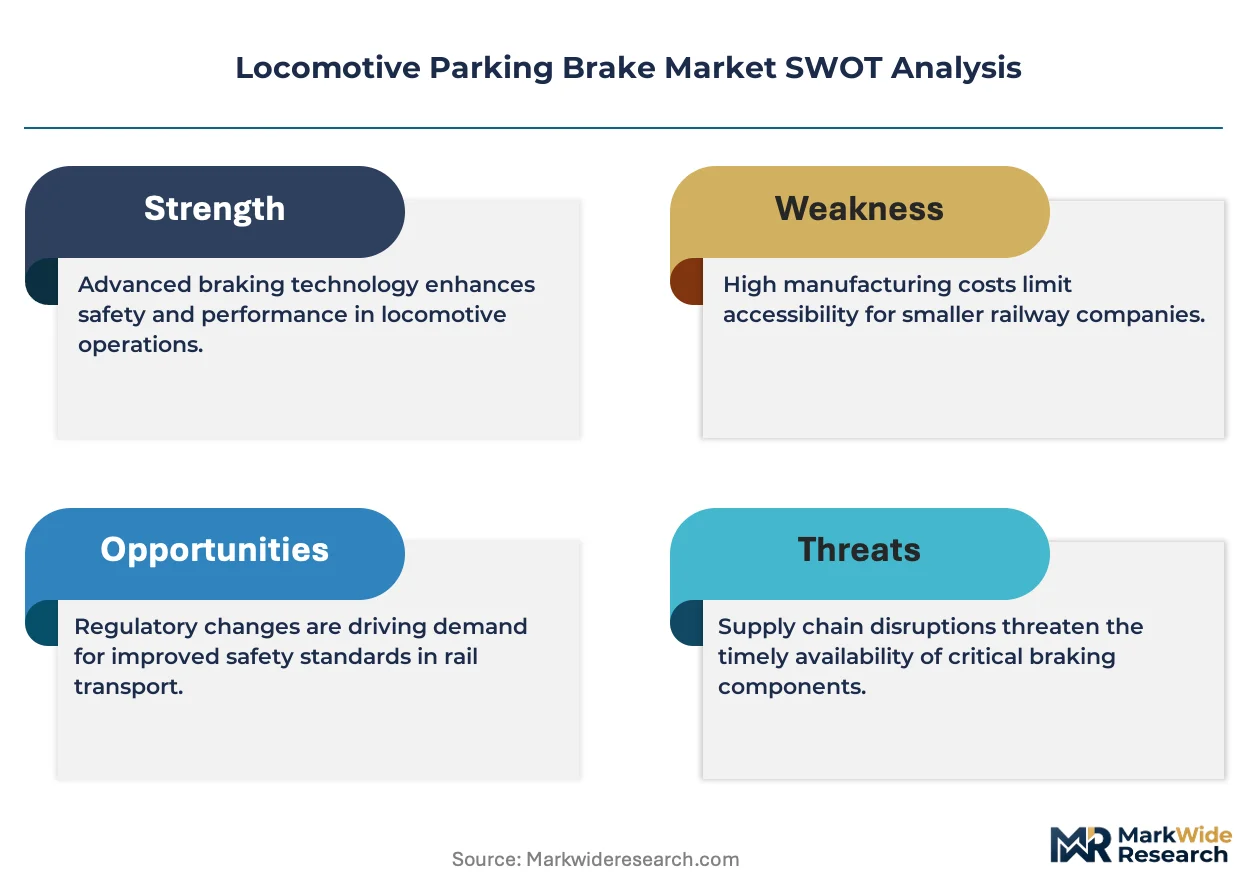
The locomotive parking brake sector is undergoing a fundamental transition as electromechanical brake-by-wire architectures displace legacy pneumatic systems across freight and passenger rail fleets. This technology shift compresses supplier margins on traditional pneumatic components while creating premium positioning for integrated electronic control platforms.
Growth Catalysts
- Federal Railroad Administration mandates:49 CFR Part 232 holding-force standards compel North American freight operators to upgrade aging brake systems during scheduled overhaul cycles.
- Intermodal freight expansion:Classification yards in the United States face heightened braking duty cycles as container volumes surge through Chicago, Los Angeles, and Savannah gateway corridors.
- Spring-applied air-release mechanisms:These pneumatic designs deliver fail-safe operation that satisfies insurer risk assessments for unattended consist staging.
Market Restraints
- Specialized friction material costs:Ceramic-composite brake pads face price volatility from rare earth mineral supply concentration in China.
- Electromechanical actuator supplier concentration:Precision motor and sensor sourcing clusters in Germany and Japan create single-source vulnerability for brake-by-wire integrators.
- Technical interoperability limits:Legacy pneumatic lines on pre-2000 locomotive fleets resist seamless electromechanical retrofit without extensive structural modification.
Strategic Opportunities
- Indian freight corridor modernization:Dedicated freight corridors between Delhi and Mumbai present untapped demand for high-axle-load parking brake configurations.
- EU Green Deal alignment:Carbon-border adjustments on steel friction materials incentivize domestic European sourcing and remanufacturing hub development.
- Condition-based maintenance convergence:Integration of IoT sensors with electromechanical actuators enables predictive brake wear monitoring that reduces yard downtime.
Industry Challenges
- Mechatronics engineering scarcity:Rail brake suppliers compete with automotive and aerospace sectors for embedded systems firmware developers capable of SIL-rated safety coding.
- Multi-standard certification timelines:Simultaneous FRA, EU Agency for Railways, and GB/T compliance testing extends product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Parking Brake Market |
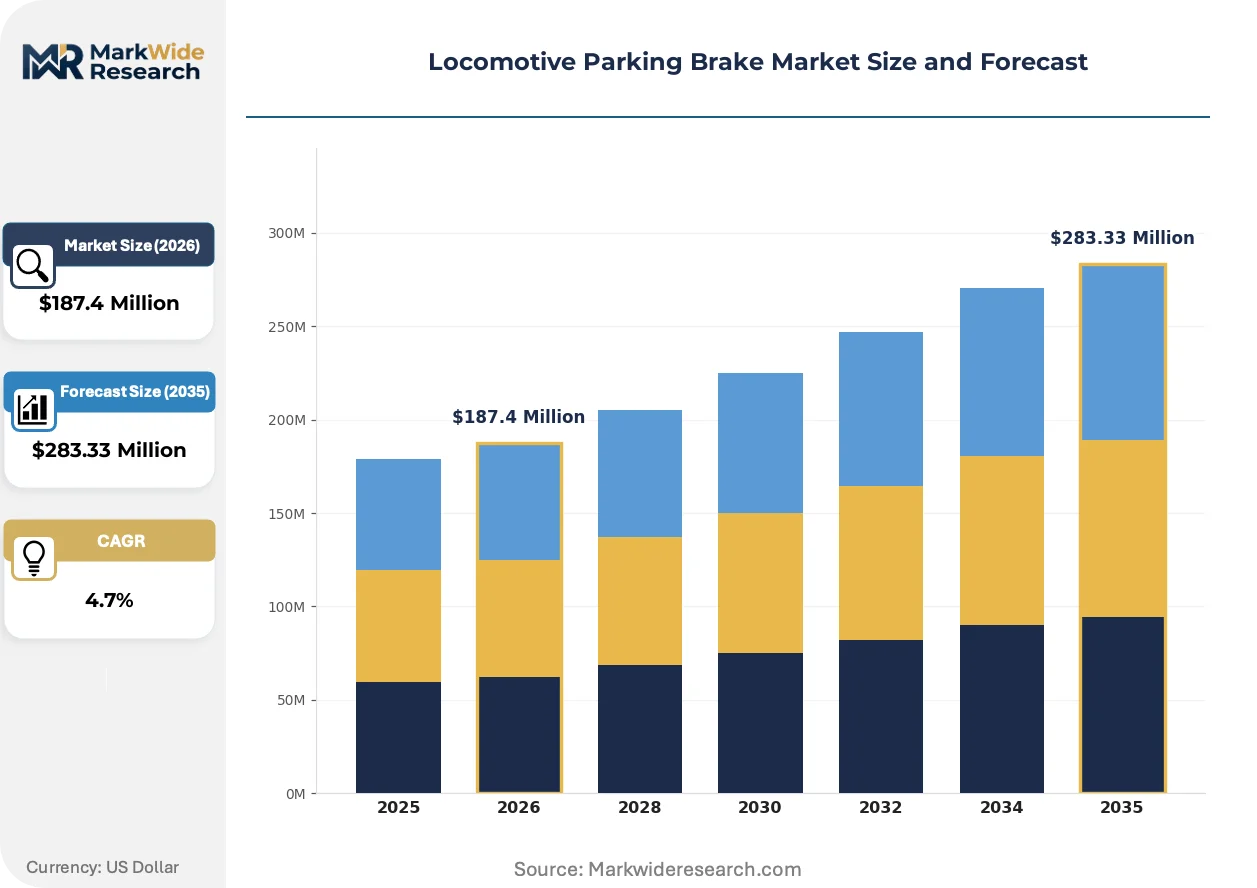
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Brake Type: Disc Brakes, Drum Brakes, Electromagnetic Brakes, Hydraulic Brakes Technology: Pneumatic, Mechanical, Electro-Pneumatic, Electromechanical End User: Rail Operators, Maintenance Facilities, OEMs, Aftermarket Providers Installation Type: New Installation, Retrofitting, Service Replacement, Maintenance |
| Companies Covered | Knorr-Bremse AG, Wabtec Corporation, Faiveley Transport, CRRC Corporation Limited, Hitachi Rail, Alstom SA, DAKO-CZ, Bosch Rexroth, Faiveley Transport Wabtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Parking Brake Market Evolving Landscape
Brake system architecture is pivoting toward integrated electronic control platforms that merge parking, dynamic, and emergency functions into unified mechatronic modules. This convergence eliminates redundant pneumatic infrastructure while enabling software-defined braking profiles.
Electromechanical parking brake actuators are consolidating market share among premium freight operators seeking reduced maintenance intervals. Union Pacific and BNSF Railway have accelerated adoption timelines for brake-by-wire retrofits on Tier 4 locomotive deliveries. The technology is consolidating supplier tiers as pneumatic component specialists lose access to new-build procurement pipelines without electronic control partnerships.
The European Union Agency for Railways has tightened CCS TSI interoperability requirements for cross-border freight braking performance. Rail operators must now demonstrate certified holding force across alpine gradients exceeding five percent. German and Swiss freight corridors face the steepest compliance costs, driving demand for validated high-load parking brake modules with documented thermal cycling histories.
Freight rail procurement departments are unbundling aftermarket service contracts from initial brake system purchases. Large North American operators now source caliper rebuilds and actuator cylinder recertification through independent third-party providers rather than captive OEM service networks. This pattern is most visible in the United States, where deregulated maintenance practices allow competitive bidding on safety-critical component overhaul work.
Locomotive Parking Brake Market Segmentation
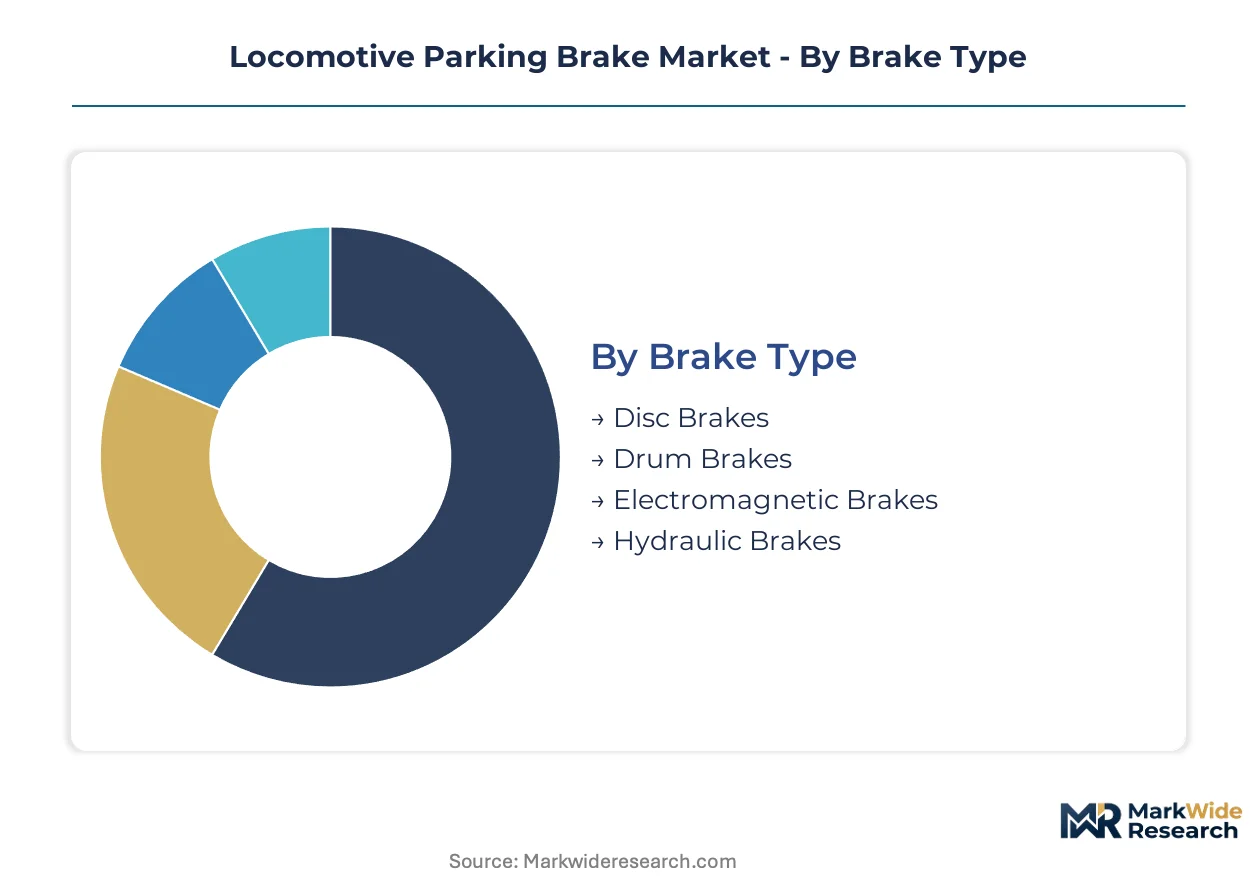
Brake system selection in rail procurement hinges on duty cycle intensity, regulatory compliance tier, and lifecycle cost modeling across freight corridors. Segment boundaries are blurring as electromechanical platforms subsume traditional pneumatic functions into unified control architectures.
Brake Type:
Fleet operators weigh thermal management capacity against retrofit compatibility when specifying brake configurations for high-axle-load freight duty.
- Disc Brakes:Cast-iron or composite rotors with caliper-mounted friction pads deliver superior heat dissipation for repeated yard braking cycles. Union Pacific and BNSF Railway specify disc configurations for new Tier 4 locomotive deliveries across Chicago and Los Angeles corridor operations where thermal fade resistance is non-negotiable.
- Drum Brakes:Internal expanding shoe mechanisms persist on legacy locomotive fleets built before 2005 due to structural mounting compatibility. Pre-2000 freight units in North American classification yards retain drum systems where frame modifications for disc retrofits prove economically prohibitive.
- Electromagnetic Brakes:Eddy-current retarders provide non-contact auxiliary braking for passenger rail applications requiring minimal maintenance intervals.
- Hydraulic Brakes:Fluid-actuated clamping systems serve specialized shunting locomotives in European terminal operations demanding precise modulation control.
Disc brakes lead on scale; electromagnetic brakes lead on momentum.
Technology:
Control architecture decisions cascade through wiring complexity, diagnostic capability, and supplier qualification requirements for safety-rated embedded systems.
- Electromechanical:Motor-driven screw actuators with integrated position sensing eliminate pneumatic infrastructure entirely. Brake-by-wire architectures are climbing the fastest among premium freight operators seeking software-defined holding force calibration and predictive wear algorithms.
- Pneumatic:Spring-applied air-release mechanisms dominate legacy fleet maintenance owing to established technician familiarity and parts availability. Yard operations across Germany's Ruhr freight corridors specify pneumatic systems for interoperability with existing consist air lines.
- Electro-Pneumatic:Hybrid designs blending electronic control with pneumatic actuation bridge retrofit scenarios where full electromechanical conversion exceeds structural modification budgets.
- Mechanical:Purely mechanical hand-brake linkages persist on isolated industrial spur lines and museum rail operations with minimal regulatory oversight.
Pneumatic technology leads on installed base; electromechanical leads on procurement pipeline growth.
End User:
Procurement authority fragmentation between capital expenditure and operating expenditure centers shapes vendor engagement strategies and contract structuring.
- Rail Operators:Class I freight railroads and national passenger services drive specification standards through fleet-wide platform decisions. CSX Transportation and Norfolk Southern Railway centralize brake system procurement under chief mechanical officer oversight with total-cost-of-ownership models spanning 30-year asset lifecycles.
- OEMs:Locomotive manufacturers including Wabtec and CRRC integrate parking brake modules into complete powertrain packages. Tier 4 emission-compliant locomotive production lines in the United States and China specify pre-validated brake-by-wire subsystems to compress commissioning timelines.
- Maintenance Facilities:Independent service depots capture rebuild and recertification work as operators unbundle aftermarket contracts from initial system purchases.
- Aftermarket Providers:Specialized rebuild shops compete on caliper overhaul turnaround time and friction material sourcing flexibility.
Rail operators lead on specification authority; aftermarket providers lead on margin expansion.
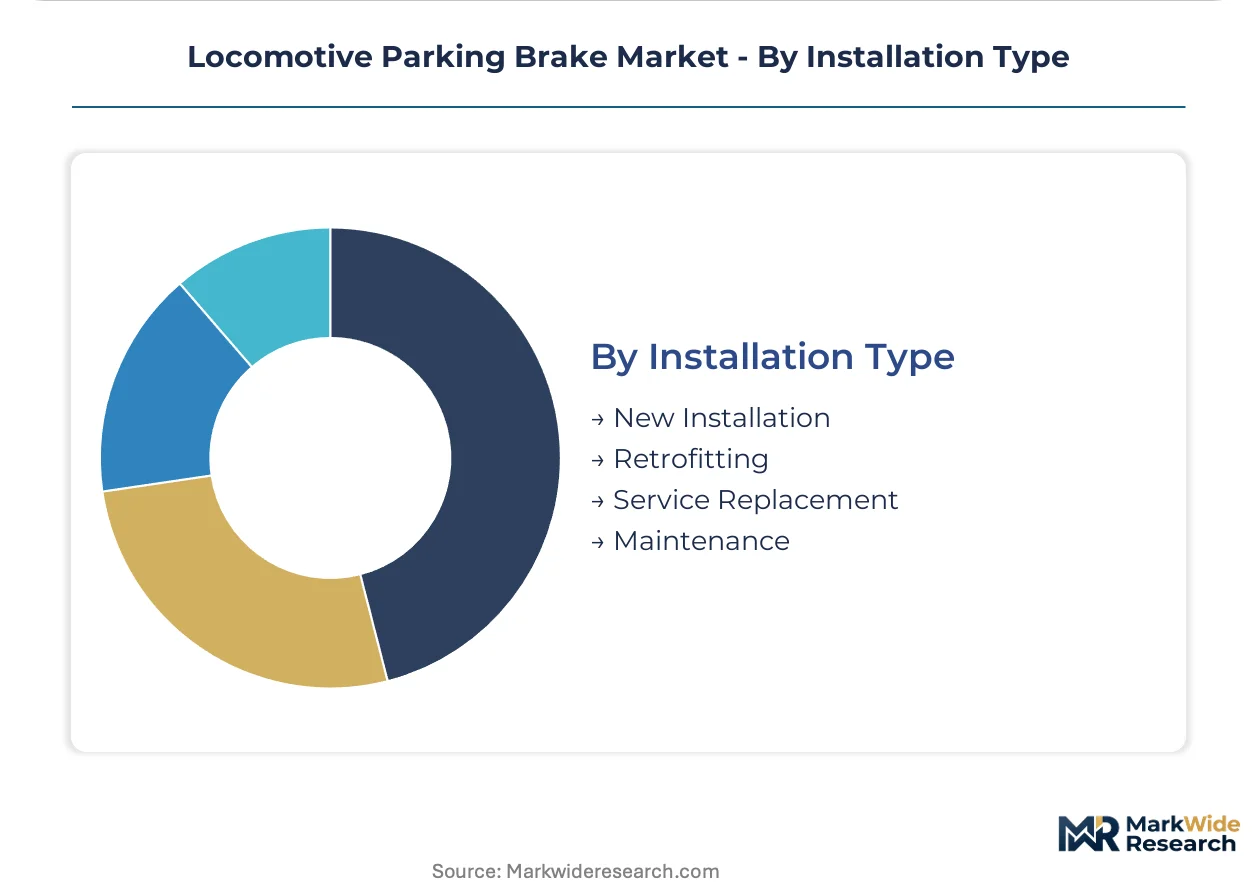
Installation Type:
Revenue timing and technical risk allocation differ materially between new-build integration and field retrofit execution.
- New Installation:Factory-integrated brake systems undergo comprehensive validation testing before revenue service entry. Greenfield locomotive assembly lines in China's state-directed rail programs specify electromechanical parking brakes as standard configuration.
- Retrofitting:Field conversion of pneumatic systems to electromechanical architectures demands structural frame analysis and wire harness routing. Union Pacific's Tier 4 retrofit program across western corridor locomotives exemplifies large-scale brake-by-wire migration.
- Service Replacement:Scheduled overhaul cycles trigger brake component exchange based on wear indicator thresholds and regulatory recertification intervals.
- Maintenance:Routine inspection and adjustment protocols preserve holding force compliance between major rebuild events.
New installation leads on revenue concentration; retrofitting leads on growth trajectory steepness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier location decisions as brake manufacturers migrate production toward jurisdictions with streamlined certification pathways and lower compliance overhead. Cost-of-compliance gaps between North American and Asian regulatory regimes now exceed fifteen percentage points in total landed cost for electromechanical actuator assemblies.
United States
Freight rail modernization cycles and Tier 4 locomotive procurement anchor demand. The Federal Railroad Administration enforces 49 CFR Part 232 holding-force standards that compel brake system upgrades during scheduled overhauls. Chicago and Los Angeles corridor classification yards concentrate retrofit activity as Union Pacific and BNSF Railway expand brake-by-wire deployments.
Germany
Alpine freight corridors and cross-border interoperability requirements drive specification complexity. The EU Agency for Railways mandates CCS TSI braking performance certification for gradients exceeding five percent. Ruhr freight corridors and Swiss border terminals concentrate demand for high-load pneumatic modules with documented thermal cycling histories.
China
State-directed rail renewal programs and high-altitude network expansion create procurement volume. The National Railway Administration imposes GB/T standards aligning brake testing with domestic temperature extremes and elevation profiles. CRRC production lines in Beijing and Shanghai specify electromechanical parking brakes as standard configuration for new-build locomotives.
India
Dedicated freight corridor construction between Delhi and Mumbai opens untapped demand for high-axle-load configurations. The Ministry of Railways accelerates procurement timelines under Make in India localization mandates. Gujarat and Maharashtra industrial corridors attract brake component fabrication as suppliers position for domestic content requirements.
Japan
Shinkansen network maintenance and freight efficiency programs sustain replacement demand. METI guidelines encourage predictive maintenance integration with electromechanical brake systems. Osaka and Nagoya manufacturing clusters supply precision actuator components to brake-by-wire integrators across Asia-Pacific procurement pipelines.
Locomotive Parking Brake Market Competitive Landscape
Technology licensing dominates the current landscape as pneumatic specialists seek electronic control partnerships to preserve access to new-build procurement pipelines. The vendor base stratifies across three tiers: integrated rail systems conglomerates with captive brake divisions, dedicated brake component specialists with certified rebuild capabilities, and emerging electromechanical actuator technology licensors. Two archetypes define competitive positioning: legacy pneumatic incumbents defending installed base through aftermarket service contracts, and brake-by-wire challengers capturing premium positioning through integrated electronic platforms. Strategic partnerships and portfolio diversification represent the dominant competitive vectors as suppliers bridge capability gaps through external technology access.
Among Germany-based diversified industrial groups, Knorr-Bremse AG exemplifies the dedicated brake specialist archetype with deep certification heritage across European regulatory frameworks. Wabtec Corporation anchors the integrated systems tier, representing the consolidated rail equipment supplier model with captive brake platform integration. CRRC Corporation Limited occupies a position reflecting state-coordinated industrial scale, exemplifying how national rail programs concentrate procurement authority within domestic supply chains. These three entities collectively illustrate the geographic and structural segmentation constraining competitive mobility across regulatory jurisdictions.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Wabtec Corporation |
| Faiveley Transport |
| CRRC Corporation Limited |
| Hitachi Rail |
| Alstom SA |
| DAKO-CZ |
| Bosch Rexroth |
| Faiveley Transport Wabtec |
| Others |
Value Network & Pricing Analysis
Brake-by-wire electromechanical actuator migration simultaneously compresses pneumatic component margins and concentrates electronic control sourcing among certified Tier 1 integrators. The Federal Railroad Administration's 49 CFR Part 232 recertification deadlines force freight operators into accelerated procurement cycles, amplifying price leverage for suppliers with pre-validated brake-by-wire platforms.
Pricing Analysis
Distributor margins on pneumatic rebuild kits are compressing as rail operators unbundle aftermarket contracts from initial system purchases. Three-tier pricing structure across premium electromechanical, standard electro-pneumatic hybrid, and economy pneumatic maintenance tiers reflects certification grade differentiation and volume scale. Pricing pressure stems from rare earth mineral volatility in ceramic-composite friction materials. Maintenance facilities exhibit highest price sensitivity; Class I freight railroads prioritize total-cost-of-ownership over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision motor and sensor sourcing clusters in Germany and Japan. Electromechanical actuator production draws from Germany, Japan, and China's precision manufacturing bases. Critical inputs include rare earth magnets, high-temperature friction composites, and SIL-rated embedded controllers. Tariff exposure on steel friction materials intensifies under EU carbon-border adjustment mechanisms. Distribution runs through OEM captive networks, independent aftermarket depots, and certified rebuild specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Federal Railroad Administration mandate timelines and EU CCS TSI interoperability requirements generate predictable demand waves for certified brake system upgrades.
For Market Incumbents: To counter brake-by-wire challengers capturing premium positioning, pneumatic specialists must secure electronic control partnerships through technology licensing or joint development agreements. Backward integration into rare earth magnet sourcing mitigates friction material cost volatility. Certification investment across FRA, EU Agency for Railways, and GB/T standards preserves access to multi-jurisdictional procurement pipelines. For New Entrants and Emerging Players: Enter via India's dedicated freight corridor modernization between Delhi and Mumbai, where Make in India localization mandates create procurement entry points for domestic brake component fabrication. Target aftermarket rebuild services for legacy pneumatic fleets in North American classification yards. Position through condition-based maintenance convergence with IoT-enabled predictive wear monitoring. For Investors and Strategic Acquirers: Valuations sit cheapest among pneumatic component specialists facing installed base erosion but holding certified rebuild capabilities and regulatory heritage. Long-term viability hinges on electromechanical technology access and multi-standard certification portfolios. Watch brake-by-wire adoption velocity among Union Pacific and BNSF Railway Tier 4 locomotive deliveries as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Pneumatic specialists secure electronic control access to preserve new-build pipeline participation. |
| Certification Investment | Simultaneous FRA, EU Agency for Railways, and GB/T compliance testing compresses product launch cycles. |
| Aftermarket Service Unbundling | Independent rebuild shops capture margin pools as operators separate overhaul contracts from initial purchases. |
| Condition-Based Maintenance Integration | IoT sensor convergence with electromechanical actuators enables predictive brake wear monitoring. |
| Domestic Content Localization | India's Make in India mandates attract brake fabrication to Gujarat and Maharashtra industrial corridors. |
Research Methodology
Direct dialogue with chief mechanical officers at Class I freight railroads, brake system procurement leads, aftermarket facility managers, and regulatory compliance specialists grounded qualitative findings. Secondary validation drew from Federal Railroad Administration rulemaking dockets, EU Agency for Railways CCS TSI documentation, National Railway Administration GB/T standards, and SEC filings from listed rail equipment suppliers. Bottom-up and top-down triangulation cross-checked unit shipment estimates against fleet modernization program disclosures.
Bottom-up modeling segmented the market across brake type, technology architecture, end-user procurement authority, and installation scenario throughout the forecast period. Electromechanical technology growth trajectories incorporated Tier 4 locomotive delivery schedules and brake-by-wire retrofit penetration assumptions. CAGRs were derived from regression analysis of historical fleet replacement cycles and regulatory mandate timing.
Inputs from FRA enforcement calendars and OEM production disclosures were available through the study window; gaps in aftermarket channel shipment data introduce uncertainty bands around retrofit volume estimates. Forecasts reflect assumptions on regulatory compliance timelines and technology substitution elasticities. Cybersecurity requirements for electromechanical controllers and dual-carbon compliance in steel sourcing represent revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway System Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
India Rail Freight Transport Market
Railway
Train Bogie Market
Railway
Tugger Trains Market
Railway
Global Train Lighting Market
Railway
Rail Brace Market
Railway
Rail Bellows Market
Railway
Solar Powered Train Market
Railway
Automatic Train Supervision Market
Railway
Automatic Train Operation System Market
Railway
Railway Automated Inspection Equipment Market
Railway
Railway Window Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Global High-Speed Train Seat Market
Railway
Train Suspension System Market