
 Freight Wagon Market | 2026-2036
Freight Wagon Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Wagon Market Analytics
EN 12663 structural integrity certification for railway rolling stock is unwinding the competitive landscape, as smaller fabricators struggle to meet fatigue-testing and weld-qualification thresholds. Wabtec Corporation leverages its braking and digital systems portfolio to anchor North American retrofit demand. Titagarh Wagons Ltd sustains cost leadership through integrated steel processing and domestic foundry capacity. The Greenbrier Companies differentiates via specialized tank car and intermodal designs for chemical shippers.
Freight wagons are unpowered rail vehicles designed to carry bulk commodities, intermodal containers, or liquid cargoes, typically constructed from high-tensile steel or aluminum alloys with standardized bogie systems rated for axle loads exceeding 25 tonnes. Their primary purpose is to maximize payload efficiency per train-kilometre while minimizing tare weight and maintenance intervals. Tank car configurations command premium margin pools due to hazardous-material certification requirements and limited qualified fabricators. Flat car and intermodal segments are expanding fastest as port-rail connectivity improves across Asian manufacturing hubs. Gondola wagons remain mature in North American coal corridors, though steel and scrap-metal applications sustain replacement cycles.
The European Union Agency for Railways enforces TSIs covering crashworthiness and noise emissions, while the US Federal Railroad Administration mandates continuous brake inspections and tank car thickness standards under 49 CFR. India's Ministry of Railways and BIS prescribe axle load limits and coupling specifications that govern domestic procurement eligibility. Stakeholders must monitor evolving axle-load harmonization talks between Russian gauge and standard-gauge networks, as interoperability rules will reshape cross-border fleet economics.
Market Dynamics
European Union F-Gas Regulation enforcement is compressing tare-weight tolerances and accelerating aluminum alloy substitution across intermodal fleet renewals. This regulatory pressure cascades through procurement specifications, favoring fabricators with integrated metallurgy capabilities over assembly-only competitors.
Growth Catalysts
- Axle-load harmonization:Ongoing technical talks between Russian gauge and standard-gauge networks are expanding addressable fleet economics for cross-border mineral corridors.
- India's Dedicated Freight Corridors:Ministry of Railways electrification and double-tracking projects on the Eastern and Western DFC routes are generating dedicated wagon procurement windows for domestic steel and agricultural shippers.
- Hazardous-material certification scarcity:Limited qualified tank car fabricators under 49 CFR thickness standards are sustaining premium margin pools for specialized chemical transport configurations.
Market Restraints
- High-tensile steel price volatility:Input cost swings for specialized rail-grade alloys compress fabrication margins during contract bidding cycles.
- Weld-qualification concentration:EN 12663 fatigue-testing infrastructure clusters in Germany and Poland, creating geographic bottlenecks for smaller fabricators seeking certification.
- Intermodal road competition:Flexible trucking networks on sub-500km corridors siphon time-sensitive container volumes from short-haul rail.
Strategic Opportunities
- Port-rail connectivity gaps:Vietnamese and Indonesian manufacturing clusters lack integrated intermodal terminals, creating greenfield infrastructure-wagon bundling opportunities.
- EU Green Deal alignment:Emissions-trading scheme pressures on road freight are redirecting bulk agricultural and construction flows toward rail-qualified equipment.
- Digital freight matching:Asset-light platforms connecting empty backhaul capacity with spot cargo demand are emerging as alternative fleet utilization channels.
Industry Challenges
- Certified welder scarcity:EN 3834-2 qualified personnel shortages extend production lead times for structural integrity-critical components.
- Legacy brake system integration:Retrofitting digital condition-monitoring sensors onto pneumatic braking architectures requires bespoke engineering without standardized interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Wagon Market |
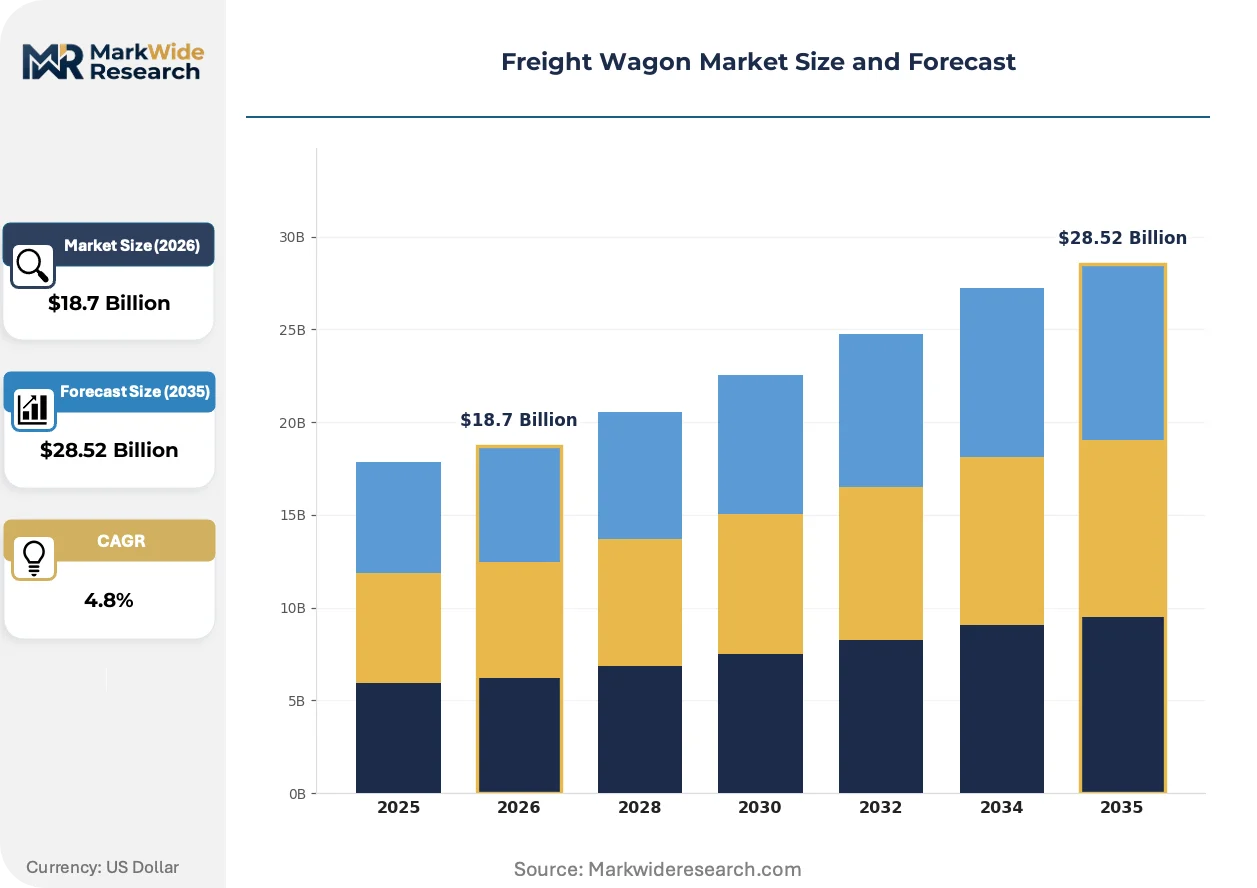
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Car, Flat Car, Tank Car, Gondola End User: Rail Operators, Freight Forwarders, Logistics Companies, Manufacturing Plants Material: Steel, Aluminum, Composite, Wood Application: Bulk Cargo, Intermodal, Agriculture, Automotive |
| Companies Covered | FreightCar America, Titagarh Wagons Ltd, United Wagon Company, Jupiter Wagons Limited, AmstedMaxion, Wabtec Corporation, Trinity Industries, The Greenbrier Companies, National Steel Car, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Wagon Market Evolving Landscape
Digital telemetry and lightweight material science are converging to redefine fleet lifecycle economics. These shifts are compressing traditional maintenance intervals while opening new service-revenue streams for equipment suppliers.
Telematics-enabled predictive maintenance is fragmenting the aftermarket service structure. Sensors monitoring bearing temperature, brake wear, and structural fatigue transmit real-time data to rail operators. Mining and energy firms with captive fleets are adopting these systems fastest. The technology is fragmenting historical maintenance contracts away from scheduled overhauls toward condition-triggered interventions.
European Union Agency for Railways Technical Specifications for Interoperability on noise emissions are mandating composite brake block adoption. This regulatory framework requires retrofitting existing gondola and hopper fleets with low-friction materials. Chemical shippers operating tank cars across trans-European corridors face the steepest compliance timelines and are accelerating replacement cycles ahead of enforcement deadlines.
Spot-market digitization is compressing traditional wagon pooling arrangements. Agricultural commodity traders and scrap metal processors are bypassing legacy leasing companies through direct platform-based asset matching. This behavioral shift is most visible in Indian mineral corridors where Jupiter Wagons and regional operators experiment with app-based empty-wagon location services. The disintermediation threatens long-term lease rate stability while rewarding fleet owners with superior real-time visibility systems.
Freight Wagon Market Segmentation
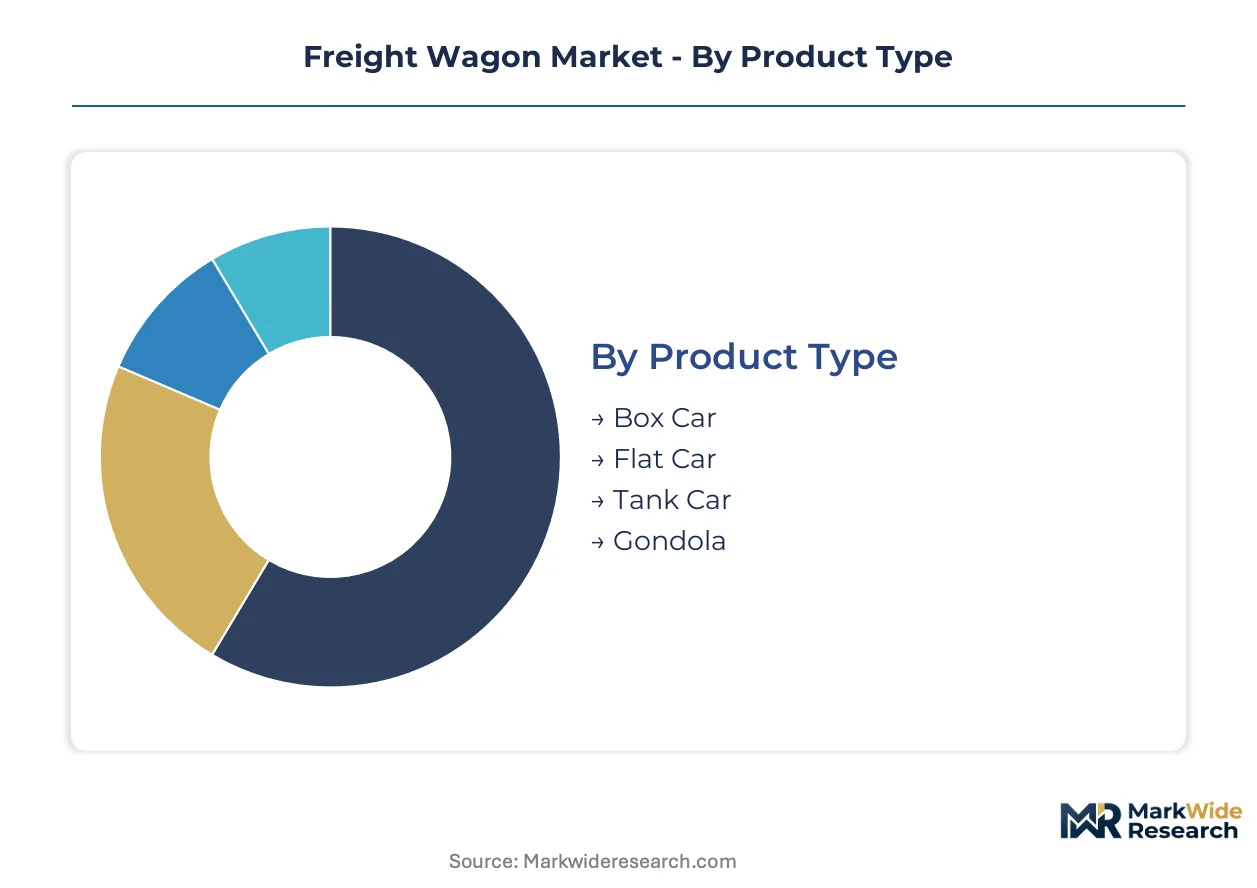
Segmentation in freight wagons reveals where capital deployment concentrates and which specifications command procurement priority. Fabricators align production capacity against axle-load requirements, hazardous-material certification tiers, and regional gauge standards to capture margin pools.
Product Type:
Margins cluster around specialized configurations where regulatory certification creates supply scarcity and limits qualified competitors.
- Tank Car:Cylindrical pressure vessels constructed from high-tensile steel with thickness certification under 49 CFR for hazardous liquid transport. Chemical shippers across trans-European corridors face compressed compliance timelines for composite brake block retrofits, accelerating replacement demand ahead of EU Agency for Railways noise emission deadlines.
- Flat Car:Deck structures rated for intermodal container stacking or heavy machinery lashing, typically employing high-strength steel or aluminum alloys to minimize tare weight. Port-rail connectivity improvements at Vietnamese and Indonesian manufacturing clusters are expanding procurement for double-stack capable designs.
- Box Car:Enclosed weatherproof bodies for palletized or bulk granular cargo, featuring sliding or plug doors. Grain handlers and packaged goods distributors dominate North American and Indian procurement.
- Gondola:Open-top hoppers for coal, steel scrap, and construction aggregates. Mature replacement cycles persist in North American coal corridors despite energy transition headwinds.
The dominant share belongs to Gondola configurations, while Flat Car demand is closing the gap fastest.
End User:
Procurement scale and technical specification authority vary sharply across buyer categories, determining contract structure and aftermarket service attachment rates.
- Rail Operators:National and regional carriers with captive maintenance infrastructure. Indian Railways and Eastern Dedicated Freight Corridor operations generate concentrated wagon procurement windows tied to electrification milestones.
- Logistics Companies:Asset-light or hybrid fleet operators prioritizing telematics integration and flexible lease structures. Digital freight matching platforms are reshaping their equipment sourcing patterns.
- Freight Forwarders:Intermediaries bundling multimodal capacity. Their influence concentrates in European cross-border corridors where TSI interoperability compliance determines fleet eligibility.
- Manufacturing Plants:Captive industrial users in mining and energy sectors. These buyers adopt predictive maintenance sensors fastest, fragmenting traditional scheduled overhaul contracts.
Rail Operators command the largest procurement volumes, though Logistics Companies are gaining purchasing influence most rapidly through platform-based asset aggregation.
Material:
Weight-performance tradeoffs and regulatory emissions frameworks are rebalancing material selection across fleet renewal cycles.
- Steel:High-tensile rail-grade alloys dominating structural members and impact-resistant components. Price volatility for specialized alloys compresses fabrication margins during contract bidding.
- Aluminum:Extruded and cast alloys substituting into intermodal and tank car bodies to reduce tare weight. EU F-Gas Regulation enforcement is accelerating aluminum penetration where lighter designs improve energy efficiency ratings.
- Composite:Fiber-reinforced polymers for interior linings, brake components, and noise-dampening elements. Limited to non-structural applications pending EN 12663 fatigue-testing validation expansion.
- Wood:Flooring and bracing in historical or specialized configurations. Restricted to niche agricultural and heritage fleet applications.
Steel retains structural dominance, while Aluminum is expanding application share most aggressively under emissions compliance pressure.
Application:
Payload density and handling infrastructure requirements segment demand by cargo category and corridor economics.
- Intermodal:Container and trailer-on-flatcar operations requiring standardized twist-lock spacing and stack height clearance. Asian manufacturing hub port expansions are driving specification harmonization between regional gauge networks.
- Bulk Cargo:Mineral, coal, and construction aggregate movements in gondola and hopper configurations. Dedicated corridor investments in India and cross-border Russian gauge-standard gauge harmonization talks are expanding addressable fleet economics.
- Agriculture:Grain, fertilizer, and perishable product transport. EU Green Deal road freight emissions pricing is redirecting agricultural flows toward rail-qualified equipment.
- Automotive:Finished vehicle and component transport in enclosed or specialized deck configurations. Just-in-time delivery requirements favor trucking on sub-500km corridors, constraining rail modal share.
Bulk Cargo commands established procurement volumes, yet Intermodal is climbing the fastest as port-rail terminal integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and India's Dedicated Freight Corridor electrification are redirecting procurement volumes toward lighter, more efficient wagon specifications across mineral and agricultural corridors.
United States
The Federal Railroad Administration enforces 49 CFR tank car thickness standards that sustain premium margin pools for qualified fabricators serving chemical shippers. Wabtec Corporation anchors North American retrofit demand through braking and digital systems integration. Houston-Gulf Coast petrochemical clusters generate concentrated procurement for hazardous-material certified configurations.
India
Ministry of Railways electrification milestones on the Eastern and Western Dedicated Freight Corridors are opening dedicated procurement windows for domestic steel and agricultural shippers. BIS axle load limits and coupling specifications govern domestic procurement eligibility. Titagarh Wagons and Jupiter Wagons serve mineral corridors radiating from Dhanbad and Raipur steel centers.
Germany
The EU Agency for Railways Technical Specifications for Interoperability mandate composite brake block adoption across trans-European corridors. EN 12663 fatigue-testing infrastructure clusters create geographic bottlenecks for fabricators seeking structural integrity certification. Ruhr industrial basin steel and scrap-metal applications sustain replacement cycles for gondola configurations.
China
MIIT rail-grade alloy standards and dual carbon goals are accelerating aluminum substitution in intermodal fleet renewals to improve energy efficiency ratings. Yangtze River Delta port-rail connectivity improvements are expanding procurement for double-stack capable flat car designs. Manufacturing clusters around Shanghai and Ningbo drive specification harmonization discussions.
Russia
Ongoing technical talks between Russian gauge and standard-gauge networks are expanding addressable fleet economics for cross-border mineral corridors. The country's national rail regulator oversees axle-load harmonization protocols that will reshape fleet interoperability rules. Ural mining districts and Siberian coal basins sustain bulk cargo wagon demand.
Freight Wagon Market Competitive Landscape
Player mix skews toward integrated steel processors and specialized tank car fabricators with hazardous-material certification. The competitive structure concentrates around fabricators with captive metallurgy capabilities and those with assembly-only models struggling against EN 12663 weld-qualification thresholds. Two strategic archetypes dominate: vertically integrated domestic champions with foundry and rolling mill assets, and technology-anchored multinationals leveraging digital braking and telemetry portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves, with fabricators securing EN 3834-2 certified welder pipelines and rail operators bundling infrastructure-wagon procurement.
Within the integrated domestic tier, Titagarh Wagons Ltd exemplifies cost leadership through captive steel processing and foundry capacity. Jupiter Wagons Limited occupies a comparable position serving Indian mineral corridors with app-based empty-wagon location experiments. Wabtec Corporation anchors the technology-anchored multinational archetype, representing digital systems integration across North American retrofit demand. These three fabricators illustrate how regulatory certification scarcity and metallurgy integration separate sustainable margin positions from assembly-only competitors.
| Leading Market Players |
|---|
| FreightCar America |
| Titagarh Wagons Ltd |
| United Wagon Company |
| Jupiter Wagons Limited |
| AmstedMaxion |
| Wabtec Corporation |
| Trinity Industries |
| The Greenbrier Companies |
| National Steel Car |
| Others |
Value Network & Pricing Analysis
EN 12663 structural integrity certification gates both supply qualification and price differentiation simultaneously, compressing the vendor base to fabricators with captive fatigue-testing infrastructure while elevating certified-welder premiums across contract structures. This regulatory threshold feeds directly into procurement economics, where buyers face step-function cost increases when crossing from assembly-only suppliers to integrated metallurgy competitors.
Pricing Analysis
Certification tier under 49 CFR and EN 12663 standards creates the primary spread between premium tank car configurations and commodity gondola replacements. Three-tier pricing structure across hazardous-material certified, structural-critical, and standard freight designs stratifies buyer segments, with chemical shippers absorbing the steepest premiums for limited-qualified fabricator access. Cost compression in standard hopper and flat car segments is intensifying because high-tensile steel price volatility feeds directly into margin pressure during bidding cycles. Rail operators with captive maintenance infrastructure demonstrate the lowest price sensitivity, while logistics companies aggregating through digital freight platforms drive the hardest volume-based negotiations.
Supply Chain Analysis
EN 3834-2 qualified welder availability in Germany and Poland underwrites production lead times for structural integrity-critical components across European procurement. High-tensile rail-grade steel draws from integrated mills in India, China, and Germany, while aluminum extrusion capacity for lightweight intermodal designs rests on Chinese and South Korean smelter output. Single-source vulnerability concentrates around specialized brake system casting foundries serving North American retrofit demand. Distribution runs through operator-direct procurement contracts for national rail carriers and leasing company intermediaries for asset-light logistics aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Axle-load harmonization between Russian gauge and standard-gauge networks is repositioning fleet economics as a platform interoperability play, where wagons capable of cross-border mineral corridors capture expanding addressable demand. This ecosystem shift rewards fabricators with multi-certification capabilities and real-time visibility systems.
For Market Incumbents: Fortify EN 12663 certification infrastructure against emerging assembly-only competitors by deepening captive welder pipelines in Poland and Germany. Anchor retrofit demand through digital braking system integration, as Wabtec Corporation's telemetry portfolios demonstrate, while defending margin position against aluminum substitution pressure from Chinese intermodal fleet renewals under MIIT efficiency mandates. For New Entrants and Emerging Players: Predictive maintenance service layers represent the most penetrable white-space, where incumbent fabricators under-serve mining and energy captive fleets with condition-triggered intervention contracts. Target Vietnamese and Indonesian port-rail connectivity gaps with infrastructure-wagon bundling propositions, leveraging app-based empty-wagon location capabilities as Jupiter Wagons experiments demonstrate in Indian mineral corridors. For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement reshapes the acquisition landscape toward aluminum-capable metallurgy integrators and hazardous-material certified tank car specialists. Long-term viability favors vertically integrated fabricators with foundry assets over assembly-only competitors facing EN 12663 qualification bottlenecks. Watch EN 3834-2 certified welder wage inflation as the inflection signal for production cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EN 12663 Certification Investment | Captive fatigue-testing infrastructure in Germany and Poland locks out assembly-only competitors from premium contract tiers. |
| Aluminum Alloy Capacity Expansion | MIIT rail-grade standards and EU F-Gas Regulation accelerate lightweight intermodal designs for energy efficiency compliance. |
| Digital Telemetry Integration | Real-time bearing temperature and brake wear monitoring fragments scheduled overhaul contracts toward condition-triggered service revenue. |
| Cross-Border Gauge Harmonization | Technical talks between Russian and standard-gauge networks expand addressable fleet economics for mineral corridor operators. |
| Certified Welder Pipeline Development | EN 3834-2 qualification scarcity in Eastern Europe creates production bottlenecks extending lead times for structural-critical components. |
Research Methodology
A spread of perspectives from rail operator procurement directors, freight wagon fabrication engineers, leasing company portfolio managers, and mining fleet maintenance heads converged on the working assumptions. Primary interviews combined with secondary validation from EU Agency for Railways TSI documentation, US Federal Railroad Administration 49 CFR filings, Indian Ministry of Railways procurement circulars, and customs trade data for rail-grade steel and aluminum alloy imports. Bottom-up segment sizing triangulated against top-down macroeconomic freight volume indicators.
Segmentation dimensions modeled across the analysis window include product type configuration, end-user procurement authority, material substitution trajectory, and application payload density. CAGRs derived from regression against mineral corridor investment flows, port-rail terminal completion schedules, and hazardous-material certification capacity constraints. Forecast inputs incorporated Dedicated Freight Corridor electrification milestones and composite brake block retrofit compliance timelines.
Forecasts assume regulatory continuity in EU F-Gas Regulation enforcement, US 49 CFR tank car standards, and Indian BIS axle load specifications; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as axle-load harmonization protocols and aluminum alloy price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Bullet Train Market
Railway
India Rail Freight Transport Market
Railway
Check Rails Market
Railway
France Connected Rail Market
Railway
Rail Glazing Market
Railway
Rail Bellows Market
Railway
Locomotive Doors Market
Railway
Railway Axle Market
Railway
Rail Damper Market
Railway
Railway Rolling Stock Market
Railway
40-Foot Platform Wagons Market
Railway
Gearbox for Rail Vehicles Market
Railway
Gangway for Railway Vehicles Market
Railway
France Rail Freight Transport Market
Railway
Locomotive Radiator Fan Market
Railway
Railway Horn Market