
 Railway Fishplate Market | 2026-2036
Railway Fishplate Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Fishplate Market Outlook
Welding technician shortages across mature rail networks is bifurcating the competitive landscape between bolted-system incumbents and welded-rail specialists. AGICO Group leverages its integrated forging capacity to dominate standard fishplate supply across Belt and Road corridors. Voestalpine AG anchors European demand through rail-grade steel expertise and proximity to Austrian-German maintenance hubs. Pandrol Limited differentiates via clipped fastening systems that reduce field welding dependency.
A railway fishplate is a metal or composite bar bolted, welded, or bonded across the abutting ends of two rails to maintain alignment and transfer wheel loads, typically manufactured from pearlitic rail steel (R260 or R350HT grade) through hot forging or rolling processes with drilled holes for high-tensile bolts. Its primary purpose is to provide longitudinal and lateral continuity at rail joints while permitting thermal expansion. Standard fishplates still occupy the largest volume share in emerging networks where bolted joints predominate, though margin pools concentrate in insulated and glued variants where electrical isolation and reduced maintenance justify premium positioning. Composite material adoption remains nascent but accelerates in corrosion-prone coastal installations where aluminum and fiber-reinforced alternatives displace conventional steel.
Network Rail standards in the United Kingdom, EN 14587 welding protocols under European Committee for Standardization jurisdiction, and Federal Railroad Administration track safety regulations in the United States collectively elevate product certification barriers and shape procurement specifications. India's Ministry of Railways through Research Designs and Standards Organisation mandates BIS-certified fishplates for all trunk routes, creating compliance-driven supplier consolidation. Stakeholders must monitor how decarbonization mandates and rail electrification timelines redirect material specifications and installation method preferences across their served corridors.
Market Dynamics
Continuously welded rail standards are bifurcating demand between legacy bolted fishplate systems and insulated composite variants, forcing suppliers to maintain dual production capabilities while procurement specifications diverge across network maturity levels.
Growth Catalysts
- Heavy-haul freight corridors:North American and Australian operators are compressing replacement cycles as axle loads exceed 32.5 tonnes, generating recurring demand for high-wear-resistant R350HT grade fishplates.
- EN 14587 welding protocols:European standardization is redirecting capital toward glued and insulated fishplate variants that maintain electrical continuity for signaling systems.
- BIS certification mandates:India's Ministry of Railways through Research Designs and Standards Organisation is consolidating supplier bases by requiring certified fishplates for all trunk route expansions.
Market Restraints
- Scrap steel price volatility:Pearlitic rail steel input costs fluctuate with electric arc furnace capacity utilization, squeezing forging margins for standard fishplate producers.
- Welding technician scarcity:Mature networks in Germany and Japan face structural shortages of certified thermite welding crews, limiting conversion rates from bolted to continuously welded rail.
- Composite substitution threat:Fiber-reinforced polymer alternatives from coastal infrastructure projects are penetrating corrosion-sensitive installations, threatening steel volume in marine-adjacent corridors.
Strategic Opportunities
- Southeast Asian network buildouts:Indonesia and Vietnam are prioritizing standard bolted fishplates for rapid gauge expansion, favoring forging capacity proximity over premium welded solutions.
- EU Green Deal procurement incentives:Carbon-accounted rail maintenance contracts are rewarding suppliers with verified Scope 3 emissions reductions in fishplate production.
- Aluminum-steel hybrid bonding:Advanced adhesive technologies are converging with lightweight alloy forging to create insulated fishplates with 40% mass reduction for high-speed applications.
Industry Challenges
- Thermite welding certification timelines:European and North American networks require 18-24 month field apprenticeship completion before technicians qualify for continuous weld installation, constraining labor supply elasticity.
- Legacy joint inventory rationalization:Operators maintaining mixed bolted and welded networks face SKU proliferation in maintenance depots, complicating spare parts forecasting and working capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Fishplate Market |
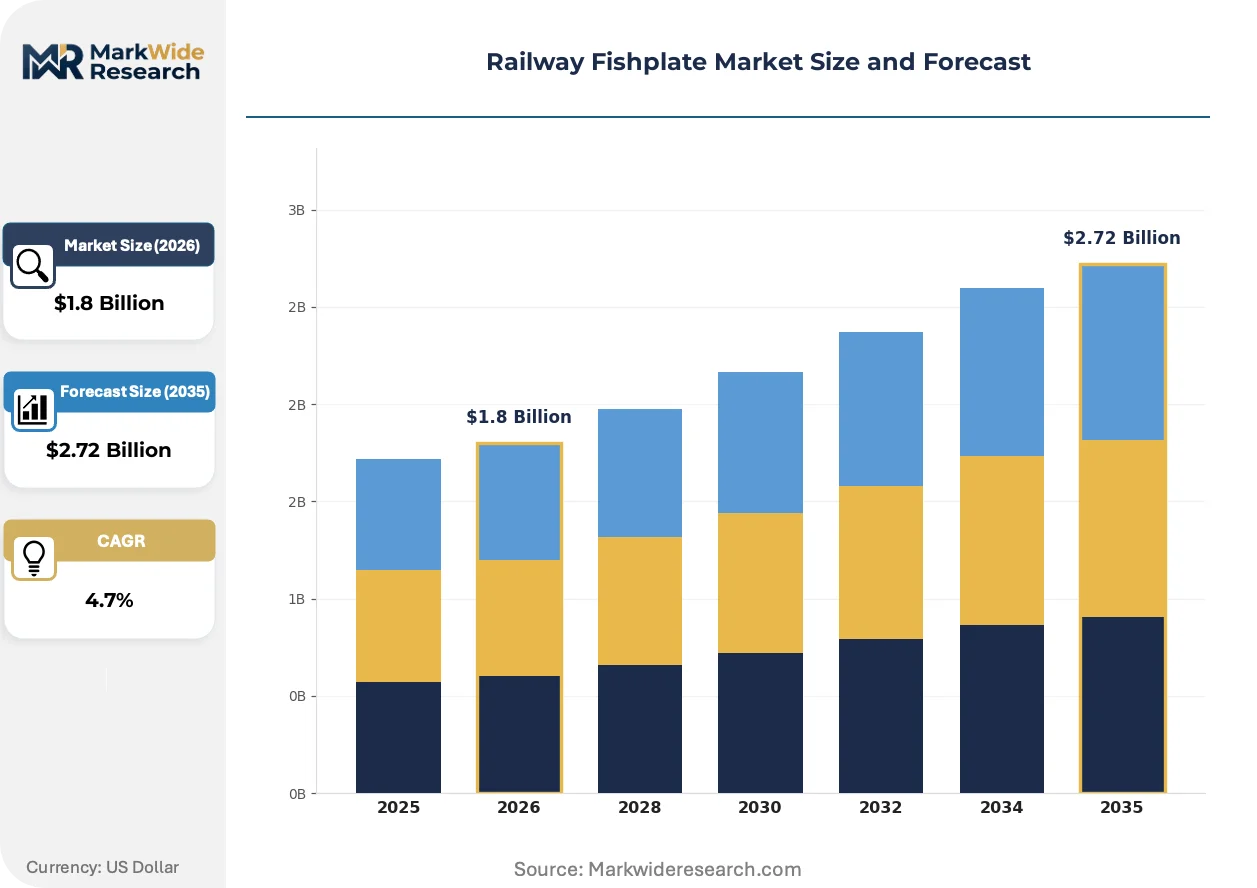
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fishplates, Insulated Fishplates, Glued Fishplates, Welded Fishplates Material: Steel, Aluminum, Plastic, Composite Installation Method: Bolted, Welded, Clipped, Riveted End User: Railway Operators, Maintenance Contractors, Infrastructure Developers, Government Agencies |
| Companies Covered | AGICO Group, Koppers Holdings Inc., L.B. Foster Company, Vossloh AG, Pandrol Limited, Voestalpine AG, Kimes Steel & Rail, Inc., Taicang Zhongbo Railway Fastening Co. Ltd., Progress Rail Services Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Fishplate Market Strategic Shifts
Material science advances and regulatory pressure on track electrification are converging to accelerate composite adoption and compress traditional steel-forging dominance in jointing systems across mature networks.
Glued insulated fishplates utilizing epoxy-bonded aluminum cores are supplanting conventional bolted steel variants in European high-speed corridors where signaling integrity demands electrical isolation. Network Rail and Deutsche Bahn maintenance divisions are specifying these systems for renewal programs exceeding 200 km annually. The shift is compressing demand for field welding services while elevating adhesive chemistry expertise among tier-one suppliers.
REACH chemical safety regulations are restricting hexavalent chromium surface treatments historically applied to corrosion protection for coastal fishplate installations. Finnish and Norwegian infrastructure managers are responding by mandating zinc-nickel alloy coatings or thermal spray aluminum alternatives in procurement specifications issued since 2023. The compliance burden is favoring integrated coating capabilities over merchant finishing houses.
Consolidated purchasing by state-owned rail operators is compressing distributor margins and redirecting contract flows toward direct manufacturer relationships. Indian Railways and China State Railway Group are centralizing fishplate procurement through multi-year framework agreements that bypass traditional trading houses. The channel restructuring is most visible in standard-grade bolted segments where specification standardization enables volume aggregation.
Railway Fishplate Market Segmentation
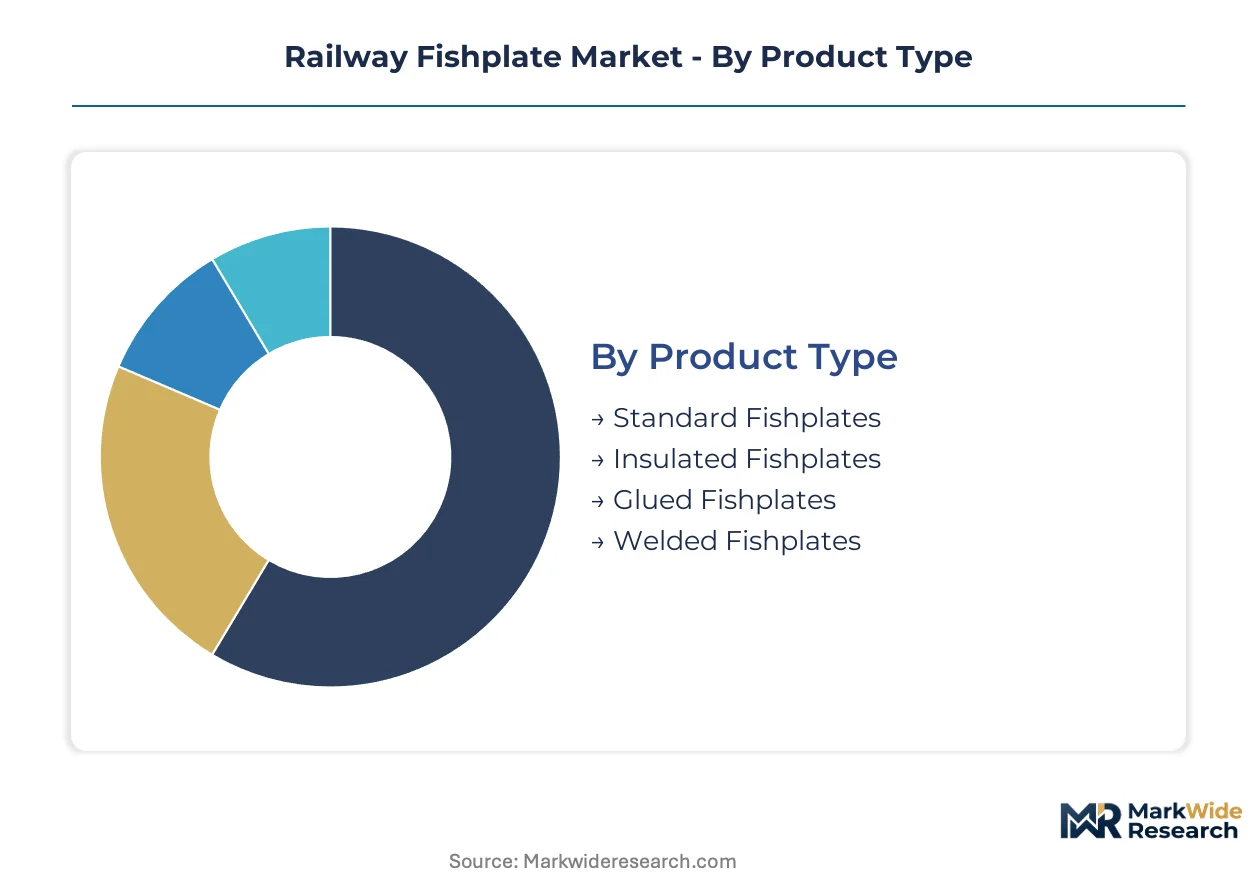
Railway fishplate procurement channels diverge sharply by segment maturity. Standard-grade bolted products flow through consolidated distributor networks serving emerging markets, while insulated and glued variants command direct manufacturer relationships with European and Asian high-speed operators.
Product Type:
Channel economics split between legacy forging houses and specialized adhesive-system suppliers, with procurement specifications determining whether fishplates reach trackside through maintenance contractors or direct rail operator frameworks.
- Standard Fishplates:Hot-forged pearlitic rail steel with drilled bolt holes for R260 or R350HT grade applications. Demand concentrates across Indian trunk route expansions and Southeast Asian gauge buildouts where BIS-certified suppliers dominate procurement through Ministry of Railways framework agreements. Margin compression from scrap steel volatility favors integrated forging capacity.
- Insulated Fishplates:Epoxy-bonded aluminum or steel composite cores engineered for electrical isolation in signaling corridors. European high-speed renewals exceeding 200 km annually under Network Rail and Deutsche Bahn specifications are redirecting procurement toward adhesive chemistry specialists with REACH-compliant coating capabilities.
- Glued Fishplates:Advanced polymer-bonded systems eliminating mechanical fastening for continuously welded rail transitions.
- Welded Fishplates:Thermite-compatible jointing for permanent rail continuity in heavy-haul corridors.
Standard Fishplates dominate installed base. Insulated Fishplates is where expansion concentrates.
Material:
Cost tiers stratify by corrosion exposure and axle load requirements, with coastal infrastructure managers paying premiums for aluminum and fiber-reinforced alternatives over conventional pearlitic steel.
- Steel:Pearlitic grades R260 and R350HT remain the baseline for heavy-haul freight corridors in North America and Australia where axle loads exceed 32.5 tonnes. Electric arc furnace capacity utilization directly shapes input cost structures for forging operators.
- Aluminum:Lightweight alloy cores bonded in insulated configurations deliver 40% mass reduction for high-speed applications. Finnish and Norwegian coastal mandates since 2023 are accelerating zinc-nickel coating substitution for hexavalent chromium treatments under REACH protocols.
- Plastic:Limited deployment in temporary track installations and yard switching zones.
- Composite:Fiber-reinforced polymer alternatives penetrating corrosion-sensitive marine-adjacent corridors.
Steel commands volume leadership. Aluminum is climbing the fastest on electrification and coastal corrosion mandates.
Installation Method:
Customer type determines method preference, with state-owned operators in India and China centralizing bolted-system procurement while European maintenance contractors face welding technician scarcity.
- Bolted:Mechanical fastening with high-tensile bolts through aligned rail and fishplate holes. Indonesia and Vietnam rapid network buildouts favor this method for speed of deployment and lower skill requirements in field crews.
- Welded:Thermite or flash-butt continuous rail joining eliminating joint maintenance. Germany and Japan face 18-24 month certification timelines constraining labor supply elasticity for conversion from bolted systems.
- Clipped:Pandrol-style fastening reducing field welding dependency in European renewal programs.
- Riveted:Legacy method retained in heritage railway preservation and select industrial sidings.
Bolted methods anchor emerging network expansion. Welded installations are gaining share fastest in mature corridor electrification.
End User:
Volume concentration versus margin extraction splits across government procurement centralization and contractor specialization in maintenance outsourcing markets.
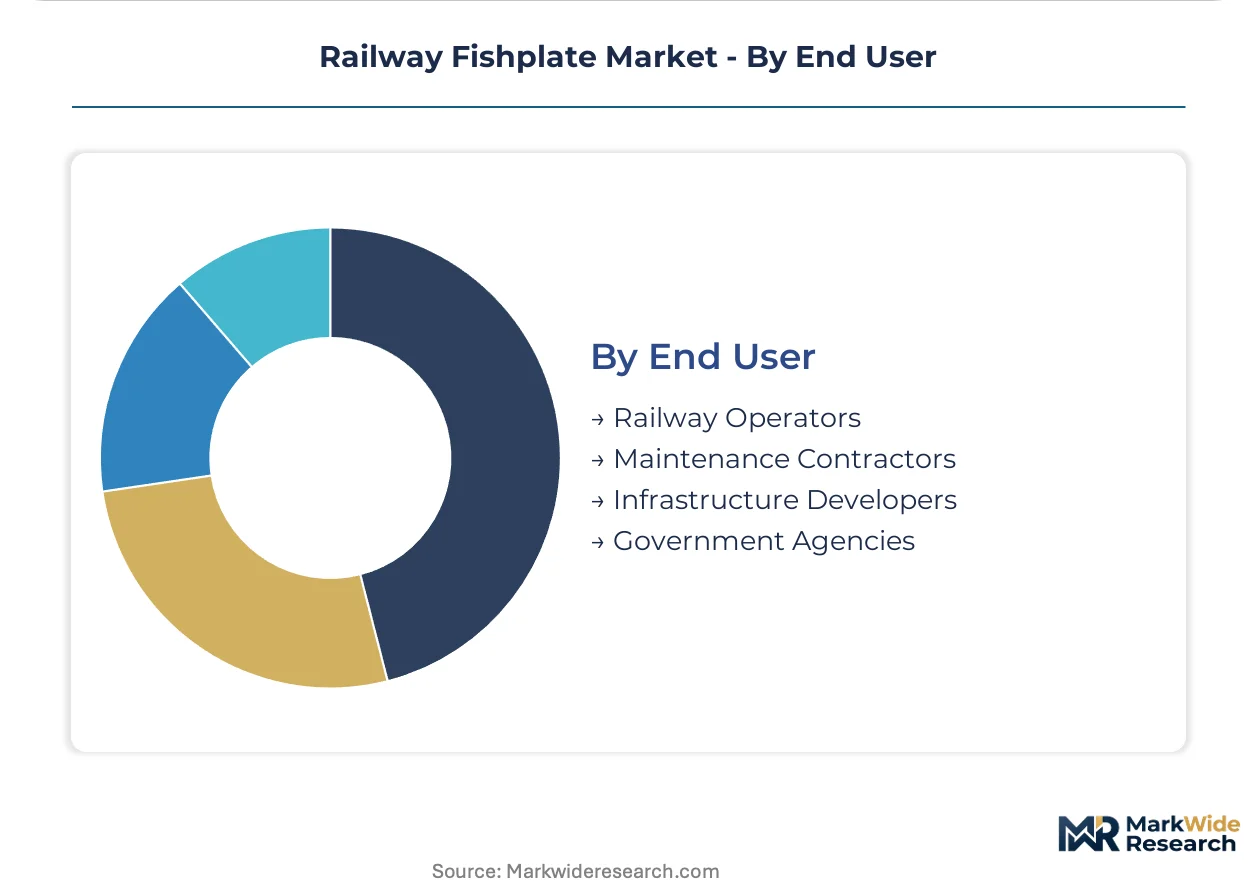
- Railway Operators:State-owned entities including Indian Railways and China State Railway Group are consolidating fishplate procurement through multi-year direct manufacturer agreements, bypassing traditional trading houses in standard-grade segments.
- Maintenance Contractors:Specialized track renewal firms in the United Kingdom and Germany are specifying insulated and glued variants for signaling integrity, capturing premium margins through adhesive expertise and coating compliance.
- Infrastructure Developers:Greenfield project sponsors in Southeast Asia prioritizing speed-to-completion over lifecycle cost optimization.
- Government Agencies:National transport ministries mandating certification standards and carbon-accounted procurement under EU Green Deal incentives.
Railway Operators dominate installed base procurement volume. Maintenance Contractors is where premium segment expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates through India's Ministry of Railways are consolidating supplier bases across the largest emerging network expansion, while EN 14587 welding protocols in Europe redirect capital toward insulated variants. Heavy-haul freight corridors in North America and Australia compress replacement cycles as axle loads rise.
United States
Heavy-haul freight operators compress replacement cycles as axle loads exceed 32.5 tonnes, generating recurring demand for R350HT grade fishplates. Federal Railroad Administration track safety regulations elevate product certification barriers and shape procurement specifications. Maintenance depots across Illinois and Ohio rail corridors face SKU proliferation from mixed bolted and welded network inventories.
Germany
Deutsche Bahn maintenance divisions specify glued insulated fishplates for renewal programs exceeding 200 km annually. REACH chemical safety regulations restrict hexavalent chromium surface treatments, mandating zinc-nickel alloy coatings since 2023. Thermite welding certification timelines of 18-24 months constrain labor supply elasticity for continuous weld conversion in Bavarian maintenance hubs.
India
Rapid trunk route expansion concentrates demand for standard bolted fishplates amid gauge buildouts. Research Designs and Standards Organisation mandates BIS-certified fishplates, consolidating supplier bases through Ministry of Railways framework agreements. Forging capacity clusters in Punjab and Uttar Pradesh dominate procurement for Belt and Road corridor projects.
Australia
Heavy-haul iron ore corridors in Western Australia accelerate replacement cycles as axle loads intensify. State rail regulators enforce fatigue-resistant specifications for desert-climate thermal expansion management. Maintenance contractors in Perth and Port Hedland prioritize R350HT grade sourcing from integrated forging operators.
China
China State Railway Group centralizes fishplate procurement through multi-year framework agreements bypassing traditional trading houses. GB standards and dual carbon goals redirect material specifications toward carbon-accounted production methods. Manufacturing clusters in Hebei and Shanxi provinces supply standard-grade segments for domestic network densification.
Railway Fishplate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Railway Fishplate Market structure. The upper tier commands direct relationships with state-owned rail operators through multi-year framework agreements, while mid-scale forging houses serve maintenance contractors and regional distributors. Three archetypes dominate: integrated steel-forging conglomerates with captive rail-grade capacity, adhesive-system specialists with REACH-compliant coating capabilities, and regional forging operators serving emerging network buildouts. Competitive moves center on backward integration into pearlitic rail steel supply and geographic expansion through Belt and Road corridor anchoring.
Among integrated forging conglomerates, AGICO Group exemplifies the archetype of operators leveraging captive capacity to dominate standard fishplate supply across Asian network expansions. Voestalpine AG anchors European positioning through rail-grade steel expertise and proximity to Austrian-German maintenance hubs. Pandrol Limited occupies a distinct tier as a fastening-system specialist reducing field welding dependency for signaling-integrity corridors. These three entities represent the competitive spectrum from volume-driven forging to premium adhesive-system positioning.
| Leading Market Players |
|---|
| AGICO Group |
| Koppers Holdings Inc. |
| L.B. Foster Company |
| Vossloh AG |
| Pandrol Limited |
| Voestalpine AG |
| Kimes Steel & Rail, Inc. |
| Taicang Zhongbo Railway Fastening Co. Ltd. |
| Progress Rail Services Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day inventory cycles for R350HT grade pearlitic rail steel concentrate pricing power with integrated forging operators in Punjab and Hebei provinces, while spot-market buyers face margin compression from electric arc furnace capacity volatility. This lead-time asymmetry rewards backward integration into rail-grade steel supply and penalizes merchant forging houses dependent on scrap steel spot markets.
Pricing Analysis
Geographic price spreads between European glued insulated variants and Southeast Asian standard bolted fishplates reflect certification-tier differentiation rather than material cost alone. Three-tier pricing structure across premium insulated, standard certified, and economy non-certified levels anchors procurement frameworks, with BIS certification and REACH compliance as the primary price differentiation drivers. Cost compression in standard-grade segments is intensifying because Indian Railways and China State Railway Group centralize multi-year framework agreements. Maintenance contractors in Germany and the United Kingdom show least price sensitivity due to signaling-integrity mandates, while infrastructure developers in Indonesia and Vietnam prioritize unit economics.
Supply Chain Analysis
China and India anchor global forging capacity for standard fishplate production, with Austria and Germany specializing in adhesive-system manufacturing for insulated variants. Raw material flows draw from pearlitic rail steel R260 and R350HT grades, epoxy bonding agents, and zinc-nickel alloy coatings. Single-source vulnerability concentrates in thermite welding consumables for continuous rail conversion. Distribution runs through direct manufacturer relationships with state-owned rail operators in Asia and specialized maintenance contractors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through state-owned rail operator procurement centralization, with Indian Railways and China State Railway Group bypassing traditional trading houses to compress distributor margins across standard-grade segments.
For Market Incumbents: Compound defensive positioning by securing captive rail-grade steel supply through backward integration into electric arc furnace operations, insulating forging margins from scrap price volatility. Invest in REACH-compliant coating capabilities to capture premium positioning in European insulated fishplate renewals, defending against adhesive-system specialists penetrating signaling-corridor maintenance contracts. For New Entrants and Emerging Players: Differentiate on aluminum-steel hybrid bonding expertise to serve Finnish and Norwegian coastal mandates replacing hexavalent chromium treatments. Target Southeast Asian gauge buildouts in Vietnam and Indonesia with standard bolted fishplate offerings, leveraging forging capacity proximity over premium welded solutions. Pursue direct relationships with infrastructure developers prioritizing speed-to-completion over lifecycle cost optimization. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because state-owned procurement centralization favors integrated forging conglomerates with multi-year framework agreement access. Acquisition targets should exhibit captive rail-grade steel supply and BIS or EN 14587 certification credentials. Monitor thermite welding technician certification completion rates as inflection indicator for continuous welded rail conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rail-Grade Steel | Captive R260 and R350HT supply insulates forging margins from electric arc furnace volatility. |
| REACH-Compliant Coating Investment | Zinc-nickel alloy capabilities unlock Network Rail and Deutsche Bahn insulated fishplate specifications. |
| Multi-Year Framework Agreement Negotiation | Direct relationships with Indian Railways and China State Railway Group bypass distributor margin compression. |
| Aluminum-Steel Hybrid Bonding Development | 40% mass reduction addresses EU Green Deal carbon-accounted procurement incentives for high-speed corridors. |
| Southeast Asian Forging Capacity Expansion | Proximity to Indonesia and Vietnam gauge buildouts captures standard bolted demand with lower logistics exposure. |
Study Parameters
A spread of perspectives from track maintenance directors, rail operator procurement leads, forging plant managers, and adhesive-system R&D heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, Ministry of Railways framework agreement disclosures, and SEC filings from listed rail infrastructure suppliers. Bottom-up volume modeling triangulated against top-down market sizing across product type, material grade, installation method, and end-user segments.
Segmentation dimensions modeled include product type tier, material composition, installation methodology, and geographic regulatory cluster. Growth trajectories were derived from replacement cycle analysis in heavy-haul corridors, network electrification timelines, and certification mandate implementation schedules. Forecast inputs incorporated axle load intensification trends, thermite welding technician supply constraints, and composite substitution penetration in coastal installations.
Decision-makers should treat outputs as directional under assumptions of sustained state-owned procurement centralization and stable EN 14587 welding protocol adoption; material deviation in scrap steel pricing or REACH regulatory expansion would warrant model refresh. Recalibration cycles align with material shifts in BIS certification enforcement, EU Green Deal procurement incentive structures, and Southeast Asian network buildout acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Sleepers Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railcar Movers Market