
 UAE ICT Market | 2026-2036
UAE ICT Market Size, Share, and Industry Trends Forecast 2026-2036
UAE ICT Market Analytics
Specialized cloud architecture talent is reorganizing how technology providers structure their UAE operations. Microsoft Corporation leverages its hyperscale Azure footprint to anchor enterprise and government contracts across the Emirates. Oracle Corporation competes through database-to-cloud migration services tailored to regional compliance requirements. Huawei Technologies sustains infrastructure dominance in 5G and fiber backbone deployment despite geopolitical headwinds.
Information and communications technology in the UAE encompasses computing hardware, telecommunications infrastructure, enterprise software, and digital services operating across fixed and mobile networks with latency thresholds below 20 milliseconds for real-time applications. The primary purpose centers on enabling data-driven decision-making, automation, and connectivity across public and private sector operations. Cloud Solutions within the Product Type dimension capture expanding margin pools as government mandates favor subscription over capital expenditure models. Edge Computing under Deployment Model is gaining traction in oilfield operations and autonomous logistics corridors where latency sensitivity exceeds centralized cloud capabilities.
MOHAP and the UAE Telecommunications and Digital Government Regulatory Authority shape market access through data residency mandates and cybersecurity certification requirements for critical infrastructure vendors. TRAI-aligned spectrum policies and the UAE National Informatization Plan direct procurement standards toward interoperable, sovereign-cloud-compliant architectures. Stakeholders must monitor evolving AI governance frameworks and localization rules that will determine which technology stacks qualify for federal and emirate-level contracts.
Market Dynamics
Federal cloud-first procurement mandates under the UAE National Informatization Plan are compressing legacy infrastructure refresh cycles while redirecting capital toward sovereign-compliant subscription architectures across Dubai and Abu Dhabi government entities.
Growth Catalysts
- MOHAP Data Residency Mandates:Healthcare and critical infrastructure operators must store citizen data within UAE borders, creating immediate demand for localized hyperscale facilities and edge nodes.
- Smart City Infrastructure:Dubai's autonomous logistics corridors and AI-powered traffic management systems require sub-20-millisecond latency networks that only fiber-plus-5G combinations can deliver.
- Federal Digital Transformation:The UAE Telecommunications and Digital Government Regulatory Authority mandates interoperable architectures, forcing legacy system replacements with API-native platforms.
Market Restraints
- Specialized Talent Scarcity:Cloud architecture and AI governance expertise concentrates among a limited pool of expatriate professionals, inflating compensation costs for implementation partners.
- Geopolitical Supply Concentration:5G radio equipment and submarine cable landing stations face sourcing restrictions that complicate multi-vendor redundancy strategies for Emirates-based carriers.
- Cybersecurity Certification Friction:TRAI-aligned security frameworks impose 12-18 month approval timelines for foreign cloud providers seeking critical infrastructure eligibility.
Strategic Opportunities
- Ras Al Khaimah and Fujairah:These northern emirates lag Dubai and Abu Dhabi in digital government maturity, presenting first-mover advantages for localized service delivery partnerships.
- Oilfield Edge Computing:ADNOC's remote drilling operations generate terabyte-scale sensor data that cannot transit to centralized clouds, requiring on-rig processing nodes with AI inference capabilities.
- AI Governance Frameworks:Pending federal AI ethics regulations will create compliance service revenue streams for consultancies that interpret localization and bias-testing requirements.
Industry Challenges
- Legacy System Integration:Federal ministries operate 15-20 year-old ERP platforms that resist API connectivity, forcing expensive middleware development for cloud-hybrid architectures.
- Multi-Cloud Orchestration Complexity:Government buyers demand workload portability across Azure, Oracle Cloud, and emerging sovereign providers, straining vendor-agnostic DevOps capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE ICT Market |
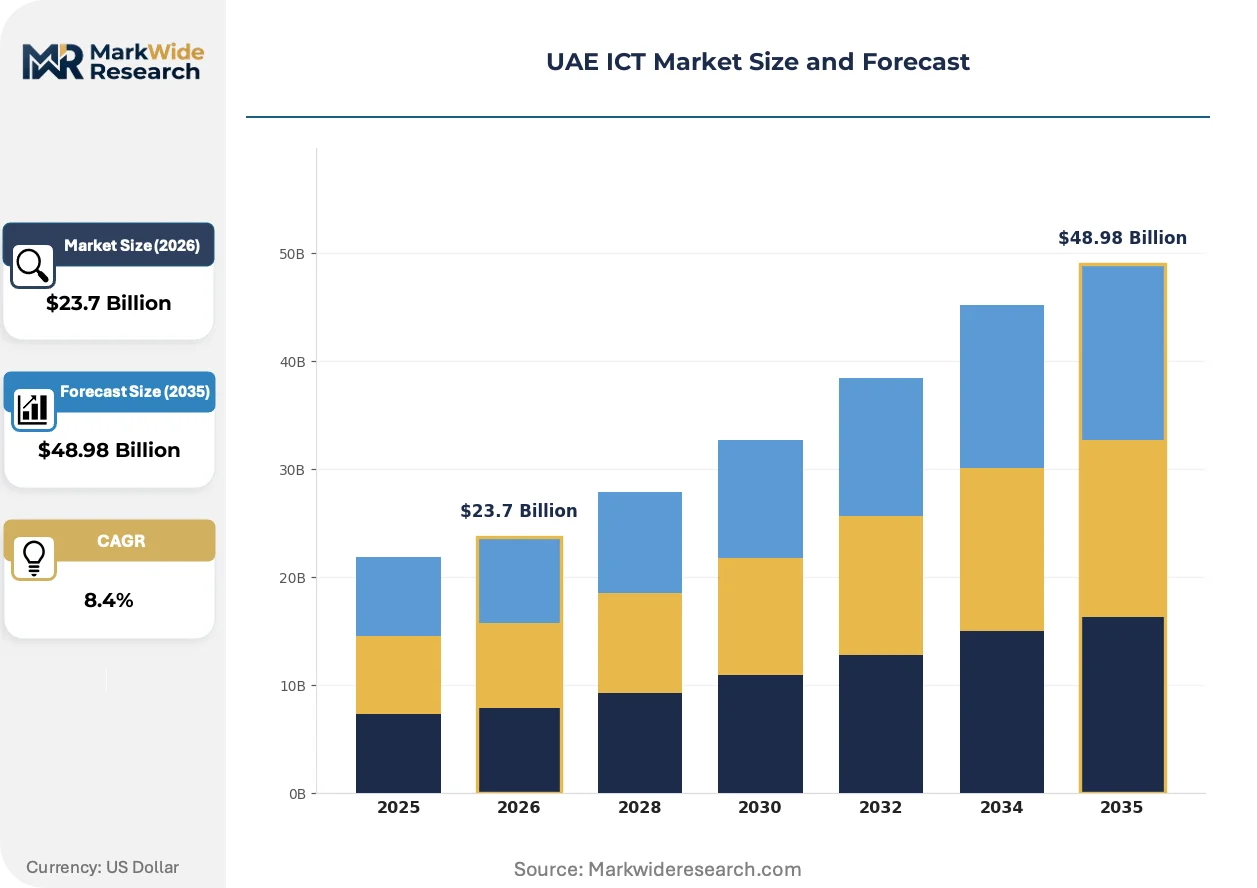
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions Deployment Model: On-Premise, Cloud, Hybrid, Edge Computing End User: Government, Enterprises, SMEs, Educational Institutions Technology: AI, IoT, Blockchain, Big Data |
| Companies Covered | Google LLC, Oracle Corporation, e& (Etisalat Group), SAP SE, Cisco Systems, Microsoft Corporation, IBM Corporation, Huawei Technologies, Amazon Web Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE ICT Market Evolving Landscape
Deployment architectures across the Emirates are fragmenting between centralized hyperscale consumption and distributed edge processing, with regulatory pressure accelerating this polarization beyond pure technical logic.
Edge computing infrastructure is bifurcating the UAE cloud market into latency-tolerant centralized workloads and mission-critical local processing. ADNOC and Emirates Airlines deploy on-premise GPU clusters for real-time predictive maintenance, bypassing public cloud routes. This split is compressing margins for undifferentiated IaaS providers while expanding systems integration opportunities for hybrid specialists.
MOHAP and the UAE Telecommunications and Digital Government Regulatory Authority have tightened data classification requirements for healthcare and financial services. Critical infrastructure operators must now demonstrate physical data center location within UAE territory and staff citizenship screening. Banks and insurers are responding by repatriating workloads from European cloud regions and negotiating dedicated local availability zones.
Subscription-based software procurement is displacing perpetual license purchases across federal and emirate-level entities. Dubai's Department of Finance mandates opex-only budgeting for new technology acquisitions, forcing legacy vendors to restructure pricing and delivery models. This behavioral shift concentrates buying power within centralized procurement frameworks and disadvantages smaller regional resellers lacking direct vendor relationships.
UAE ICT Market Segmentation
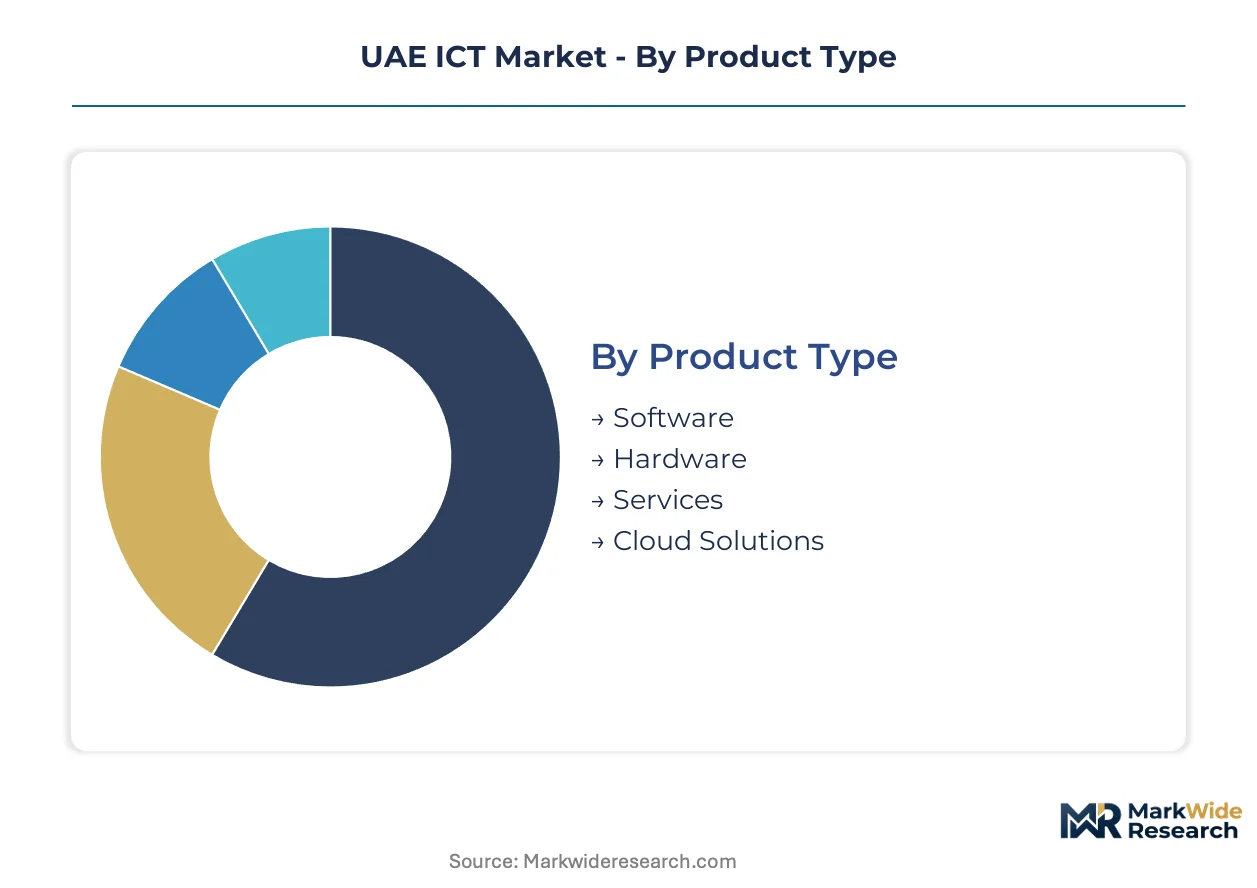
Segmentation in the UAE ICT market reveals how procurement mandates and infrastructure requirements reshape vendor priorities. Federal cloud-first policies and data residency rules create divergent margin profiles across product types and deployment models.
Product Type:
Margin pools concentrate where recurring revenue meets compliance complexity, particularly in subscription architectures serving regulated sectors.
- Cloud Solutions:Sovereign-compliant hyperscale and edge deployments dominate procurement frameworks under UAE National Informatization Plan mandates. Federal entities in Abu Dhabi and Dubai prioritize opex-only budgeting, compressing legacy license models while expanding multi-year subscription values.
- Software:Enterprise applications and API-native platforms capture spend as ministries replace 15-20 year-old ERP systems. MOHAP data residency requirements force healthcare operators toward localized SaaS instances with citizenship-screened support staff.
- Hardware:Server and storage procurement concentrates in fiber-plus-5G infrastructure builds across smart city corridors.
- Services:Systems integration and managed security offerings expand with multi-cloud orchestration complexity.
The dominant share belongs to Cloud Solutions, while Software is closing the gap fastest.
Deployment Model:
Customer procurement patterns split sharply between latency-tolerant centralized workloads and mission-critical edge processing.
- Edge Computing:On-rig GPU clusters at ADNOC drilling sites and autonomous logistics nodes in Dubai process terabyte-scale sensor data without cloud transit. Real-time inference requirements for predictive maintenance and traffic management command premium pricing over undifferentiated IaaS.
- Cloud:Hyperscale consumption grows where TRAI-aligned security certifications and 12-18 month approval timelines permit foreign provider participation.
- Hybrid:Government buyers demand workload portability across Azure, Oracle Cloud, and sovereign alternatives, straining vendor-agnostic DevOps capabilities.
- On-Premise:Legacy infrastructure persists in ministries resisting API connectivity, forcing expensive middleware development.
Edge Computing commands the steepest expansion trajectory as oilfield and logistics applications outpace centralized cloud growth.
End User:
Budget scale and compliance maturity determine service delivery economics across buyer categories.
- Government:Federal and emirate-level entities drive standardization through centralized procurement frameworks, concentrating buying power and disadvantaging regional resellers lacking direct vendor relationships.
- Enterprises:Large corporates in financial services and aviation repatriate workloads from European cloud regions to satisfy MOHAP physical location requirements.
- SMEs:Smaller businesses access subsidized digital transformation programs in Ras Al Khaimah and Fujairah, where government maturity lags Dubai and Abu Dhabi.
- Educational Institutions:Universities and training centers adopt collaboration platforms under federal interoperability mandates.
Government holds the dominant share, though Enterprises are gaining share fastest through compliance-driven infrastructure investment.
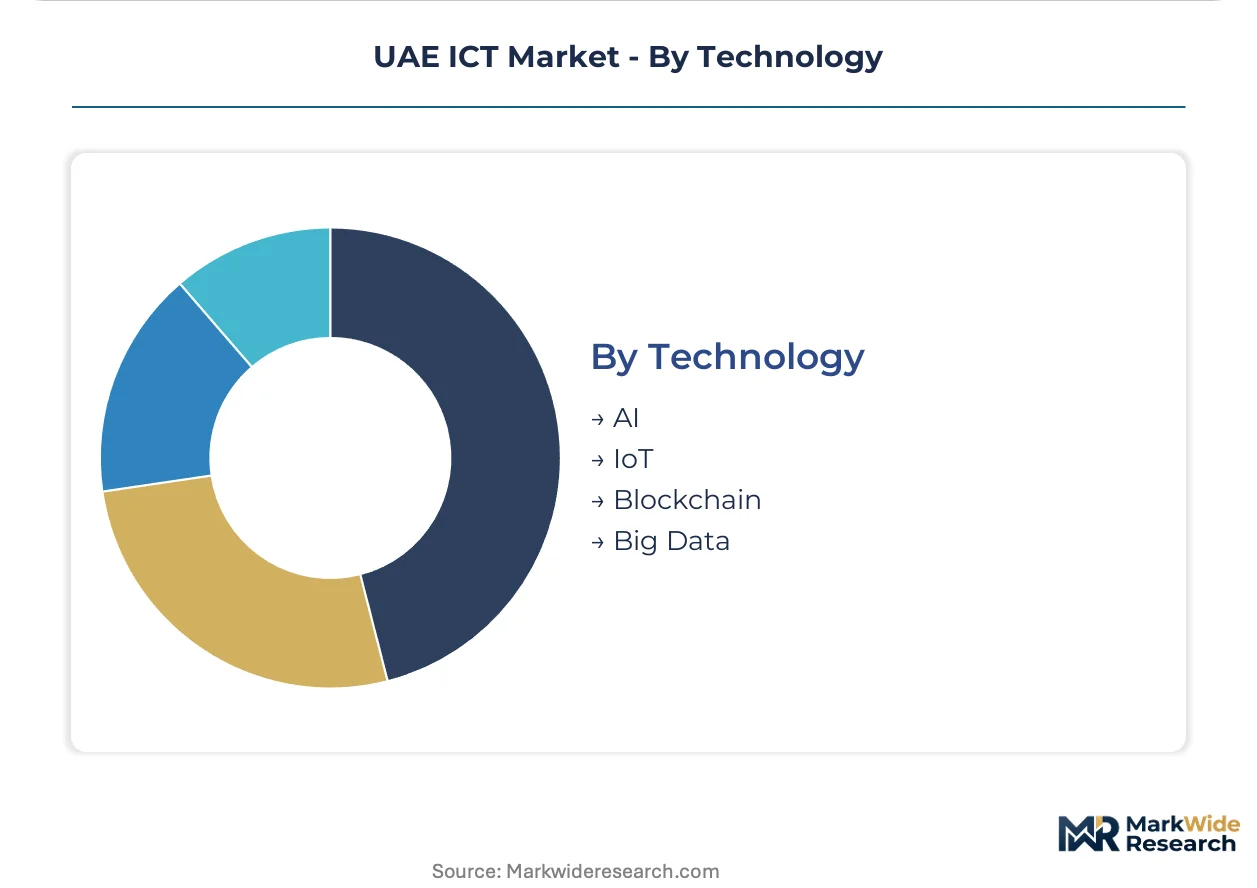
Technology:
Commercial viability depends on integration depth with existing government systems and clarity of regulatory pathways.
- AI:Predictive maintenance at ADNOC and traffic optimization in Dubai require localized inference capabilities. Pending federal AI ethics regulations will create compliance service revenue for consultancies interpreting bias-testing requirements.
- IoT:Sensor networks across smart city infrastructure generate data volumes that strain centralized processing architectures.
- Big Data:Analytics platforms support data-driven decision-making in federal digital transformation initiatives.
- Blockchain:Distributed ledger applications concentrate in trade finance and government identity verification pilots.
AI captures the dominant technology investment, with IoT expanding most quickly through sensor deployment in logistics and energy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP anchors the UAE ICT market through data residency mandates that reshape procurement across federal and emirate-level entities. The UAE Telecommunications and Digital Government Regulatory Authority enforces interoperable architectures that compress legacy refresh cycles. Seven emirates present divergent maturity profiles, with infrastructure investment clustering in commercial and administrative centers.
Dubai
Autonomous logistics corridors and AI-powered traffic management systems drive fiber-plus-5G deployment across the emirate. Dubai's Department of Finance mandates opex-only budgeting for new technology acquisitions, forcing subscription restructuring among enterprise vendors. Smart city infrastructure concentrates in Downtown Dubai and Dubai South, where sub-20-millisecond latency networks support real-time municipal operations.
Abu Dhabi
ADNOC's remote drilling operations generate terabyte-scale sensor data requiring on-rig GPU clusters with localized inference capabilities. The UAE National Informatization Plan directs federal procurement toward sovereign-cloud-compliant architectures across government entities. Masdar City and Yas Island host concentrated hyperscale facilities serving energy and aviation sectors.
Sharjah
Educational institutions and cultural institutions adopt collaboration platforms under federal interoperability mandates, expanding connectivity demand. The emirate's media free zone attracts content delivery network investments requiring localized edge nodes. University City clusters research computing infrastructure alongside training centers for cloud architecture certification.
Northern Emirates
Ras Al Khaimah and Fujairah lag Dubai and Abu Dhabi in digital government maturity, presenting first-mover advantages for localized service delivery partnerships. Subsidized digital transformation programs target SME adoption in manufacturing and tourism corridors. Fujairah's submarine cable landing stations position the emirate as a regional connectivity hub despite lagging enterprise software penetration.
UAE ICT Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers and telecommunications incumbents commanding federal procurement frameworks. The market structure reflects procurement concentration within centralized government buying centers, disadvantaging regional resellers lacking direct vendor relationships. Three archetypes dominate: sovereign-compliant hyperscalers, infrastructure-integrated carriers, and hybrid systems integrators. Competitive moves center on multi-cloud orchestration capabilities and edge computing partnerships for oilfield and logistics applications.
Within the sovereign-compliant tier, Microsoft Corporation and Oracle Corporation exemplify contrasting approaches to federal contract capture. Microsoft leverages its hyperscale Azure footprint across Emirates-based government entities, while Oracle competes through database-to-cloud migration services aligned with regional compliance requirements. Huawei Technologies occupies a distinct position in infrastructure deployment despite sourcing restrictions affecting 5G radio equipment procurement. These three anchors illustrate how geopolitical positioning and technical specialization determine market access under TRAI-aligned security frameworks.
| Leading Market Players |
|---|
| Google LLC |
| Oracle Corporation |
| e& (Etisalat Group) |
| SAP SE |
| Cisco Systems |
| Microsoft Corporation |
| IBM Corporation |
| Huawei Technologies |
| Amazon Web Services |
| Others |
Value Network & Pricing Analysis
Hyperscale facility utilization rates above 85 percent in Dubai and Abu Dhabi compress marginal costs for cloud providers while establishing price floors that regional resellers cannot match. This scale concentration reinforces subscription-only procurement mandates across federal entities and squeezes undifferentiated hardware vendors from margin pools.
Pricing Analysis
Abu Dhabi commands 15-20 percent premiums over Ras Al Khaimah for equivalent sovereign-compliant cloud services due to proximity to federal procurement centers and certified data center density. The dominant pricing structure is subscription-based SaaS with tiered service levels separating hyperscale capacity from edge node deployments. Price differentiation rests on data residency certification grade and citizenship-screened support staff availability. Cost compression in standardized IaaS is intensifying because federal buyers consolidate purchasing through centralized frameworks. SMEs in northern emirates exhibit highest price sensitivity, while ADNOC and Emirates Airlines prioritize latency guarantees over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites submarine cable landing station economics for UAE connectivity, concentrating international bandwidth flows through Fujairah and Dubai. Equipment supply draws from China for 5G radio units, Taiwan for server-grade semiconductors, and USA for enterprise software licenses. Single-source vulnerability in submarine cable landing rights creates chokepoint exposure for Emirates-based carriers. Distribution runs through hyperscale provider direct sales organizations and systems integrators holding federal security clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
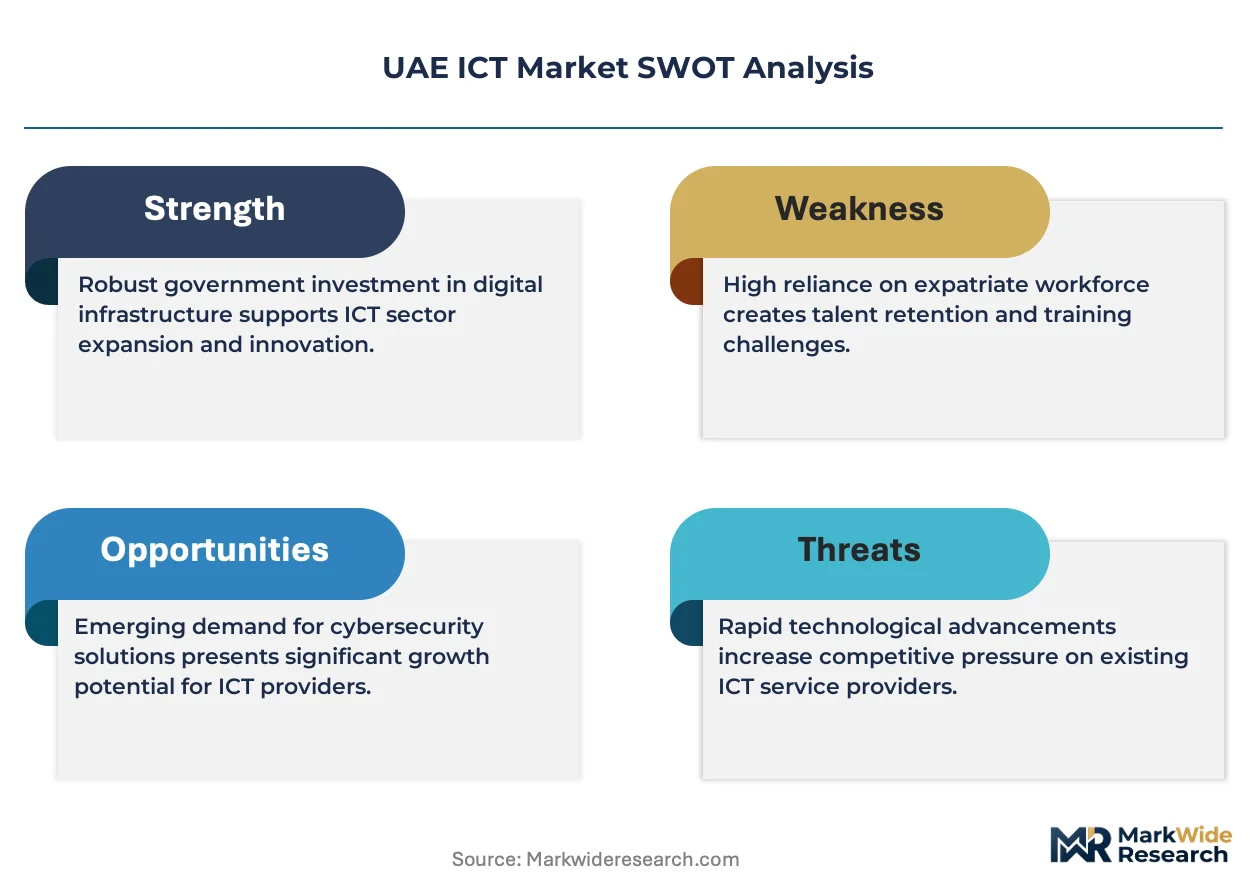
UAE ICT sits in early-cycle expansion as sovereign cloud mandates displace perpetual license models and edge computing penetrates oilfield operations. Federal data residency requirements create structural tailwinds for localized infrastructure deployment.
For Market Incumbents: Compound hyperscale capacity advantages by securing additional federal availability zone certifications before competitors complete TRAI-aligned security approval timelines. Defend position against emerging sovereign cloud providers through vertical integration into edge node manufacturing partnerships with ADNOC. Prioritize API-native platform development to capture legacy ERP replacement cycles across ministries. For New Entrants and Emerging Players: Differentiate on oilfield edge computing specialization where ADNOC's terabyte-scale sensor processing demands outpace incumbent response capabilities. Target Ras Al Khaimah and Fujairah government digitization programs offering subsidized SME transformation budgets with limited vendor competition. Pursue channel partnerships with Emirates-based systems integrators holding existing federal procurement relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid cloud orchestration specialists with proven multi-vendor deployment credentials across Azure, Oracle Cloud, and sovereign alternatives. Long-term viability hinges on regulatory compliance capabilities as AI governance frameworks materialize. Acquisition targets should demonstrate physical UAE data center presence and citizenship-screened technical staff. Watch federal AI ethics regulation publication as inflection indicator for compliance service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | TRAI-aligned security approval unlocks critical infrastructure eligibility for federal contracts. |
| Edge Node Partnership | ADNOC on-rig GPU deployment captures oilfield predictive maintenance revenue pools. |
| Multi-Cloud Orchestration Platform | Workload portability across Azure, Oracle Cloud, and sovereign providers satisfies government procurement mandates. |
| API-Native ERP Migration | Federal interoperability requirements force legacy system replacement with subscription architectures. |
| AI Governance Compliance Service | Pending federal ethics regulations create interpretive consulting revenue for bias-testing requirements. |
Research Methodology
A standing panel of federal IT procurement officers, hyperscale cloud platform engineers, systems integration specialists, and ADNOC digital transformation leads provided ongoing calibration against secondary validation. Primary interviews combined with UAE Telecommunications and Digital Government Regulatory Authority policy filings, hyperscaler capex disclosures, MOHAP data classification directives, and federal budget appropriation records enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment model, organization size, vertical sector, integration complexity, and regional adoption pattern dimensions. CAGRs were derived from segment-level build-ups incorporating federal cloud-first mandate penetration curves and edge computing adoption rates in oilfield operations.
The analysis sits within stated boundaries; outcomes outside sustained federal digital transformation funding and stable TRAI-aligned regulatory frameworks would require recalibration. Forecasts reflect assumptions regarding procurement mandate continuity and hyperscale facility commissioning timelines. Practitioners should keep alternative scenarios live as AI governance regulations and geopolitical equipment sourcing restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Global Website Builders Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Utility Cases Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Document Management System Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
South Korea Digital Twin Market