
 Global Continuous Delivery Market | 2026-2036
Global Continuous Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Delivery Market Foresight
Modular packaging of CI/CD toolchains is pivoting buyer procurement toward composable platform stacks. Microsoft Corporation leverages its Azure DevOps ecosystem to anchor enterprise accounts across hybrid deployment environments. Atlassian Corporation specializes in developer-centric workflow orchestration that competes with broader platform plays from IBM Corporation.
Continuous Delivery encompasses the automated pipeline infrastructure that moves code changes through build, test, and deployment stages using version control triggers, container orchestration, and infrastructure-as-code protocols. Its primary commercial purpose is to compress release cycles while maintaining production stability through automated rollback mechanisms. Cloud-based deployment leads solution delivery, though release orchestration captures expanding margin pools as enterprises seek governance across multi-cloud estates. Large enterprises dominate end-user demand, yet independent software vendors represent the fastest-growing adoption segment as product companies internalize DevOps capabilities.
The EU AI Act, GDPR, and ISO 27001 frameworks impose audit-trail and explainability requirements that shape procurement criteria for deployment automation platforms. FDA 21 CFR Part 11 in the United States and BIS cybersecurity guidelines in India extend compliance burdens to regulated sectors, restricting market access for vendors lacking certification depth. Stakeholders must monitor how sovereignty-driven data residency rules fragment cloud architecture choices across jurisdictions.
Market Dynamics
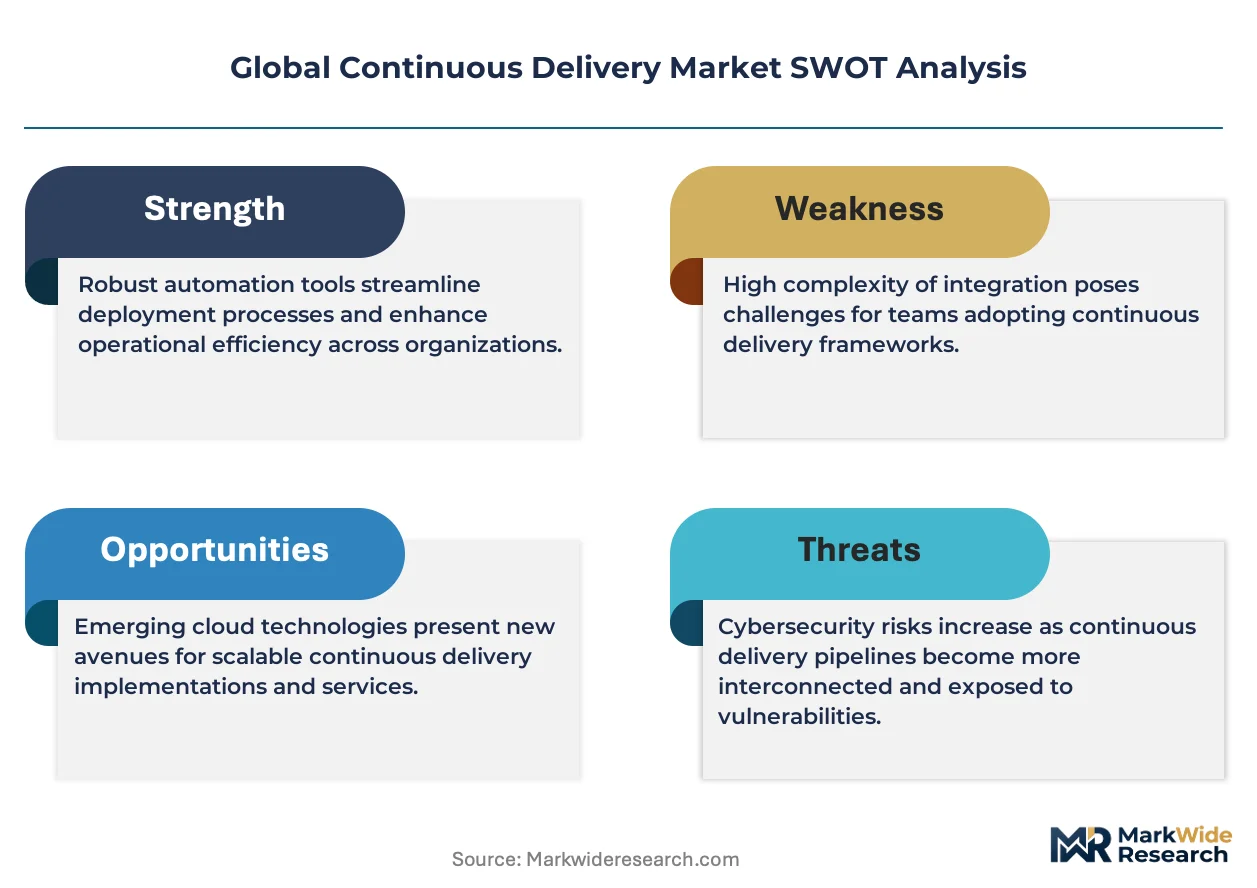
Pipeline modularization is fragmenting procurement decisions across financial services and healthcare sectors, forcing platform vendors to disaggregate monolithic suites into interoperable components that buyers compose against ISO 27001 and EU AI Act audit requirements.
Growth Catalysts
- EU AI Act Compliance Mandates:Financial institutions in Germany and France must maintain immutable deployment logs, accelerating replacement of legacy script-based release tools with auditable orchestration platforms.
- Container Orchestration Maturation:Kubernetes-native deployment patterns have standardized infrastructure abstraction, lowering adoption barriers for mid-market software vendors building internal DevOps capabilities.
- India's BIS Cybersecurity Guidelines:Domestic banks and payment processors face mandatory security certification for automation tools, creating regulated demand for compliant CI/CD infrastructure.
Market Restraints
- Cloud Concentration Risk:Three hyperscalers control over 70% of underlying compute infrastructure for deployment automation, exposing buyers to egress cost volatility and service continuity vulnerabilities.
- Specialized Talent Scarcity:Site reliability engineering and platform engineering roles command 40-60% salary premiums over traditional IT operations, constraining enterprise scaling velocity.
- Legacy Integration Friction:Mainframe and AS/400 systems in US insurance and banking retain critical batch processes that resist containerization, forcing hybrid complexity that slows pipeline consolidation.
Strategic Opportunities
- FDA 21 CFR Part 11 Automation:Pharmaceutical manufacturers require validated electronic records for software deployments in GxP environments, opening specialized vertical platforms with pre-built compliance templates.
- Edge Deployment Orchestration:Manufacturing and energy operators need synchronized release coordination across thousands of distributed nodes, extending continuous delivery beyond centralized cloud estates.
- Internal Developer Platform Convergence:Platform engineering teams are consolidating fragmented toolchain procurement under unified self-service portals, creating consolidation plays for vendors with broad integration depth.
Industry Challenges
- Multi-Cloud Governance Complexity:Enterprises operating across AWS, Azure, and Google Cloud struggle to maintain consistent policy enforcement and cost attribution across divergent native deployment services.
- Security Scanning Pipeline Latency:Shift-left mandates embed SAST and DAST tools into pre-commit hooks, extending build durations by 15-40 minutes and triggering developer workarounds that undermine compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Delivery Market |
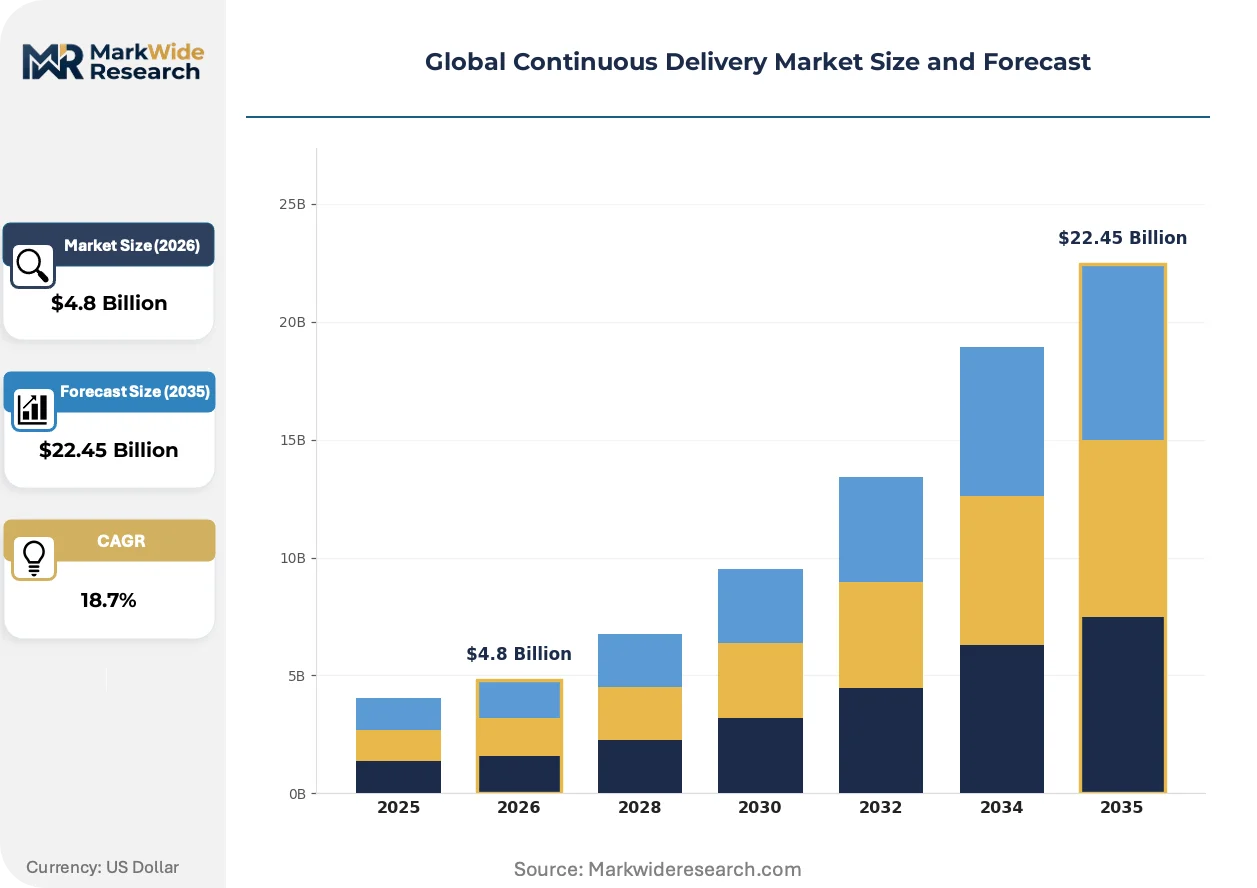
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud Solution: Build Automation, Release Orchestration, Configuration Management, Monitoring & Logging, Testing Automation Application: Financial Services, Telecommunications, Software Development, Media & Entertainment, E-Commerce, Government Agencies End User: Startups, Small & Medium Enterprises, Large Enterprises, Independent Software Vendors, System Integrators |
| Companies Covered | Microsoft Corporation, IBM Corporation, Atlassian Corporation, CloudBees Inc., Google LLC, Broadcom Inc., XebiaLabs, Accenture PLC, Clarive Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Delivery Market Shifts & Advancements
Deployment automation is converging with policy-as-code and AI-assisted remediation, compressing the gap between commit and production while embedding governance checkpoints that previously required manual approval gates.
GitOps reconciliation loops are electrifying infrastructure state management by replacing imperative provisioning with declarative desired-state enforcement. Platform teams at telecommunications and logistics operators are adopting Flux and ArgoCD controllers to automate drift detection and self-healing across Kubernetes clusters. This pattern is compressing mean-time-to-recovery for configuration incidents from hours to minutes while reducing human access to production environments.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for high-risk AI systems deployed through automated pipelines. Medical device manufacturers and credit scoring platforms must now embed documentation generation and bias testing into release workflows before production deployment. German automotive suppliers and Dutch fintech operators are restructuring pipeline architectures to capture model provenance and performance telemetry for regulatory inspection.
Independent software vendors are displacing enterprise IT departments as the primary procurement authority for DevOps tooling, with product engineering teams directly selecting and expensing pipeline components through cloud marketplaces. This pattern concentrates purchasing influence with developers rather than infrastructure architects, favoring vendors with frictionless onboarding and consumption-based pricing over traditional enterprise sales cycles. The shift is most visible among Series B and C software companies in the United States and United Kingdom building platform teams without dedicated operations headcount.
Global Continuous Delivery Market Segmentation
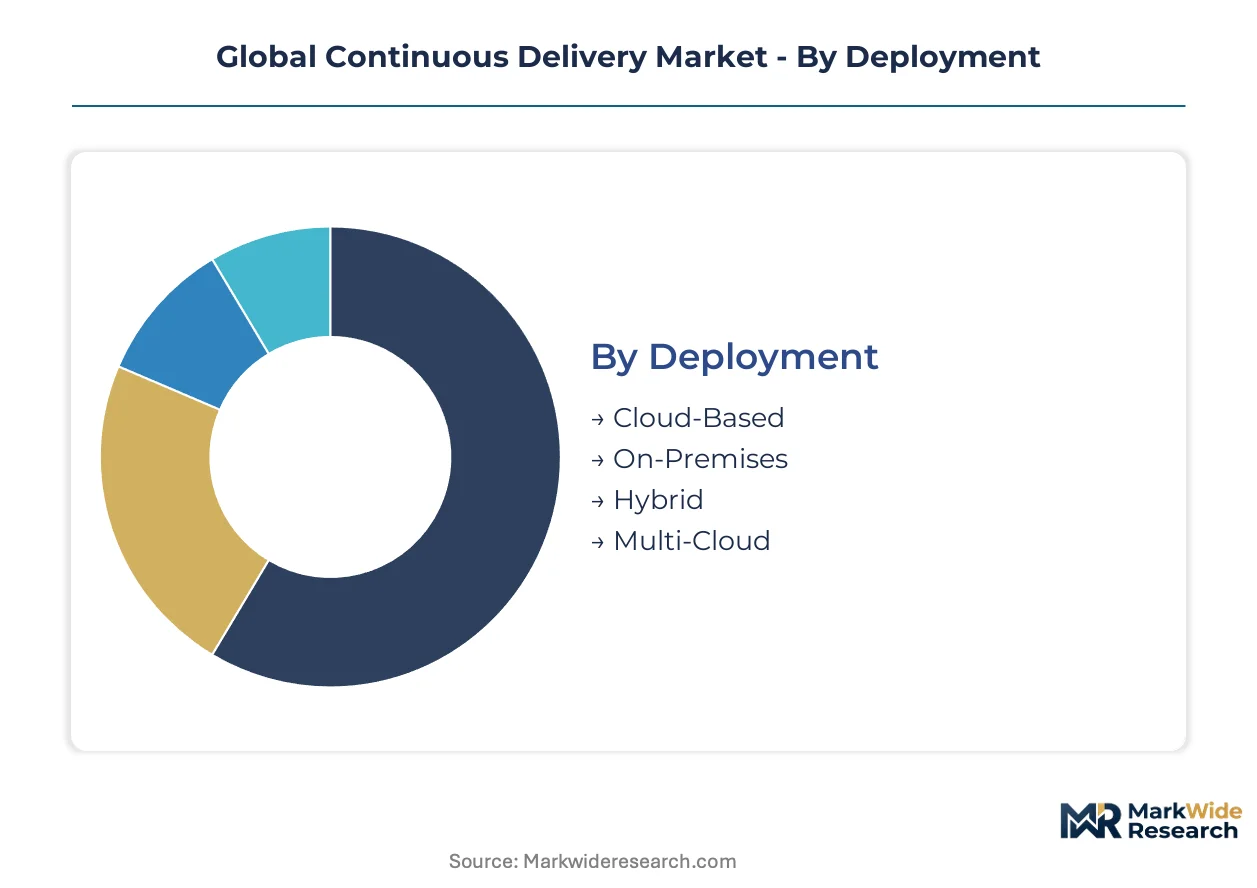
Continuous Delivery procurement varies sharply by infrastructure posture, compliance burden, and release velocity requirements. Buyers segment themselves through deployment topology choices, solution stack priorities, and organizational scale thresholds that dictate platform complexity tolerance.
Deployment:
Cost tier separates buyers in this category, with hyperscaler commitment levels and data sovereignty obligations driving topology selection.
- Cloud-Based:Fully managed deployment pipelines leverage hyperscaler-native DevOps services with consumption-based pricing. Financial services firms in Germany and the United States concentrate demand here, compelled by EU AI Act audit-trail mandates and FDA 21 CFR Part 11 validation requirements that favor centralized logging infrastructure.
- Hybrid:Split workloads between on-premises build farms and cloud-based artifact repositories, preserving sensitive compilation environments while enabling elastic test scaling. Pharmaceutical manufacturers and defense contractors in the United States and Switzerland favor this pattern to satisfy validated systems requirements without surrendering operational control.
- On-Premises:Self-hosted pipeline infrastructure with air-gapped execution environments for classified or regulated workloads.
- Multi-Cloud:Orchestration layers abstracting AWS, Azure, and Google Cloud deployment targets through unified control planes.
Cloud-Based deployments lead volumes today; Multi-Cloud configurations are gaining share fastest.
Solution:
Application maturity distinguishes buyers, with release sophistication determining which automation layer absorbs procurement investment.
- Release Orchestration:Coordinates promotion workflows across staging environments with approval gates and rollback triggers. Telecommunications operators in India and Germany prioritize this capability to manage thousands of microservice deployments while satisfying BIS cybersecurity guidelines and EU AI Act documentation requirements.
- Testing Automation:Embeds SAST, DAST, and contract testing into CI pipelines with quality gate enforcement. E-commerce platforms and fintech startups in the United States and United Kingdom concentrate demand here, driven by shift-left mandates and developer self-service expectations.
- Build Automation:Compiles source artifacts, manages dependencies, and produces container images through declarative pipeline definitions.
- Configuration Management:Maintains infrastructure state through version-controlled manifests and drift detection.
- Monitoring & Logging:Captures deployment telemetry, audit trails, and performance baselines for pipeline optimization.
Release Orchestration leads volumes today; Testing Automation is climbing the fastest.
Application:
Regulatory exposure stratifies buyers, with audit intensity and release frequency creating divergent platform requirements.
- Financial Services:Banks, insurers, and payment processors deploy mission-critical updates through validated pipelines with immutable audit logs. German and French institutions under EU AI Act high-risk system classifications drive specialized procurement for algorithmic impact assessment integration.
- Software Development:Product companies building SaaS applications internalize DevOps capabilities through platform engineering teams. Independent software vendors in the United States and United Kingdom represent the steepest expansion trajectory as Series B and C companies build release infrastructure without dedicated operations headcount.
- Telecommunications:Network function virtualization and edge orchestration demand synchronized deployment across distributed infrastructure.
- E-Commerce:Peak-load scaling requirements drive automated rollback and canary release sophistication.
- Government Agencies:FedRAMP and sovereign cloud mandates constrain vendor selection to certified providers.
- Media & Entertainment:Content delivery pipelines require asset-heavy build processes with geographic distribution optimization.
Financial Services leads volumes today; Software Development is expanding most quickly.
End User:
Organizational scale and technical staffing depth determine platform complexity tolerance and procurement authority location.
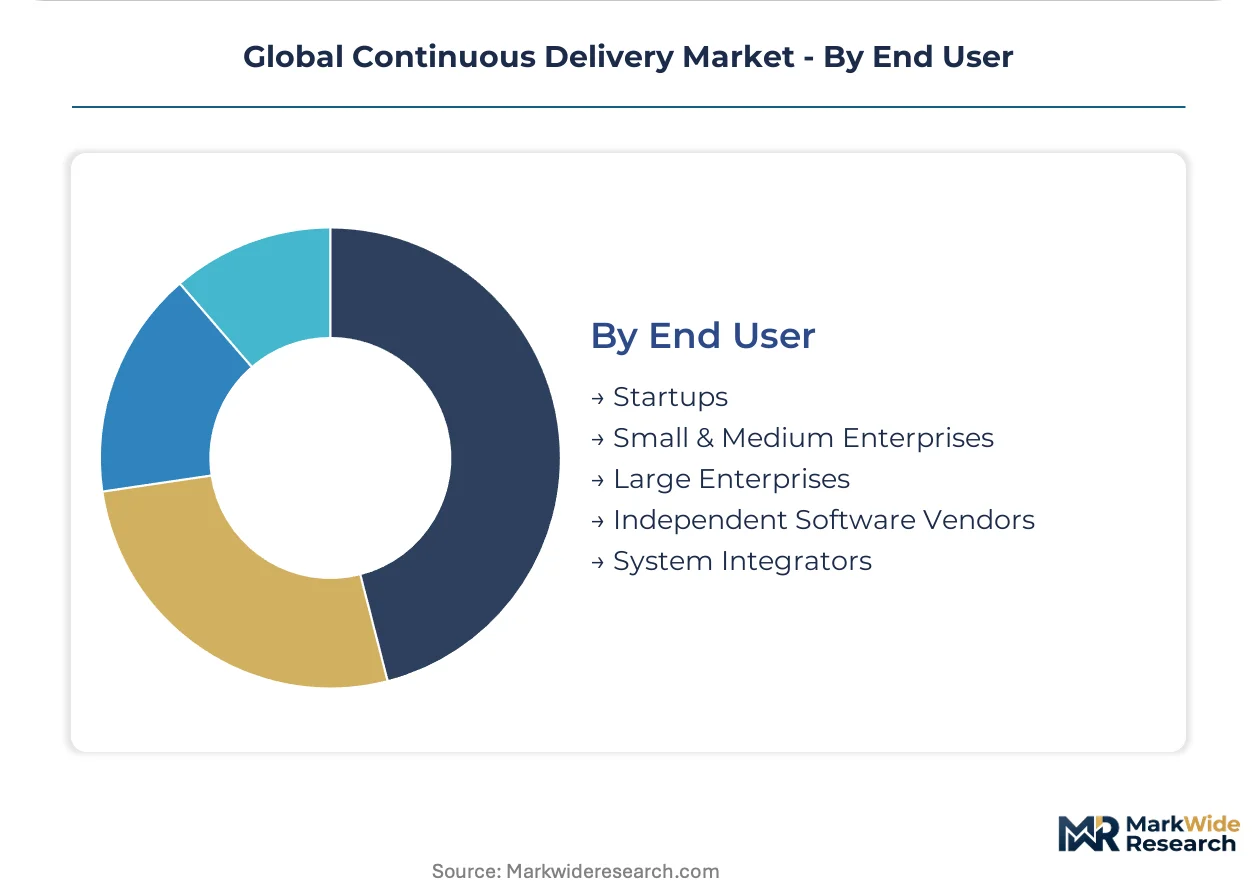
- Large Enterprises:Centralized platform engineering teams consolidate fragmented toolchain procurement under internal developer portals. Manufacturing and energy conglomerates in the United States and Germany anchor this segment, pursuing edge deployment orchestration across thousands of distributed nodes.
- Independent Software Vendors:Product engineering teams directly select and expense pipeline components through cloud marketplaces, bypassing traditional enterprise procurement. This segment concentrates among venture-backed software companies in the United States and United Kingdom.
- Small & Medium Enterprises:Managed DevOps services and simplified SaaS pipelines reduce operational overhead.
- Startups:GitHub Actions and GitLab CI default choices with minimal customization requirements.
- System Integrators:Consulting firms packaging deployment automation into client transformation engagements.
Large Enterprises lead volumes today; Independent Software Vendors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Continuous Delivery infrastructure originated in Silicon Valley's hyperscaler ecosystems before diffusing to financial centers in London and Frankfurt, then accelerating through India's software services corridor as global enterprises sought distributed engineering capacity.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina drive specialized demand for FDA 21 CFR Part 11 validated deployment pipelines, while defense contractors in Virginia and California pursue FedRAMP-certified orchestration platforms for classified workloads. The FDA's electronic records requirements force GxP-compliant automation investments that exceed standard enterprise tooling costs by significant margins.
Germany
Automotive suppliers in Stuttgart and Munich restructure CI/CD architectures to embed EU AI Act algorithmic impact assessments for autonomous driving and credit scoring systems. The KBA and BSI jointly enforce cybersecurity certification that restricts vendor selection to providers with immutable audit-trail capabilities and sovereign cloud data residency options.
India
Bangalore and Hyderabad host platform engineering teams at Series B and C software companies that bypass traditional procurement through direct cloud marketplace purchases. RBI and BIS cybersecurity guidelines for payment processors mandate security certification for automation tools, creating regulated demand that favors compliant domestic and international vendors equally.
United Kingdom
London's fintech cluster embeds shift-left security scanning into pre-commit hooks, extending build durations but satisfying FCA operational resilience mandates for critical payment infrastructure. Manchester and Edinburgh follow with platform engineering consolidations that unify fragmented toolchain procurement under internal developer portals.
Switzerland
Zurich-based pharmaceutical and private banking institutions favor hybrid deployment topologies that preserve on-premises build farms for sensitive compilation while leveraging cloud artifact repositories for elastic test scaling. Swissmedic validation requirements and FINMA operational risk frameworks constrain vendor selection to providers with proven GxP and banking compliance depth.
Global Continuous Delivery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across release orchestration sophistication, with governance-heavy financial services contracts commanding pricing multiples over developer-centric SaaS tiers. The vendor base organizes into three strategic archetypes: hyperscaler-anchored platform suites, specialized release orchestration vendors, and consulting-integrated transformation partners. Consolidation pressures favor M&A activity targeting Kubernetes-native tooling and vertical compliance templates, while strategic partnerships between automation vendors and sovereign cloud providers accelerate under data residency fragmentation.
Within the hyperscaler-anchored tier, Microsoft Corporation and Google LLC exemplify platform ecosystem strategies that embed deployment automation within broader cloud service consumption. IBM Corporation occupies a position bridging legacy enterprise integration with modern container orchestration, reflecting the hybrid complexity that persists in regulated industries. Atlassian Corporation represents the developer-centric workflow archetype that competes through frictionless onboarding and consumption-based pricing models favored by independent software vendors.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Atlassian Corporation |
| CloudBees Inc. |
| Google LLC |
| Broadcom Inc. |
| XebiaLabs |
| Accenture PLC |
| Clarive Software |
| Others |
Supply & Pricing Matrix
Captive integration of hyperscaler infrastructure anchors supply positions and pricing power for deployment automation platforms, with AWS, Azure, and Google Cloud controlling underlying compute capacity that dictates cost structures for orchestration vendors serving financial services and pharmaceutical buyers.
Pricing Analysis
Consumption-based SaaS tiers with enterprise-grade compliance premiums dominate pricing structures, separating validated GxP-ready pipelines from standard developer tooling. Price differentiation rests on ISO 27001 certification depth and EU AI Act audit-trail capabilities. Cost compression in mid-market tiers intensifies as independent software vendors bypass procurement committees through direct cloud marketplace purchases. Large enterprises exhibit lowest price sensitivity due to regulatory mandates, while Series B software companies demand frictionless onboarding at minimal per-seat costs.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler compute concentration in the United States, Ireland, and Singapore, where AWS, Microsoft Azure, and Google Cloud anchor global infrastructure for deployment automation. The supply chain draws from specialized Kubernetes distribution providers, security scanning engine vendors, and sovereign cloud operators. Tariff exposure on cross-border data transfers threatens margin stability for multi-cloud orchestration platforms. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and systems integrators embedding tooling into transformation engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement authority shifting toward developers who prioritize compliant, auditable pipelines over lowest-cost alternatives.
For Market Incumbents: Extend platform engineering consolidation plays by acquiring Kubernetes-native tooling specialists before independent software vendors internalize DevOps capabilities. Reinforce FedRAMP and EU AI Act certification depth as cloud-agnostic orchestration becomes table stakes. Defend against hyperscaler-native DevOps services by embedding policy-as-code governance that exceeds baseline compliance automation. For New Entrants and Emerging Players: EU AI Act high-risk system classifications in Germany and France open a window for specialized vertical platforms with pre-built algorithmic impact assessment templates. Target pharmaceutical manufacturers in New Jersey and North Carolina requiring FDA 21 CFR Part 11 validated electronic records. Pursue edge deployment orchestration for manufacturing and energy operators with distributed node synchronization needs. Lead with consumption-based pricing and frictionless GitOps onboarding to bypass entrenched procurement cycles. For Investors and Strategic Acquirers: Roll-up economics work for compliance-heavy release orchestration specialists because regulatory fragmentation creates durable moats against hyperscaler commoditization. Platform engineering teams at Series B and C software companies represent the fastest-consolidating demand pool. Monitor BIS cybersecurity guideline enforcement in India as an inflection signal for regulated CI/CD infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Compliance Specialist | Captures FDA 21 CFR Part 11 and EU AI Act template libraries for pharmaceutical and financial services verticals. |
| Strategic Partnership with Sovereign Cloud Provider | Addresses German KBA and BSI data residency mandates for automotive suppliers restructuring CI/CD architectures. |
| Platform Integration with GitOps Controllers | Compresses mean-time-to-recovery for telecommunications operators adopting Flux and ArgoCD reconciliation loops. |
| Geographic Expansion into India | Aligns with RBI and BIS cybersecurity guidelines creating regulated demand for certified automation tools. |
| Product Launch for Edge Orchestration | Serves manufacturing and energy conglomerates synchronizing releases across thousands of distributed nodes. |
Research Methodology
Bottom-up platform engineering team modeling reconciled against top-down hyperscaler DevOps service tracking forms the analytical core of this study. Primary interviews with CTOs, platform engineering leads, IT procurement officers, and channel integration specialists combined with secondary validation from SEC filings, hyperscaler capex disclosures, cloud marketplace transaction data, and regulatory certification databases. Triangulation across stakeholder inputs and documented deployment patterns ensures coverage of both enterprise consolidation trends and independent software vendor procurement shifts.
Historical trendline analysis of release orchestration adoption across financial services, pharmaceutical, and software development verticals established baseline growth parameters. Segmentation dimensions modeled include deployment topology, solution stack layer, application vertical, and organizational scale tier. CAGRs derived from regression analysis against compliance mandate timelines and container orchestration maturation curves. Industry-specific inputs encompass EU AI Act implementation schedules, FDA validation requirement updates, and BIS cybersecurity guideline enforcement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated sovereign cloud fragmentation or hyperscaler pricing volatility. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, talent availability for site reliability engineering roles, and legacy system containerization feasibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Data Broker Market