
 Asia-Pacific Digital Pen Market | 2026-2036
Asia-Pacific Digital Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Pen Market Analytics
Enterprise professionals are bifurcating from consumer artists as the dominant buyer archetype in the Asia-Pacific Digital Pen Market. Wacom Co., Ltd. leverages its pressure-sensitive technology heritage to dominate premium creative workflows. Samsung Electronics Co., Ltd. anchors large-format display-integrated stylus ecosystems across Korean corporate deployments. Hanvon Technology Co. Ltd. competes on cost-optimized optical digitization for China's education procurement channels.
A digital pen is an electronic input device combining positional sensors, microprocessors, and wireless transmitters to capture handwriting or drawing strokes and convert them into digital data for display, storage, or transmission. Active pens incorporate powered components such as Bluetooth radios and pressure transducers to enable palm rejection, tilt recognition, and sub-millimeter positional accuracy for professional annotation and design applications. Active pens command the highest margin pools in the product type dimension due to their chip-intensive architecture and firmware customization requirements. Capacitive technology leads volume shipments across the technology dimension, though pressure-sensitive modules are capturing share in art and design applications where line-weight fidelity determines purchasing decisions.
China's MIIT enforces GB standards for electromagnetic compatibility and radio transmission in stylus devices, while Japan's METI coordinates JIS interoperability requirements with domestic electronics manufacturers. India's TRAI digital literacy mandates and BIS certification for electronic learning tools are expanding institutional procurement channels. Stakeholders must monitor how China's SAMR interprets dual carbon goals into battery and materials compliance for wireless pen accessories.
Market Dynamics
Enterprise workflow digitization across financial services and legal sectors is compressing replacement cycles for ink-to-digital capture systems, while China's component clustering around Shenzhen and Shanghai tightens supply-side coordination costs.
Growth Catalysts
- TRAI Digital Literacy Mandates:India's institutional procurement channels for electronic learning tools are expanding as BIS certification requirements standardize quality benchmarks for education-sector deployment.
- Pressure-Sensitive Module Adoption:Art and design applications where line-weight fidelity determines purchasing decisions are pulling high-margin active pen architectures into professional creative workflows.
- Yangtze River Delta Clustering:Component supplier concentration around Shanghai and Shenzhen reduces logistics friction for OEM assembly operations serving domestic and export demand.
Market Restraints
- GB Standards Compliance Costs:China's MIIT electromagnetic compatibility and radio transmission requirements impose certification overhead that disadvantages smaller regional assemblers without dedicated testing facilities.
- Active Pen Chip Dependency:The powered component architecture incorporating Bluetooth radios and pressure transducers ties margin pools to semiconductor foundry capacity concentrated in Taiwan and South Korea.
- Capacitive Technology Substitution:Lower-cost passive stylus alternatives for basic annotation tasks limit pricing power at the volume-shipment tier of the product mix.
Strategic Opportunities
- Indian Education Procurement:State-level digital classroom initiatives under TRAI coordination create institutional demand corridors underserved by current distributor networks.
- Healthcare Annotation Workflows:Medical imaging and clinical documentation applications represent an emerging vertical where palm rejection and sub-millimeter accuracy command premium positioning.
- Dual Carbon Battery Compliance:SAMR's interpretation of environmental goals into materials standards creates first-mover advantage for suppliers with recyclable power cell architectures.
Industry Challenges
- Firmware Customization Talent Scarcity:The chip-intensive architecture of active pens requires embedded systems engineers capable of integrating pressure transducer algorithms with wireless transmission protocols.
- JIS-MIIT Interoperability Testing:Divergent certification timelines between Japan's METI coordination requirements and China's GB standards delay synchronized product launches across Northeast Asia markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Pen Market |
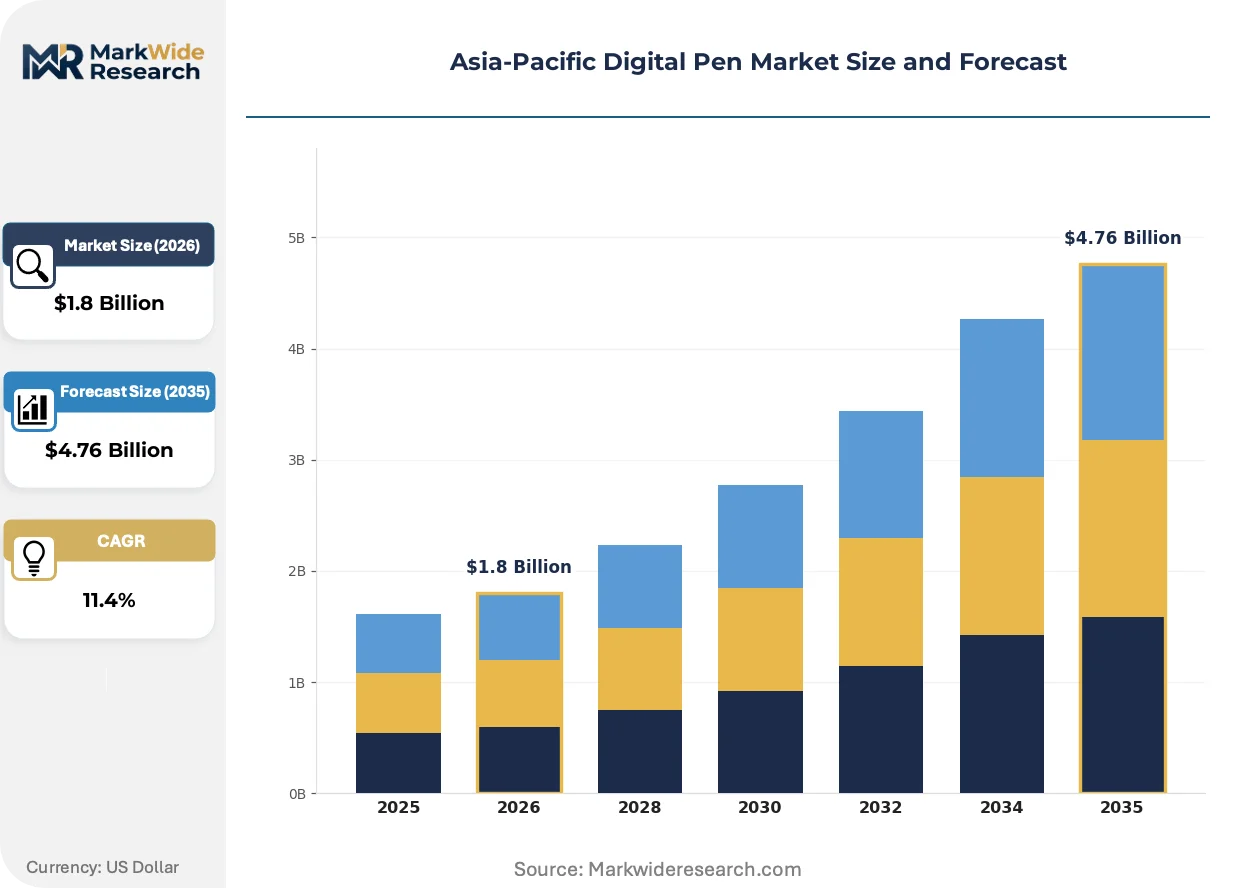
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pens, Passive Pens, Smart Pens, Stylus Pens End User: Students, Professionals, Artists, Designers Technology: Capacitive, Optical, Pressure-Sensitive, Bluetooth Application: Education, Art & Design, Note Taking, Graphic Design |
| Companies Covered | Wacom Co., Ltd., Canon Inc., Samsung Electronics Co., Ltd., Hanvon Technology Co. Ltd., Toshiba Corporation, NeoLAB Convergence Inc., Apple Inc., Huion Animation Technology Co., Ltd., HP Development Company L.P., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Pen Market Evolving Landscape
Stylus technology is bifurcating between premium active architectures and cost-optimized passive alternatives, with regulatory compliance emerging as a competitive differentiator rather than a baseline requirement.
Pressure-sensitive digitization is fragmenting the creative professional segment into specialized sub-niches. Active pens incorporating powered tilt recognition and sub-millimeter positional accuracy now serve architectural draftsmen, industrial designers, and medical illustrators with divergent grip ergonomics and surface compatibility requirements. Wacom's heritage dominance faces erosion as Korean display-integrated ecosystems and Chinese optical digitization alternatives capture workflow-specific deployments.
China's MIIT enforcement of GB electromagnetic compatibility standards is compressing import windows for non-compliant accessories. The radio transmission specifications now require pre-market testing at designated Shenzhen laboratories, adding 6-8 week lead times for regional distributors. Japanese electronics manufacturers with established METI-JIS coordination protocols are adapting firmware stacks to dual-certify products for simultaneous China-Japan release.
Institutional procurement through education ministries is displacing retail channel dominance across India and Southeast Asia. State tenders for digital classroom bundles now specify stylus compatibility with mandated tablet platforms, compressing vendor selection to pre-qualified OEMs with BIS-certified supply chains. Korean corporate deployments of large-format display ecosystems similarly favor integrated stylus procurement over aftermarket accessory purchases.
Asia-Pacific Digital Pen Market Segmentation
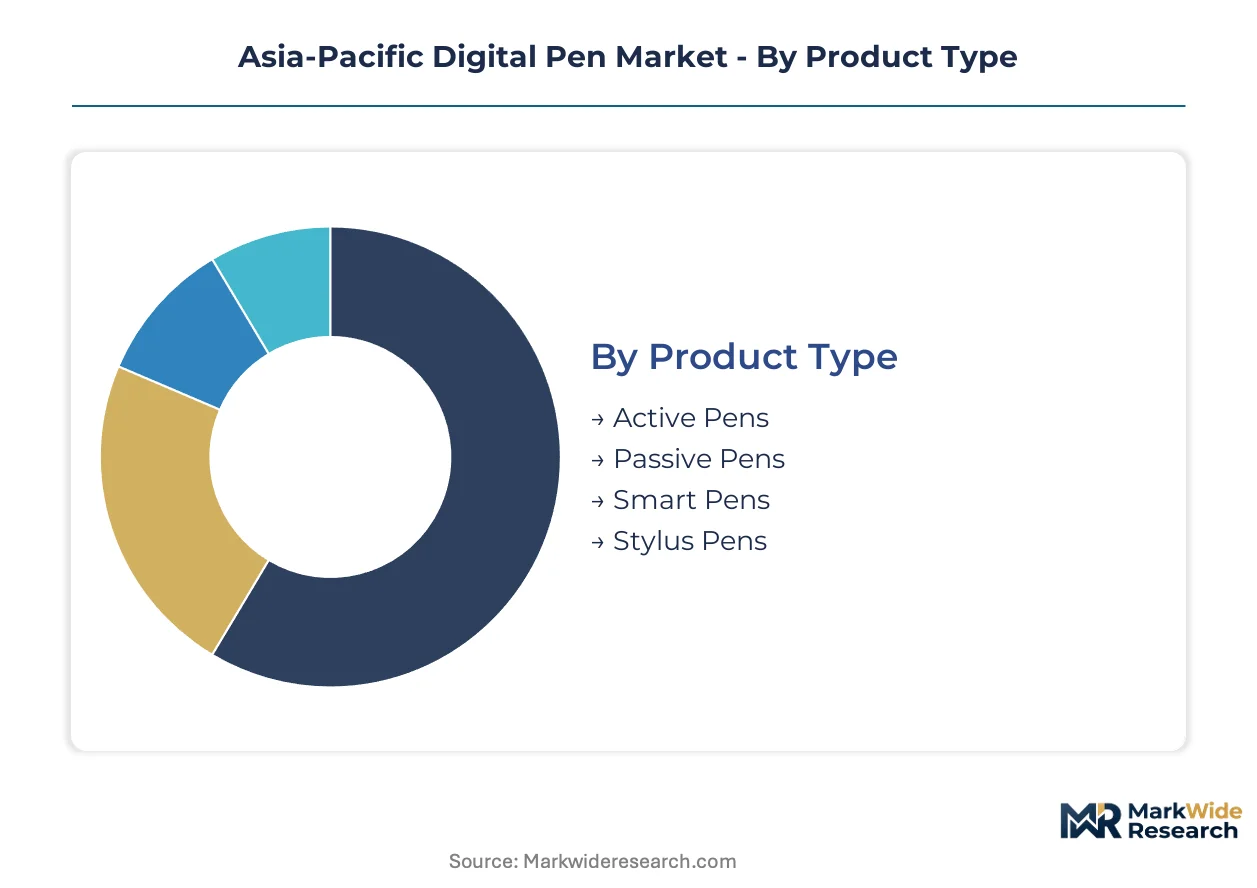
Segmentation in the Asia-Pacific Digital Pen Market reveals divergent margin pools across powered versus passive architectures, with procurement channels and certification requirements fragmenting addressable demand into distinct competitive arenas.
Product Type:
Margin pools concentrate in chip-intensive powered architectures where firmware customization and pressure transducer integration create defensible premium positioning.
- Active Pens:Powered components incorporating Bluetooth radios and pressure transducers enable palm rejection, tilt recognition, and sub-millimeter positional accuracy. Enterprise workflows across Korean corporate deployments and Japanese design studios concentrate demand for these high-margin architectures.
- Smart Pens:Optical digitization combined with onboard storage and wireless transmission targets institutional procurement channels under India's TRAI digital literacy mandates. BIS certification requirements filter supplier participation toward established OEMs with testing facility access.
- Passive Pens:Capacitive-based alternatives without powered components serve basic annotation tasks at compressed price points.
- Stylus Pens:Display-integrated variants anchor large-format ecosystem deployments across enterprise meeting room installations.
Active pens hold installed capacity. Smart pens are rotating up the share rankings.
End User:
Volume leadership sits with institutional procurement channels displacing individual purchasing decisions across education and enterprise verticals.
- Professionals:Financial services and legal sector workflows drive replacement cycles for ink-to-digital capture systems. China's Yangtze River Delta manufacturing corridor supplies component clusters for OEMs serving this segment.
- Students:State-level digital classroom initiatives under India's TRAI coordination and China's education ministry procurement create bundled demand specifying stylus-tablet compatibility. BIS certification and GB standards compliance determine vendor qualification.
- Artists:Line-weight fidelity requirements pull pressure-sensitive modules into creative workflows.
- Designers:Industrial and architectural applications demand grip ergonomics optimized for extended surface contact.
Professionals anchor current revenue concentration. Students are expanding most quickly as institutional procurement scales.
Technology:
Cost tier fragmentation separates high-performance powered modules from commodity capacitive alternatives serving divergent use cases.
- Pressure-Sensitive:Force-transducing architectures capturing line-weight variation command premium positioning in art and medical illustration workflows. Japanese METI-coordinated JIS interoperability requirements and China's MIIT GB electromagnetic compatibility standards impose dual certification overhead on suppliers targeting both markets.
- Bluetooth:Wireless transmission protocols enabling real-time stroke capture and cloud synchronization anchor enterprise annotation ecosystems. Semiconductor foundry capacity concentration in Taiwan and South Korea ties margin pools to regional chip supply dynamics.
- Capacitive:Passive electrical coupling dominates volume shipments for basic touchscreen interaction.
- Optical:Camera-based positional tracking offers cost-optimized digitization for China's education procurement channels.
Pressure-sensitive technology commands premium pricing tiers. Bluetooth is gaining share fastest as wireless integration becomes standard.
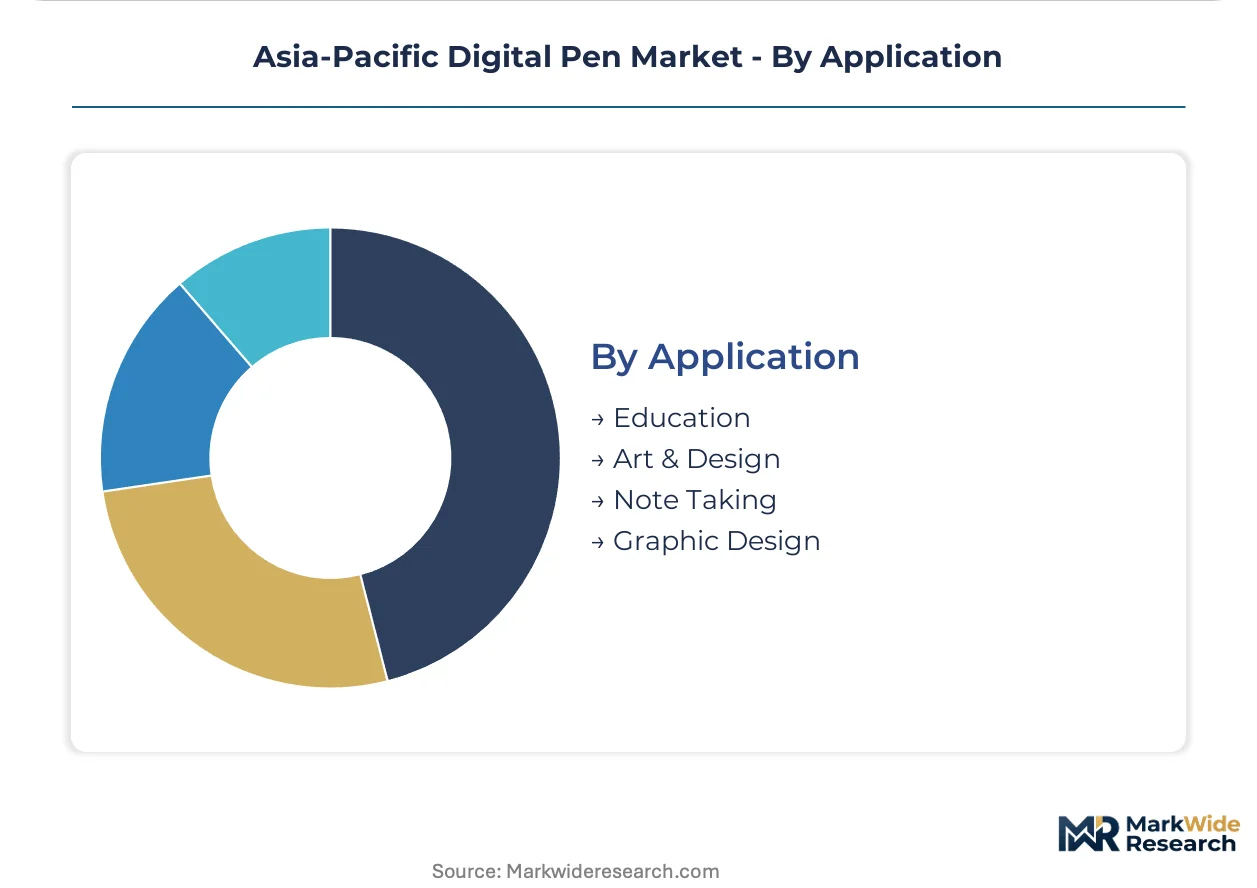
Application:
Customer type divergence separates institutional tender-driven procurement from individual professional purchasing with distinct certification and compatibility requirements.
- Education:Ministry-level digital classroom mandates across India, China, and Southeast Asia specify stylus compatibility with mandated tablet platforms. BIS certification, GB standards compliance, and TRAI coordination protocols compress vendor selection to pre-qualified OEMs.
- Art & Design:Creative workflows fragment into specialized sub-niches with divergent grip ergonomics and surface compatibility requirements. Wacom's heritage pressure-sensitive technology faces erosion from Korean display-integrated ecosystems and Chinese optical alternatives.
- Note Taking:Enterprise and academic productivity applications drive demand for palm rejection and sub-millimeter accuracy.
- Graphic Design:Professional creative software integration requirements favor established ecosystem players with established driver certification.
Education holds institutional procurement volume. Art & Design is climbing the fastest as creative professional segmentation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese component exports flow to Korean corporate assembly and Indian education procurement channels, consolidating the Asia-Pacific Digital Pen Market around three national demand centers with divergent certification requirements.
China
Yangtze River Delta electronics manufacturing and Pearl River Delta component clustering drive supply-side concentration. MIIT enforces GB electromagnetic compatibility standards requiring pre-market testing at designated Shenzhen laboratories. Component suppliers cluster around Shanghai and Shenzhen to reduce logistics friction for OEM assembly operations.
India
State-level digital classroom initiatives under TRAI coordination create institutional demand corridors for electronic learning tools. BIS certification requirements filter supplier participation toward established OEMs with testing facility access. Procurement concentrates in Delhi-NCR and Karnataka as education ministry tenders specify stylus-tablet compatibility.
Japan
Professional creative workflows and design studio demand anchor high-margin active pen consumption. METI coordinates JIS interoperability requirements with domestic electronics manufacturers for synchronized product launches. Industrial concentration in Kanto and Kansai regions supports firmware customization talent pools.
South Korea
Large-format display-integrated stylus ecosystems dominate corporate meeting room deployments. MFDS-equivalent coordination with semiconductor foundries ties margin pools to regional chip supply dynamics. Seoul Capital Area anchors enterprise procurement channels favoring integrated stylus purchases over aftermarket accessories.
Australia
Healthcare annotation workflows and medical imaging applications represent emerging vertical demand. TGA-equivalent device standards influence procurement specifications for clinical documentation tools. Sydney and Melbourne concentrate professional services adoption of palm-rejection technologies.
Asia-Pacific Digital Pen Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and firmware customization dimensions, producing a tiered structure where scale-driven conglomerates share space with focused component architects. Market concentration sits at the premium active pen tier where chip-intensive architectures create defensible positioning. Three archetypes dominate: heritage pressure-sensitive technology holders, display-integrated ecosystem builders, and cost-optimized optical digitization suppliers. Competitive moves center on dual-certification firmware stacks for simultaneous China-Japan release and backward integration into pressure transducer supply.
Within the heritage technology tier, Wacom Co., Ltd. and Hanvon Technology Co. Ltd. exemplify divergent strategic positioning. Wacom represents premium creative workflow anchoring through pressure-sensitive module heritage. Hanvon occupies a position as a cost-optimized optical digitization supplier targeting China's education procurement channels. Samsung Electronics Co., Ltd. anchors the display-integrated ecosystem archetype across Korean corporate deployments.
| Leading Market Players |
|---|
| Wacom Co., Ltd. |
| Canon Inc. |
| Samsung Electronics Co., Ltd. |
| Hanvon Technology Co. Ltd. |
| Toshiba Corporation |
| NeoLAB Convergence Inc. |
| Apple Inc. |
| Huion Animation Technology Co., Ltd. |
| HP Development Company L.P. |
| Others |
Value Network & Pricing Analysis
Component scale economies in Taiwan's semiconductor foundries and South Korea's Bluetooth radio manufacturing compress unit costs for active pen architectures while elevating price floors for smaller assemblers lacking volume purchasing power. This concentration simultaneously tightens margin pools at the premium tier and forces cost-optimized alternatives toward Shenzhen's optical digitization suppliers.
Pricing Analysis
Current-generation active pen architectures incorporating pressure transducers and tilt recognition command substantial premiums over prior-generation capacitive alternatives and next-generation display-integrated stylus systems. Three-tier pricing structure across premium, standard, and economy levels separates Wacom's creative workflow anchoring from Hanvon's education procurement positioning and unbranded passive stylus commodity tiers. Pricing pressure stems from capacitive technology substitution in basic annotation tasks, compressing margins at the volume-shipment tier. Students through India's TRAI-mandated institutional procurement exhibit highest price sensitivity, while Japanese design studios demonstrate lowest sensitivity due to line-weight fidelity requirements.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites active pen chip supply chains, creating vulnerability concentration for pressure transducer and Bluetooth radio components. Manufacturing draws from Taiwan's foundry capacity, South Korea's wireless module assembly, and China's Yangtze River Delta plastics and battery integration. Raw material dependencies span lithium-ion cells, rare-earth magnets for positional sensing, and specialized polymers for grip ergonomics. Single-source vulnerability in Taiwan's 8-inch foundry capacity for analog-mixed signal chips represents structural risk. Distribution runs through Shenzhen's designated MIIT testing laboratories for GB certification before regional channel deployment across education and enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware customization services and cloud synchronization subscriptions attach to hardware sales with faster expansion than pen unit shipments alone. Enterprise procurement channels increasingly bundle ongoing software integration support with initial stylus-tablet compatibility certification.
For Market Incumbents: Consolidate backward integration into pressure transducer supply chains to defend margin pools against Korean display-integrated ecosystem erosion. Lock Shenzhen laboratory relationships for GB electromagnetic compatibility pre-market testing to compress certification timelines versus Japanese competitors. Channel control through BIS-certified distributor networks in India protects against optical digitization alternatives. For New Entrants and Emerging Players: Differentiate on healthcare annotation workflows where palm rejection and sub-millimeter accuracy command premium positioning underserved by current creative-focused vendors. Australia's TGA-equivalent clinical documentation standards create the most penetrable regulatory corridor. Target state-level digital classroom tenders in Karnataka and Delhi-NCR through BIS certification investment and stylus-tablet bundle partnerships with mandated tablet OEMs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firmware customization specialists with embedded systems engineering talent capable of integrating pressure algorithms with wireless protocols. Long-term viability hinges on dual-certification capability for simultaneous China-Japan release windows. Acquisition targets should demonstrate SAMR-aligned recyclable battery architectures. The signal to watch is MIIT enforcement intensity at Shenzhen testing laboratories, which accelerates compliance cost advantages for pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Firmware Development | Simultaneous GB-JIS compliance compresses Northeast Asia product launch windows against single-market competitors. |
| Backward Integration into Pressure Transducers | Captive supply of force-sensing modules insulates margin pools from Taiwan foundry capacity constraints. |
| BIS Certification Investment | Testing facility access qualifies suppliers for India's TRAI-coordinated state education tenders. |
| Healthcare Workflow Partnership | TGA-aligned clinical documentation positioning opens Australia's emerging medical imaging annotation vertical. |
| Recyclable Battery Architecture | SAMR environmental compliance creates first-mover advantage in China's dual carbon procurement criteria. |
Research Methodology
Initial hypotheses were tested against primary input from OEM procurement managers, embedded systems engineers, education ministry tender officials, and semiconductor foundry account executives and refined through secondary validation. Primary fieldwork combined structured interviews with distribution channel partners in Shenzhen and Delhi-NCR alongside firmware developer surveys across Kanto and Seoul Capital Area clusters. Secondary sources encompassed MIIT GB standard filings, BIS certification registries, TRAI digital literacy mandate documentation, and METI JIS interoperability protocols. Bottom-up demand modeling across institutional procurement channels triangulated against top-down semiconductor foundry capacity allocation data.
Variance decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions span product type architecture, end-user procurement channel, pressure-sensitive versus capacitive technology tier, and application vertical with regulatory cluster overlay. CAGRs derive from installed base replacement cycle analysis and institutional tender pipeline conversion rates. Industry-specific forecast inputs incorporate MIIT electromagnetic compatibility enforcement intensity and TRAI state-level digital classroom budget allocation patterns.
Material uncertainties — GB standards interpretation shifts, Taiwan foundry capacity reallocation, and Indian state tender timing volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline stability and semiconductor supply continuity. Practitioners should keep alternative scenarios live as SAMR dual carbon battery material requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Switzerland ICT Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Master Data Management Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
System Integrator Market
Digital Solutions
Global Network Engineering Service Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Digital BSS Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Cloud Field Service Management (FSM) Market