
 Intelligent Enterprise Data Capture Software Market | 2026-2036
Intelligent Enterprise Data Capture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Enterprise Data Capture Software Market Outlook
Platform licensing is rewriting margin economics across the enterprise software stack. UiPath leverages its robotic process automation foundation to extend into intelligent capture workflows. ABBYY anchors its position through deep specialization in optical character recognition and document analytics. IBM Corporation competes by integrating data capture with broader hybrid cloud and AI governance portfolios.
Intelligent enterprise data capture software encompasses systems that automatically identify, classify, and extract structured and unstructured data from physical and digital documents using machine learning models, computer vision algorithms, and natural language processing pipelines operating at sub-second latency for high-volume transaction environments. The technology serves commercial and industrial organizations seeking to eliminate manual data entry, reduce processing errors, and create audit-ready digital records for regulatory compliance and operational analytics. Intelligent Document Processing solutions command the deepest margin pools as enterprises prioritize end-to-end automation of complex multi-page documents over basic extraction. Cloud-Based deployment models represent the fastest-expanding segment as organizations retire on-premises infrastructure in favor of elastic, API-accessible capture services. Optical Character Recognition remains the most mature capability, now commoditized at the low end while premium value concentrates in context-aware extraction that preserves semantic relationships across tables, handwriting, and mixed formats.
The EU AI Act imposes transparency and risk-classification requirements on automated decision systems, directly shaping product roadmaps for vendors selling into European financial services and healthcare sectors. HIPAA in the United States and GDPR across European jurisdictions mandate granular data lineage and access controls, forcing capture platforms to embed encryption, consent management, and retention policies at the ingestion layer. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor shortlists. Stakeholders must monitor how evolving AI liability frameworks in multiple jurisdictions reshape indemnification structures and vendor-customer contracting norms.
Market Dynamics
EU AI Act transparency mandates and HIPAA audit requirements are compressing procurement cycles, forcing enterprises to prioritize explainable extraction pipelines over black-box automation tools.
Growth Catalysts
- Healthcare digitization mandates:Patient intake automation and claims processing workflows drive hospital system procurement of intelligent document processing platforms. The US HIPAA Security Rule accelerates compliance-focused deployments.
- GDPR lineage requirements:European enterprises must maintain granular data provenance records, creating pull for capture solutions with embedded consent management and retention policy enforcement.
- Computer vision advancement:Sub-second latency extraction from mixed-format documents enables real-time transaction processing in high-volume financial services environments.
Market Restraints
- Cloud infrastructure concentration:Elastic capture services depend on hyperscaler availability zones, creating geographic dependency risk for mission-critical document workflows.
- Legacy system integration friction:Mainframe-based ERP architectures in established enterprises resist API-native capture solutions without expensive middleware layers.
- Specialized talent scarcity:Machine learning operations engineers with document AI expertise command compensation premiums that inflate implementation budgets.
Strategic Opportunities
- German industrial automation:Precision-engineering clusters in Bavaria and Baden-Württemberg favor auditable capture solutions for quality documentation and supply chain traceability.
- Large language model convergence:Natural language processing pipelines are hybridizing with traditional OCR to extract semantic relationships from unstructured contract and correspondence archives.
- API-first distribution channels:Developer marketplaces and low-code integration platforms enable direct procurement by line-of-business units bypassing traditional enterprise software sales cycles.
Industry Challenges
- ISO 27001 certification timelines:Vendor security audits extend sales cycles by 4-8 months as enterprise buyers mandate baseline procurement filters.
- Annotation workforce scaling:Training accurate extraction models requires domain-specific labeled datasets that resist automation and demand skilled document analysts.
- Multi-jurisdiction AI liability:Diverging indemnification frameworks across EU member states and US federal districts complicate vendor-customer contracting norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Enterprise Data Capture Software Market |
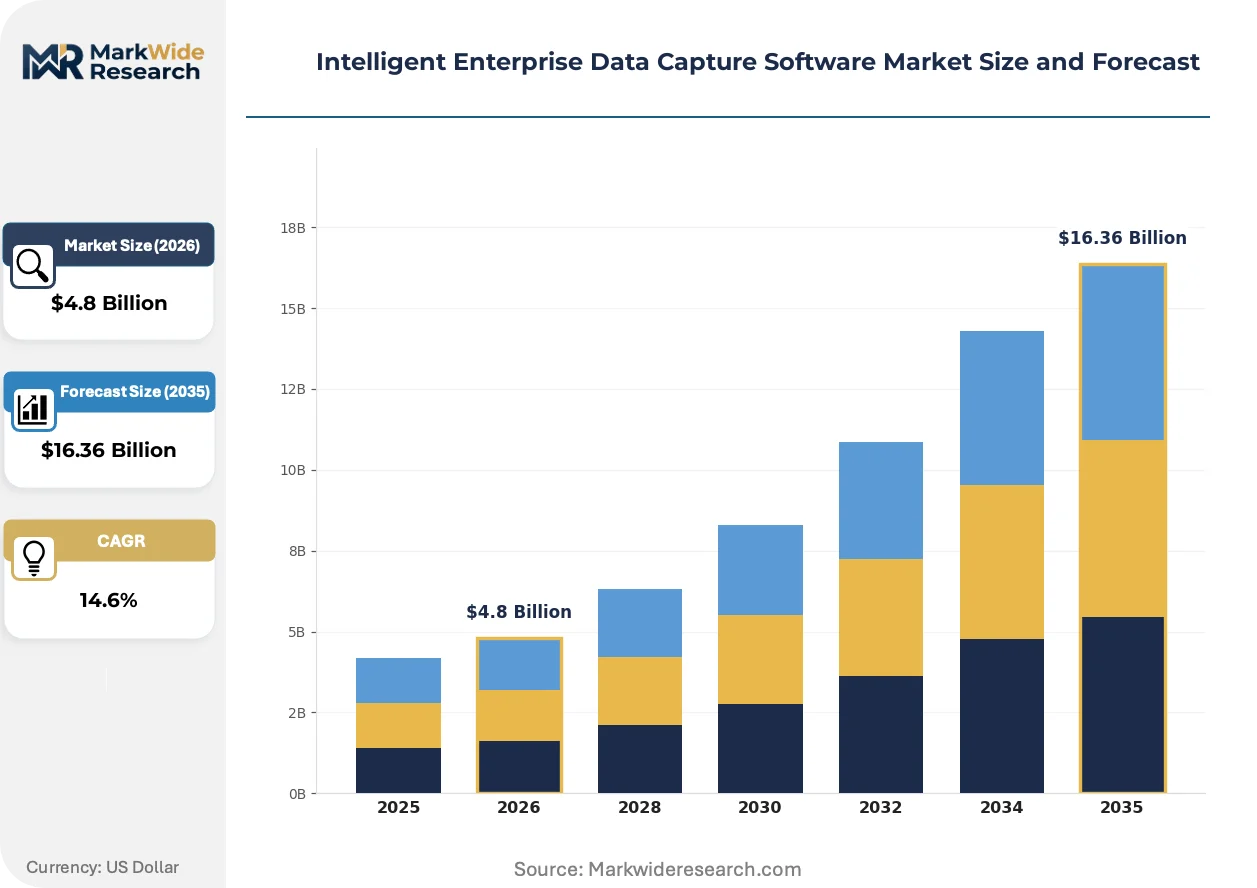
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Character Recognition, Intelligent Document Processing, Data Extraction, Image Recognition Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: Retail, Manufacturing, Healthcare, Financial Services Integration Type: API, Workflow Automation, Third-Party Applications, Custom Integrations |
| Companies Covered | Blue Prism, Automation Anywhere, UiPath, Adobe, Hyperscience, ABBYY, Kofax, IBM Corporation, OpenText, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Enterprise Data Capture Software Market Strategic Shifts
Document AI architectures are fragmenting along deployment-model lines, with cloud-native pipelines gaining traction while on-premises solutions retreat to highly regulated niches requiring air-gapped processing environments.
Transformer-based language models are hybridizing with computer vision encoders to process visually rich documents containing tables, handwriting, and mixed layouts within single inference passes. Financial services procurement teams in London and Frankfurt are piloting these unified architectures for trade finance documentation. The technology is compressing vendor differentiation around format-specific handling, collapsing premium pricing for specialized table-extraction modules.
The EU AI Act risk-classification framework imposes documentation and human-oversight requirements on automated decision systems processing sensitive personal data. Healthcare providers in France and the Netherlands are restructuring capture workflows to maintain audit trails for high-risk extraction scenarios. Vendors are embedding explainability dashboards that surface confidence scores and alternative interpretations for each field extraction.
Enterprise buyers are consolidating document processing spend under platform licensing agreements rather than point-solution procurement. Chief information officers in manufacturing and insurance verticals favor end-to-end automation suites over best-of-breed OCR tools. German automotive suppliers and US property-casualty insurers represent the vanguard of this consolidation, negotiating multi-year enterprise agreements that subsume capture functionality within broader process automation contracts.
Intelligent Enterprise Data Capture Software Market Segmentation
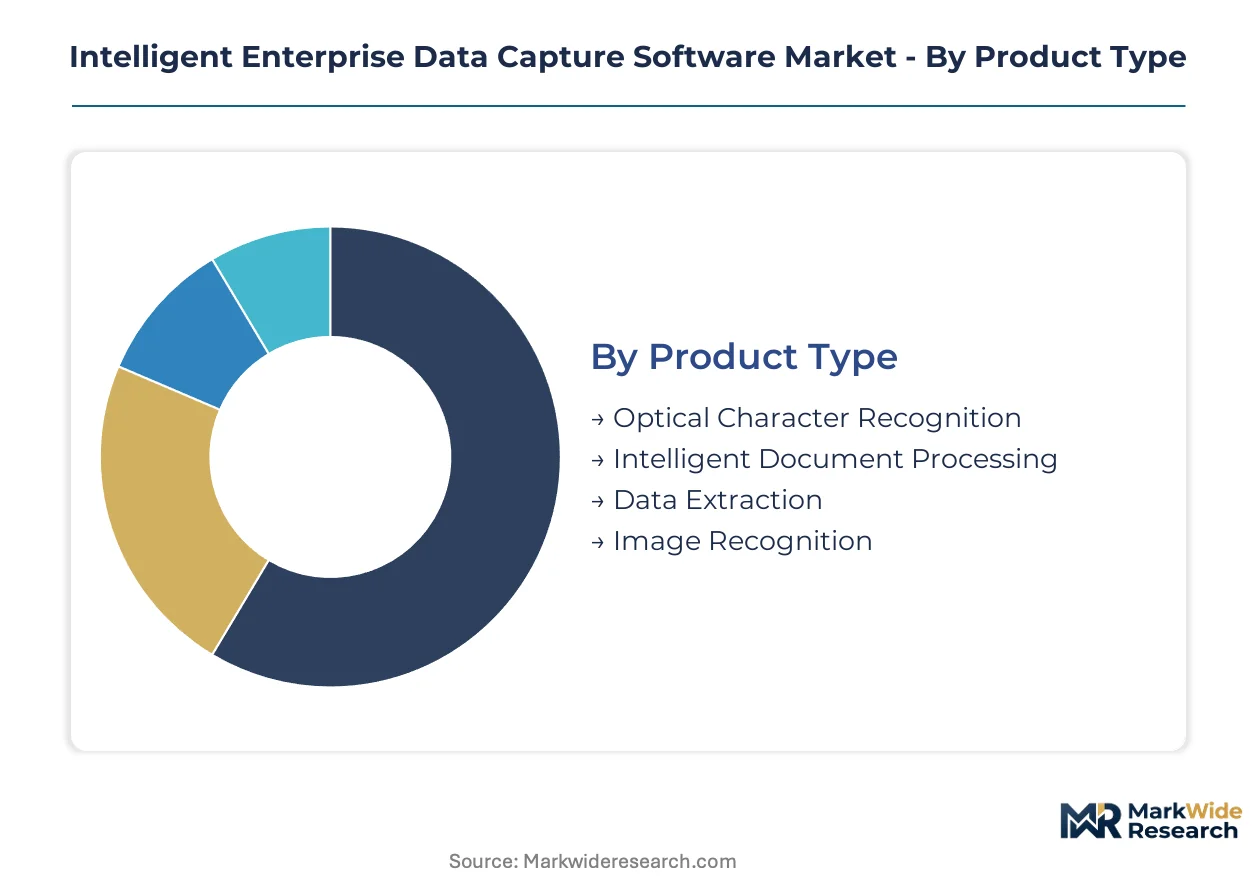
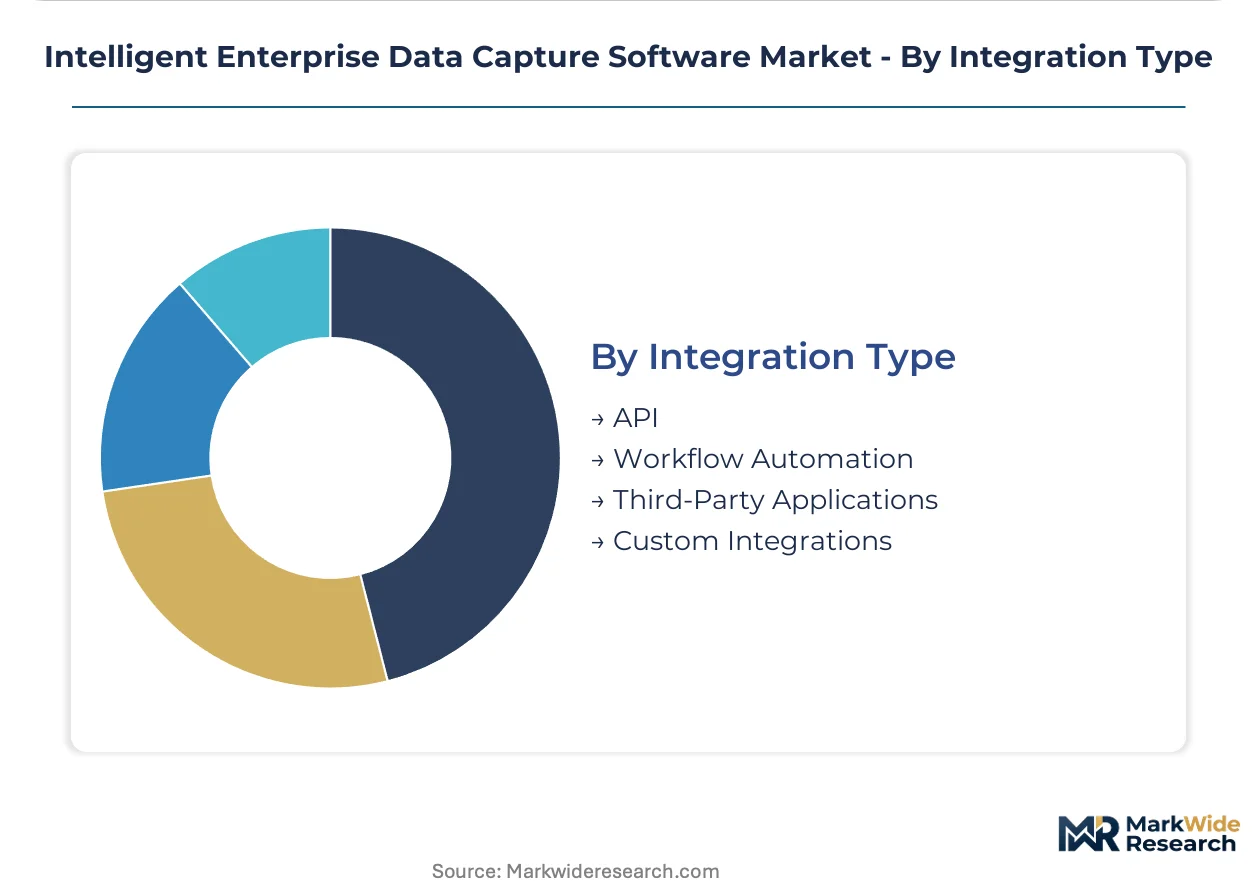
Segmentation reveals how capture technology value pools concentrate across deployment models and integration architectures. Product maturity varies dramatically, with commoditized OCR contrasting against premium intelligent document processing suites.
Product Type:
Mature capabilities anchor the low end while emerging AI-native extraction commands premium positioning.
- Optical Character Recognition:Rule-based character recognition from scanned images and PDFs. Retail invoice processing in Germany and France relies on OCR for high-volume, low-complexity transactions where latency tolerance permits batch operations.
- Intelligent Document Processing:Machine learning pipelines classify, extract, and validate data from unstructured multi-page documents. Healthcare providers in the Netherlands deploy IDP for patient intake automation where HIPAA and GDPR lineage requirements demand explainable extraction with full audit trails.
- Data Extraction:Field-level parsing from structured forms and semi-structured documents. Manufacturing quality documentation in Bavaria uses extraction tools for supply chain traceability.
- Image Recognition:Computer vision models identify document types and detect visual anomalies. Financial services pilot this for trade finance documentation verification.
Intelligent Document Processing handles the majority of throughput; Image Recognition is the fastest mover on share.
Deployment Model:
Cost tier stratification separates legacy infrastructure commitments from elastic consumption economics.
- Cloud-Based:API-accessible capture services with elastic scaling and pay-per-document pricing. US property-casualty insurers favor cloud deployment for seasonal claims volume spikes without capital expenditure.
- Hybrid:Sensitive document processing on-premises with archival and analytics in cloud environments. German automotive suppliers use hybrid models to satisfy air-gapped quality documentation requirements while enabling centralized analytics.
- On-Premises:Fully contained capture infrastructure within enterprise data centers. Defense contractors and classified government workflows mandate on-premises for sovereignty compliance.
- Multi-Tenant:Shared infrastructure with tenant isolation for software vendors and managed service providers. European SaaS platforms leverage multi-tenant architectures to serve mid-market clients without dedicated infrastructure costs.
Cloud-Based deployment attracts the most new customer acquisitions; Hybrid models show the steepest expansion trajectory among regulated industries.
End User:
Application intensity varies by document volume and compliance exposure across vertical workflows.
- Healthcare:Patient registration, claims adjudication, and clinical documentation automation. US hospital systems drive procurement to satisfy HIPAA Security Rule audit requirements.
- Financial Services:Trade finance, mortgage processing, and regulatory reporting. London and Frankfurt banking centers deploy capture for real-time transaction documentation.
- Manufacturing:Quality certificates, supplier documentation, and customs paperwork. German precision-engineering clusters prioritize auditable capture for supply chain traceability.
- Retail:Invoice processing, returns documentation, and vendor onboarding. High-volume retailers use capture to eliminate manual data entry in accounts payable.
Healthcare generates the largest absolute spend; Financial Services is climbing the fastest as real-time transaction demands intensify.
Integration Type:
Customer technical sophistication determines whether direct API consumption or mediated workflow tools dominate procurement.
- API:Direct REST and GraphQL endpoints for developer-led integration. Line-of-business units in technology-forward enterprises procure API-native capture without central IT involvement.
- Workflow Automation:Pre-built connectors to robotic process automation and business process management platforms. Manufacturing and insurance CIOs consolidate spend under platform licensing agreements.
- Third-Party Applications:Embedded capture within enterprise content management and ERP systems. Legacy ERP architectures in established enterprises favor this integration path.
- Custom Integrations:Bespoke middleware for mainframe and proprietary system connectivity. Mainframe-based financial institutions require custom integration for core banking system compatibility.
Workflow Automation captures the largest integration project volume; API is gaining share fastest as developer marketplaces democratize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement environments. German industrial buyers absorb premium pricing for audit-grade precision, while US healthcare systems prioritize compliance bundling over per-feature cost optimization.
United States
Hospital systems drive demand for patient intake automation and claims adjudication workflows. HIPAA Security Rule audit requirements compress vendor evaluation cycles toward explainable extraction platforms. Healthcare procurement clusters in Texas and the Northeast favor bundled enterprise agreements over point-solution licensing.
Germany
Precision-engineering manufacturers prioritize supply chain traceability and quality documentation automation. EU AI Act risk-classification mandates reshape product roadmaps for vendors selling into Bavarian automotive clusters. Baden-Württemberg industrial buyers demand embedded consent management and retention policy enforcement at the ingestion layer.
United Kingdom
Financial services procurement teams in London pilot unified transformer-vision architectures for trade finance documentation. GDPR lineage requirements push banking centers toward capture solutions with granular data provenance records. The Lloyd's insurance market drives demand for real-time transaction processing with sub-second latency extraction.
France
Healthcare providers restructure capture workflows to maintain audit trails for high-risk extraction scenarios under EU AI Act transparency mandates. CNIL enforcement actions accelerate procurement of platforms with embedded explainability dashboards. Pharmaceutical documentation clusters in the Île-de-France region favor hybrid deployment models with air-gapped processing for sensitive clinical records.
Netherlands
Healthcare providers deploy intelligent document processing for patient intake automation where HIPAA and GDPR lineage requirements overlap. Amsterdam financial services firms pilot API-native capture procurement through developer marketplaces. Dutch manufacturing exporters prioritize customs documentation automation for supply chain resilience.
Intelligent Enterprise Data Capture Software Market Competitive Environment
Capability concentration sits with specialized document AI vendors; scale advantage sits with platform software conglomerates. The market structures around three tiers: robotic process automation incumbents extending into capture workflows, pure-play optical character recognition specialists defending premium positioning, and hybrid cloud providers integrating extraction with broader governance portfolios. Dominant competitive moves include workflow automation platform consolidation and API-first distribution channel expansion through developer marketplaces.
Within the pure-play specialist tier, ABBYY and Hyperscience occupy positions anchored in deep optical character recognition and document analytics specialization. UiPath represents the automation-platform extension archetype, leveraging robotic process automation foundations to capture document processing spend under consolidated enterprise agreements. IBM Corporation sits within the hybrid cloud integration tier, competing through data capture embedded within broader AI governance and infrastructure portfolios.
| Leading Market Players |
|---|
| Blue Prism |
| Automation Anywhere |
| UiPath |
| Adobe |
| Hyperscience |
| ABBYY |
| Kofax |
| IBM Corporation |
| OpenText |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler infrastructure concentration in the United States and Ireland concentrates compute cost leverage upstream, directing margin capture toward vendors with captive cloud capacity or long-term reserved instance contracts rather than purely software-layer specialists.
Pricing Analysis
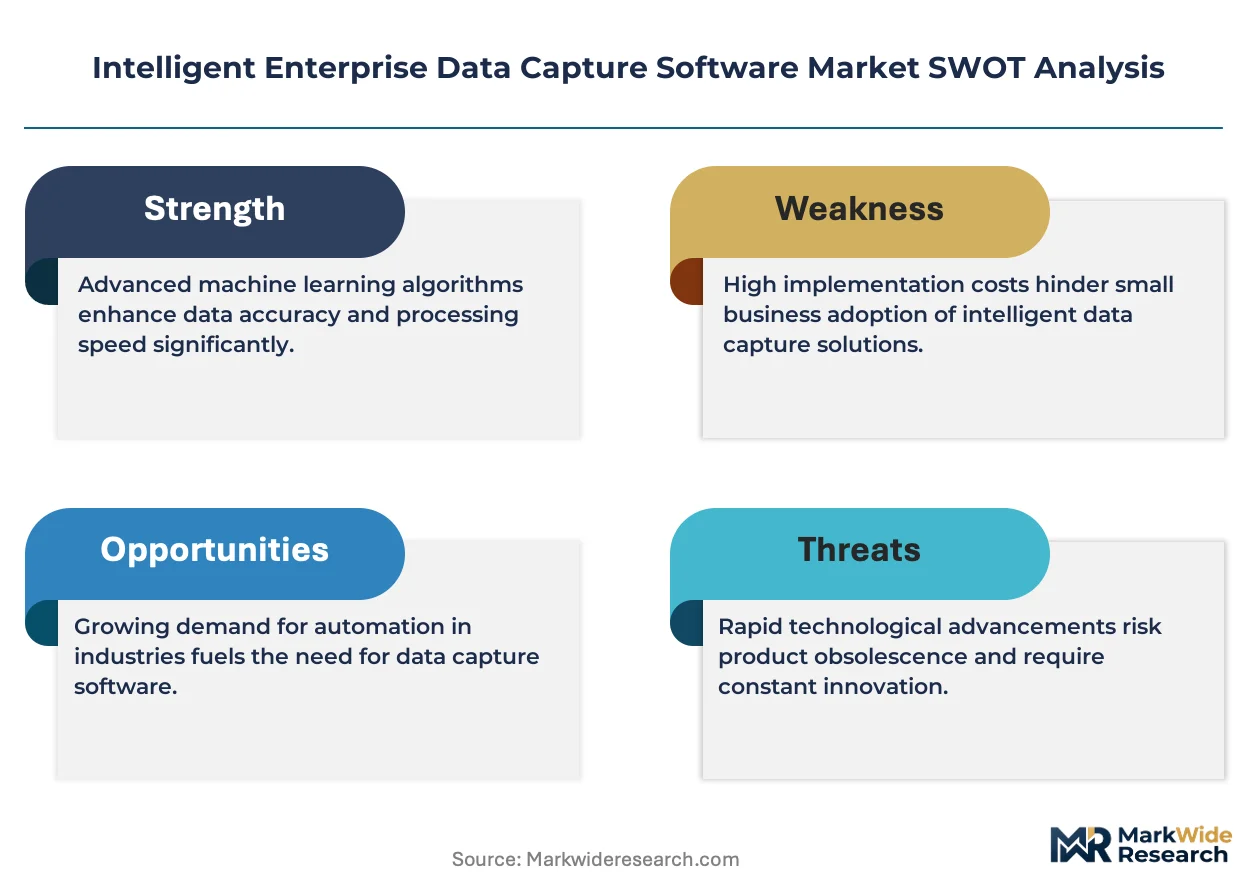
Platform maintenance and professional services revenue streams now drive lifetime value economics across the enterprise data capture stack. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 27001 certification grade and embedded explainability dashboard depth. Cost compression in the economy tier is intensifying because open-source OCR libraries commoditize basic extraction, while premium pricing holds firm for HIPAA-compliant healthcare deployments. Mid-market manufacturing buyers exhibit highest price sensitivity; German automotive suppliers show lowest sensitivity due to air-gapped processing requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for GPU-accelerated inference hardware. Taiwan, South Korea, and the United States anchor semiconductor supply for document AI training clusters. Training data pipelines draw from annotation workforces in India, the Philippines, and Poland. Single-source vulnerability in NVIDIA GPU supply creates procurement bottlenecks for latency-sensitive financial services deployments. Distribution runs through direct enterprise sales with developer marketplace channels gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large language model substitution threatens traditional OCR-centric architectures, forcing incumbents to defend against unified transformer-vision platforms that collapse format-specific premium pricing.
For Market Incumbents: Harden platform stickiness through workflow automation consolidation and embedded consent management modules that satisfy EU AI Act risk-classification mandates. Invest in backward integration into annotation workforce operations to reduce training data cost inflation. Defend against LLM-native entrants by anchoring customer relationships through multi-year enterprise agreements with embedded professional services. For New Entrants and Emerging Players: French healthcare providers under CNIL enforcement pressure represent the most penetrable white-space segment for explainability-first capture platforms. API-native distribution through developer marketplaces bypasses traditional procurement cycles. Target hybrid deployment models for pharmaceutical documentation clusters in the Île-de-France region where air-gapped processing commands premium positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed RPA platforms seeking document AI capability to round out automation suites. Five-to-ten year viability hinges on consolidation economics rather than standalone growth. Monitor EU AI Act liability framework harmonization across member states as the inflection signal for vendor-customer contracting norm stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | UiPath leverages RPA foundations to subsume capture spend under consolidated enterprise agreements. |
| Acquisition of Specialist Firm | Pure-play OCR vendors like ABBYY defend positioning through deep document analytics specialization. |
| Product Launch | Transformer-vision hybrid architectures compress vendor differentiation around format-specific handling. |
| Strategic Partnership | Hyperscaler alliances enable elastic scaling for seasonal claims volume spikes in property-casualty insurance. |
| Geographic Expansion | Baden-Württemberg precision-engineering clusters favor auditable capture for supply chain traceability. |
Study Parameters
Initial hypotheses were tested against primary input from chief information officers, healthcare procurement managers, platform engineers, and integration specialists and refined through secondary validation across SEC filings, hyperscaler capex disclosures, hospital procurement databases, and GPO contracts. Bottom-up deployment model sizing triangulated against top-down vertical spend analysis.
Demand-supply balance across the analysis window reflects deployment model adoption curves, vertical compliance exposure, and integration complexity tiers. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline penetration estimates, with inputs from API transaction volume disclosures and enterprise license renewal rates.
Practitioners should monitor EU AI Act implementation divergence across member states and hyperscaler infrastructure availability constraints for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Server Operating System Market
Software & Services
Audio and Video Editing Software Market
Software & Services
India Software Services Export Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Intelligent Apps Market
Software & Services
File Analysis Software Market
Software & Services
Global Log Management Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Global Quoting Software Market
Software & Services
Online Recruitment Software Market
Software & Services
Courier Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global Open Source Services Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Media Planning Software Market
Software & Services
Lab Automation Software Market