
 Saudi Arabia Study of Data Center Water Consumption Market | 2026-2036
Saudi Arabia Study of Data Center Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Study of Data Center Water Consumption Market Insights
Liquid cooling adoption is narrowing the gap between thermal design power and traditional air-based dissipation in Saudi facilities. DataVolt leverages direct-to-chip architectures for its gigawatt-scale campuses under development. stc anchors domestic demand through its sovereign cloud and edge node expansion. Equinix competes on interconnection density while navigating extreme ambient temperature constraints.
The Saudi Arabia Study of Data Center Water Consumption encompasses the measurement, treatment, and reuse of water deployed for heat rejection in server environments, where cooling towers typically operate at 1.8 to 5.0 liters per kilowatt-hour depending on technology configuration. Evaporative cooling dominates installed capacity but faces intensifying scrutiny under water stress protocols. Chilled water systems capture premium margins from financial services tenants demanding precise temperature control. Hybrid solutions are gaining share as operators balance efficiency against the Kingdom's groundwater conservation targets.
SFDA and MEE frameworks intersect with SASO efficiency mandates to govern chemical treatment discharge and consumption benchmarking across facilities. NEOM's regulatory sandbox is testing closed-loop recycling standards that could propagate nationally. Stakeholders must weigh capital allocation between evaporative infrastructure and dry cooling alternatives as policy trajectories harden.
Market Dynamics
The Saudi Arabia Study of Data Center Water Consumption Market is being fundamentally restructured by NEOM's zero-liquid-discharge mandates, which are forcing operators to abandon once-standard evaporative cooling architectures in favor of closed-loop recycling systems with radically different capital profiles.
Growth Catalysts
- Hyperscale cluster formation:Riyadh and Jeddah are consolidating sovereign cloud demand from stc's edge expansion and financial services tenants requiring precise thermal control, concentrating procurement volume in specific municipal zones.
- SASO efficiency mandates:The Saudi Standards, Metrology and Quality Organization has imposed consumption benchmarking that rewards early adopters of hybrid cooling configurations with preferential permitting timelines.
- Liquid cooling maturation:Direct-to-chip architectures are narrowing the performance gap against traditional air systems, enabling higher rack densities without proportional water scaling.
Market Restraints
- Groundwater access constraints:The Kingdom's aquifer depletion rates have triggered MEE withdrawal permits that cap facility-level consumption regardless of operational efficiency gains.
- Dry cooling capital intensity:Air-cooled chiller installations demand 2.3-3.1x the upfront expenditure of evaporative towers, compressing project IRRs for independent operators without sovereign balance sheet backing.
- Chemical treatment discharge limits:SFDA pharmaceutical-grade water standards for adjacent manufacturing zones impose secondary treatment costs that erode margin structures in mixed-use developments.
Strategic Opportunities
- Eastern Province greenfield sites:Dammam's industrial corridor offers untapped seawater cooling potential with lower regulatory scrutiny than inland aquifer-dependent zones.
- NEOM regulatory sandbox:The linear city's experimental closed-loop standards are generating IP and operational playbooks that will propagate to Riyadh and Jeddah once validated at scale.
- Modular water treatment skids:Containerized reverse osmosis and electrodialysis reversal units are enabling rapid deployment without permanent infrastructure commitments, matching hyperscale tenants' lease flexibility preferences.
Industry Challenges
- Thermal engineering specialization gaps:The Kingdom's vocational pipeline produces insufficient technicians versed in liquid cooling manifold maintenance and dielectric fluid handling protocols.
- Legacy air-cooled asset stranding:Existing facilities face accelerated obsolescence as SASO benchmarks tighten, forcing operators to choose between costly retrofits and contract non-renewal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Study of Data Center Water Consumption Market |
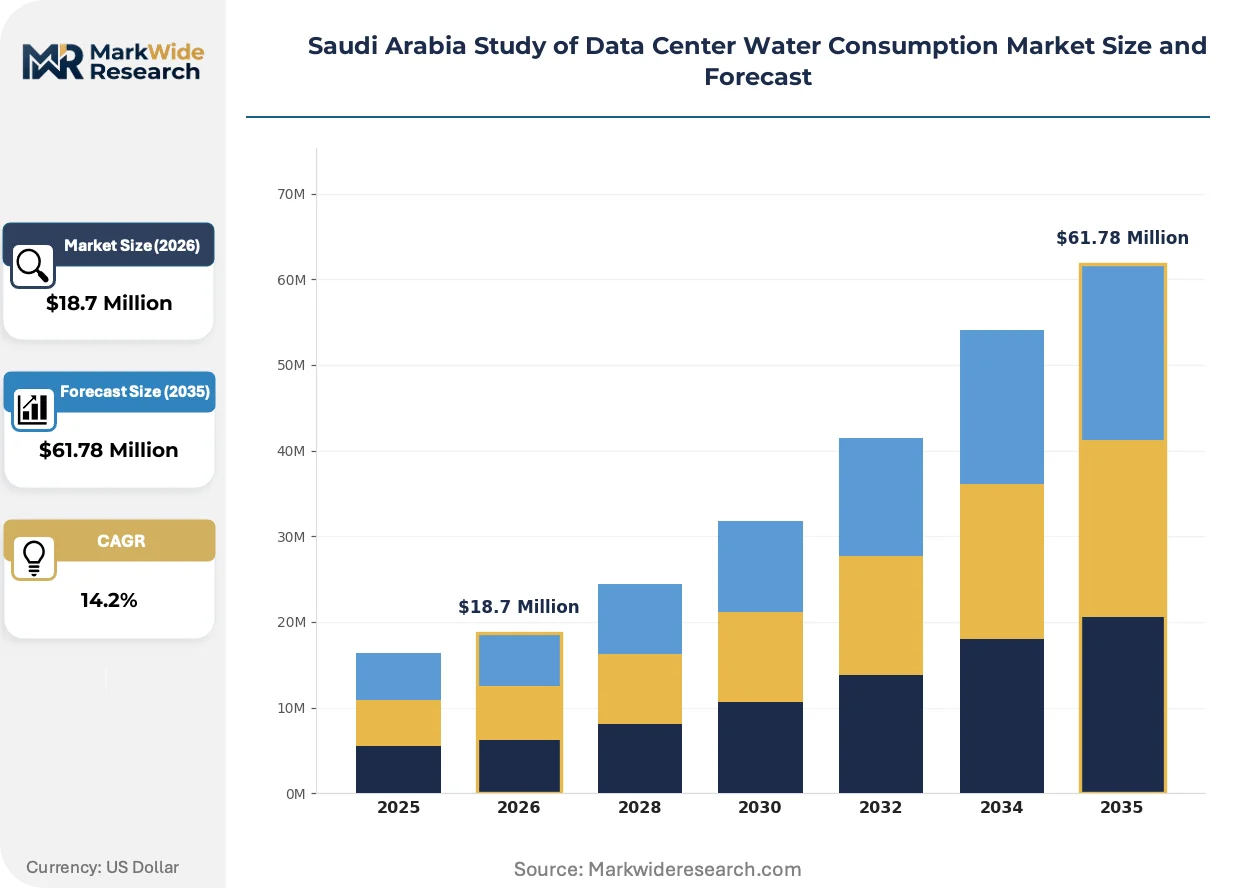
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cooling Solutions, Water Treatment, Monitoring Systems, Recycling Technologies End User: Telecommunications, Financial Services, Cloud Service Providers, Government Agencies Technology: Evaporative Cooling, Chilled Water Systems, Direct Air Cooling, Hybrid Solutions Application: Data Storage, Disaster Recovery, Cloud Computing, Big Data Analytics |
| Companies Covered | HostGee Cloud Hosting Inc., ICS Arabia, ETIHAD ATHEEB TELECOMMUNICATION COMPANY (GO Telecom), Equinix, DataVolt, Etihad Etisalat Company (Mobily), Shabakah Integrated Technology, Digital Realty Trust, stc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Study of Data Center Water Consumption Market Trends and Innovations
Water stewardship is digitizing operational architectures across Saudi facilities, compressing the traditional trade-off between thermal performance and aquifer conservation. Three distinct vectors are converging to reshape deployment patterns.
Direct-to-chip liquid cooling is digitizing heat rejection workflows by eliminating the intermediate water-to-air exchange layer entirely. Hyperscale operators in Riyadh's King Abdullah Financial District are adopting this architecture for AI training clusters exceeding 100kW per rack. The technology is digitizing facility-level water accounting, enabling real-time consumption telemetry that satisfies MEE audit requirements without manual meter readings.
NEOM's regulatory sandbox is testing closed-loop recycling standards that could propagate nationally once validated. The framework mandates 98% water recovery rates through membrane bioreactor and zero-liquid-discharge crystallizer sequences. Financial services tenants in Jeddah's King Abdullah Economic City are already pre-certifying suppliers against these draft standards to secure preferential lease terms.
Hyperscale procurement teams are unbundling water treatment from facility operations, contracting directly with specialized vendors rather than accepting bundled landlord services. This disintermediation is compressing pricing transparency and enabling outcome-based contracts tied to specific consumption thresholds. The pattern is most visible in stc's sovereign cloud expansion, where water treatment SLAs are now negotiated separately from power and space agreements.
Saudi Arabia Study of Data Center Water Consumption Market Segmentation
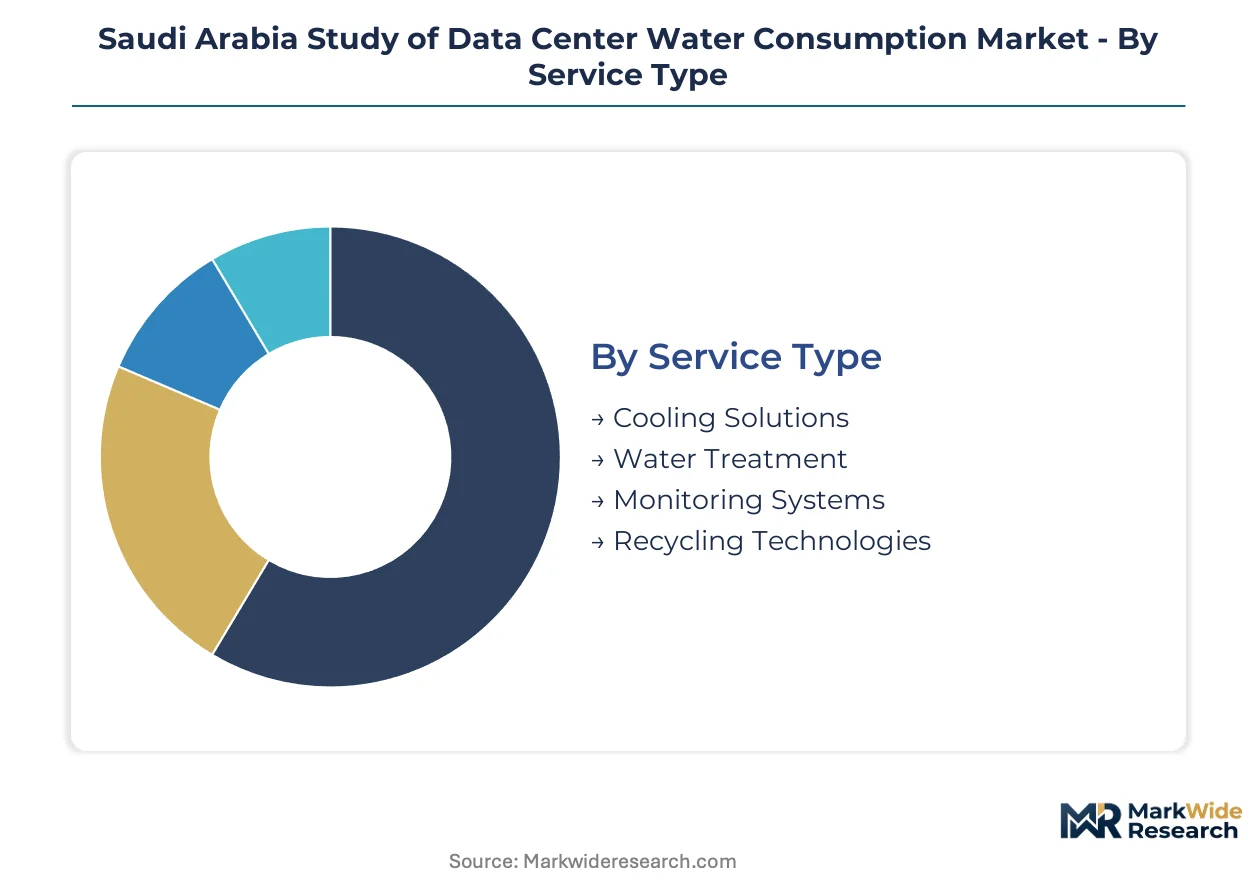
Water consumption patterns in Saudi data centers diverge sharply across service configurations and tenant requirements. Segmentation reveals how hyperscale operators prioritize recycling infrastructure while financial tenants demand precision cooling regardless of water intensity.
Service Type:
Service configurations span the full operational lifecycle from heat rejection through effluent management, with each tier commanding distinct procurement relationships and margin structures.
- Cooling Solutions:Evaporative towers and liquid cooling manifolds constitute the primary water interface, consuming 1.8 to 5.0 liters per kilowatt-hour depending on thermal design power. Riyadh's hyperscale clusters drive demand for hybrid configurations that balance efficiency against MEE withdrawal permit constraints.
- Water Treatment:Chemical dosing systems and membrane filtration units prepare make-up water and manage blowdown discharge. Financial services tenants in Jeddah's King Abdullah Economic City require pharmaceutical-grade treatment to satisfy SFDA standards for adjacent manufacturing zones.
- Monitoring Systems:Real-time telemetry platforms track consumption against SASO benchmarks.
- Recycling Technologies:Closed-loop crystallizers and membrane bioreactors enable NEOM's zero-liquid-discharge mandates.
The dominant share belongs to Cooling Solutions, while Recycling Technologies is closing the gap fastest.
End User:
Tenant archetypes dictate capital allocation priorities across the Kingdom's emerging facility clusters.
- Telecommunications:stc's sovereign cloud expansion anchors domestic procurement volume, deploying edge nodes with standardized water treatment SLAs negotiated separately from power agreements. The operator's Riyadh and Jeddah footprints concentrate demand for modular treatment skids.
- Financial Services:Banks and fintech operators in the King Abdullah Financial District demand chilled water systems with precise temperature control, accepting higher water intensity for operational resilience. These tenants pre-certify suppliers against NEOM's draft closed-loop standards.
- Cloud Service Providers:Hyperscale operators unbundle water treatment from facility operations.
- Government Agencies:Sovereign data requirements prioritize compliance with MEE frameworks over cost optimization.
Telecommunications holds the largest installed base, though Cloud Service Providers are expanding most quickly.
Technology:
Cooling architectures face accelerated obsolescence as SASO efficiency mandates tighten operational parameters.
- Evaporative Cooling:Traditional cooling towers dominate installed capacity but face intensifying scrutiny under groundwater conservation protocols. Legacy facilities in inland aquifer-dependent zones confront permit caps regardless of efficiency gains.
- Chilled Water Systems:Precision temperature control captures premium margins from financial services tenants. These installations command higher capital expenditure but satisfy tenants requiring tight thermal envelopes for sensitive compute workloads.
- Direct Air Cooling:Air-cooled chillers avoid water consumption entirely.
- Hybrid Solutions:Configurations combining evaporative and dry cooling modes balance efficiency against regulatory risk.
Evaporative Cooling retains the majority position, yet Hybrid Solutions are gaining share fastest as operators hedge policy trajectories.
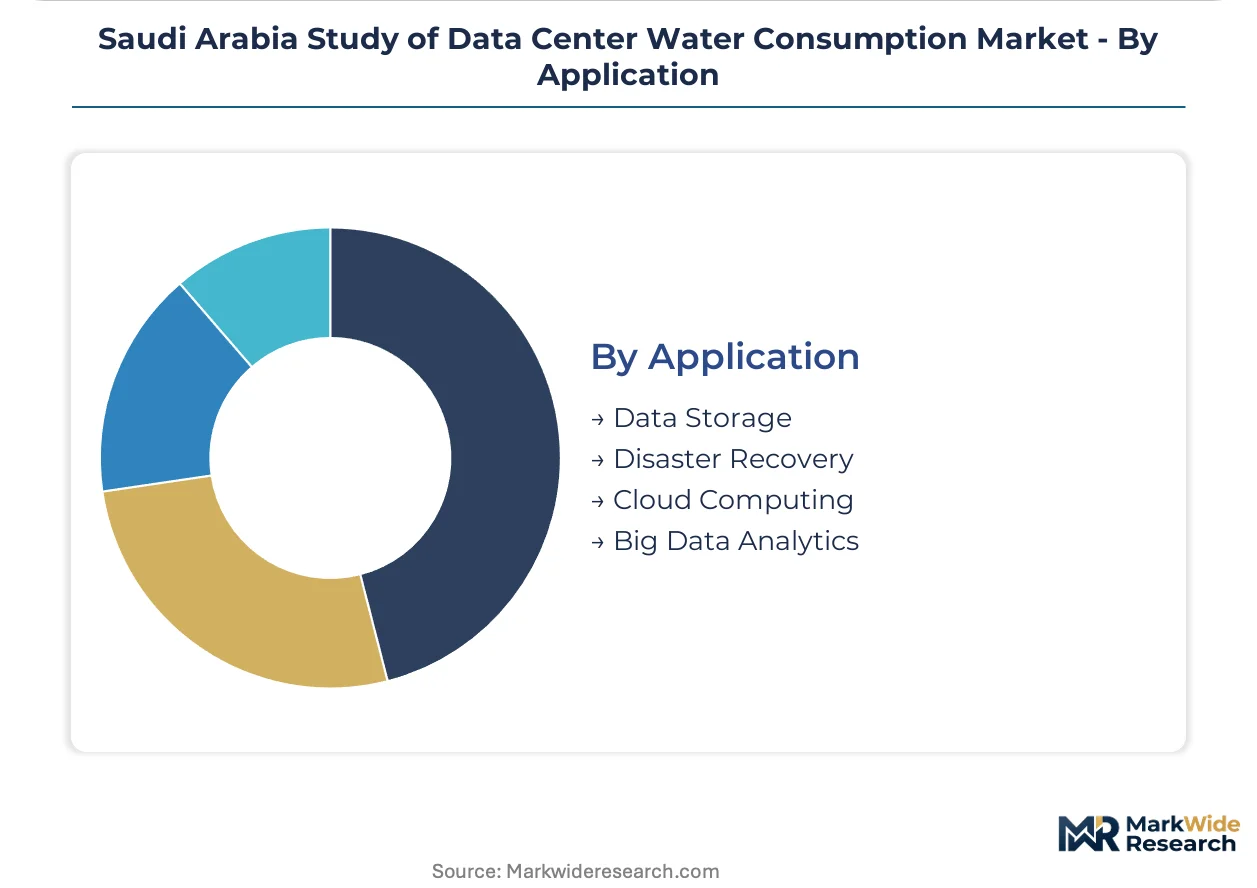
Application:
Compute workloads impose distinct thermal profiles that reshape water infrastructure requirements.
- Data Storage:Archive and backup facilities generate steady-state thermal loads well-suited to evaporative cooling. These applications tolerate wider temperature bands than transactional workloads, enabling simpler water management protocols.
- Disaster Recovery:Standby facilities require rapid cooling activation with minimal water conditioning lead time. Eastern Province greenfield sites leverage Dammam's seawater access for lower regulatory scrutiny than inland alternatives.
- Cloud Computing:Multi-tenant virtualization demands flexible cooling capacity.
- Big Data Analytics:AI training clusters exceed 100kW per rack, necessitating direct-to-chip liquid cooling that eliminates intermediate water-to-air exchange.
Data Storage commands the greatest water volume, while Big Data Analytics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's data center water consumption infrastructure concentrates in trade corridors connecting Riyadh and Jeddah to Red Sea and Arabian Gulf maritime routes. Domestic hyperscale demand flows through these nodes while NEOM's experimental standards reshape regulatory baselines.
Riyadh
King Abdullah Financial District hosts AI training clusters exceeding 100kW per rack, driving direct-to-chip liquid cooling procurement. MEE withdrawal permits cap facility-level consumption regardless of efficiency gains. Hyperscale operators cluster in the capital to serve sovereign cloud and financial services tenants.
Jeddah
King Abdullah Economic City anchors Red Sea connectivity with pre-certified suppliers meeting NEOM's draft closed-loop standards. SFDA pharmaceutical-grade water standards impose secondary treatment costs on mixed-use developments. Financial services tenants demand chilled water systems with precise temperature control.
Eastern Province
Dammam's industrial corridor offers seawater cooling potential with lower regulatory scrutiny than inland aquifer-dependent zones. Disaster recovery facilities leverage rapid cooling activation with minimal water conditioning lead time. The region's untapped coastal access attracts greenfield hyperscale development.
NEOM Northwest
The linear city's regulatory sandbox mandates 98% water recovery rates through membrane bioreactor and zero-liquid-discharge crystallizer sequences. DataVolt's gigawatt-scale campuses test closed-loop recycling standards that will propagate nationally. Experimental frameworks generate IP and operational playbooks for Kingdom-wide adoption.
Western Region
Edge node expansion by telecommunications operators concentrates modular water treatment skid deployment. Containerized reverse osmosis units enable rapid deployment without permanent infrastructure commitments. The region matches hyperscale tenants' lease flexibility preferences with standardized SLAs.
Saudi Arabia Study of Data Center Water Consumption Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Saudi data center water consumption ecosystem. The market structure consolidates around sovereign-backed telecommunications operators and international colocation specialists with established interconnection density. Two strategic archetypes dominate: hyperscale campus developers with captive water treatment infrastructure, and modular service providers offering rapid-deployment skids. Competitive moves center on strategic partnerships with membrane technology vendors and geographic expansion into Eastern Province greenfield sites.
Within the sovereign telecommunications tier, stc anchors domestic procurement volume through standardized water treatment SLAs negotiated separately from power agreements. DataVolt exemplifies the hyperscale campus developer archetype with gigawatt-scale projects under development. Equinix occupies a position among international colocation specialists competing on interconnection density while navigating extreme ambient temperature constraints. These three entities represent the primary competitive vectors reshaping capital allocation toward closed-loop recycling and direct-to-chip architectures.
| Leading Market Players |
|---|
| HostGee Cloud Hosting Inc. |
| ICS Arabia |
| ETIHAD ATHEEB TELECOMMUNICATION COMPANY (GO Telecom) |
| Equinix |
| DataVolt |
| Etihad Etisalat Company (Mobily) |
| Shabakah Integrated Technology |
| Digital Realty Trust |
| stc |
| Others |
Pricing and Supply Chain Analysis
The Dammam-Jeddah freight corridor's cooling equipment logistics cost dynamics compress margins for inland facility operators while amplifying price differentiation between aquifer-dependent and coastal deployment zones. Supply concentration around membrane technology vendors in Riyadh's King Abdullah Financial District feeds downstream pricing power into hybrid cooling configurations that satisfy MEE withdrawal permit constraints.
Pricing Analysis
The evaporative-to-liquid cooling pricing gap stratifies procurement decisions across three technology generations, with legacy cooling towers commanding economy-tier positioning against premium direct-to-chip architectures. Pricing stratifies across premium, standard, and economy tiers according to certification grade against NEOM's draft closed-loop standards and volume scale of hyperscale campus commitments. Cost compression in standard-tier hybrid configurations intensifies as stc's sovereign cloud expansion consolidates procurement volume. Financial services tenants in Jeddah's King Abdullah Economic City exhibit least price sensitivity, prioritizing pharmaceutical-grade treatment compliance over capital expenditure optimization.
Supply Chain Analysis
Upstream feedstock for membrane bioreactor and crystallizer components draws from Germany, Japan, and South Korea, with electrodialysis reversal membrane production concentrated among specialty chemical manufacturers. Dielectric fluid formulations for direct-to-chip systems rest on fluorinated compound supply from Belgian and American specialty chemical producers. Single-source vulnerability permeates zero-liquid-discharge crystallizer procurement, where NEOM's regulatory sandbox validates designs from limited qualified vendors. Distribution runs through modular skid integrators serving hyperscale campus developers with rapid-deployment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water treatment service contracts represent the fastest-expanding recurring-revenue layer, outpacing hardware procurement as hyperscale operators unbundle treatment from facility operations and negotiate standalone SLAs. This service-attach dynamic restructures vendor relationships toward outcome-based consumption thresholds.
For Market Incumbents: Harden position through backward integration into membrane bioreactor manufacturing and captive supply of dielectric fluid formulations, neutralizing single-source vulnerability as NEOM's standards propagate nationally. Incumbent operators must pre-certify supplier networks against draft closed-loop standards before SASO efficiency mandates tighten, accelerating legacy air-cooled asset obsolescence for competitors caught unprepared. For New Entrants and Emerging Players: Eastern Province greenfield sites with Dammam seawater access represent the most penetrable entry point, offering lower regulatory scrutiny than inland aquifer-dependent zones where MEE withdrawal permits cap consumption. Modular water treatment skid deployment for telecommunications edge nodes provides a rapid go-to-market angle, matching stc's standardized SLA preferences without permanent infrastructure commitments. For Investors and Strategic Acquirers: SFDA pharmaceutical-grade water standard harmonization with MEE frameworks reshapes the acquisition landscape, elevating treatment technology vendors with dual-certification capabilities above pure-play cooling equipment manufacturers. Target vertically integrated operators combining membrane technology IP with established hyperscale customer relationships. Monitor NEOM closed-loop validation milestones as the critical inflection signal for national standard propagation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive supply of bioreactor components insulates against single-source crystallizer vendor constraints. |
| NEOM Pre-Certification Program | Early alignment with draft closed-loop standards secures preferential permitting timelines under SASO mandates. |
| Modular Skid Deployment Partnership | Containerized reverse osmosis units match hyperscale tenants' lease flexibility preferences in Western Region edge expansion. |
| Seawater Cooling Infrastructure Development | Dammam coastal access bypasses MEE groundwater withdrawal caps constraining inland competitors. |
| Dielectric Fluid Formulation Licensing | Proprietary direct-to-chip coolant chemistry locks in recurring supply relationships with AI training cluster operators. |
Research Methodology
A standing panel of data center engineering directors, MEE compliance officers, membrane technology procurement leads, and hyperscale facility operations managers provided ongoing calibration against primary field observations. Secondary validation drew from SASO efficiency mandate documentation, SFDA pharmaceutical water standard filings, NEOM regulatory sandbox disclosures, and customs records for cooling equipment imports. Bottom-up facility-level consumption modeling triangulated against top-down Kingdom-wide capacity projections.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning service type, end-user archetype, cooling technology generation, and compute workload thermal profile. CAGRs derived from facility-level deployment timelines, MEE permit issuance patterns, and hyperscale tenant pre-commitment disclosures. Liquid cooling adoption curves and closed-loop recycling validation milestones served as primary forecast sensitivity inputs.
Practitioners should monitor NEOM crystallizer performance validation, SASO benchmark tightening announcements, and stc procurement SLA unbundling patterns for early signals requiring forecast revision. Cross-checking against MEE withdrawal permit issuance databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market