
 Artificial Intelligence Platform Market | 2026-2036
Artificial Intelligence Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence Platform Market Intelligence
The substitution of general-purpose CPUs with specialized silicon like GPUs and TPUs for large-scale model training is recalibrating the unit economics of AI development. NVIDIA currently dominates the supply of accelerator hardware essential for complex machine learning tasks. Meanwhile, Google Cloud leverages its proprietary Tensor Processing Units to offer differentiated performance for its platform users. Microsoft positions its Azure cloud services by integrating advanced hardware from multiple vendors to support diverse enterprise AI workloads.
An Artificial Intelligence Platform provides an integrated suite of software tools, application programming interfaces, and infrastructure to build, deploy, and manage AI models. These platforms typically support popular frameworks like TensorFlow and PyTorch, enabling developers to streamline the machine learning lifecycle. Within solution offerings, Machine Learning and Natural Language Processing capabilities represent the largest and most mature segments. While Public Cloud remains the dominant deployment model, Hybrid Cloud solutions are gaining significant traction among enterprises seeking greater control over sensitive data.
Regulatory frameworks like the EU AI Act, directives from China's MIIT, and voluntary AI safety commitments in the United States are establishing new rules for development and deployment. These policies directly influence data governance protocols, model transparency standards, and market access requirements for platform providers. Stakeholders must now balance rapid innovation with the need to ensure compliance across divergent and evolving international legal landscapes.
Market Dynamics
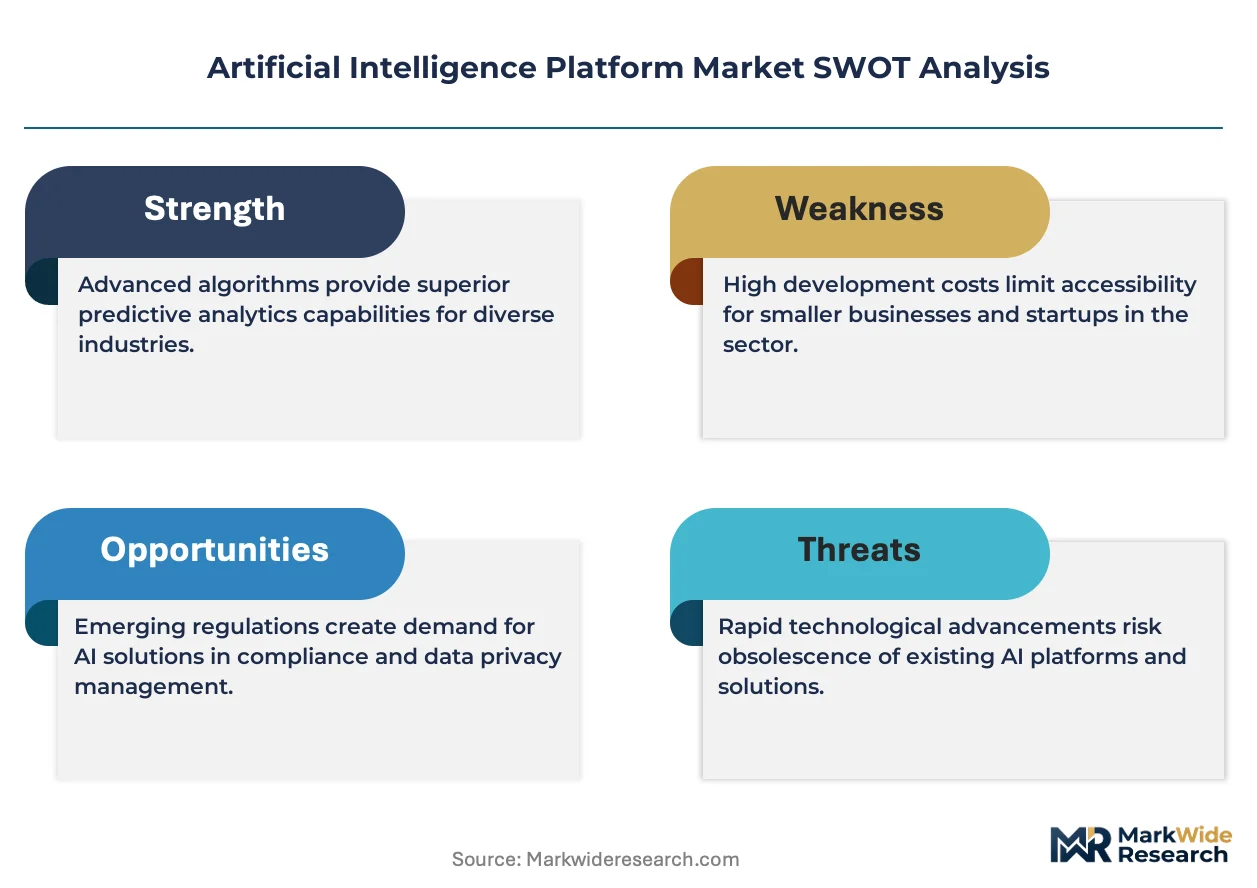
The primary structural force shaping the market is the dual pressure of explosive computational demand for foundational models and the concurrent rise of global regulatory frameworks. This dynamic forces platform providers to secure scarce, specialized hardware while simultaneously engineering for compliance with divergent standards like the EU AI Act.
Growth Catalysts
- Specialized Hardware Economics:The proliferation of GPUs and custom accelerators like TPUs improves the unit economics for training large models, making advanced AI capabilities more accessible to a wider range of developers and enterprises.
- BFSI Sector Demand:Financial services institutions are a primary demand driver, seeking platform capabilities for real-time fraud detection, credit risk modeling, and algorithmic trading, which necessitates sophisticated machine learning infrastructure.
- Regulatory Clarity:The emergence of comprehensive legal frameworks, exemplified by the EU AI Act, helps define development standards and accountability, which in turn builds enterprise confidence for larger-scale AI investments.
Market Restraints
- Accelerator Hardware Concentration:The supply of high-performance GPUs and other AI accelerators is highly concentrated among a few vendors, creating supply chain vulnerabilities and significant pricing power that can limit platform scalability.
- Data Sovereignty Conflicts:Divergent international regulations on data residency and cross-border data flows, such as Europe's GDPR, create significant architectural and compliance complexities for globally-oriented AI platforms.
- High Energy Consumption:The substantial electrical power required to train and operate large-scale AI models presents both a major operational cost and an environmental sustainability challenge, limiting deployment in certain regions.
Strategic Opportunities
- Vertical-Specific Platforms:Developing AI platforms tailored for regulated industries like life sciences, with pre-built components for drug discovery or clinical trial data analysis, offers a path to high-value differentiation.
- Hybrid Cloud Solutions:Enterprises are seeking hybrid cloud deployments to balance the scalability of public clouds with the security of on-premise infrastructure for sensitive data, creating an opportunity for flexible platform offerings.
- Edge AI Integration:Extending platform capabilities to manage and deploy models on edge devices opens new applications in autonomous vehicles, industrial IoT, and smart retail where low-latency processing is critical.
Industry Challenges
- MLOps Talent Gap:A critical shortage of engineers with expertise in Machine Learning Operations (MLOps) creates a bottleneck for enterprises attempting to operationalize and scale their AI initiatives beyond experimental phases.
- Legacy System Integration:Connecting modern AI platforms to existing enterprise resource planning systems and decades-old data architectures is a significant technical hurdle that slows down adoption and time-to-value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence Platform Market |
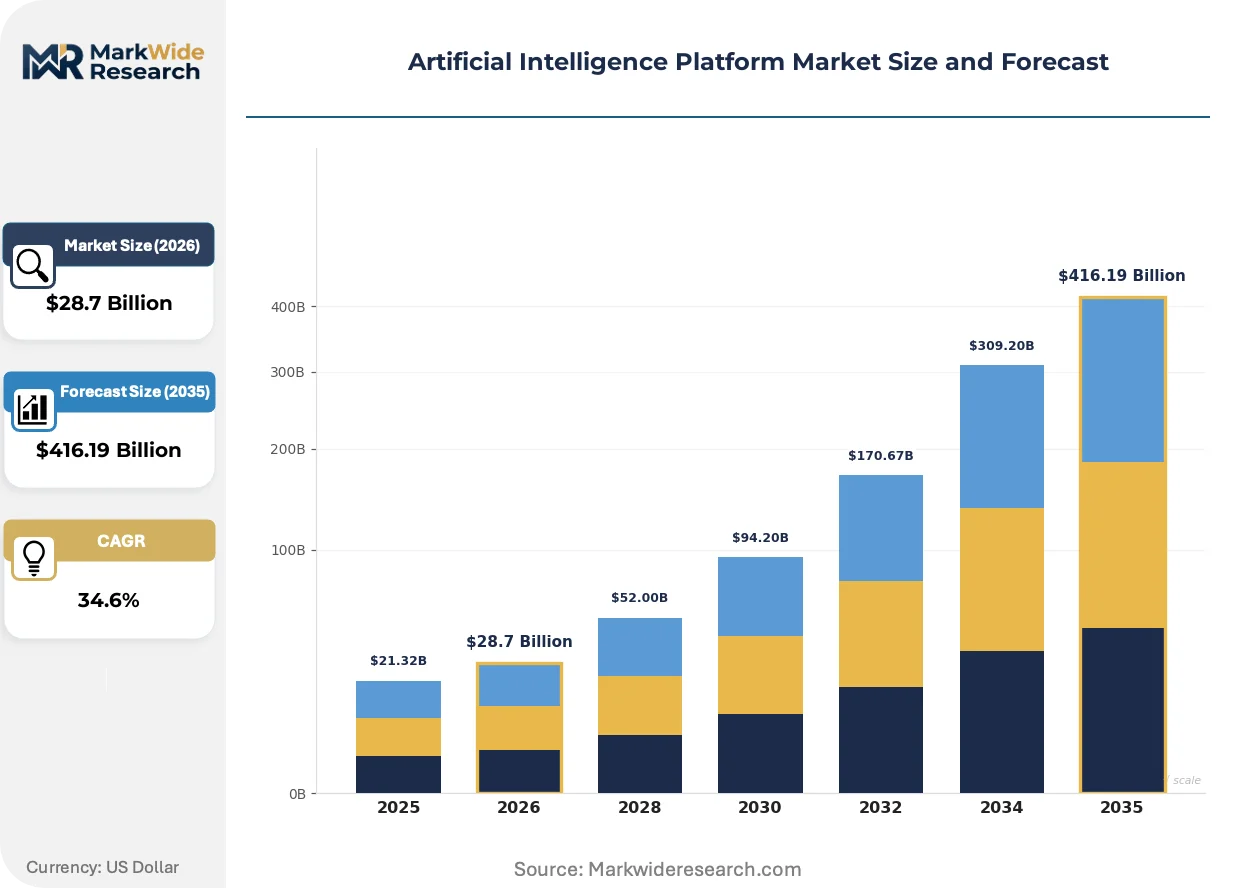
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $416.19 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Solution Offering: Machine Learning, Natural Language Processing, Computer Vision, Robotics Process Automation, Speech Recognition Use Case: Fraud Detection, Predictive Maintenance, Customer Analytics, Supply Chain Optimization, Quality Control End User Industry: BFSI, Telecom, Manufacturing, Government, Education |
| Companies Covered | NVIDIA, Meta Platforms, Microsoft, Palantir, IBM, Amazon, Google Cloud, Databricks, Alphabet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence Platform Market Strategic Shifts & Innovations
The market's focus is pivoting from raw model performance toward the industrialization of the entire AI development lifecycle. This shift prioritizes efficiency, governance, and the seamless integration of AI capabilities into core business processes, moving beyond isolated data science projects.
MLOps platforms provide a unified toolkit for automating the build, test, and deployment phases of the machine learning lifecycle. Enterprises across the financial and e-commerce sectors are adopting these tools to manage model performance and ensure algorithmic reproducibility. The adoption of MLOps is consolidating the previously fragmented set of point solutions for data versioning and model monitoring into integrated platform suites.
Regulatory mandates like the EU AI Act are establishing risk-based classifications that impose stringent requirements on high-risk systems. This policy directly influences platform architecture, requiring auditable data governance, model transparency logs, and human-in-the-loop oversight protocols. Platform providers targeting the European Union are consequently embedding features for explainability and bias detection directly into their core offerings to ensure compliance.
A change in enterprise AI strategy from building bespoke models to fine-tuning pre-trained foundation models is altering procurement patterns. This movement away from long, consultant-led development cycles favors platforms that provide access to model libraries and efficient fine-tuning APIs. The trend is most prominent within the United States, particularly in the technology and media sectors that are rapidly leveraging large language models.
Artificial Intelligence Platform Market Segmentation
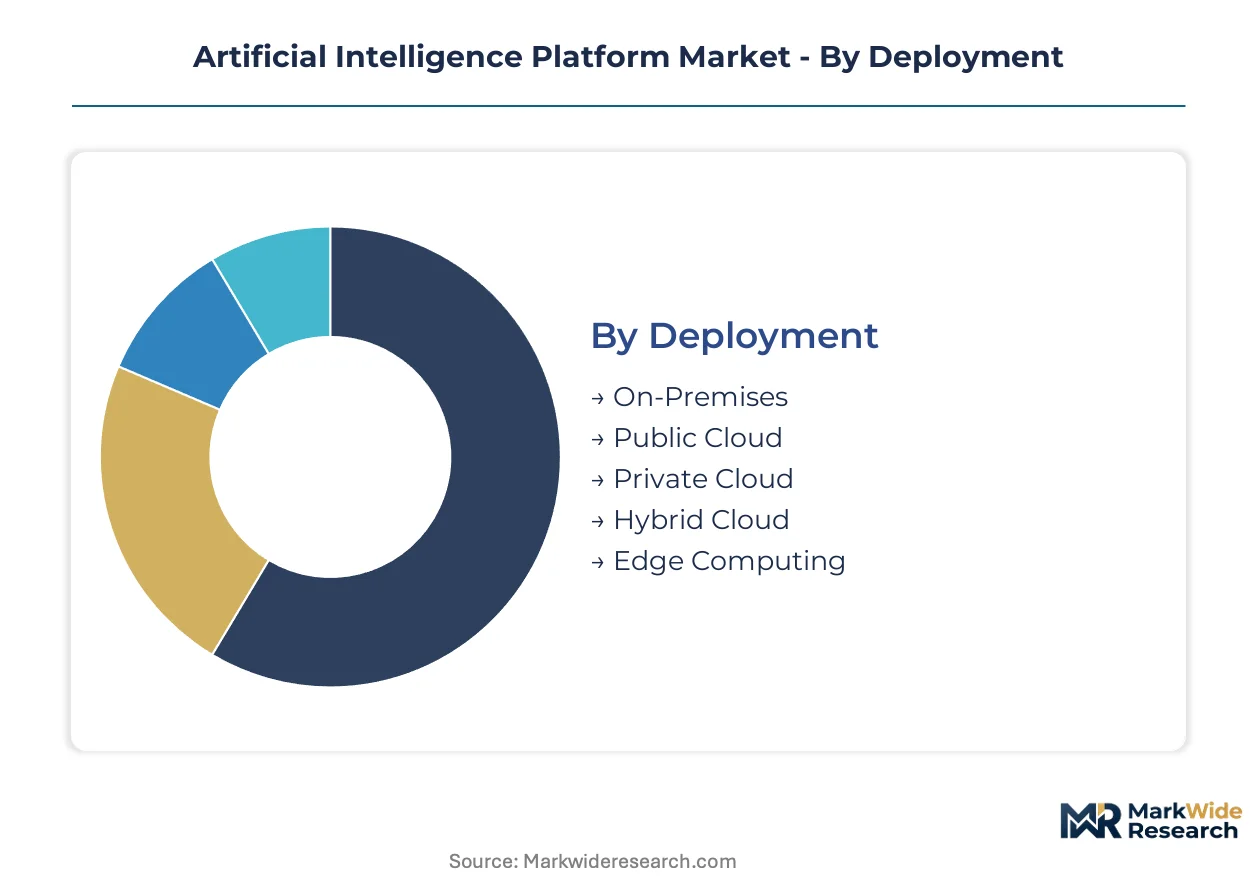
The Artificial Intelligence Platform market segments across diverse deployment models, solution offerings, use cases, and end-user industries. Understanding these distinctions is critical for providers to tailor their offerings effectively and for enterprises to align platform capabilities with specific operational requirements. This segmentation highlights the varied adoption patterns and technological preferences across the global landscape.
Deployment:
The upgrade and replacement cycles for IT infrastructure heavily influence the adoption of different AI platform deployment models. Enterprises are continuously evaluating the balance between control, scalability, and cost efficiency when integrating AI capabilities into their existing systems.
- Hybrid Cloud:This model combines public and private cloud environments, retaining sensitive data on-premises while using public cloud scalability. Regulated sectors, including finance and healthcare, adopt hybrid solutions for data sovereignty and compliance.
- Public Cloud:Public cloud deployments offer immense scalability and reduced upfront costs, with major providers leading this space. Technology and media sectors in the United United States frequently utilize public cloud platforms for rapid development and deployment.
- On-Premises:On-premises deployments host AI platforms within data centers for maximum data control.
- Private Cloud:Private cloud solutions offer dedicated infrastructure for a single organization, preferred by enterprises with stringent security.
- Edge Computing:Edge computing extends AI model deployment to devices closer to data sources, enabling low-latency processing.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Hybrid Cloud.
Solution Offering:
The inherent application capabilities of AI platforms drive their adoption across various business functions and technical requirements. Each solution offering addresses distinct challenges, from processing unstructured text to automating complex visual tasks.
- Machine Learning:Machine learning capabilities form the core of AI platforms, providing tools for pattern recognition and prediction. The BFSI sector relies on machine learning for credit risk modeling and fraud detection.
- Natural Language Processing:NLP solutions enable platforms to understand and generate human language, facilitating sentiment analysis and chatbots. E-commerce platforms leverage NLP for enhanced customer service and personalized recommendations.
- Computer Vision:Computer vision enables machines to interpret visual information, used in quality control and security surveillance.
- Robotics Process Automation:RPA integrates AI to automate repetitive business processes, streamlining back-office operations.
- Speech Recognition:Speech recognition converts spoken language into text, essential for voice assistants and transcription.
Natural Language Processing solutions are currently gaining share fastest, while Machine Learning maintains the largest installed base.
Use Case:
The specific customer types and their operational needs dictate the most impactful AI platform use cases. Enterprises prioritize solutions that directly address their most pressing business challenges and offer clear return on investment.
- Fraud Detection:AI platforms for fraud detection analyze transactional data in real-time to identify anomalous patterns and prevent financial losses. Financial institutions in Europe deploy these systems to comply with anti-money laundering regulations.
- Customer Analytics:Customer analytics solutions leverage AI to process vast customer data, providing insights into behavior and preferences. Retailers in the United States utilize these platforms to optimize product recommendations and improve engagement.
- Predictive Maintenance:Predictive maintenance uses AI to forecast equipment failures, allowing proactive servicing.
- Supply Chain Optimization:AI platforms optimize supply chain logistics by predicting demand and managing inventory.
- Quality Control:AI-powered quality control systems use computer vision to inspect products for defects.
Fraud Detection represents a significant volume of deployments, while Customer Analytics exhibits a steeper expansion trajectory.
End User Industry:
The maturity of AI adoption within different end-user industries significantly shapes the demand for specialized platform features and services. Industries with complex data landscapes and high regulatory burdens often require more tailored AI solutions.
- BFSI:The BFSI sector is a primary driver for AI platform adoption, leveraging AI for fraud detection and risk assessment. Major banks in London and New York invest heavily in advanced AI platforms for competitive advantage.
- Manufacturing:Manufacturing firms deploy AI platforms for predictive maintenance, quality control, and supply chain optimization to enhance operational efficiency. German automotive manufacturers integrate AI into production lines for greater precision.
- Telecom:The telecom sector uses AI for network optimization and customer service automation.
- Government:Government agencies adopt AI platforms for data analysis and public service delivery.
- Education:Educational institutions utilize AI for personalized learning and administrative automation.
BFSI maintains the largest market share, with Manufacturing climbing the fastest in AI platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Artificial Intelligence platforms concentrates heavily within established technology hubs and rapidly industrializing economies. These regions drive innovation in AI development and deployment, responding to both market opportunities and regulatory pressures. Major cloud providers and research institutions anchor these centers, influencing global adoption patterns.
United States
Enterprises in the United States prioritize AI platforms for customer analytics and large language model fine-tuning. The National Institute of Standards and Technology (NIST) AI Risk Management Framework guides responsible AI development. Silicon Valley and Seattle serve as major centers for cloud providers and AI research, fostering rapid platform innovation.
China
China's market requires AI platforms for industrial automation and smart city initiatives. Directives from China's MIIT shape AI development standards and data governance protocols. Technology clusters in Beijing and Shenzhen drive significant investment in AI infrastructure and applications.
Germany
Manufacturing firms in Germany integrate AI platforms for predictive maintenance and quality control. The EU AI Act establishes stringent requirements for high-risk AI systems, influencing platform design. Munich and Berlin are key innovation hubs for industrial AI and automotive sector applications.
United Kingdom
The BFSI sector in the United Kingdom drives demand for AI platforms in fraud detection and risk modeling. The UK government's AI strategy emphasizes ethical AI principles and responsible innovation. London's financial district accelerates the adoption of advanced AI solutions for competitive advantage.
India
India's market leverages AI platforms for customer analytics and digital transformation across various sectors. The country's national cybersecurity policies influence data handling and platform security requirements. Bengaluru and Hyderabad emerge as prominent AI development centers, attracting significant tech investments.
Artificial Intelligence Platform Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with the Artificial Intelligence Platform market exhibiting a tiered structure. Large cloud providers offer comprehensive platforms, while specialized vendors focus on niche solutions. Strategic archetypes include integrated platform providers, hardware-accelerator developers, and MLOps tool specialists. These players primarily engage in strategic partnerships to expand ecosystem reach and invest in portfolio diversification to address evolving enterprise needs.
Within the platform ecosystem, NVIDIA exemplifies a dominant hardware-accelerator developer, providing essential specialized silicon for complex machine learning tasks. Microsoft, through its Azure cloud services, represents an integrated platform provider, leveraging advanced hardware from multiple vendors to support diverse enterprise AI workloads. Google Cloud, with its proprietary Tensor Processing Units, occupies a position as a differentiated performance provider for its platform users, anchoring innovation in custom AI silicon. These companies often drive market direction through continuous R&D and strategic collaborations.
| Leading Market Players |
|---|
| NVIDIA |
| Meta Platforms |
| Microsoft |
| Palantir |
| IBM |
| Amazon |
| Google Cloud |
| Databricks |
| Alphabet |
| Others |
Cost & Logistics Intelligence
Large cloud providers and hyperscale enterprises often drive pricing structures, demanding performance-based models for their extensive AI platform deployments. This concentration of significant buying power influences platform providers to offer tiered subscription models with volume discounts.
Pricing Analysis
Volume-driven platform sales often feature tiered subscription models, while specialized AI services command higher margins through value-based pricing. Pricing differentiation stems from proprietary hardware integration and the level of managed services offered to enterprises. Pricing softness reflects intense competition among platform providers and the commoditization of basic AI capabilities. Startups and small businesses exhibit higher price sensitivity, prioritizing cost-effective public cloud options for foundational AI tools.
Supply Chain Analysis
Direct-to-enterprise distribution models handle the bulk of AI platform deployments, especially for large-scale cloud services and customized solutions. Geographic supply concentration for critical AI accelerators centers on Taiwan for advanced chip manufacturing and the United States for design and proprietary silicon. The supply chain relies heavily on advanced semiconductors and specialized memory components. Accelerator hardware concentration among a few vendors presents a structural risk for platform scalability and cost stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Artificial Intelligence Platform market is supply-constrained, with the limited availability of specialized AI accelerator production capacity propping up hardware pricing. This bottleneck impacts platform providers' ability to scale offerings and meet burgeoning demand.
For Market Incumbents: Deploy strategic R&D investment to diversify sourcing for specialized AI accelerators, reducing single-vendor dependency. Integrate advanced compliance features and auditable data governance tools directly into core platform offerings to mitigate regulatory threats. Expand ecosystem partnerships with MLOps specialists to offer comprehensive lifecycle management solutions, addressing the MLOps talent gap. Focus on developing proprietary silicon capabilities to differentiate performance and control supply.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized platforms focusing on explainability, bias detection, and robust data governance for high-risk applications. Target vertical-specific platforms in regulated industries like life sciences, offering pre-built components for drug discovery or clinical trial analysis. A go-to-market angle focusing on hybrid cloud deployments addresses enterprise demand for data sovereignty and control over sensitive workloads. Provide niche MLOps solutions for specific compliance requirements.
For Investors and Strategic Acquirers: The window for entry favors long-term growth-oriented investors seeking foundational technology plays over the next 5-10 years. Target acquisition archetypes include MLOps tool specialists and providers of vertical-specific AI solutions with strong data governance intellectual property. A key signal to watch for inflection is the increased enterprise spending on AI governance and model operationalization tools, indicating broader adoption beyond experimental phases.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop proprietary AI accelerators | Enhances platform performance and reduces reliance on external hardware vendors. |
| Integrate advanced compliance features | Ensures adherence to evolving global regulations like the EU AI Act. |
| Expand MLOps ecosystem partnerships | Addresses the critical talent gap in machine learning operations for enterprises. |
| Target vertical-specific platform solutions | Captures high-value demand in regulated industries with tailored offerings. |
| Invest in hybrid cloud deployment capabilities | Balances scalability with enterprise data control and security requirements. |
Research Approach
Government technology directives, academic research papers, and SEC filings of major cloud providers formed the secondary backbone of this analysis. This was complemented by primary interviews with AI platform architects, enterprise IT procurement leads, data scientists, and regulatory compliance officers. Both bottom-up and top-down triangulation were applied to ensure data consistency and accuracy across all market segments.
Historical trendline analysis established the trajectory of AI platform adoption and technological evolution across the analysis window. The analytical framework modeled key segmentation dimensions including deployment model, solution offering, use case, end-user industry, and regulatory compliance requirements. Compound annual growth rates were derived by factoring in market expansion drivers and industry-specific forecast inputs such as AI model size growth trends.
Caveats apply where shifts in regulatory frameworks or significant technological breakthroughs could materially shift the outlook for the Artificial Intelligence Platform market. Forecasts reflect assumptions regarding specialized hardware availability and enterprise AI investment patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Semantic Web Market