
 Singapore System Integration Market | 2026-2036
Singapore System Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore System Integration Market Insights
Enterprise buyers in financial services and healthcare are redrawing procurement priorities for system integration. ST Engineering leverages its defense-to-civilian technology pipeline to anchor large-scale infrastructure projects. Ensign InfoSecurity specializes in cybersecurity-embedded integration, occupying a defensive niche as threat surfaces expand. Johnson Controls competes on building-to-digital convergence, extending its position in smart facility integration across commercial estates.
Singapore system integration encompasses the engineering and orchestration of disparate hardware, software, and network subsystems into unified operational environments, typically involving API mediation, middleware configuration, and real-time data synchronization across heterogeneous IT estates. Its primary purpose is to eliminate information silos, automate cross-platform workflows, and enable centralized monitoring for enterprise and government clients. Cloud integration services are leading current project pipelines as agencies and banks migrate legacy workloads to sovereign cloud architectures. API management and security solutions within the technology dimension command premium margins due to compliance complexity and vendor certification requirements. Implementation services dominate service-type revenue volumes, though maintenance contracts are lengthening as clients prioritize operational continuity over discrete deployment cycles.
Singapore's Infocomm Media Development Authority (IMDA) shapes vendor qualification through accreditation frameworks that filter market access for government and critical infrastructure contracts. The Monetary Authority of Singapore (MAS) imposes technology risk management guidelines that mandate integrated audit trails and resilience testing for financial system integrations. Enterprise stakeholders must weigh vendor alignment with IMDA accreditation tiers against the specialized domain expertise required for sector-specific compliance regimes.
Market Dynamics
Sovereign cloud migration mandates from Singapore's IMDA and MAS are compressing procurement cycles for system integration vendors, forcing accelerated certification timelines and API-security bundling requirements across financial and government verticals.
Growth Catalysts
- MAS Technology Risk Management Guidelines:Financial institutions must maintain integrated audit trails and resilience testing, creating mandatory integration spend across banking and insurance sectors.
- Smart Nation Sensor Platform:Government agencies are deploying unified IoT data layers across transport, utilities, and public safety networks, requiring extensive middleware orchestration.
- API-first architecture adoption:Enterprise IT teams are retiring point-to-point integrations in favor of microservices mesh patterns, expanding demand for mediation layer specialists.
Market Restraints
- Certified talent scarcity:IMDA-accredited solution architects and MAS-compliant security engineers command premium compensation, inflating project delivery costs by 25-40% versus regional alternatives.
- Sovereign cloud vendor concentration:Government contracts restrict eligible infrastructure providers to three accredited platforms, limiting client negotiation leverage and architectural flexibility.
- Legacy mainframe dependency:Core banking systems running on IBM z/OS and Unisys Dorado resist containerization, forcing expensive emulation layers that erode cloud migration ROI.
Strategic Opportunities
- Jurong Innovation District expansion:Advanced manufacturing clusters in western Singapore require OT-IT convergence for predictive maintenance and digital twin deployment.
- Healthcare AI integration:SingHealth and National University Hospital systems are embedding diagnostic algorithms into electronic medical record workflows, creating demand for HIPAA-equivalent data pipeline engineering.
- Green building integration:BCA Green Mark certification mandates are driving smart facility retrofits that combine energy management, access control, and occupancy analytics into unified dashboards.
Industry Challenges
- Cross-domain certification timelines:Vendors must simultaneously maintain IMDA accreditation, MAS TRM compliance, and ISO 27001 certification, with renewal cycles creating administrative overhead that delays project staffing.
- Interoperability debt accumulation:Decades of bespoke ERP customizations in Singapore's trading houses and family offices resist standard API mapping, requiring expensive reverse-engineering before cloud migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore System Integration Market |
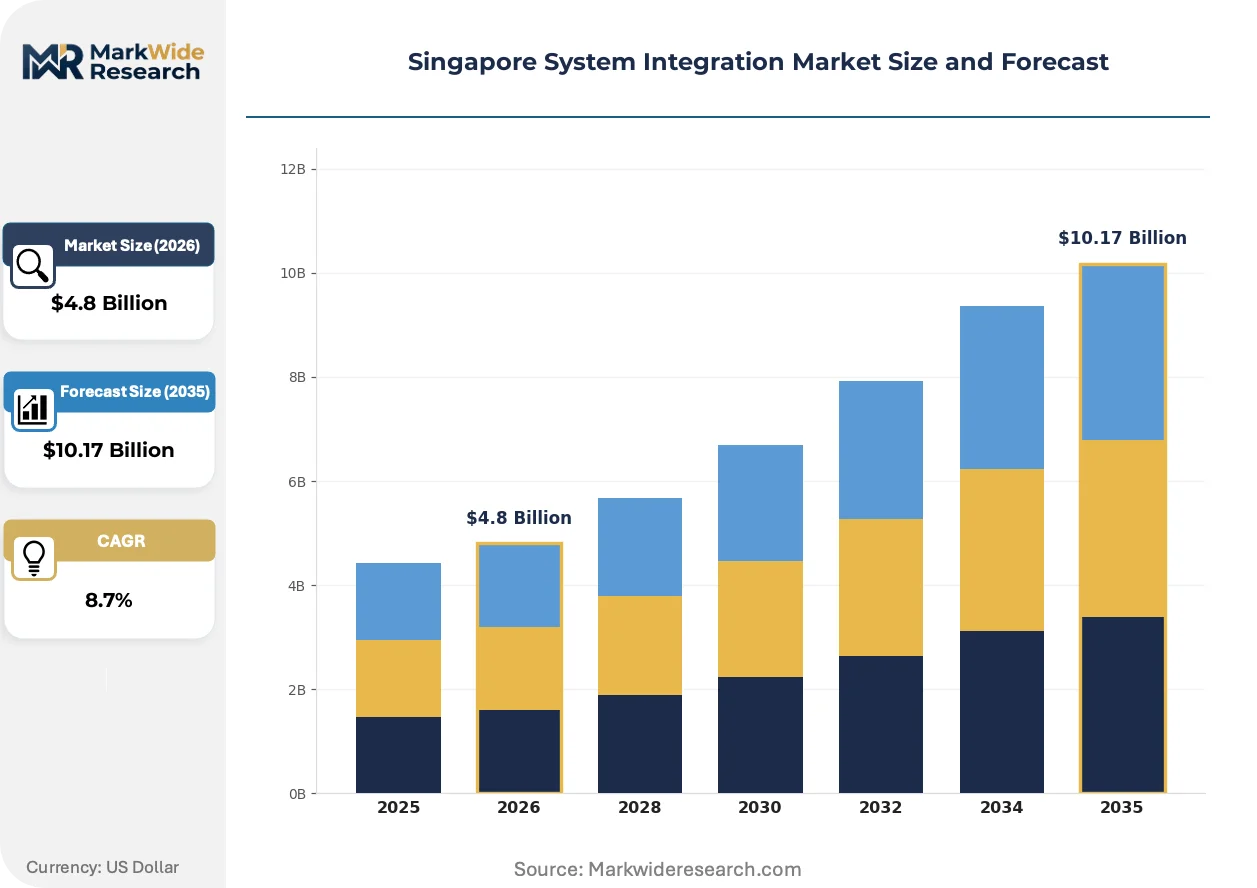
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cloud Integration, Enterprise Resource Planning, Data Integration, IT Infrastructure End User: Healthcare Providers, Financial Institutions, Retailers, Manufacturing Firms Technology: API Management, Middleware, Automation Tools, Security Solutions Service Type: Consulting Services, Support Services, Implementation Services, Maintenance Services |
| Companies Covered | ST Engineering, Win-Pro Consultancy Pte Ltd, Edvantis, Ensign InfoSecurity, Johnson Controls, Slash, Atta Systems, IT BLOCK PTE. LTD., AsiaCloud Solutions Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore System Integration Market Trends and Innovations
Integration architecture is pivoting from centralized enterprise service buses toward distributed mesh patterns that accommodate edge computing and real-time analytics requirements across Singapore's island-wide sensor networks.
Event-driven architecture is fragmenting traditional request-response integration patterns. Financial services teams at DBS and OCBC are deploying Apache Kafka and Pulsar clusters to stream transaction data across fraud detection, customer analytics, and regulatory reporting systems in sub-100-millisecond windows. This shift is compressing the addressable market for conventional batch-oriented middleware vendors while expanding specialist consulting around stream processing optimization.
IMDA's Digital Infrastructure Act is mandating operational technology cybersecurity standards for critical infrastructure operators. Energy, water, and transport agencies must now implement zero-trust network segmentation with continuous monitoring, forcing integration vendors to embed micro-segmentation controllers and SIEM connectors into every deployment. Healthcare providers face parallel pressure from MOH cybersecurity directives that require equivalent controls for connected medical devices.
Enterprise buyers are unbundling long-term maintenance contracts from initial implementation fees. Government agencies and GLCs now prefer 3-year service agreements with explicit SLA penalties rather than decade-long vendor lock-in, compressing recurring revenue visibility for system integrators. This pattern is most pronounced in the central business district, where property management firms and trading houses negotiate separate support contracts with niche cybersecurity specialists rather than incumbent infrastructure providers.
Singapore System Integration Market Segmentation
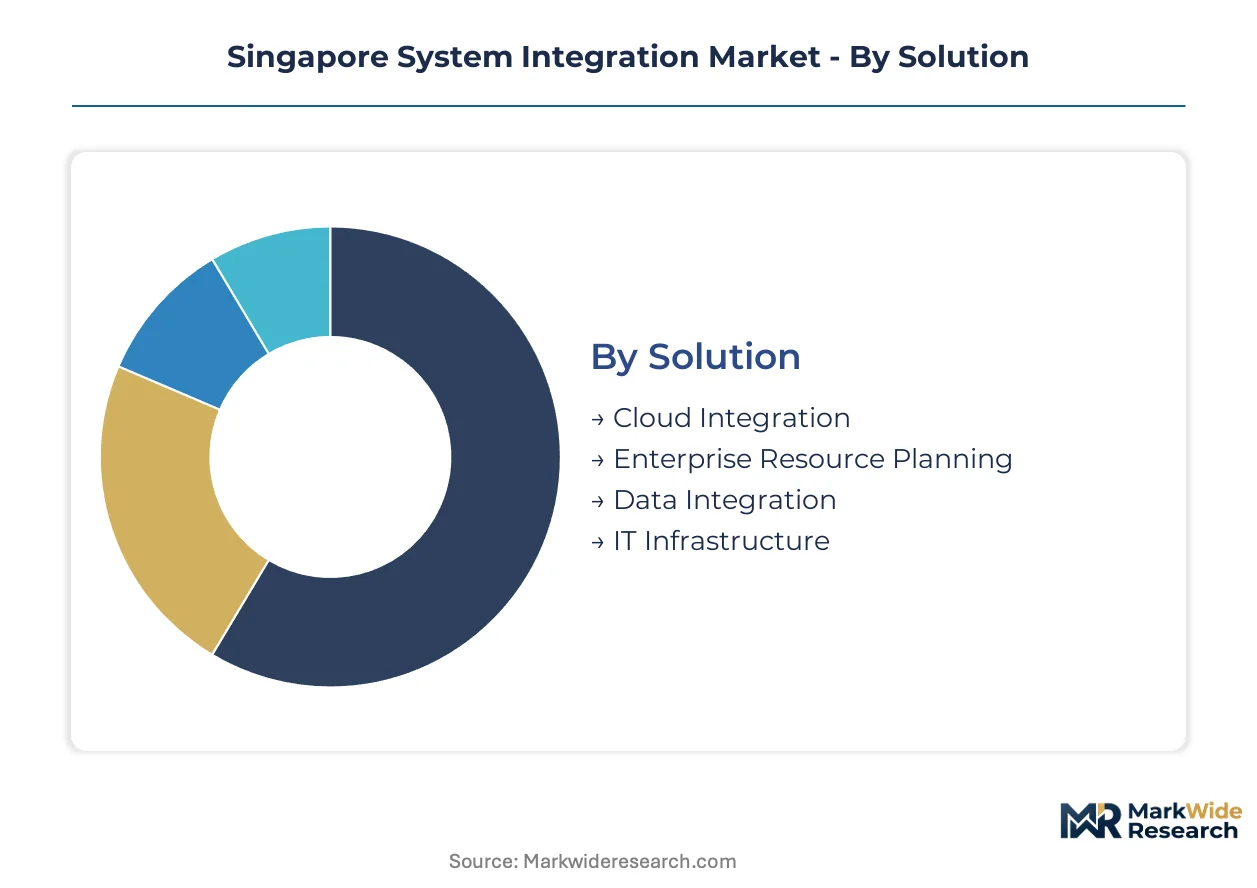
Singapore's system integration market fragments across solution architectures, regulatory compliance tiers, and service delivery models. Understanding these dimensions reveals how IMDA accreditation requirements and MAS technology risk mandates reshape vendor positioning and procurement patterns across financial, healthcare, and government verticals.
Solution:
IMDA's sovereign cloud certification tiers and MAS technology risk management guidelines create divergent compliance burdens across solution categories, with financial institutions facing stricter audit trail requirements than retail or manufacturing counterparts.
- Cloud Integration:Orchestrates workload migration and hybrid infrastructure management across government-accredited sovereign platforms. DBS and OCBC are compressing procurement cycles for API-security bundled implementations as MAS mandates accelerate certification timelines.
- Enterprise Resource Planning:Unifies finance, supply chain, and human capital modules through middleware layers that bridge SAP, Oracle, and legacy mainframe estates. Trading houses in the central business district require expensive reverse-engineering of decades-old bespoke customizations before cloud migration.
- Data Integration:Engineers real-time synchronization pipelines between operational and analytical systems.
- IT Infrastructure:Deploys compute, storage, and network virtualization across on-premise and edge environments.
Established volume favors Enterprise Resource Planning; emerging adoption favors Cloud Integration.
End User:
Customer procurement authority concentrates in regulated sectors where compliance failure carries license revocation risk, elevating solution architect compensation premiums by 25-40% above regional benchmarks.
- Financial Institutions:Banks, insurers, and asset managers must maintain integrated audit trails and resilience testing under MAS Technology Risk Management Guidelines. Mandatory integration spend across this vertical creates defensive moats for IMDA-accredited vendors with parallel cybersecurity credentials.
- Healthcare Providers:SingHealth and National University Hospital systems embed diagnostic algorithms into electronic medical record workflows. MOH cybersecurity directives mandate zero-trust segmentation for connected medical devices, expanding demand for HIPAA-equivalent data pipeline engineering.
- Retailers:Omnichannel merchants unify point-of-sale, inventory, and customer analytics platforms.
- Manufacturing Firms:Jurong Innovation District clusters pursue OT-IT convergence for predictive maintenance.
Financial Institutions command premium pricing; Healthcare Providers are expanding most quickly.
Technology:
Margin concentration follows architectural complexity, with security-embedded integration commanding superior returns than commodity middleware configuration.
- API Management:Mediates microservices mesh patterns replacing point-to-point integrations across DBS and OCBC transaction streaming architectures. Apache Kafka and Pulsar deployments for sub-100-millisecond fraud detection are compressing the addressable market for batch-oriented middleware vendors.
- Security Solutions:Embeds zero-trust network segmentation, SIEM connectors, and continuous monitoring into every deployment. IMDA's Digital Infrastructure Act mandates these controls for energy, water, and transport agencies, creating defensive pricing power for accredited specialists.
- Middleware:Configures message brokers and enterprise service buses for legacy system interoperability.
- Automation Tools:Orchestrates robotic process automation and workflow engines across heterogeneous IT estates.
Middleware retains established volume; Security Solutions are gaining share fastest.
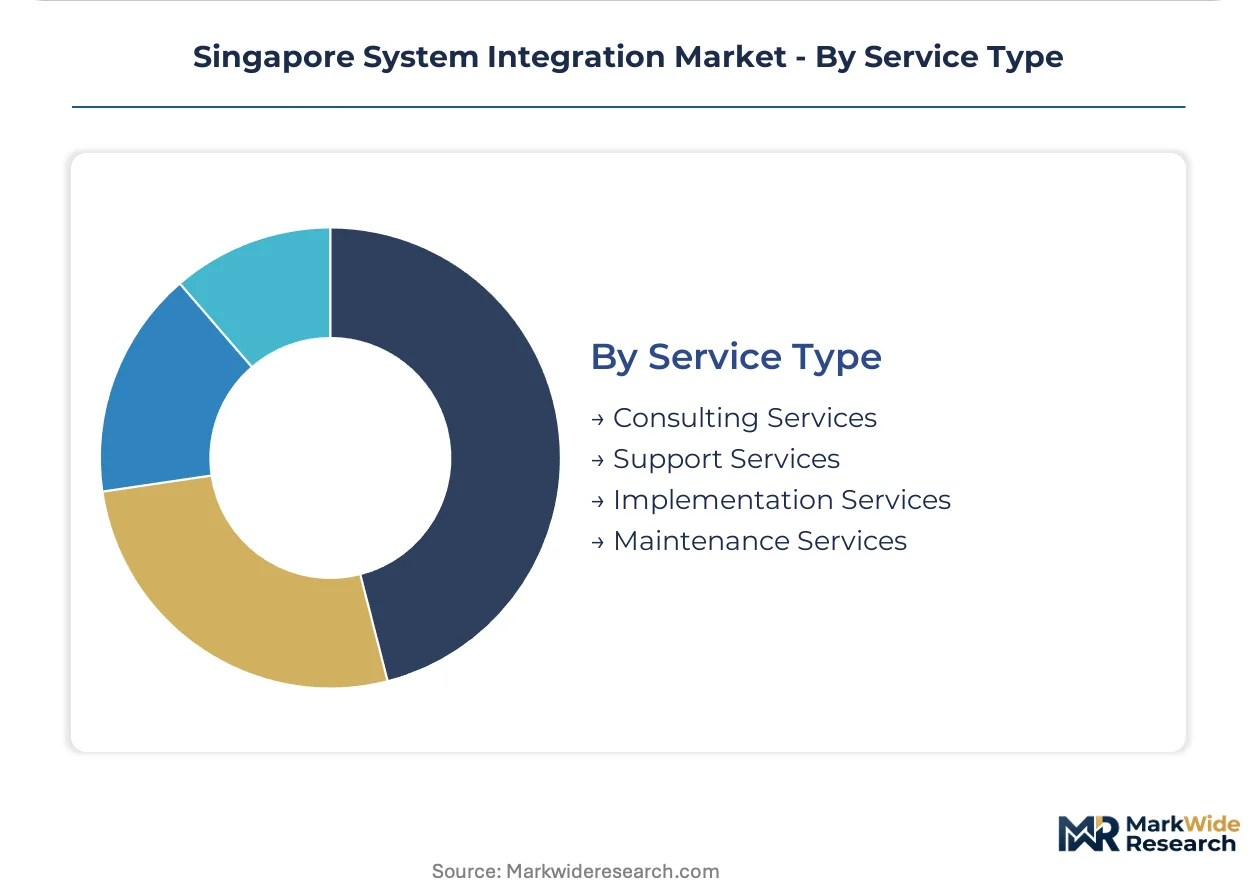
Service Type:
Government agencies and GLCs are unbundling long-term maintenance from implementation fees, compressing recurring revenue visibility for system integrators.
- Implementation Services:Dominates revenue volumes through discrete deployment of integration platforms, middleware configuration, and API mediation layers. Project pipelines concentrate in cloud migration and cybersecurity-embedded integration across the central business district and Jurong corridor.
- Maintenance Services:Contracts are lengthening as clients prioritize operational continuity over discrete deployment cycles. Property management firms now negotiate separate 3-year service agreements with explicit SLA penalties rather than decade-long vendor lock-in.
- Consulting Services:Advises on architecture design, vendor selection, and compliance roadmap planning.
- Support Services:Delivers break-fix remediation and technical helpdesk operations.
Implementation Services anchor current revenue; Maintenance Services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
System integration demand concentrates in Singapore's central business district and Jurong Innovation Corridor, where financial institutions and advanced manufacturing clusters drive procurement. The island-state's Smart Nation initiative and IMDA accreditation frameworks filter vendor access, creating localized supply constraints. Sub-regional variation reflects sectoral specialization across commercial, industrial, and government estates.
Central Business District
Financial services and trading houses anchor demand for cloud integration and API management solutions. MAS Technology Risk Management Guidelines mandate integrated audit trails and resilience testing across banking and insurance verticals. DBS and OCBC deploy Apache Kafka clusters for sub-100-millisecond transaction streaming, compressing procurement cycles for cybersecurity-embedded integration vendors.
Jurong Innovation Corridor
Advanced manufacturing clusters pursue OT-IT convergence for predictive maintenance and digital twin deployment. IMDA's sovereign cloud certification tiers restrict eligible infrastructure providers to three accredited platforms, limiting architectural flexibility. Pharmaceutical and precision engineering facilities require middleware orchestration for heterogeneous equipment estates.
One-North and Buona Vista
Biomedical research institutions and technology startups drive demand for HIPAA-equivalent data pipeline engineering. SingHealth and National University Hospital systems embed diagnostic algorithms into electronic medical record workflows. MOH cybersecurity directives mandate zero-trust segmentation for connected medical devices across this research precinct.
Punggol Digital District
Smart facility retrofits combine energy management, access control, and occupancy analytics into unified dashboards. BCA Green Mark certification mandates accelerate building-to-digital convergence across commercial estates. Government agencies negotiate 3-year service agreements with explicit SLA penalties rather than decade-long vendor lock-in.
Tampines Regional Centre
Retail and logistics operations unify point-of-sale, inventory, and customer analytics platforms through omnichannel integration. Event-driven architecture replaces batch-oriented middleware as enterprise IT teams retire point-to-point integrations. Property management firms source separate support contracts with niche cybersecurity specialists.
Singapore System Integration Market Competitive Landscape
Concentration sits with defense-to-civilian technology pipelines and cybersecurity-embedded specialists. The vendor base spans engineering conglomerates, information security firms, and building automation providers competing on compliance credentials and IMDA accreditation tiers. Three archetypes dominate: infrastructure-scale integrators with government relationships, security-first boutiques with MAS TRM expertise, and smart facility specialists with BCA Green Mark alignment. Competitive moves center on certification maintenance across overlapping regulatory regimes and unbundling of maintenance contracts from implementation fees.
Within the infrastructure-scale tier, ST Engineering anchors large-scale government and critical infrastructure projects through its defense technology pipeline. Ensign InfoSecurity occupies the security-embedded niche, leveraging MAS compliance requirements to command premium positioning as threat surfaces expand. Johnson Controls exemplifies the building-to-digital convergence archetype, extending its presence across smart facility retrofits driven by BCA certification mandates. Win-Pro Consultancy and Edvantis sit within the mid-market implementation segment, competing on project delivery velocity for cloud migration and API management engagements.
| Leading Market Players |
|---|
| ST Engineering |
| Win-Pro Consultancy Pte Ltd |
| Edvantis |
| Ensign InfoSecurity |
| Johnson Controls |
| Slash |
| Atta Systems |
| IT BLOCK PTE. LTD. |
| AsiaCloud Solutions Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Ninety-day certification timelines for IMDA-accredited solution architects compress vendor staffing flexibility and inflate project delivery costs by 25-40% versus regional alternatives, concentrating pricing power with accredited specialists who can guarantee compliance-ready deployment teams.
Pricing Analysis
MAS Technology Risk Management Guidelines dictate the pricing tier structure across Singapore's system integration market, separating IMDA-accredited specialists with parallel cybersecurity credentials from uncertified implementation providers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the mid-market tier is intensifying because government agencies now unbundle long-term maintenance contracts and negotiate separate 3-year service agreements with explicit SLA penalties. Retail and logistics operations in Tampines Regional Centre exhibit the highest price sensitivity, while financial institutions in the central business district prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Just-in-time talent procurement dominates vendor staffing models, with IMDA-accredited solution architects and MAS-compliant security engineers sourced through contracted specialist networks rather than permanent benches. Singapore's system integration supply chain draws from India, the Philippines, and Malaysia for implementation capacity, while cybersecurity expertise concentrates domestically. Raw material dependencies include sovereign cloud infrastructure from three government-accredited platforms, API management software licenses, and SIEM connector hardware. Single-source vulnerability sits with the restricted sovereign cloud vendor pool, which limits client negotiation leverage. Distribution runs through direct enterprise sales teams for financial and government verticals, with channel partners handling mid-market retail and manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IMDA-accredited solution architects with cross-domain MAS and ISO 27001 certification command compensation premiums that outstrip supply growth, creating a persistent capability gap that reshapes competitive positioning toward compliance-guaranteed delivery rather than price-based procurement.
For Market Incumbents: Secure multi-year certification maintenance contracts with IMDA and MAS to lock in compliance credentials before renewal cycle bottlenecks intensify. Defend against boutique cybersecurity specialists by embedding zero-trust network segmentation capabilities into every implementation proposal, not just security-specific engagements. Vertical integration into accredited training pipelines for solution architects addresses the 25-40% cost inflation from external talent sourcing. For New Entrants and Emerging Players: Differentiate on OT-IT convergence expertise for Jurong Innovation District manufacturing clusters, where predictive maintenance and digital twin deployment demand outpaces established vendor capacity. Target healthcare AI integration for SingHealth and National University Hospital systems, where HIPAA-equivalent data pipeline engineering requirements exceed current specialist supply. White-space penetration succeeds through fixed-price API management implementations with explicit MAS TRM compliance guarantees rather than time-and-materials competition. For Investors and Strategic Acquirers: Carve-out targets emerge from defense-to-civilian technology pipelines and mid-market implementation boutiques with IMDA accreditation but limited cybersecurity credentials. Long-term viability across the projection horizon hinges on simultaneous maintenance of IMDA, MAS TRM, and ISO 27001 certification stacks, with renewal administrative overhead creating natural consolidation pressure. The signal to watch is government contract unbundling velocity—accelerated separation of implementation and maintenance awards indicates pricing power erosion for undifferentiated vendors.| Strategic Initiative | Industry Significance |
|---|---|
| IMDA Accreditation Investment | Filters market access for government and critical infrastructure contracts under IMDA's tiered certification framework. |
| MAS TRM Compliance Integration | Mandates integrated audit trails and resilience testing that elevate solution architect compensation premiums. |
| API-Security Bundling | Compresses procurement cycles for financial institutions deploying Apache Kafka clusters for sub-100-millisecond transaction streaming. |
| OT-IT Convergence Capability | Addresses predictive maintenance and digital twin deployment demand across Jurong Innovation District manufacturing clusters. |
| Zero-Trust Network Segmentation | Satisfies IMDA Digital Infrastructure Act mandates for energy, water, and transport agency deployments. |
Research Methodology
Initial hypotheses were tested against primary input from system integration project directors, IMDA accreditation officers, MAS technology risk compliance leads, and enterprise IT procurement managers at financial institutions and government agencies, and refined through secondary validation against IMDA policy circulars, MAS Technology Risk Management Guidelines, Smart Nation initiative progress reports, and BCA Green Mark certification databases. Bottom-up project pipeline analysis across the central business district and Jurong Innovation Corridor was triangulated with top-down vendor revenue segmentation.
Variance decomposition across solution architecture, regulatory compliance tier, and service delivery model dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included sovereign cloud migration velocity under IMDA mandates, API-first architecture adoption curves at DBS and OCBC, and maintenance contract unbundling patterns among government agencies and GLCs.
Material uncertainties — regulatory timeline acceleration, certified talent availability shocks, and sovereign cloud vendor pool expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued MAS TRM guideline enforcement and IMDA accreditation tier stability. Revision becomes warranted when cross-domain certification timeline compression exceeds current administrative overhead thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Thin Client Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market