
 Returnless Refund Fraud Detection Market | 2026-2036
Returnless Refund Fraud Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Returnless Refund Fraud Detection Market Insights
The EU AI Act is repositioning how vendors architect automated refund decision engines, forcing transparency into black-box scoring models. Riskified leverages behavioral analytics to sustain its position among tier-one fashion retailers. SEON anchors its growth on device fingerprinting and velocity checks for European digital merchants. Forter differentiates through its identity graph that spans both fraud and policy abuse vectors.
Returnless refund fraud detection encompasses software systems that analyze transaction metadata, customer behavior patterns, and device signals to identify illegitimate refund claims without physical merchandise return. These platforms apply machine learning models to velocity thresholds, geolocation mismatches, and account history anomalies to flag suspicious requests before payment disbursement. Cloud-based deployment models now lead adoption, though hybrid architectures gain traction among enterprises with legacy on-premises payment stacks. Behavioral analytics and identity verification command the strongest margin pools, while anomaly detection competes primarily on price.
The Federal Trade Commission's Mail, Internet, or Telephone Order Merchandise Rule shapes refund timeline obligations in the United States, while the EU AI Act imposes documentation and human-oversight requirements on automated refusal decisions. Payment processors must now navigate overlapping compliance obligations across consumer protection and algorithmic accountability regimes. Stakeholders should monitor how refund policy abuse gets reclassified relative to traditional payment fraud in regulator guidance.
Market Dynamics
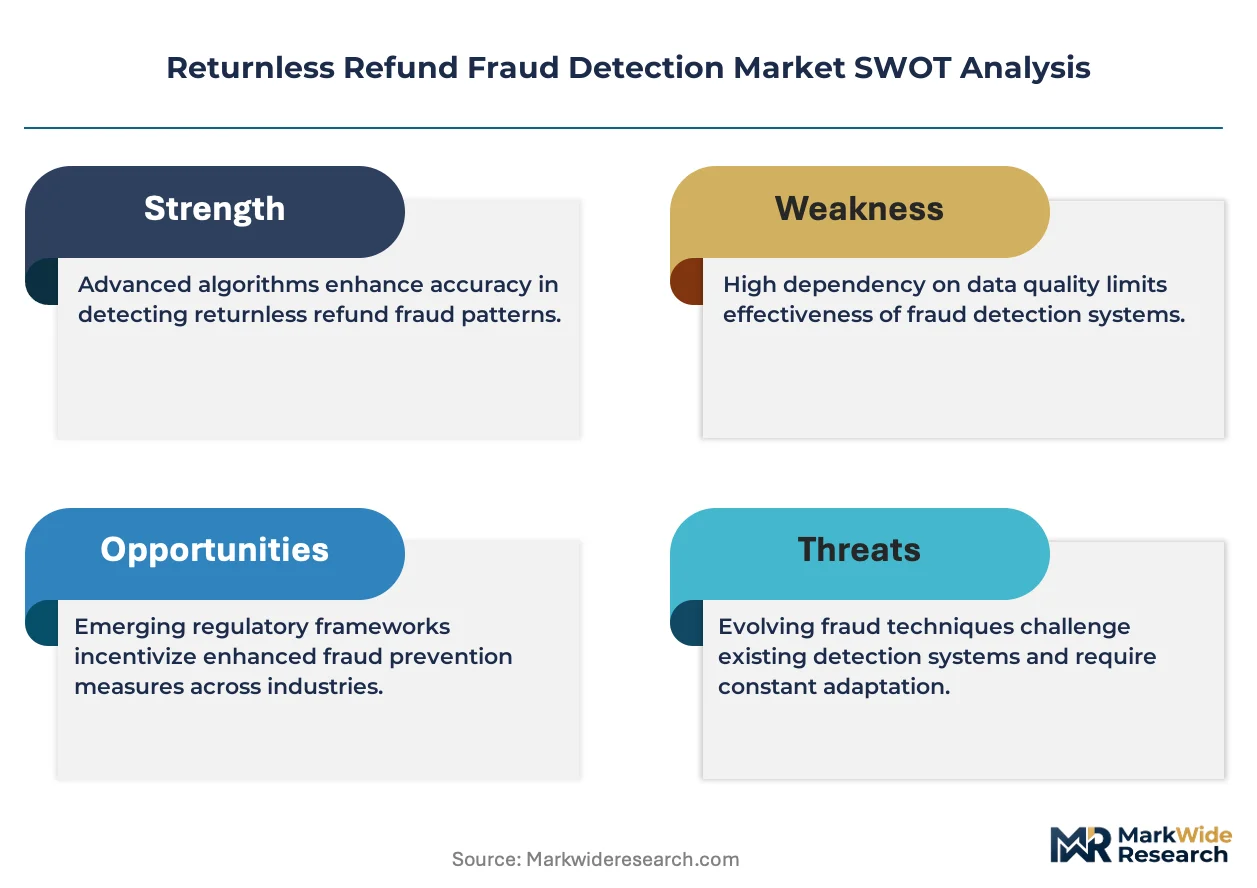
The EU AI Act's risk-based classification for automated decision-making is forcing vendors to rearchitect black-box scoring models into auditable, explainable systems before deployment in refund workflows.
Growth Catalysts
- Returnless refund policy expansion:Mass-market apparel retailers in the United States have normalized no-return refunds, expanding the attack surface that demands automated detection coverage.
- Cloud deployment maturation:Enterprise migration to cloud-native fraud stacks enables real-time velocity checks and behavioral analytics without on-premises infrastructure overhead.
- Device fingerprinting sophistication:Signal collection from mobile and desktop endpoints now identifies synthetic identities and emulator farms before refund disbursement.
Market Restraints
- Algorithmic accountability compliance costs:The EU AI Act imposes documentation, human oversight, and audit trail requirements that inflate engineering overhead for automated refusal engines.
- Legacy payment stack entanglement:Enterprises with decades-old on-premises transaction processing face hybrid architecture friction when embedding cloud-based detection layers.
- False positive revenue leakage:Overly aggressive refund blocking alienates legitimate customers, creating measurable churn in subscription and high-frequency purchase segments.
Strategic Opportunities
- Policy abuse-fraud convergence:Vendors that unify identity graphs across traditional payment fraud and returnless refund abuse capture cross-sell potential with existing merchant relationships.
- Behavioral biometrics integration:Keystroke dynamics and touchscreen interaction patterns offer low-friction signals for mobile-first refund request verification.
- Regulatory arbitrage in mid-market:Smaller merchants outside EU jurisdiction seek detection solutions that balance automation depth against compliance documentation burden.
Industry Challenges
- Machine learning explainability talent scarcity:Engineering teams with both fraud domain expertise and regulatory-compliant model interpretability skills command premium compensation and extended hiring timelines.
- Cross-border data residency fragmentation:Refund transaction data must remain within jurisdictional boundaries, complicating centralized model training for multinational merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Returnless Refund Fraud Detection Market |
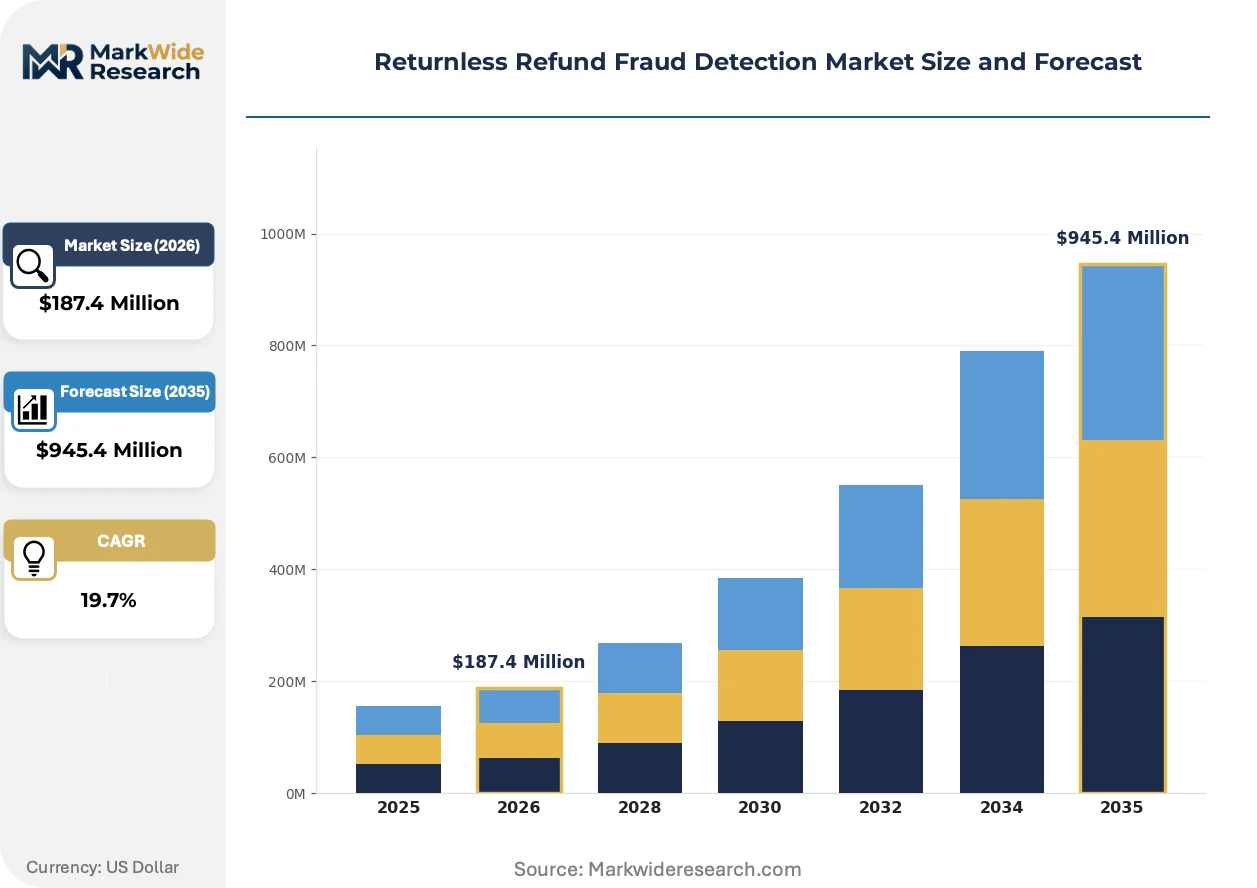
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Behavioral Analytics, Transaction Monitoring, Identity Verification, Pattern Recognition, Anomaly Detection Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services Application Area: E-Commerce, Telecommunications, Insurance, Financial Services, Electronics, Consumer Goods Customer Type: Retailers, Payment Processors, Merchants, Online Marketplaces, Subscription Services |
| Companies Covered | Appriss Retail, Riskified, Narvar, Signifyd, Forter, Sift, SEON, Amazon, Happy Returns, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Returnless Refund Fraud Detection Market Trends and Innovations
Behavioral analytics and identity verification layers are converging into unified detection stacks, compressing the historical separation between fraud prevention and policy abuse monitoring.
Graph neural networks applied to customer-account-device relationships are unifying previously siloed signal streams into single scoring architectures. Tier-one fashion retailers now deploy these systems for sub-second refund decisions at checkout. This convergence is compressing vendor competitive differentiation around standalone behavioral or identity capabilities into integrated platform evaluations.
The EU AI Act's documentation requirements for high-risk automated decision systems are reshaping vendor product roadmaps toward built-in audit logging and human-in-the-loop override interfaces. Engineering teams must now embed explainability modules from model inception rather than retrofitting compliance layers post-deployment. European digital merchants are responding by demanding vendor certifications that demonstrate pre-built regulatory alignment.
Merchant procurement of refund fraud detection is consolidating from point solutions toward bundled identity and risk platforms. Mid-market retailers previously buying standalone velocity-check tools now favor integrated suites from existing payment fraud vendors. This consolidation is most visible in the United States, where returnless refund policies first achieved mass-market scale and procurement sophistication lags behind enterprise counterparts.
Returnless Refund Fraud Detection Market Segmentation
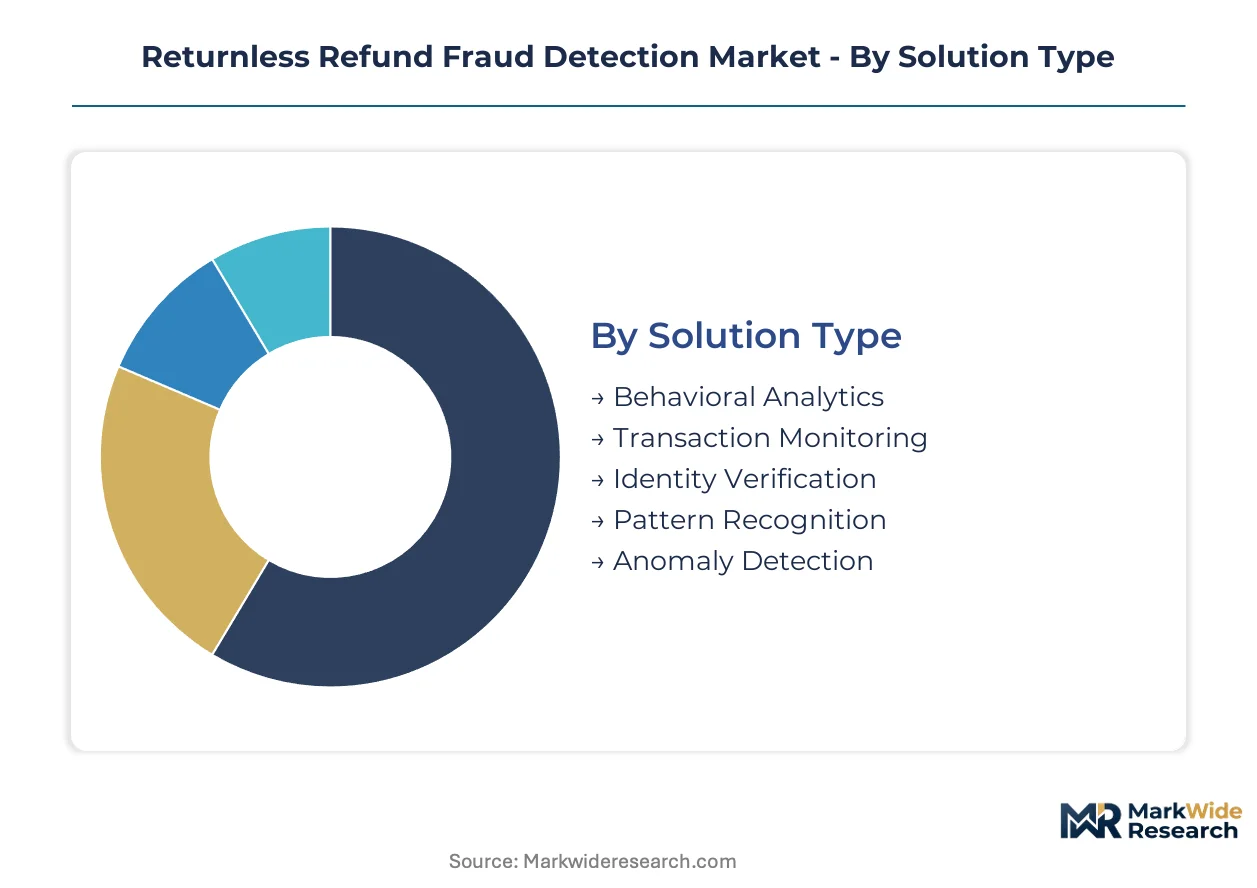
Returnless refund fraud detection vendors architect pricing and integration strategies around four structural dimensions. Solution type determines margin pools and technical talent requirements. Deployment model shapes customer acquisition costs and recurring revenue predictability. Application area and customer type together define competitive positioning against incumbent fraud prevention platforms.
Solution Type:
Behavioral analytics and identity verification segments embed most deeply into merchant checkout flows, while anomaly detection and pattern recognition often operate as standalone monitoring layers.
- Behavioral Analytics:These systems ingest clickstream data, session duration patterns, and navigation sequences to flag suspicious refund request behaviors. Tier-one fashion retailers in the United States concentrate procurement here, driven by pressure to minimize false positives that alienate legitimate customers. Cloud-native architectures enable sub-second scoring without checkout friction.
- Identity Verification:Document authentication, biometric matching, and device binding confirm claimant legitimacy before refund disbursement. European digital merchants under EU AI Act compliance obligations prioritize this segment for its built-in audit trails and human-in-the-loop override capabilities. Regulatory documentation requirements inflate engineering overhead but create switching costs.
- Transaction Monitoring:Real-time analysis of payment velocity, geolocation mismatches, and account history anomalies.
- Pattern Recognition:Machine learning models trained on historical fraud labels to identify emerging attack modalities.
- Anomaly Detection:Unsupervised statistical methods flagging deviations from established customer behavioral baselines.
Behavioral analytics leads volumes today; identity verification is gaining share fastest.
Deployment Model:
Cloud-based and SaaS offerings command premium pricing through rapid deployment and elastic scaling, while on-premises and hybrid models persist among enterprises with legacy payment infrastructure.
- Cloud-Based:Native cloud architectures enable real-time velocity checks and behavioral analytics without infrastructure overhead. Mass-market apparel retailers in the United States favor this model for its speed-to-value and minimal IT burden.
- SaaS:Subscription pricing with standardized integration APIs reduces procurement friction for mid-market merchants. European vendors emphasize pre-built EU AI Act compliance certifications to accelerate sales cycles.
- Hybrid:Split architectures accommodating sensitive data residency requirements while leveraging cloud compute for model training.
- On-Premises:Fully controlled environments for enterprises with decades-old transaction processing stacks and strict data governance policies.
- Managed Services:Vendor-operated detection layers with dedicated analyst teams handling alert triage and merchant communication.
Cloud-based deployments dominate current installations; SaaS delivery is climbing the fastest.
Application Area:
E-commerce and electronics verticals exhibit the steepest refund fraud attack rates, while financial services and insurance apply detection budgets against policy abuse rather than pure fraud.
- E-Commerce:Online marketplaces face coordinated refund abuse rings exploiting returnless policies at scale. United States-based mass-market retailers embed detection directly into checkout flows as standard practice.
- Electronics:High-value, easily resold devices attract sophisticated synthetic identity operations. Device fingerprinting sophistication here identifies emulator farms before disbursement.
- Financial Services:Banks and payment processors extend existing fraud stacks to cover refund-specific attack vectors.
- Insurance:Claims processing workflows adapt detection models for policy abuse identification.
- Telecommunications:Subscription refund requests and equipment return waivers create distinct fraud surfaces.
- Consumer Goods:Lower transaction values and higher volume characterize detection requirements here.
E-commerce anchors revenue today; electronics shows the steepest expansion trajectory.
Customer Type:
Online marketplaces and payment processors consolidate procurement around bundled identity and risk platforms, while standalone retailers and subscription services lag in solution sophistication.
- Online Marketplaces:Platform operators must protect merchant ecosystems from buyer-side refund abuse while maintaining seller trust. These customers demand unified identity graphs spanning fraud and policy abuse vectors.
- Payment Processors:Acquirers and gateways embed detection as value-added services to merchant portfolios. Regulatory overlap between consumer protection and algorithmic accountability regimes complicates compliance roadmaps.
- Retailers:Direct merchants with returnless refund policies drive initial detection adoption.
- Merchants:Broader category capturing mid-market digital sellers with varying technical sophistication.
- Subscription Services:Recurring billing models face distinct refund timing and churn risk considerations.
Online marketplaces lead volumes today; payment processors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent for explainable AI systems clusters in the United States, Germany, and Israel, with regulatory compliance expertise concentrating in Brussels and London financial centers.
United States
Mass-market apparel retailers in the United States pioneered returnless refund policies at scale, creating sustained procurement demand for behavioral analytics platforms. The Federal Trade Commission's Mail, Internet, or Telephone Order Merchandise Rule mandates specific refund timeline obligations that shape detection workflow design. Silicon Valley and New York City host the densest concentrations of fraud detection engineering teams serving tier-one fashion merchants.
Germany
German e-commerce operators face acute pressure from synthetic identity rings exploiting cross-border refund channels within the European single market. The EU AI Act imposes documentation and human-oversight requirements that inflate compliance costs for automated refusal engines deployed here. Berlin and Munich anchor the country's fraud detection vendor ecosystem, with particular strength in identity verification engineering.
United Kingdom
British digital merchants prioritize device fingerprinting sophistication to counter emulator farms targeting high-value electronics refunds. The Financial Conduct Authority's consumer duty rules intersect with emerging algorithmic accountability expectations from the Digital Regulation Cooperation Forum. London's fintech corridor concentrates procurement decision-making for payment processors extending detection to refund-specific attack vectors.
France
French luxury e-commerce platforms demand sub-second refund decisions that preserve customer experience while blocking policy abuse. The Commission Nationale de l'Informatique et des Libertés enforces GDPR-aligned transparency requirements for automated scoring systems. Paris and Lyon host specialized consulting practices bridging technical detection implementation with regulatory documentation obligations.
Israel
Israeli cybersecurity talent feeds behavioral biometrics innovation for mobile-first refund verification systems. The country's national cyber directorate facilitates public-private collaboration on synthetic identity detection methodologies. Tel Aviv's startup density produces specialized vendors occupying positions between research-stage prototypes and enterprise deployment readiness.
Returnless Refund Fraud Detection Market Competitive Landscape
Capital-heavy platform operators compete with asset-light specialists in fraud detection architecture, creating a tiered competitive structure where scale advantages meet niche technical depth. The vendor base separates into three strategic archetypes: integrated identity-and-risk platforms, standalone behavioral analytics providers, and device-centric verification specialists. Consolidation pressures intensify as merchant procurement shifts from point solutions toward bundled suites. Dominant competitive moves include strategic partnerships with payment processors and portfolio diversification into adjacent policy abuse detection.
Among integrated platform providers, Riskified and Forter occupy positions exemplifying the identity-graph approach unifying fraud and refund abuse vectors. SEON represents the device-centric verification archetype, with its European base aligning with regulatory compliance demand concentration. These three companies anchor the competitive landscape's premium tier, though their specific strategic postures remain proprietary.
| Leading Market Players |
|---|
| Appriss Retail |
| Riskified |
| Narvar |
| Signifyd |
| Forter |
| Sift |
| SEON |
| Amazon |
| Happy Returns |
| Others |
Pricing and Supply Chain Analysis
Platform-tier divergence between integrated identity suites and standalone behavioral tools manifests in both subscription pricing and engineering talent sourcing patterns. Premium vendors bundle device fingerprinting with policy abuse detection, commanding annual commitments from tier-one fashion retailers, while point-solution providers compete on per-transaction fees for mid-market merchants with lighter compliance obligations.
Pricing Analysis
Bundled versus unbundled service architecture splits the market into divergent pricing models. SaaS-tiered subscriptions dominate integrated platform procurement, with differentiation anchored in EU AI Act certification depth and real-time scoring latency. Point-solution vendors face downward pricing pressure as merchant procurement consolidates around bundled suites. Payment processors exhibit lowest price sensitivity due to regulatory overlap burdens; mid-market digital merchants remain most cost-conscious.
Supply Chain Analysis
Machine learning explainability talent scarcity in the United States, Germany, and Israel constrains vendor capacity expansion. Engineering teams draw from Tel Aviv's cybersecurity corridor, Berlin's identity verification clusters, and Silicon Valley's behavioral analytics depth. Cloud compute infrastructure rests on hyperscaler concentration in Virginia, Frankfurt, and Dublin. Single-source vulnerability in specialized GPU provisioning for model training complicates scaling timelines. Distribution runs through direct enterprise sales with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Returnless refund fraud detection functions as a late-cycle quality market where merchant procurement shifts toward explainable AI specifications under regulatory pressure. Tier-one retailers now mandate audit-ready scoring architectures as table stakes.
For Market Incumbents: Cement platform stickiness by embedding human-in-the-loop override interfaces before EU AI Act enforcement deadlines. Acquire specialized behavioral biometrics talent from Israeli research-stage vendors to close mobile verification gaps. Consolidation threats from payment processors extending adjacent fraud stacks demand preemptive certification investment in Brussels-aligned documentation standards. For New Entrants and Emerging Players: Begin with mid-market merchants outside EU jurisdiction seeking automation depth without compliance documentation burden. Target Latin American and Southeast Asian e-commerce platforms where returnless refund policies are scaling fastest. Lead with device-centric verification priced below integrated suite alternatives, then upsell behavioral analytics modules. For Investors and Strategic Acquirers: Consolidation pressure builds where procurement shifts from point solutions toward bundled identity platforms. Five-to-ten-year viability favors vendors with pre-built regulatory alignment and cross-border data residency architectures. Watch for inflection in merchant RFP language explicitly unifying fraud and policy abuse detection requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies behavioral analytics with identity verification for tier-one fashion retailers. |
| Regulatory Certification | Pre-built EU AI Act compliance accelerates European digital merchant sales cycles. |
| Acquisition of Specialist Firm | Behavioral biometrics talent from Israeli startups closes mobile verification gaps. |
| Strategic Partnership | Payment processor alliances embed detection as value-added merchant services. |
| Geographic Expansion | Mid-market penetration in Latin America exploits regulatory arbitrage opportunities. |
Research Methodology
Bottom-up merchant procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with fraud detection engineering leads, merchant risk officers, payment processor product managers, and regulatory compliance consultants combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory documentation. Triangulation across these sources ensures segmentation accuracy.
Historical trendline analysis of solution-type adoption rates, deployment model migration patterns, and customer-type procurement sophistication informed projection frameworks. Segmentation dimensions span solution type, deployment model, application area, and customer vertical across the modeling period. CAGR derivation incorporated velocity of EU AI Act implementation, cloud migration timelines among legacy payment stack enterprises, and behavioral biometrics commercialization curves.
Several conditions sit outside the modeled scope, including sovereign AI regulations beyond EU jurisdiction, merchant insolvency waves, and fundamental shifts in returnless refund policy prevalence. Forecasts reflect assumptions about regulatory enforcement consistency and talent availability for explainable AI development. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
United Kingdom ICT Market
Digital Solutions
US Transcription Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Shipping Software Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Chile ICT Market
Digital Solutions
Web Content Management Market
Digital Solutions
Docketing Solution Market