
 United Kingdom ICT Market | 2026-2036
United Kingdom ICT Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom ICT Market Analytics
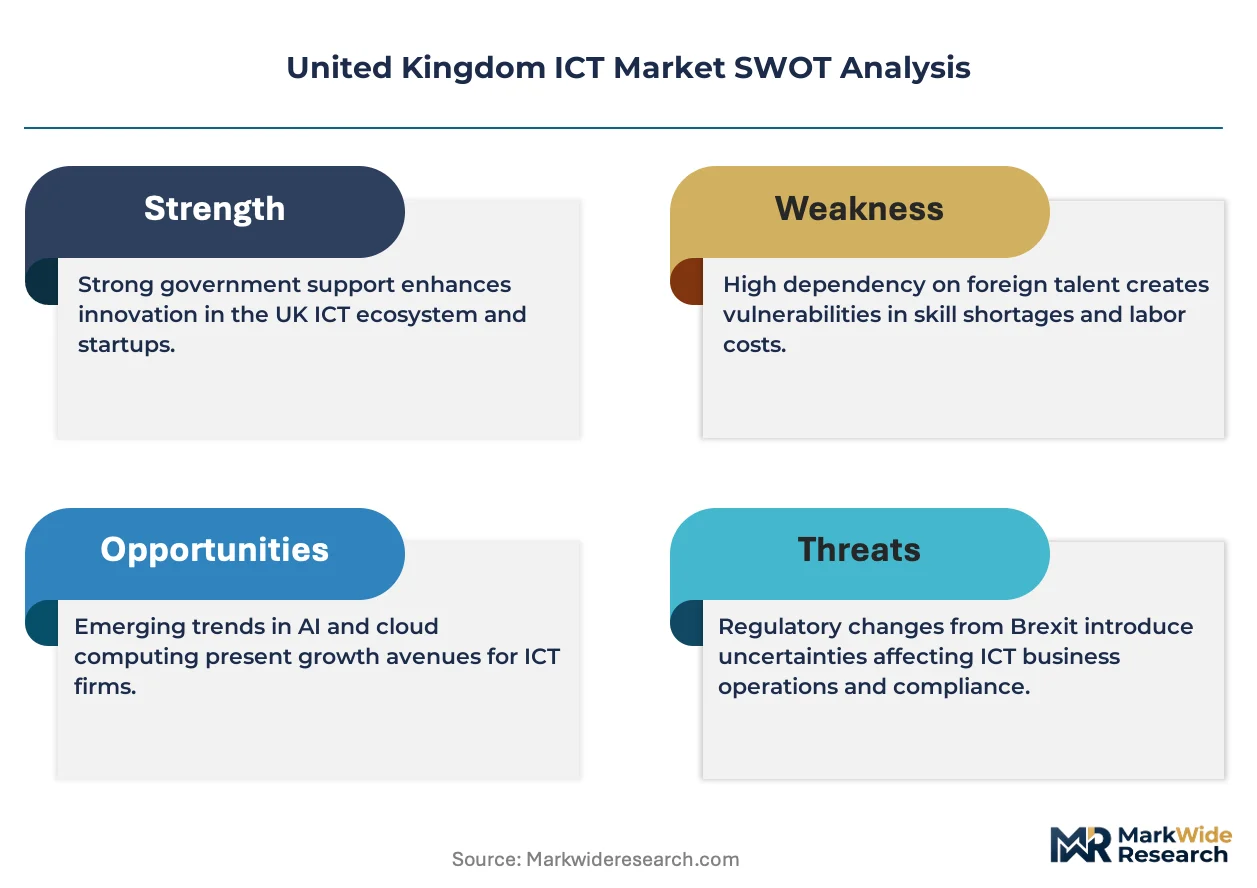
A shift from single-source IT outsourcing to multi-source cloud ecosystems is repositioning how British enterprises procure technology infrastructure. BT Group leverages its nationwide fibre footprint to compete in managed services. Amazon Web Services anchors hyperscale cloud capacity across UK regions. Microsoft differentiates through integrated productivity and security stacks.
United Kingdom ICT encompasses hardware, software, networking equipment, and professional services enabling digital information processing, storage, and transmission across enterprises and public bodies. The sector operates on standards including ISO 27001 for information security management and ITIL frameworks for service delivery, with primary purpose spanning operational automation, customer engagement, and regulatory compliance. Cloud Computing commands the fastest expansion trajectory among technology segments as migration from on-premises data centres accelerates. Software captures disproportionate margin pools relative to hardware due to recurring subscription economics and lower incremental delivery costs. Services, particularly cybersecurity consulting, sustains premium pricing through persistent talent scarcity.
Ofcom governs telecommunications infrastructure competition and spectrum allocation, directly influencing broadband deployment timelines and mobile network investment cycles. The UK Cyber Security Council and National Cyber Security Centre set professional standards and threat response protocols that shape vendor qualification requirements for government and critical national infrastructure contracts. Stakeholders must monitor Ofcom's wholesale pricing reviews and the evolving UK AI regulation framework to anticipate compliance cost shifts and procurement rule changes.
Market Dynamics
The United Kingdom ICT market is undergoing a fundamental procurement transformation as enterprise buyers dismantle monolithic outsourcing contracts in favor of composable, multi-cloud architectures that demand new vendor orchestration capabilities.
Growth Catalysts
- Financial Services Digital Mandates:UK banking regulators require operational resilience frameworks that accelerate cloud migration timelines and cybersecurity investment across retail and investment banking.
- ISO 27001 Certification Requirements:Public sector procurement rules mandate information security management standards, creating qualification barriers that favor established managed service providers with compliance infrastructure.
- London-Manchester Digital Corridor:Concentrated enterprise demand across these two technology clusters generates network effects that attract hyperscale cloud region investments and specialized talent pools.
Market Restraints
- Semiconductor Supply Concentration:UK ICT hardware procurement remains exposed to Taiwan and South Korea fabrication bottlenecks, creating delivery volatility for networking equipment and servers.
- Ofcom Wholesale Pricing Controls:Regulated Openreach fibre pricing limits infrastructure monetization for alternative network operators, compressing capital recovery timelines.
- Legacy System Technical Debt:Mainframe and on-premises ERP dependencies in government and financial services create integration friction that slows cloud-native architecture deployment.
Strategic Opportunities
- Greater Manchester Digital Cluster:Underdeveloped relative to London, this northern hub offers lower commercial real estate costs and government levelling-up incentives for data centre and R&D facility placement.
- AI Regulation Framework Tailwinds:Anticipated UK AI legislation creates compliance service opportunities for consultancies able to bridge technical implementation and governance design.
- Edge-Cloud Convergence:Integration of distributed edge computing with centralised cloud orchestration enables low-latency applications for manufacturing and autonomous systems.
Industry Challenges
- Cybersecurity Talent Scarcity:Persistent gaps in certified security architects and incident response specialists force wage inflation and project delays across managed services.
- Multi-Vendor Integration Complexity:Enterprises struggle to operationalise fragmented cloud estates spanning AWS, Azure, and Google Cloud Platform, requiring costly middleware and governance tooling.
- ITIL-to-DevOps Transition Friction:Organisational resistance to agile service delivery models slows automation adoption and perpetuates manual ticketing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom ICT Market |
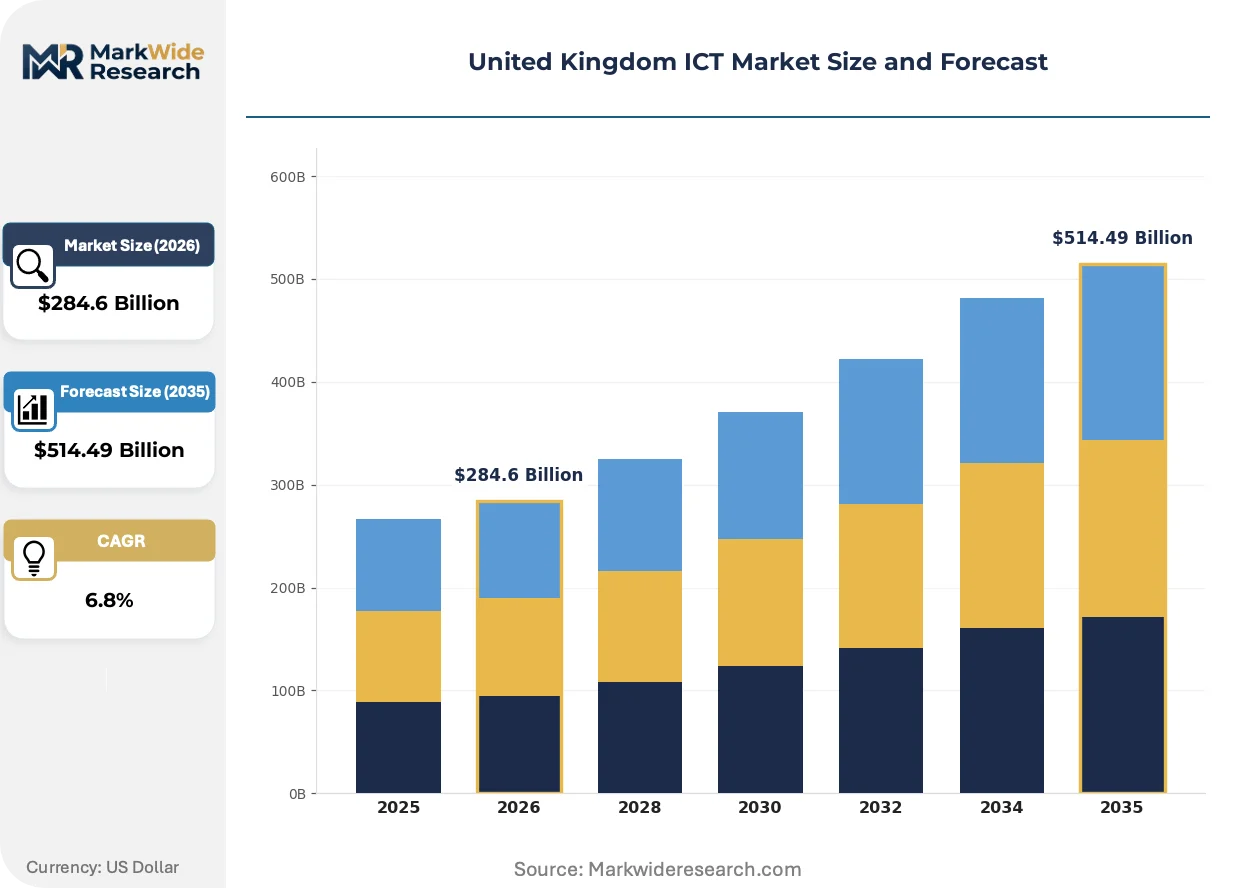
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $514.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Networking, Services End User: SMEs, Government, Large Enterprises, Education Technology: Cloud Computing, AI, IoT, Cybersecurity Application: Data Management, Communication, E-commerce, Enterprise Resource Planning |
| Companies Covered | Microsoft, Amazon Web Services, Google Cloud, BT Group, Vodafone Group Services, Computacenter, Accenture, IBM, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom ICT Market Evolving Landscape
Generative AI capabilities are penetrating enterprise software stacks at unprecedented velocity, forcing incumbent vendors to rearchitect product roadmaps and pricing models around inference-based consumption.
Generative AI is absorbing natural language processing workloads that previously required dedicated machine learning engineering teams. Mid-market enterprises in professional services and legal sectors are adopting copilot-style interfaces faster than anticipated twelve months prior. This absorption pattern is compressing the addressable market for standalone NLP software vendors and redirecting procurement toward platform-embedded capabilities.
Ofcom's March 2024 wholesale fixed access market review reset copper-to-fibre transition timelines and price controls for Openreach infrastructure. Alternative network operators face compressed wholesale margins that constrain rural deployment economics. Full-fibre broadband providers in Scotland and Wales are responding by clustering demand aggregation around enterprise campuses and public sector anchor tenants.
Enterprise software purchasing is consolidating around integrated platform suites that bundle productivity, security, and infrastructure management. Independent best-of-breed vendors in identity management and endpoint protection face displacement as buyers prioritise vendor consolidation over functional depth. This preference shift is most visible in NHS digital transformation programmes and central government shared services frameworks.
United Kingdom ICT Market Segmentation
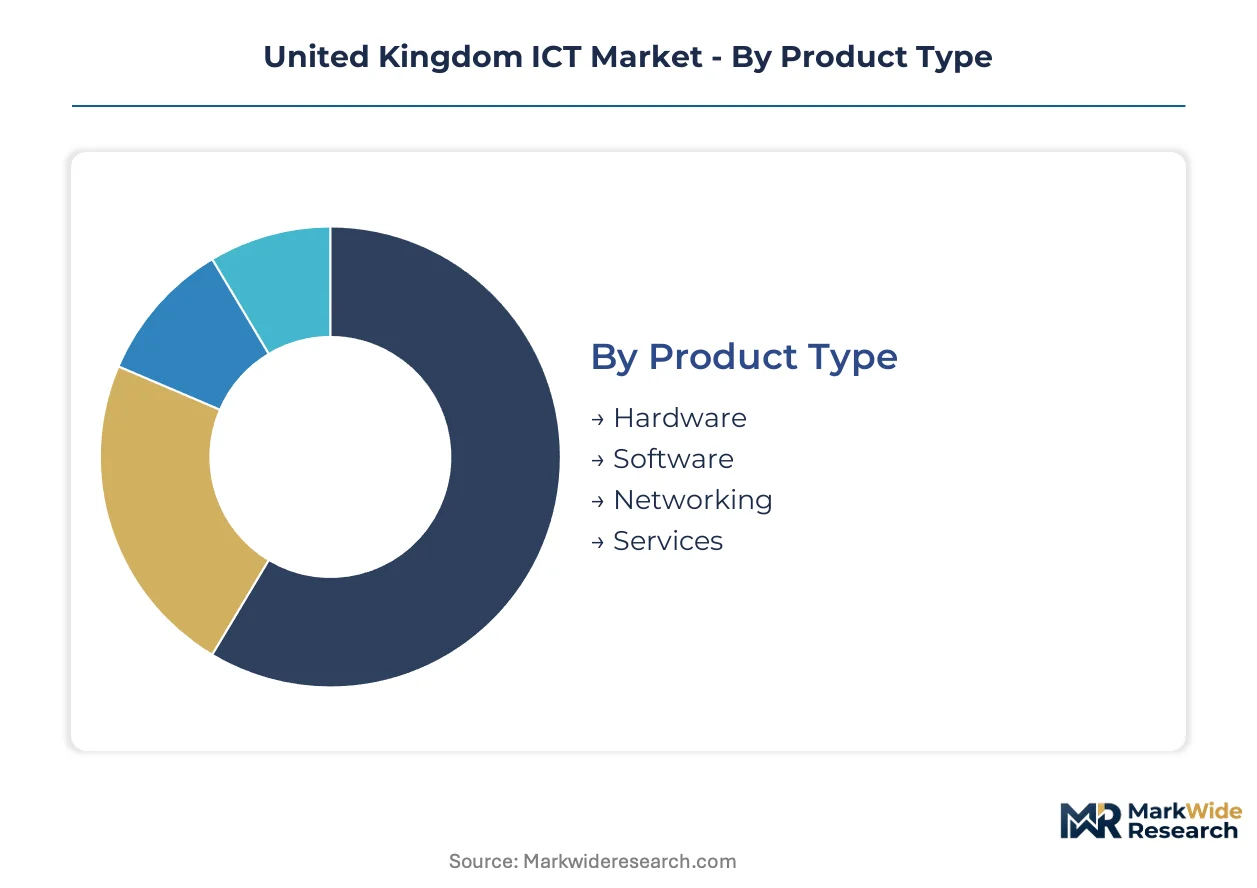
Segmentation reveals how procurement power concentrates across buyer types and technology layers in United Kingdom ICT. Distinct investment patterns emerge between regulated financial institutions and public sector bodies, each driving divergent vendor qualification requirements.
Product Type:
Supply concentration in semiconductors and hyperscale cloud infrastructure shapes margin distribution across hardware, software, and services procurement channels.
- Hardware:Servers, storage arrays, and networking equipment constitute capital-intensive procurement with elongated replacement cycles. Financial services data centres in London and Edinburgh drive demand for high-availability infrastructure, though Taiwan fabrication bottlenecks create delivery volatility.
- Software:Enterprise applications and system software deliver recurring subscription revenue with lower incremental delivery costs. NHS digital transformation programmes and central government shared services frameworks favor integrated platform suites over best-of-breed point solutions.
- Networking:Fibre optic infrastructure and wireless equipment enable connectivity across enterprise campuses and distributed workforces. Openreach wholesale pricing controls compress margins for alternative network operators serving Greater Manchester and Scottish enterprise zones.
- Services:Managed IT services, systems integration, and consulting engagements absorb persistent cybersecurity talent scarcity. ISO 27001 certification requirements create qualification barriers that favor established providers with compliance infrastructure.
Today's leader: Services. Tomorrow's challenger: Software.
End User:
Customer type determines contract scale, procurement cycle length, and regulatory overlay intensity across United Kingdom ICT demand.
- SMEs:Mid-market enterprises adopt cloud-native productivity suites through Microsoft and Google channel partners. Professional services firms in Manchester and Bristol accelerate generative AI copilot adoption faster than twelve-month prior forecasts anticipated.
- Government:Central departments and local authorities mandate ITIL-aligned service delivery with stringent security clearances. National Data Strategy procurement rules reshape vendor qualification requirements for critical national infrastructure contracts.
- Large Enterprises:Multinational corporations headquartered in London technology corridor drive multi-cloud orchestration complexity spanning AWS, Azure, and Google Cloud Platform estates. Legacy ERP dependencies create integration friction that slows cloud-native architecture deployment.
- Education:Universities and further education colleges balance research computing demands against constrained capital budgets. Edge-cloud convergence opportunities emerge for low-latency research applications and campus IoT deployments.
Large enterprises command current procurement volume. SMEs are climbing the fastest as cloud self-service lowers entry barriers.
Technology:
Technology layer maturity governs implementation risk profiles and talent availability constraints across United Kingdom ICT adoption curves.
- Cloud Computing:Hyperscale infrastructure services and SaaS applications dominate enterprise migration roadmaps. Migration from on-premises data centres accelerates as operational resilience mandates compress timelines for financial services.
- AI:Machine learning platforms and generative AI capabilities penetrate enterprise software stacks at unprecedented velocity. Anticipated UK AI legislation creates compliance service opportunities for consultancies bridging technical implementation and governance design.
- IoT:Connected sensor networks and industrial automation systems enable manufacturing and logistics optimization. Edge-cloud convergence supports low-latency applications for autonomous systems in automotive and aerospace clusters.
- Cybersecurity:Threat detection, identity management, and incident response services sustain premium pricing through certified architect scarcity. National Cyber Security Centre protocols shape vendor qualification requirements for government contracts.
Cloud Computing anchors current infrastructure spending. AI is gaining share fastest as inference-based consumption rearchitects product roadmaps.
Application:
Use case criticality determines resilience requirements and integration complexity across United Kingdom ICT deployment patterns.
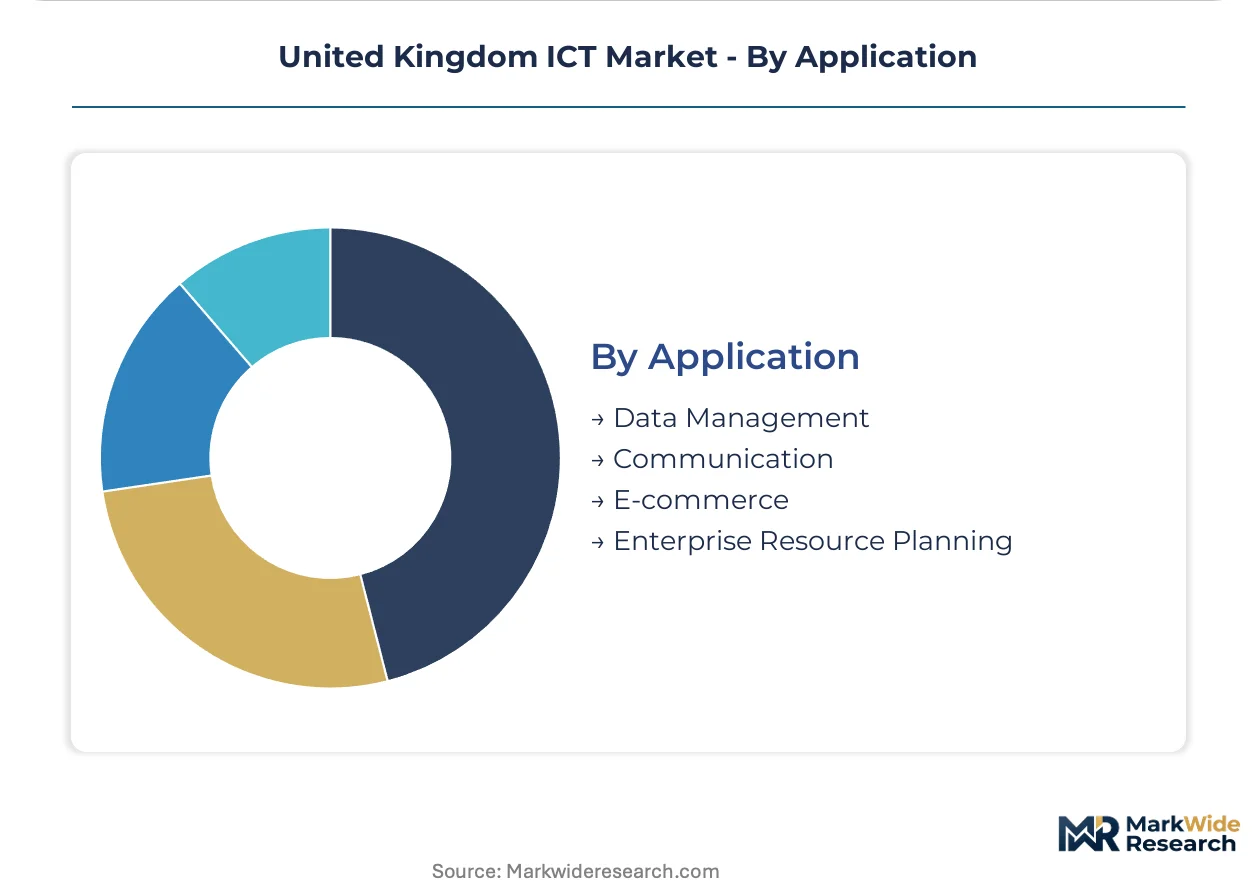
- Data Management:Database platforms, analytics infrastructure, and governance tooling support regulatory reporting and customer intelligence. Financial services operational resilience frameworks accelerate investment in real-time data pipelines.
- Communication:Unified collaboration platforms and contact centre systems enable distributed workforce coordination. Microsoft Teams and Zoom deployments displaced legacy telephony during hybrid work normalization.
- E-commerce:Digital storefronts, payment processing, and supply chain integration platforms support retail and B2B transaction volumes. Consumer protection regulations and PCI-DSS compliance overlay technical implementation requirements.
- Enterprise Resource Planning:Finance, HR, and operations systems constitute the deepest legacy technical debt in government and banking. Mainframe dependencies create integration friction that slows cloud-native replacement timelines.
Data Management leads investment intensity. E-commerce shows steepest expansion trajectory as digital transaction volumes compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between UK sub-regions are redistributing data centre investment and cloud infrastructure deployment. Compliance burden variation across England, Scotland, and Wales creates arbitrage opportunities for operators seeking lower energy costs and planning consent timelines.
London and the Southeast
Financial services cloud migration and hyperscale region expansion concentrate procurement spend in this corridor. The National Data Strategy procurement rules reshape vendor qualification for government contracts. Slough and Docklands data centre clusters attract Microsoft and Amazon Web Services capacity investments.
Greater Manchester and Northern England
Levelling-up incentives and lower commercial real estate costs pull R&D facilities away from southern concentration. Ofcom wholesale pricing reviews influence fibre deployment economics across Lancashire and Yorkshire. MediaCityUK and Manchester Science Park anchor edge computing investments for manufacturing automation.
Scotland
Renewable energy access and cooling advantages position Edinburgh and Glasgow for sustainable data centre growth. National Cyber Security Centre protocols shape critical national infrastructure vendor requirements. Scottish Enterprise grants accelerate fintech and health tech cluster development around Edinburgh.
Wales
Enterprise zone status and reduced business rates attract contact centre and back-office technology operations. Openreach fibre pricing controls compress margins for alternative network operators in Cardiff and Newport. Compound semiconductor foundry investments in South Wales create adjacent ICT services demand.
United Kingdom ICT Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance services and edge infrastructure niches. The vendor base organizes around three archetypes: hyperscale cloud platforms with integrated security stacks, incumbent telecom operators leveraging fibre footprints for managed services, and consultancies bridging technical implementation with regulatory governance. Consolidation pressure intensifies as enterprise buyers prioritize vendor reduction over functional depth. Strategic moves center on multi-cloud orchestration partnerships and vertical specialization around financial services operational resilience mandates.
Within the hyperscale platform tier, Microsoft and Amazon Web Services exemplify divergent competitive positioning. Microsoft anchors productivity-integrated cloud services through its productivity and security stack bundling. Amazon Web Services occupies infrastructure-centric positioning with regional capacity expansion across UK zones. BT Group represents the incumbent telecom archetype, converting nationwide fibre assets into managed service relationships with enterprise and public sector buyers.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Google Cloud |
| BT Group |
| Vodafone Group Services |
| Computacenter |
| Accenture |
| IBM |
| Cisco Systems |
| Others |
Value Network & Pricing Analysis
DRAM spot price indices cascade through server and networking equipment procurement, compressing margins for UK systems integrators while hyperscale cloud providers absorb volatility through long-term foundry contracts that lock in silicon supply tiers.
Pricing Analysis
Input-cost pass-through from Taiwan fabrication bottlenecks intensifies pricing pressure across hardware procurement tiers. Three-tier pricing structure across enterprise-grade, mid-market, and entry-level hardware separates ISO 27001-certified configurations from uncertified alternatives. Cost compression in mid-market servers reflects memory module volatility and constrained GPU availability. SMEs exhibit highest price sensitivity, while financial services institutions prioritize resilience specifications over unit economics.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific routes compounds semiconductor delivery uncertainty for UK enterprises. Supply concentrates in Taiwan, South Korea, and China for advanced logic chips and memory components. Raw material dependencies span silicon wafers, rare earth elements for magnetics, and copper for interconnects. Single-source vulnerability around TSMC advanced node production creates systemic exposure. Distribution runs through value-added distributors and direct hyperscale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK ICT market functions as a regulatory compounder where Ofcom wholesale pricing reviews and National Cyber Security Centre protocols continuously reshape procurement qualification requirements and vendor selection criteria.
For Market Incumbents: Cement multi-cloud orchestration capabilities through API-native integration platforms that neutralize emerging specialist middleware vendors. Deepen vertical integration into edge computing infrastructure across Greater Manchester and Scottish enterprise zones. ISO 27001 certification moats must expand to encompass anticipated UK AI legislation compliance frameworks.
For New Entrants and Emerging Players: The UK AI regulation framework opens a window for governance-design consultancies bridging technical implementation and compliance documentation. White-space targets concentrate in Greater Manchester digital cluster data centre operations and NHS cybersecurity managed services. Channel partnerships with Microsoft and AWS marketplace ecosystems offer lowest-friction customer acquisition.
For Investors and Strategic Acquirers: Asymmetric upside sits with edge infrastructure specialists possessing renewable energy-tied data centre assets in Scotland and Wales. Five-to-ten year viability hinges on regulatory compliance automation capabilities rather than pure technical performance. Monitor Ofcom spectrum allocation decisions as inflection indicator for mobile edge computing investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud Orchestration Platform | AWS and Azure API integration reduces vendor lock-in for financial services operational resilience mandates. |
| Edge Data Centre Expansion | Scottish renewable energy access lowers carbon-adjusted computing costs for AI inference workloads. |
| ISO 27001 Certification Investment | Central government shared services frameworks disqualify uncertified vendors from critical infrastructure contracts. |
| AI Governance Consultancy Capability | Anticipated UK AI legislation creates compliance service demand bridging technical and legal functions. |
| Managed Security Service Acquisition | Cybersecurity talent scarcity sustains premium pricing for incident response and threat detection capabilities. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers, hyperscaler capex disclosures, and Ofcom regulatory filings — were reconciled against secondary validation from SEC filings and enterprise software vendor earnings calls. Conversations with channel partners, integration specialists, and National Cyber Security Centre liaison officers informed qualification barrier assessments. Bottom-up segment sizing and top-down macroeconomic triangulation anchored market estimates.
Historical spending patterns were cross-referenced against panel input from financial services technology executives and public sector digital transformation leads. Segmentation modeling spanned deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts including operational resilience mandates and wholesale pricing reviews.
Revisions become necessary when semiconductor supply disruptions, Ofcom regulatory resets, or AI legislation implementation timelines materialize differently than modeled. Forecasts incorporate documented assumptions about cloud migration velocity and cybersecurity investment cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Data Converter Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Weather App Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Latin America IT Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Lecture Capture Systems Market