
 Digital BSS Market | 2026-2036
Digital BSS Market Size, Share, and Industry Trends Forecast 2026-2036
Digital BSS Market Intelligence
Customer concentration in the telecom sector is pivoting from monolithic consumer subscriptions toward a fragmented base of enterprise and IoT service partners. This shift requires flexible billing and partner management solutions. Amdocs Limited specializes in customer experience systems for communication service providers. Netcracker Technology Corporation leverages its portfolio to manage complex network and service ecosystems, while Oracle Corporation provides cloud-native BSS applications.
Digital Business Support Systems (BSS) are a suite of software applications that enable communication service providers to manage their customer-facing business operations. These systems are increasingly built on a microservices architecture, utilizing open APIs for integration with network functions and third-party services. The cloud-based deployment model is rapidly displacing traditional on-premises solutions due to its scalability and lower upfront costs. Within service types, customer management and order management solutions are central to delivering personalized, real-time digital experiences.
Data sovereignty and privacy regulations, such as Europe's GDPR, dictate how customer data is handled within BSS platforms. In the United States, the FCC sets rules for transparent billing and customer communications, directly influencing revenue assurance and customer management modules. These frameworks compel vendors to build configurable, compliant systems. The key strategic decision for operators now revolves around choosing between modernizing legacy stacks or pursuing a full greenfield transformation with cloud-native BSS partners.
Market Dynamics
The central force shaping the Digital BSS market is the telecommunications industry's pivot from a consumer-centric, high-volume business model to a complex, value-driven ecosystem supporting enterprise and IoT services, which demands unprecedented agility in service monetization.
Growth Catalysts
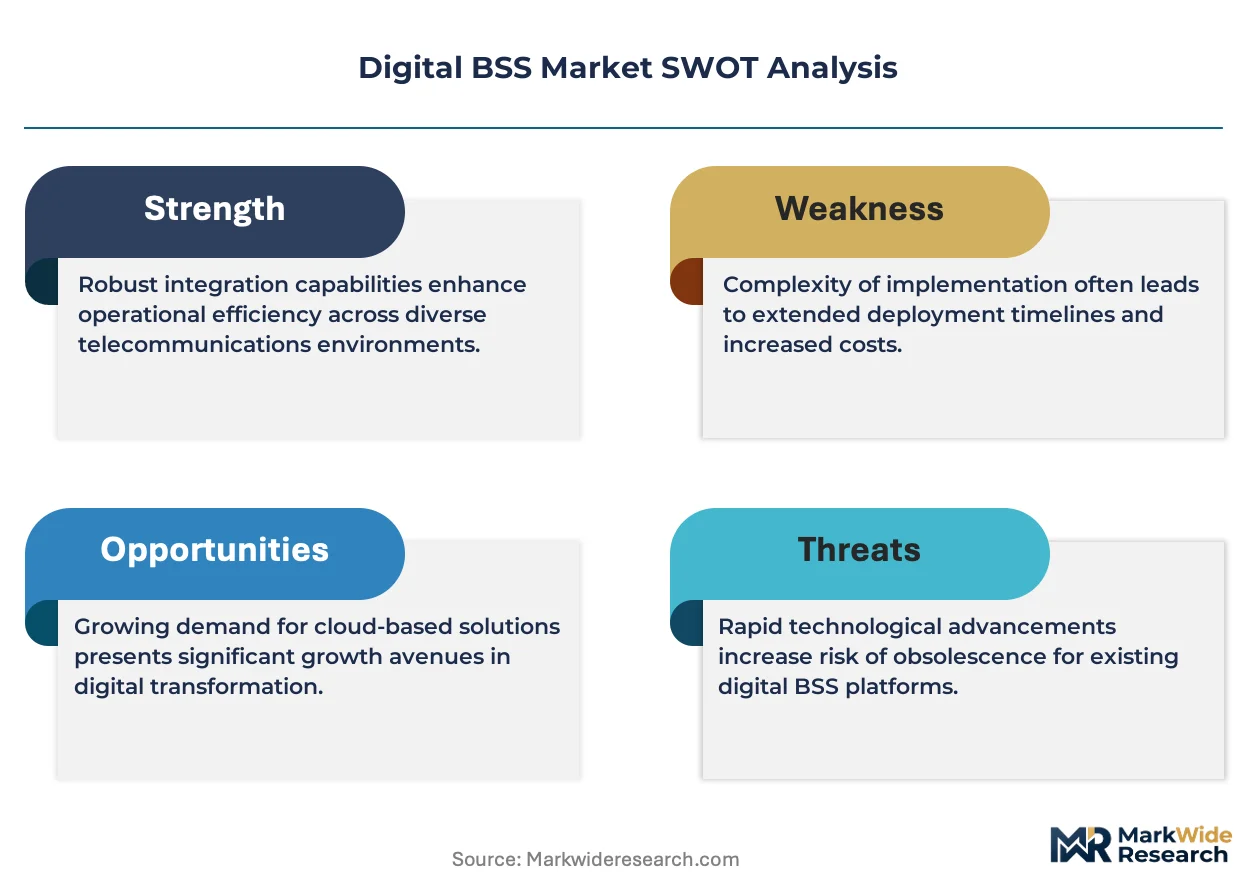
- 5G Network Slicing:The ability of 5G to create virtual, dedicated network slices for specific enterprise use cases requires a dynamic BSS to bill for differentiated quality of service, latency, and throughput, creating direct demand for modern monetization platforms.
- Enterprise IoT Expansion:Growth in private networks for manufacturing, logistics, and smart cities necessitates BSS platforms capable of managing millions of devices, complex partner revenue-sharing models, and usage-based billing for M2M communication.
- Indian Telecom Modernization:Regulatory guidance from the Telecom Regulatory Authority of India (TRAI) and intense market competition are compelling Indian operators to aggressively replace legacy systems with scalable, cloud-native BSS to support massive subscriber growth and new digital service launches.
Market Restraints
- Legacy System Complexity:The high cost, risk, and operational disruption associated with migrating from deeply embedded, highly customized on-premises BSS stacks represent a significant barrier to full-scale modernization for established communication service providers.
- Data Sovereignty Regulations:Mandates such as Europe's GDPR restrict the cross-border movement of customer data, complicating the deployment of global, multi-tenant cloud BSS solutions and often requiring costly region-specific or in-country data centers.
- Integration with Legacy OSS:Poor interoperability between new microservices-based BSS and older Operations Support Systems (OSS) can create significant technical debt and operational friction, limiting the end-to-end automation benefits of a digital transformation.
Strategic Opportunities
- Edge Computing Monetization:Developing BSS modules specifically for billing and charging for low-latency applications hosted at the network edge presents a new revenue opportunity for operators serving industries like gaming, autonomous vehicles, and remote surgery.
- AI-Powered Operations:Integrating artificial intelligence and machine learning into BSS can create significant value through predictive churn analysis, hyper-personalized marketing, and automated fraud detection, moving beyond basic billing functions.
- Greenfield Operators in Emerging Markets:New market entrants, particularly in Southeast Asia and Africa, can bypass legacy infrastructure entirely, representing a prime opportunity for vendors to deploy complete, cloud-native BSS stacks without the constraints of migration.
Industry Challenges
- Cloud-Native Talent Scarcity:A persistent shortage of software engineers, solution architects, and DevOps specialists with expertise in microservices, containerization, and CI/CD pipelines within the telecom domain slows down BSS development and deployment cycles.
- Complex System Integration:The challenge of ensuring seamless data flow and process orchestration between new digital BSS components and existing legacy systems without impacting customer experience or revenue streams remains a primary operational hurdle.
- API Standardization Gaps:The absence of universally adopted open APIs for key BSS functions leads to increased reliance on custom development for integration, raising implementation costs and creating vendor lock-in risks for service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital BSS Market |
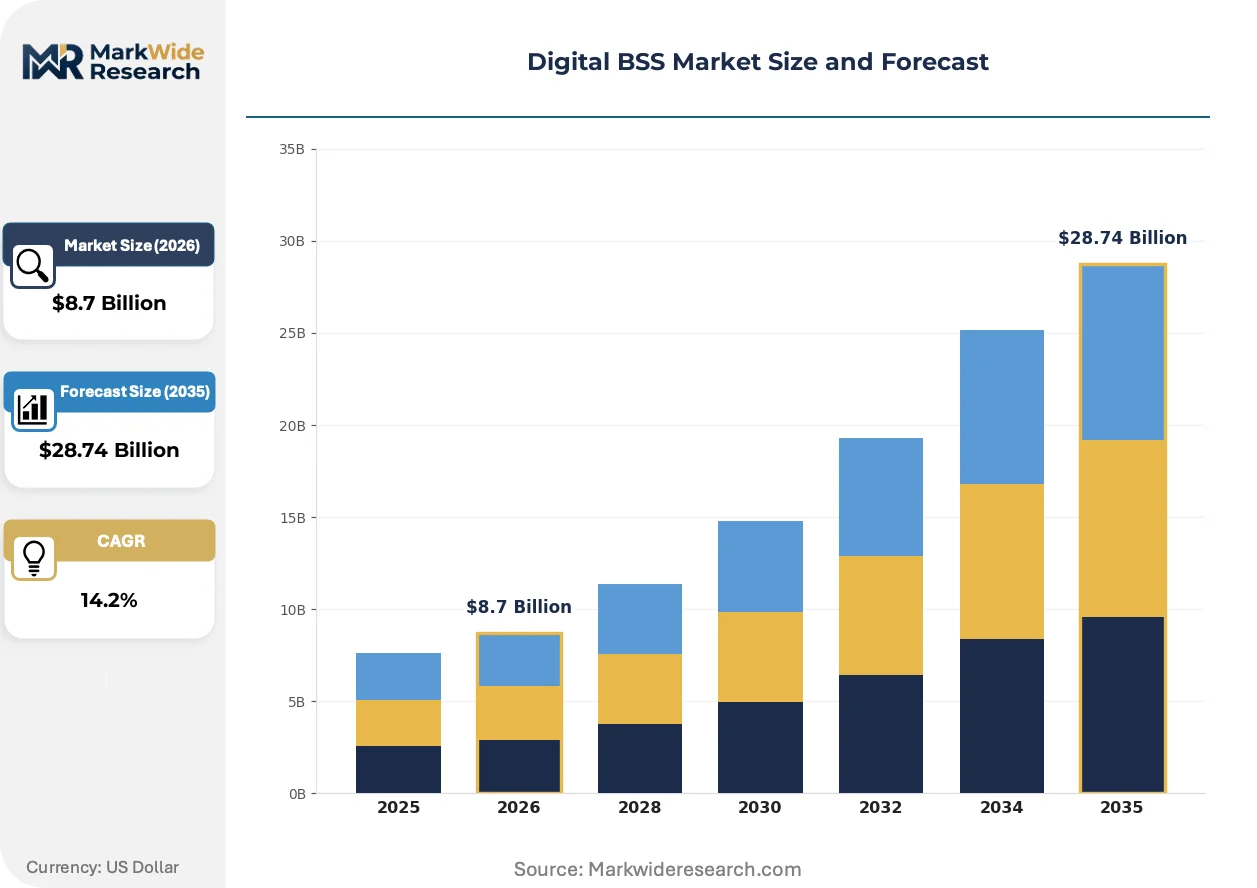
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing, Customer Management, Revenue Assurance, Order Management Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Telecommunications, Utilities, Media, Transportation Technology: AI, Machine Learning, Big Data, IoT |
| Companies Covered | Nokia Corporation, Accenture plc, Amdocs Limited, Capgemini SE, Oracle Corporation, Huawei Technologies Co., Ltd., Netcracker Technology Corporation, CSG Systems International, Inc., Telefonaktiebolaget LM Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital BSS Market Strategic Shifts & Innovations
The evolution of Digital BSS is defined by a fundamental shift towards intelligent automation. Artificial intelligence and machine learning are being embedded into core BSS functions, transforming them from systems of record into engines for proactive, real-time business decision-making.
Microservices architecture is a design paradigm where BSS applications are constructed as a suite of independent, fine-grained services. Communication service providers are adopting this to improve system resilience and accelerate the deployment of new features. This approach is modularizing the traditional monolithic BSS, enabling operators to upgrade specific functions like charging or partner management without disrupting the entire platform.
In the United States, the Federal Communications Commission's (FCC) rules governing billing transparency require that customer invoices are clear and disputes are handled systematically. This regulatory pressure forces BSS vendors to engineer revenue and customer management modules with auditable, configurable workflows. Consequently, US-based telecom operators prioritize BSS solutions that can automate compliance and provide detailed reporting to avoid regulatory penalties.
A notable change in buying behavior is the move away from large-scale, multi-year BSS replacement projects toward more focused, incremental modernization. Operators are adopting a strategy of building new digital services and customer journeys on a modern BSS platform that coexists with legacy systems. This pattern is most visible in mature European markets where minimizing risk to existing revenue streams during transformation is a primary concern.
Digital BSS Market Segmentation
Understanding the Digital BSS market's segmentation reveals the diverse operational requirements and strategic priorities of communication service providers. This granularity assists vendors in tailoring solutions that address specific business functions, deployment preferences, industry verticals, and technological integration needs across the ecosystem.
Service Type:
The integration depth of Digital BSS services varies, with some functions operating as standalone modules and others deeply embedded within broader customer experience platforms.
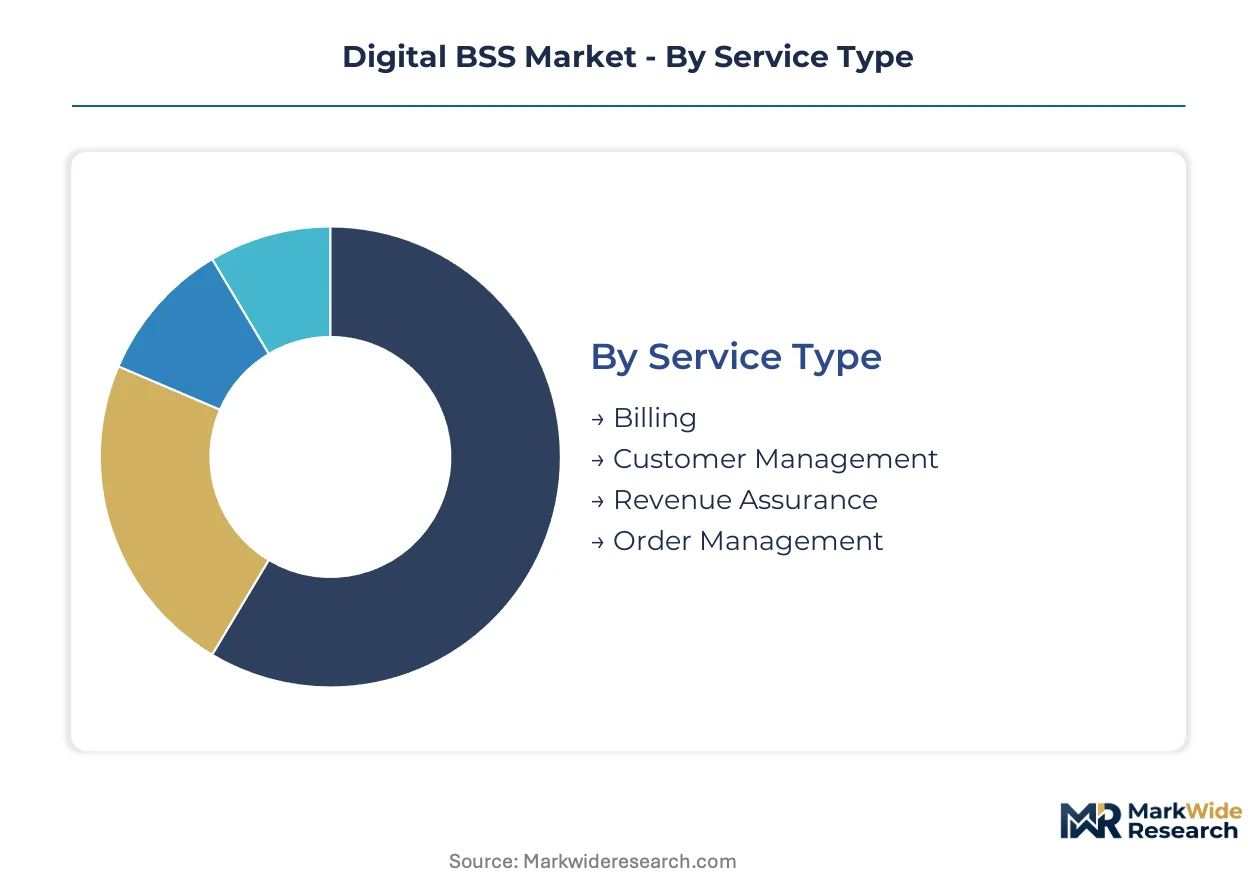
- Billing:This service type encompasses charge calculation, invoice generation, payment processing, and dispute management for diverse service offerings. Demand concentrates in India as operators manage massive subscriber bases and complex tariff plans for new 5G services.
- Customer Management:Solutions in this category handle customer interactions, service provisioning, support, and relationship management across multiple touchpoints. Personalized digital experiences drive adoption, particularly among operators seeking to reduce churn in competitive markets.
- Revenue Assurance:These systems prevent revenue leakage by detecting fraud, ensuring accurate billing, and reconciling financial data across the service lifecycle.
- Order Management:This segment orchestrates the capture, validation, and fulfillment of customer service requests, integrating with network and IT systems.
Volume placements concentrate in Billing; the faster expansion belongs to Customer Management.
Deployment Model:
The cost tier and scalability requirements heavily influence the choice of deployment model for Digital BSS solutions.
- Cloud-Based:These solutions are hosted on remote servers and accessed over the internet, offering significant scalability, lower upfront costs, and faster deployment cycles. Cloud-native BSS applications are gaining traction in markets with high infrastructure costs, such as Southeast Asia.
- On-Premises:Traditional systems installed and operated within a communication service provider's own data centers provide maximum control and customization. Established European operators with deeply customized legacy stacks often retain these deployments to minimize migration risk.
- Hybrid:This model combines elements of both cloud-based and on-premises deployments, allowing operators to leverage existing infrastructure while adopting cloud capabilities for new services.
- SaaS:Software-as-a-Service BSS platforms are fully managed by a third-party vendor, reducing operational overhead for operators.
Cloud-Based solutions lead in market share, while SaaS models gain traction for new market entrants.
End User:
The application complexity and unique service delivery models define the Digital BSS requirements across different end-user industries.
- Telecommunications:Mobile network operators and internet service providers deploy BSS to manage a wide array of consumer and enterprise services, including voice, data, and value-added offerings. The pivot to enterprise and IoT services drives demand for flexible monetization platforms.
- Utilities:Energy, water, and gas providers utilize BSS for customer billing, usage tracking, and service provisioning, often integrating with smart meter infrastructure. Smart grid initiatives in the United States necessitate robust billing and customer management.
- Media:Content providers and broadcasters use BSS for subscription management, content monetization, and audience engagement.
- Transportation:Logistics and public transit companies implement BSS for ticketing, payment processing, and fleet management services.
Telecommunications is the primary revenue contributor, with Utilities showing substantial expansion.
Technology:
The maturity and direct impact on operational efficiency shape the adoption of specific technologies within Digital BSS platforms.
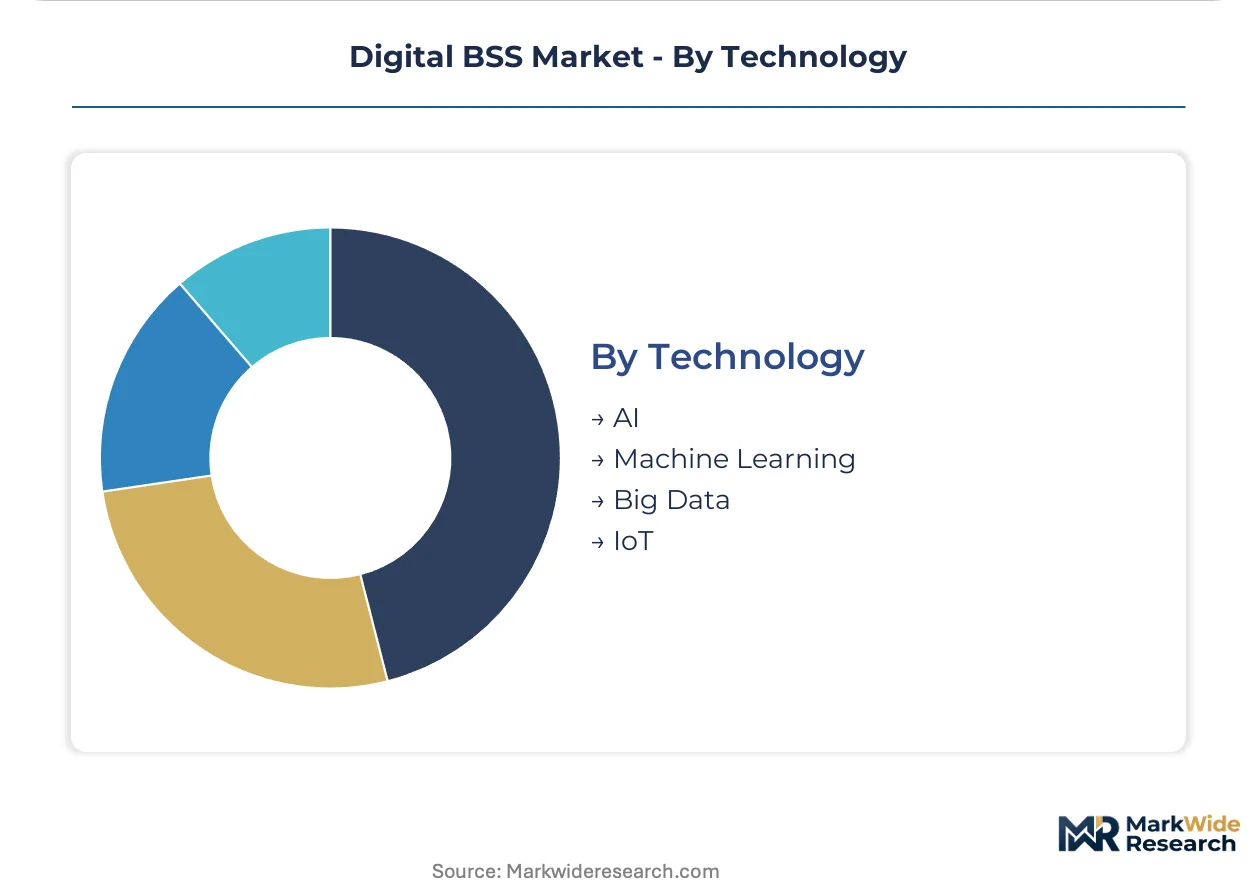
- AI:Artificial intelligence capabilities are embedded into BSS for predictive analytics, personalized customer offers, and automated decision-making processes. AI-powered operations enhance fraud detection and churn analysis for telecom operators.
- Machine Learning:Algorithms learn from historical data to optimize pricing, segment customers, and automate routine tasks within billing and customer management systems. Hyper-personalized marketing campaigns benefit significantly from machine learning.
- Big Data:This technology handles the massive volumes of customer and network data generated, enabling comprehensive analysis for business insights.
- IoT:Internet of Things integration within BSS supports the management and billing of connected devices and M2M communication services.
AI is the innovation focus, with Big Data enabling foundational capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for Digital BSS solutions is pronounced in markets undergoing rapid telecommunications infrastructure upgrades and regulatory shifts. These regions require advanced systems to manage complex service monetization and customer relationships. Operators in these areas prioritize solutions that offer scalability and compliance. The global market reflects varying levels of BSS modernization driven by distinct regional pressures.
India
Massive subscriber growth and intense market competition drive significant demand for modern Digital BSS in India. The Telecom Regulatory Authority of India (TRAI) mandates transparent billing and customer service, compelling operators to upgrade systems. Key telecom hubs like Delhi-NCR and Bengaluru are seeing substantial investment in cloud-native BSS platforms to support 5G rollout and new digital services.
United States
The United States market sees demand for Digital BSS solutions driven by smart grid initiatives and edge computing monetization. The Federal Communications Commission (FCC) enforces strict rules on billing transparency and customer communications. Technology clusters in Silicon Valley and Seattle are centers for BSS innovation, focusing on AI-powered operations and microservices architectures.
Germany
Germany's Digital BSS adoption is shaped by the need for advanced customer management and strict data sovereignty requirements. The European Union's GDPR heavily influences data handling and privacy within BSS platforms. Major industrial centers such as Munich and Berlin are investing in cloud-based BSS to support enterprise IoT and private 5G networks.
Japan
Japan exhibits strong demand for Digital BSS to manage 5G network slicing and complex enterprise IoT ecosystems. The Ministry of Economy, Trade and Industry (METI) promotes digital transformation across industries, impacting telecom operators. Metropolitan areas like Tokyo and Osaka are at the forefront of deploying agile monetization platforms for new digital services.
United Kingdom
The United Kingdom market prioritizes Digital BSS for modernizing legacy systems and ensuring compliance with data protection laws. The Information Commissioner's Office (ICO) enforces GDPR regulations, necessitating robust data privacy features in BSS. London and Manchester serve as innovation hubs for digital service providers, driving adoption of flexible billing and customer experience solutions.
Digital BSS Market Key Industry Players
North American and European producers anchor one tier, while Asian specialists hold another in the Digital BSS market. The market structure is characterized by a mix of established telecommunications vendors and specialized software providers. Strategic archetypes include comprehensive suite providers, cloud-native innovators, and system integrators. Dominant competitive moves involve strategic partnerships to expand solution portfolios and geographic expansion into emerging markets.
Dedicated BSS specialists like Amdocs Limited and Netcracker Technology Corporation represent a significant segment, focusing on advanced customer experience and network monetization. Oracle Corporation exemplifies a major technology vendor leveraging its cloud infrastructure to offer cloud-native BSS applications. These companies are continually evolving their platforms to support dynamic 5G services and complex partner ecosystems, addressing the telecommunications industry's pivot towards enterprise and IoT solutions. Their offerings often emphasize open APIs and microservices architectures to facilitate integration with diverse network functions.
| Leading Market Players |
|---|
| Nokia Corporation |
| Accenture plc |
| Amdocs Limited |
| Capgemini SE |
| Oracle Corporation |
| Huawei Technologies Co., Ltd. |
| Netcracker Technology Corporation |
| CSG Systems International, Inc. |
| Telefonaktiebolaget LM Ericsson |
| Others |
Cost & Logistics Intelligence
Venture-backed cloud-native innovators influence pricing by offering subscription models, which contrasts with established vendors' project-based pricing, affecting market entry and service delivery.
Pricing Analysis
Volume placements in core billing services offer lower per-unit margins, while specialized customer management solutions command higher value. Pricing models range from SaaS-tiered subscriptions for cloud-native solutions to project-based licensing for on-premises deployments. Customization level and after-sales integration services drive significant price differentiation. Pricing softness reflects intense competition and operator budget constraints for large digital transformations. Greenfield operators in emerging markets exhibit the most price sensitivity, while established operators prioritize migration risk reduction over initial cost for complex legacy system upgrades.
Supply Chain Analysis
Single-source vulnerability sits with the specialized talent pools for cloud-native development and microservices architecture, particularly in technology hubs like Silicon Valley and Bengaluru. The supply chain for Digital BSS relies heavily on skilled software engineers and the underlying hyperscaler cloud infrastructure providers. Cloud-native talent scarcity presents a structural risk, slowing development and deployment cycles. Distribution runs through direct sales channels for major vendors and strategic partnerships with system integrators for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital BSS market is evolving into a vertical-integration race, as vendors pursue deeper control over cloud infrastructure and AI-driven analytics to offer comprehensive, managed services.
For Market Incumbents: To counter the rapid market penetration of cloud-native innovators, established BSS incumbents must prioritize incremental modernization of their legacy stacks. Strategic partnerships with hyperscalers can accelerate cloud migration and reduce operational overhead. Investing in AI-powered operations within existing systems enhances customer experience and reduces churn, leveraging a named lever for R&D.
For New Entrants and Emerging Players: System integrators represent a critical channel for new entrants to penetrate the Digital BSS market. Focusing on greenfield operators in Southeast Asia and Africa offers a path to immediate cloud-native BSS adoption for specific enterprise IoT verticals. Offering highly modular, open API-based solutions reduces integration friction and accelerates time-to-market for new services through a SaaS model.
For Investors and Strategic Acquirers: Increased M&A activity targeting AI and microservices specialists is the leading indicator that the market is consolidating around advanced capabilities. The long-term viability of Digital BSS remains strong, driven by the ongoing shift to 5G and enterprise IoT monetization. Investors should seek cloud-native BSS providers demonstrating robust recurring revenue models and strong customer retention in competitive telecom markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Powered BSS Modules | Enhances predictive analytics and automation for telecom operators. |
| Platform Integration: Hyperscaler Cloud Partnerships | Accelerates cloud-native deployment and scalability for BSS solutions. |
| Strategic Partnership: Enterprise IoT Ecosystems | Unlocks new monetization avenues for complex M2M billing. |
| Acquisition of Specialist Firm: Microservices Expertise | Strengthens modular architecture and agile development capabilities. |
| Geographic Expansion: Emerging Markets Focus | Captures demand from greenfield operators bypassing legacy infrastructure. |
Research Approach
Regulatory filings from the FCC and TRAI, alongside industry association reports and academic research, formed the secondary backbone for this analysis. Primary interviews with CTOs, BSS product managers, and enterprise architects across telecom operators provided qualitative insights. This comprehensive data collection enabled robust bottom-up and top-down triangulation for market sizing and forecasting.
Historical trendline analysis, combined with regression models and scenario planning, underpinned the quantitative projections across the analysis window. The framework modeled segmentation dimensions including service type, deployment model, end-user, and technology adoption rates. Compound annual growth rates were derived from historical growth trends and projected market drivers such as 5G subscriber growth and enterprise IoT device activations.
Caveats apply where unforeseen regulatory changes or significant technological breakthroughs could materially shift the outlook for Digital BSS adoption. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Big Data Technology Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Database Management Platform Market
Digital Solutions
EHS Software Market
Digital Solutions
Global Website Builders Market
Digital Solutions
Digital Signage Market
Digital Solutions
Stylus Pen for Education Market