
 End User Experience Monitoring (EUEM) Market | 2026-2036
End User Experience Monitoring (EUEM) Market Size, Share, and Industry Trends Forecast 2026-2036
End User Experience Monitoring (EUEM) Market Foresight
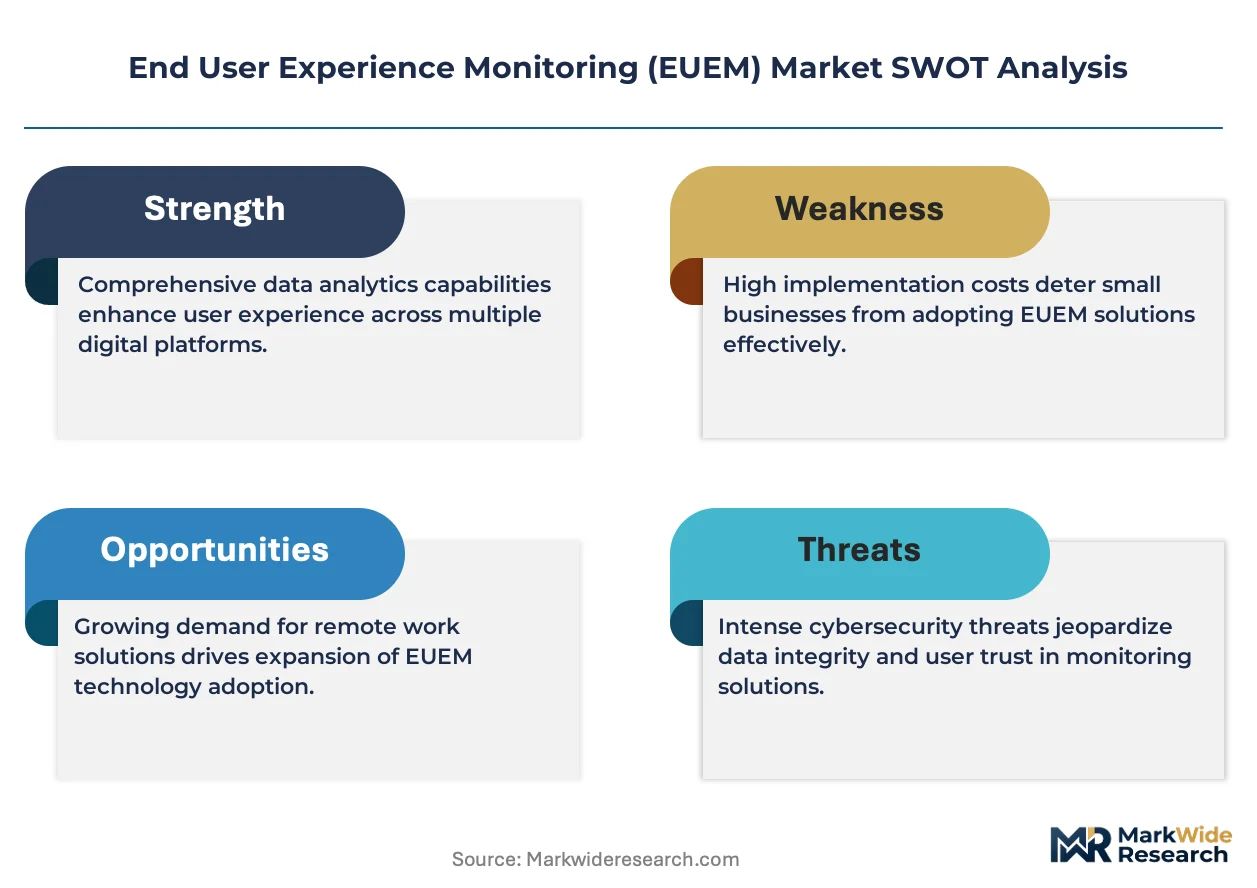
The capital-intensity divergence between full-stack observability platforms and point-solution specialists is unwinding traditional competitive boundaries. Dynatrace leverages its AI-driven Davis engine to sustain premium positioning in autonomous cloud operations. Datadog competes through aggressive platform bundling that anchors enterprise wallet share across infrastructure and application layers. Splunk differentiates via deep security analytics integration, occupying a hybrid niche where IT operations and cybersecurity budgets converge.
End User Experience Monitoring encompasses the continuous measurement, analysis, and optimization of application performance from the perspective of actual users rather than infrastructure metrics. The technology captures real-time session data, page-load times, API response latency, and error rates through browser agents, mobile SDKs, and synthetic probes to isolate degradation before business impact occurs. Cloud-Based deployment now leads expansion as enterprises abandon capital-heavy on-premises instrumentation, while Real-Time monitoring commands the highest margin pools by enabling immediate incident correlation. The Healthcare vertical shows concentrated growth potential where patient-facing portal reliability directly ties to reimbursement metrics and regulatory audit requirements.
FDA 21 CFR Part 11 and HIPAA Security Rule obligations in US healthcare compel EUEM vendors to maintain audit-grade telemetry trails and access controls. The EU AI Act and GDPR Article 32 data-processing standards shape European procurement specifications, particularly for synthetic monitoring tools that simulate user behavior. Stakeholders must weigh the trade-off between platform consolidation and specialized best-of-breed depth as buyer sophistication outpaces vendor roadmap delivery.
Market Dynamics
Cloud migration mandates under GDPR and sectoral data residency rules are tightening compliance requirements for EUEM vendors, forcing architectural redesigns of telemetry pipelines and customer data handling.
Growth Catalysts
- GDPR Article 32:Data-processing standards compel enterprises to deploy real-time session monitoring that demonstrates accountability for personal data flows across digital touchpoints.
- Financial services:Digital transaction integrity requirements accelerate EUEM adoption as payment processors seek sub-second anomaly detection for mobile banking applications.
- Synthetic monitoring probes:Proactive simulation of user journeys replaces reactive infrastructure alerts in healthcare patient portals where reimbursement ties to uptime metrics.
Market Restraints
- Data sovereignty fragmentation:Divergent national cloud localization laws in Germany, France, and Singapore force vendors to maintain redundant regional infrastructure, elevating operational overhead.
- Legacy APM substitution:Enterprises with sunk costs in infrastructure-centric observability platforms delay full EUEM replacement cycles despite functional gaps.
- Telemetry storage costs:Petabyte-scale session replay retention requirements under HIPAA and FDA 21 CFR Part 11 compress margins for cloud-native deployment models.
Strategic Opportunities
- India BIS and RBI mandates:Digital payment infrastructure reliability standards create procurement windows for EUEM vendors serving UPI and banking-as-a-service platforms.
- Edge computing convergence:Integration of EUEM agents with 5G MEC nodes enables millisecond-latency monitoring for autonomous vehicle HMI validation and industrial AR workflows.
- Outcome-based pricing:Vendors tie contract value to measurable business KPIs—cart abandonment reduction, support ticket deflection—unlocking enterprise budget reallocation from cost centers to revenue protection.
Industry Challenges
- Observability engineer scarcity:Shortage of professionals skilled in OpenTelemetry instrumentation and distributed tracing architecture slows enterprise implementation timelines.
- Multi-cloud integration complexity:Correlating user sessions across AWS, Azure, and GCP environments requires vendor-agnostic data models that strain existing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End User Experience Monitoring (EUEM) Market |
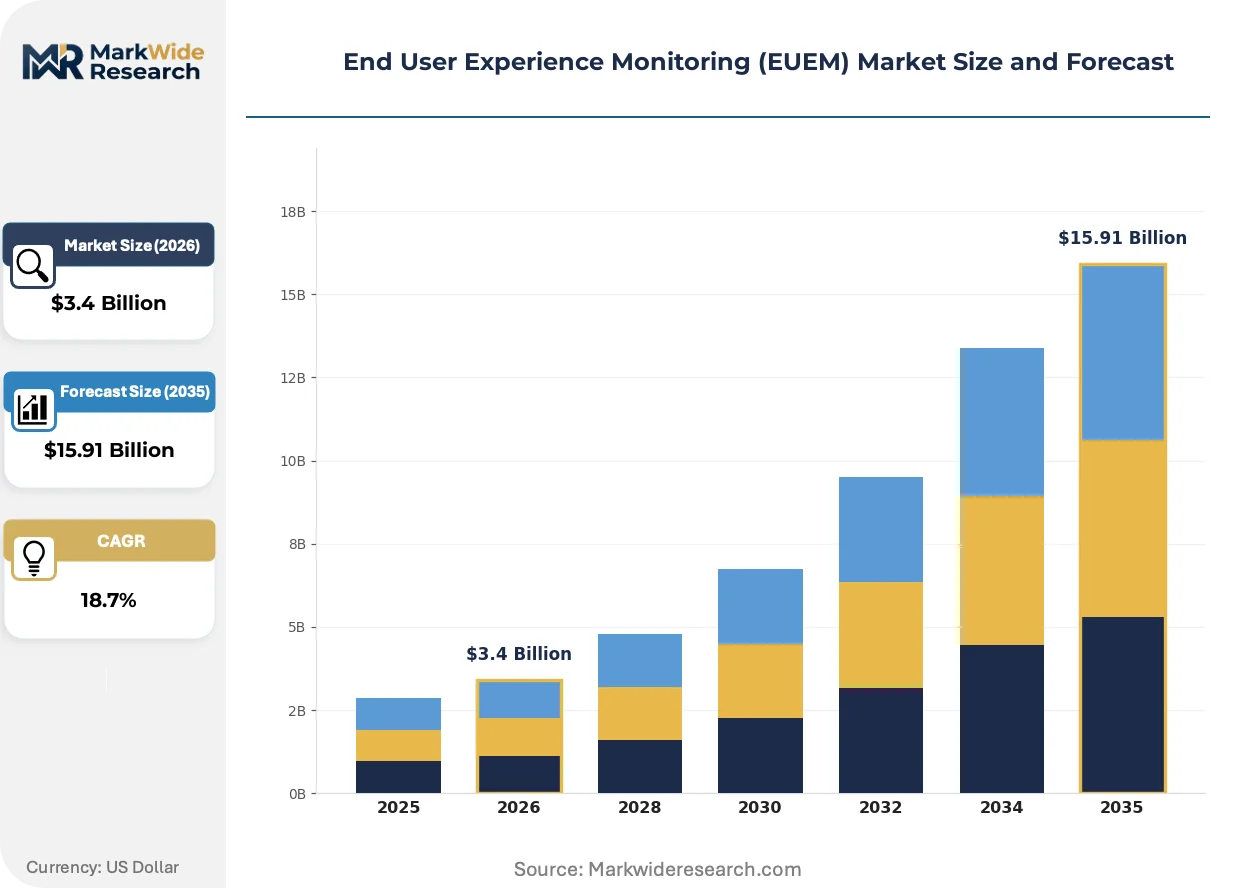
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $15.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User Type: Enterprise, SMB, Government, Education Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service Industry Vertical: Healthcare, Finance, Retail, Telecommunications Monitoring Type: Real-Time, Synthetic, User-Triggered, Performance |
| Companies Covered | AppDynamics, Catchpoint, Dynatrace, Instana, Dotcom Monitor, New Relic, Splunk, Honeycomb, Datadog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End User Experience Monitoring (EUEM) Market Shifts & Advancements
AI-driven root cause analysis is compressing mean-time-to-resolution metrics while browser-based session replay technology matures from diagnostic novelty to standard operational tooling.
OpenTelemetry is supplanting vendor-specific agent architectures as the dominant instrumentation standard. Cloud-native enterprises in SaaS and fintech verticals are mandating OTel-compliant telemetry pipelines in RFPs. This open-source convergence is eroding proprietary agent lock-in and commoditizing data collection layers while concentrating value in analytics engines.
EU AI Act risk classification rules are reshaping procurement specifications for synthetic monitoring tools that simulate user behavior. Vendors must now document algorithmic transparency and human oversight mechanisms for AI-powered anomaly detection. Healthcare and public sector buyers in Germany, France, and the Netherlands are inserting these compliance clauses into evaluation matrices ahead of enforcement deadlines.
Consolidated platform procurement is displacing point-solution best-of-breed strategies among Fortune 500 technology budgets. Infrastructure and application teams now share unified observability contracts that bundle EUEM with APM and security analytics. This pattern is most pronounced in United States federal digital modernization programs and large SaaS-native enterprises seeking vendor reduction.
End User Experience Monitoring (EUEM) Market Segmentation
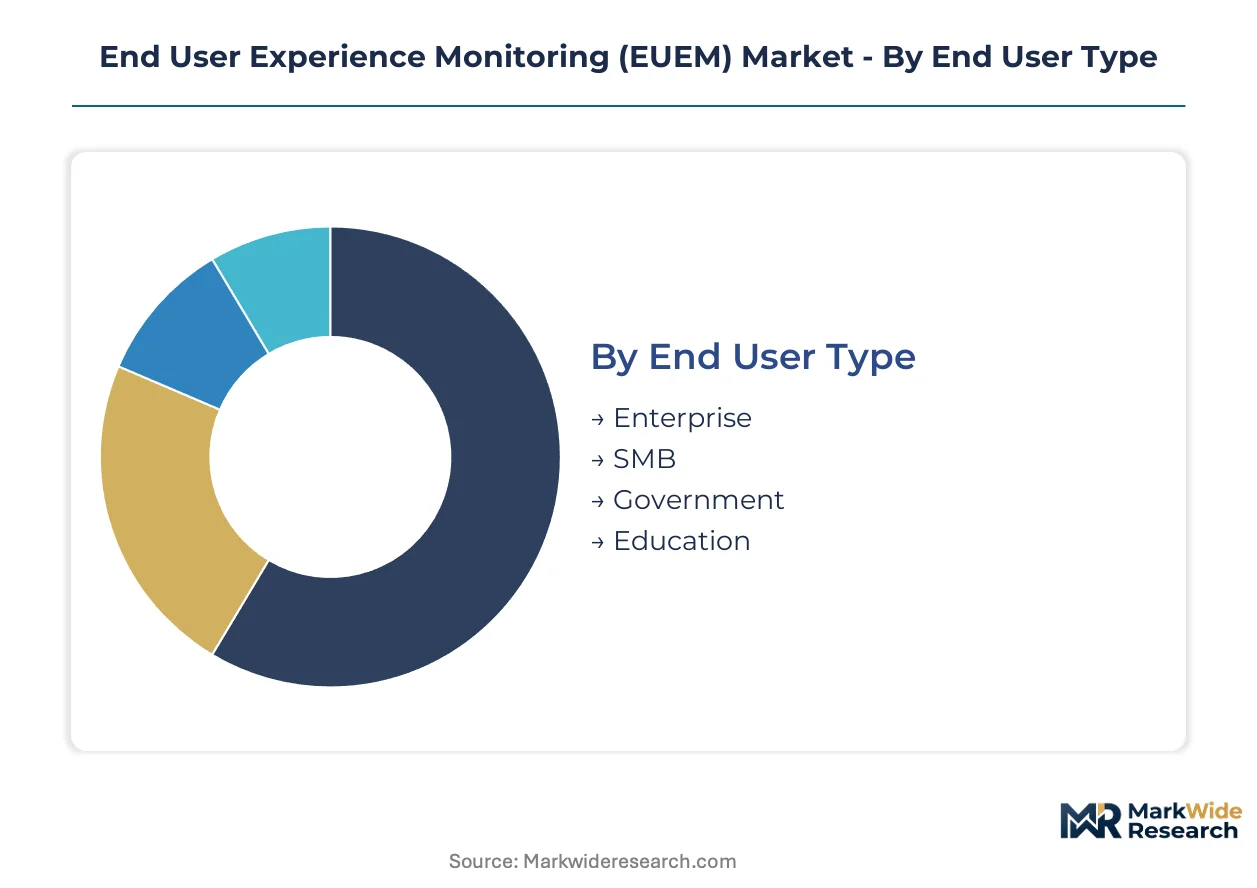
EUEM procurement patterns diverge sharply across organizational scale and technical maturity, with compliance mandates and cloud migration timelines reshaping how vendors prioritize segment-specific roadmaps. Understanding these fault lines reveals where platform consolidation yields to specialized point solutions.
End User Type:
Enterprise accounts anchor domestic revenue concentration across North American and Western European markets, while government and education segments export procurement specifications through multilateral framework agreements.
- Enterprise:Multi-divisional organizations deploy full-stack observability suites spanning thousands of endpoints, with procurement teams mandating FedRAMP or ISO 27001 certification as table stakes. Demand concentrates in United States federal digital modernization programs and German automotive conglomerates modernizing supply chain portals.
- SMB:Mid-market buyers favor SaaS-native EUEM tools with per-seat pricing and minimal configuration overhead. These organizations prioritize rapid deployment over customization, driving vendor investment in templated instrumentation for common application stacks.
- Government:Public sector procurement imposes stringent data residency and audit trail requirements, particularly under GDPR Article 32 and FedRAMP Moderate baselines. Contracts typically run through centralized IT frameworks that standardize vendor eligibility across agencies.
- Education:Universities and K-12 districts balance tight operational budgets against surging demand for reliable learning management systems. Procurement leans toward consortium purchasing agreements that aggregate volume across institutional networks.
Enterprise commands the established base. The steepest expansion runs through SMB.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from operational expenditure models favored by cloud-native entrants.
- On-Premises:Legacy financial institutions and defense contractors maintain air-gapped EUEM infrastructure to satisfy data sovereignty and classification requirements. These deployments carry high upfront license costs but eliminate recurring cloud egress fees for petabyte-scale telemetry retention.
- Cloud-Based:SaaS delivery dominates new logo acquisition, with vendors offering elastic scaling and regional tenancy options to address GDPR and sectoral localization mandates. Healthcare providers migrating patient portals to AWS and Azure drive concentrated demand for HIPAA-compliant cloud instrumentation.
- Hybrid:Organizations straddling legacy and modern infrastructure deploy edge collectors on-premises while streaming aggregated analytics to cloud control planes. This architecture satisfies mixed compliance environments without full cloud migration.
- Managed Service:Outsourced EUEM operations appeal to mid-market enterprises lacking in-house observability engineering expertise. Service providers assume responsibility for agent maintenance, alerting threshold tuning, and incident response playbook execution.
Cloud-Based deployments are gaining share fastest. On-Premises retains the highest contract values per account.
Industry Vertical:
Application criticality and regulatory exposure determine vertical-specific feature requirements and pricing tolerance.
- Healthcare:Patient-facing portal reliability directly ties to reimbursement metrics under CMS quality programs, with FDA 21 CFR Part 11 and HIPAA Security Rule compelling audit-grade telemetry trails. United States hospital systems and German telemedicine platforms represent concentrated procurement activity.
- Finance:Payment processors and mobile banking operators require sub-second anomaly detection to safeguard digital transaction integrity. EU AI Act risk classification rules are reshaping procurement specifications for synthetic monitoring tools in this vertical.
- Retail:E-commerce platforms prioritize cart abandonment reduction and checkout flow optimization, correlating EUEM data with revenue impact metrics. Seasonal traffic spikes drive demand for elastic monitoring capacity.
- Telecommunications:5G network operators integrate EUEM agents with MEC nodes to validate subscriber experience across distributed edge infrastructure. Indian telecoms responding to TRAI quality-of-service mandates represent an emerging demand pocket.
Healthcare commands premium pricing. Finance shows the steepest adoption velocity.
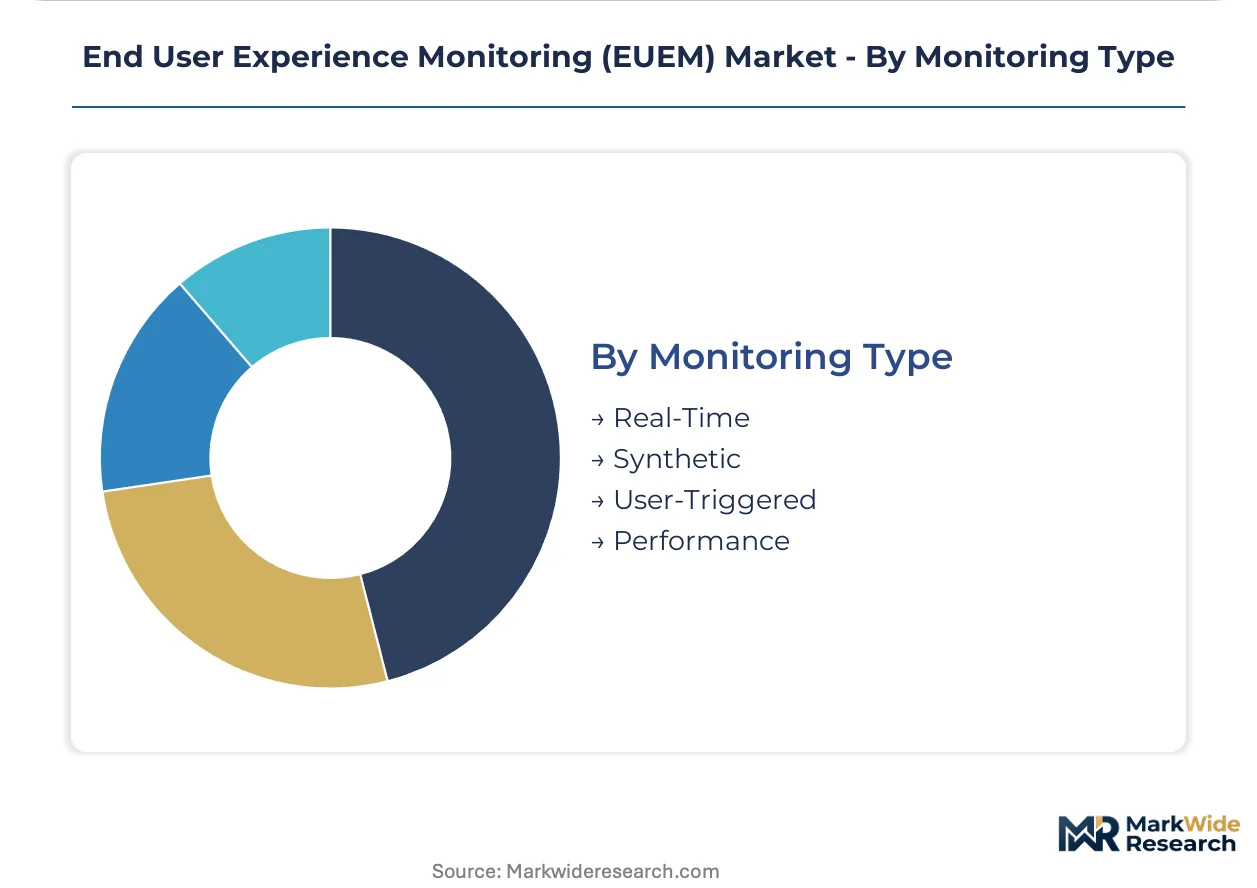
Monitoring Type:
Technical sophistication and operational use case separate reactive diagnostic tools from proactive prevention systems.
- Real-Time:Continuous stream processing of actual user sessions enables immediate incident correlation and automated escalation. These deployments command the highest margin pools by compressing mean-time-to-detection for revenue-critical applications.
- Synthetic:Scripted probes simulate user journeys across geographies and device profiles, identifying degradation before business impact. EU AI Act algorithmic transparency requirements are complicating vendor roadmaps for AI-powered anomaly detection in this category.
- User-Triggered:Feedback widgets and voluntary error reporting capture qualitative experience data that complements quantitative telemetry. These tools support support ticket deflection and product roadmap prioritization.
- Performance:Baseline and threshold-based monitoring focuses on page-load times, API latency, and resource utilization metrics without full session context. This category serves as entry-level instrumentation for organizations initiating EUEM programs.
Real-Time monitoring commands the established base. Synthetic is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where federal digital modernization programs sustain premium contract values, while German healthcare providers negotiate harder under constrained reimbursement frameworks. This asymmetry shapes vendor resource allocation across developed markets.
United States
Federal digital modernization programs and SaaS-native enterprise expansion drive concentrated demand. FedRAMP Moderate baselines and HIPAA Security Rule obligations compel audit-grade telemetry architectures. Hospital systems in the Boston-Cambridge corridor and Bay Area tech clusters deploy full-stack observability suites at scale.
Germany
Automotive conglomerates modernizing supply chain portals and telemedicine platforms represent dual demand vectors. GDPR Article 32 data-processing standards and sectoral data residency rules tighten compliance specifications. The Stuttgart-Munich industrial corridor anchors procurement for manufacturing-focused EUEM instrumentation.
United Kingdom
Financial services digital transaction integrity requirements accelerate adoption among payment processors and mobile banking operators. FCA operational resilience mandates intersect with EU AI Act risk classification rules for synthetic monitoring tools. London's fintech concentration drives sub-second anomaly detection procurement.
India
UPI infrastructure reliability standards and banking-as-a-service platform expansion create procurement windows. BIS and RBI mandates on digital payment infrastructure shape vendor qualification requirements. Mumbai and Bangalore tech clusters concentrate demand from fintech unicorns and legacy bank modernization programs.
Japan
5G MEC node integration for industrial AR workflows and autonomous vehicle HMI validation opens edge-computing convergence opportunities. METI guidelines on operational technology security influence procurement specifications. The Nagoya-Toyota manufacturing belt drives demand for millisecond-latency monitoring instrumentation.
End User Experience Monitoring (EUEM) Market Competitive Landscape
Concentration sits with full-stack observability platforms that bundle EUEM with infrastructure and security analytics, while point-solution specialists defend position through vertical depth. The vendor base stratifies across three tiers: premium platforms commanding enterprise wallet share, mid-market SaaS-native tools, and specialized synthetic monitoring boutiques. M&A activity targets telemetry pipeline capabilities and OpenTelemetry-compliant data collection layers. Geographic expansion into India and Southeast Asia represents the dominant competitive move alongside outcome-based pricing model adoption.
Within the premium platform tier, Dynatrace, Datadog, and Splunk exemplify divergent strategic positioning. Dynatrace represents autonomous cloud operations specialization through AI-driven root cause analysis. Datadog occupies the aggressive platform bundling archetype, anchoring enterprise contracts across layered infrastructure and application monitoring. Splunk sits within the hybrid niche where IT operations and cybersecurity budgets converge, differentiating through security analytics integration. These three vendors collectively illustrate how capital-intensity divergence between full-stack and point-solution approaches is unwinding traditional competitive boundaries in EUEM procurement.
| Leading Market Players |
|---|
| AppDynamics |
| Catchpoint |
| Dynatrace |
| Instana |
| Dotcom Monitor |
| New Relic |
| Splunk |
| Honeycomb |
| Datadog |
| Others |
Supply & Pricing Matrix
FedRAMP Moderate certification gates both vendor qualification and pricing power in the EUEM market, separating audit-grade providers from commodity SaaS entrants while compressing margins for those trapped in compliance retrofit cycles. HIPAA Security Rule obligations and GDPR Article 32 data-processing standards further stratify the vendor base, creating tiered access to healthcare and federal procurement channels that reward preemptive architectural investment.
Pricing Analysis
The customization-premium spread in EUEM separates configured-to-order deployments for defense contractors and hospital systems from standardized SaaS tiers targeting mid-market buyers. Subscription models dominate cloud-based delivery, with price differentiation driven by certification level (FedRAMP, HIPAA, ISO 27001) and data residency configuration. Cost compression in the standard tier intensifies as OpenTelemetry commoditizes data collection layers, while enterprise buyers with sunk legacy APM costs show acute price sensitivity compared to federal agencies with protected modernization budgets.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for EUEM platforms, with Ireland and Germany hosting regional tenancy nodes to satisfy GDPR localization mandates. Telemetry pipeline software draws from distributed engineering talent pools in India and Poland, while specialized synthetic monitoring probes source from precision hardware manufacturers in Taiwan and Japan. Single-source vulnerability concentrates in hyperscaler compute dependencies, as AWS, Azure, and GCP control the substrate for elastic scaling. Distribution runs through direct enterprise sales teams for large accounts and cloud marketplaces for self-service adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OpenTelemetry's emergence as the dominant instrumentation standard signals a platform-economics inflection, where interoperability commoditizes data collection and concentrates value in analytics engines and compliance-certified control planes.
For Market Incumbents: Secure telemetry pipeline differentiation through preemptive OpenTelemetry-native architecture, insulating against agent-replacement cycles that threaten proprietary lock-in. Invest in FedRAMP and HIPAA certification depth to defend federal and healthcare wallet share from cloud-native challengers. Vertical integration into edge computing instrumentation for 5G MEC deployments offers upstream control over emerging latency-sensitive use cases. For New Entrants and Emerging Players: Anchor in the SMB segment's unmet demand for templated, low-configuration EUEM tools that bypass the observability engineer scarcity constraining enterprise implementations. Target Indian fintechs and banking-as-a-service platforms responding to RBI infrastructure reliability mandates, where incumbent platform bundling has left white space for specialized synthetic monitoring. A channel partnership route through hyperscaler marketplaces accelerates discovery without field sales overhead. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy APM vendors with stranded healthcare and federal customer relationships but outdated agent architectures. Long-term viability hinges on OpenTelemetry compliance and AI-driven root cause analysis capabilities as table stakes. Watch for inflection in outcome-based pricing adoption, where vendors tie contract value to measurable KPIs like cart abandonment reduction or support ticket deflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates EUEM with APM and security analytics to capture unified observability budgets. |
| Acquisition of Specialist Firm | Adds vertical depth in healthcare or financial services compliance certification. |
| Geographic Expansion | Establishes regional tenancy in India and Southeast Asia to capture BIS and RBI-mandated demand. |
| Strategic Partnership | Aligns with hyperscaler marketplaces to reduce customer acquisition costs in the SMB segment. |
| Product Launch | Introduces OpenTelemetry-native pipelines to preempt agent commoditization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and regulatory enforcement databases, combining interviews with CTOs, IT procurement officers, platform engineers, and observability specialists across SaaS, fintech, and healthcare verticals. Bottom-up sizing of vendor-reported deployments and top-down triangulation against enterprise software spending patterns validate volume estimates.
Segmentation dimensions modeled span deployment model, organization size, industry vertical, monitoring type, and regional regulatory cluster across the projection horizon. CAGRs derive from fitted growth curves calibrated to cloud migration timelines and compliance enforcement schedules, with sensitivity analysis around OpenTelemetry adoption velocity and observability engineer labor market constraints.
Material uncertainties — regulatory enforcement delays, hyperscaler pricing volatility, and synthetic monitoring algorithm classification under EU AI Act rules — sit outside the modeled envelope. Forecasts reflect documented assumptions about cloud-native enterprise expansion and federal digital modernization program continuity. Recalibration cycles align with material shifts in GDPR Article 32 interpretation and BIS infrastructure reliability mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Voting System Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Web Content Management Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Utility Cases Market
Digital Solutions
Global Metadata Management Tools Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Data Converter Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Product As a Service Market
Digital Solutions
Cloud MFT Services Market