
 Electronic Document Management System (EDMS) Market | 2026-2036
Electronic Document Management System (EDMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Document Management System (EDMS) Market Analysis
Cloud-native architecture is reconfiguring how Electronic Document Management Systems are deployed and consumed across enterprises. OpenText leverages extensive partner ecosystems to sustain enterprise-grade content services at scale. Laserfiche anchors its position through deep workflow automation specialization in government and education sectors. DocuWare competes aggressively in European mid-market manufacturing with modular, industry-specific configurations.
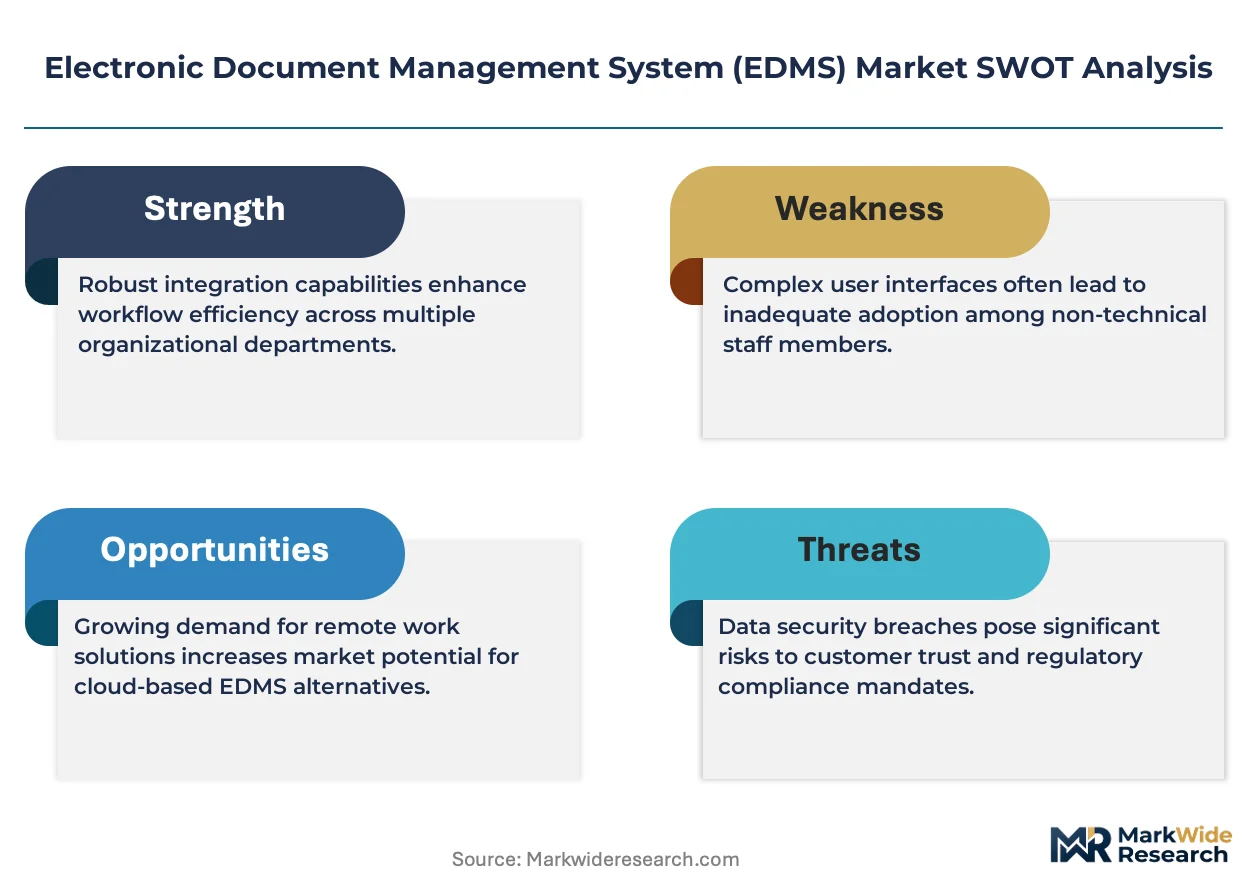
An Electronic Document Management System is a software platform that digitizes, indexes, stores, retrieves, and governs documents through centralized repositories with version control, metadata tagging, and role-based access protocols. Its primary commercial purpose is eliminating paper-based inefficiencies while enforcing audit-ready compliance across regulated industries. Cloud-Based deployment leads segment expansion as organizations abandon capital-intensive on-premise infrastructure for subscription scalability. Healthcare dominates end-user demand as hospitals integrate EDMS with electronic health record systems to satisfy HIPAA and Joint Commission documentation requirements. Workflow Management solutions capture concentrated margin pools by reducing manual routing delays in legal and financial services environments.
FDA 21 CFR Part 11, HIPAA, and the EU AI Act collectively shape product standards by mandating electronic signature validity, protected health information safeguards, and algorithmic transparency in automated document classification. Compliance Management applications absorb disproportionate R&D investment as vendors engineer pre-built regulatory templates for life sciences and legal sectors. Stakeholders must weigh interoperability commitments against the risk of vendor lock-in as platform consolidation accelerates across enterprise software stacks.
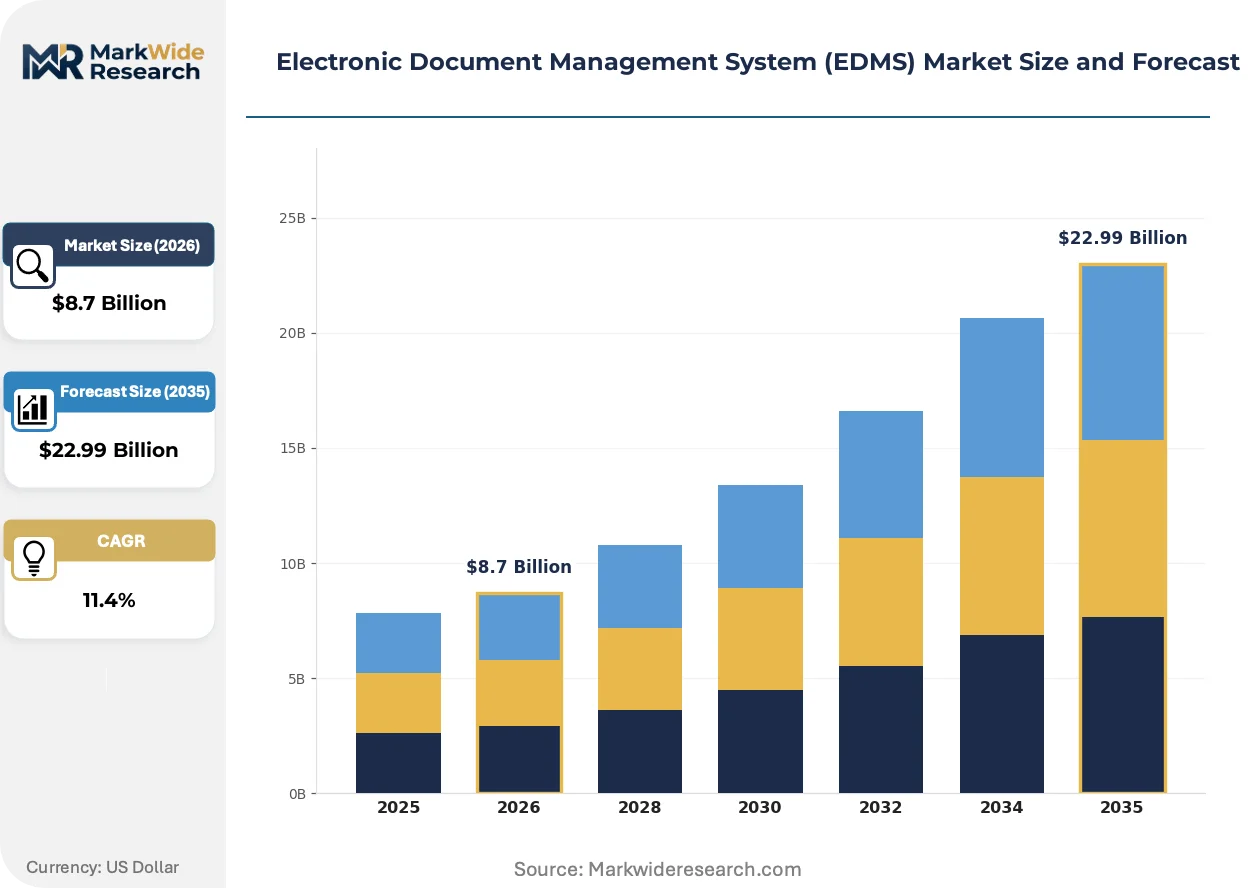
Market Dynamics
Cloud migration mandates from enterprise IT departments are forcing document management vendors to re-architect legacy platforms for containerized deployment, eliminating perpetual license revenue streams in favor of consumption-based pricing models.
Growth Catalysts
- HIPAA Compliance Pressure:US healthcare systems face escalating audit scrutiny for patient record accessibility, driving replacement of paper-based filing with searchable digital repositories.
- EU AI Act Algorithmic Transparency:Automated document classification systems in European financial services must now maintain explainable decision trails, creating upgrade cycles for legacy EDMS installations.
- German Industrial Digitization:Mittelstand manufacturers in Baden-Württemberg and Bavaria are consolidating quality documentation into centralized platforms to satisfy automotive OEM supply chain requirements.
Market Restraints
- Data Sovereignty Fragmentation:Conflicting localization requirements between GDPR, China's PIPL, and Russia's data localization laws force vendors to maintain redundant infrastructure stacks.
- Legacy System Entrenchment:Decades of on-premise SharePoint and IBM FileNet deployments create technical debt that delays cloud migration timelines by 18-36 months in Fortune 500 accounts.
- Cybersecurity Insurance Costs:Ransomware attacks against document repositories have spiked premiums for cyber liability coverage, squeezing margins for mid-market SaaS providers.
Strategic Opportunities
- India PLI Scheme Alignment:Pharmaceutical manufacturers qualifying for production-linked incentives must demonstrate digitized batch records, opening EDMS deployment opportunities in Hyderabad and Ahmedabad clusters.
- Blockchain-Anchored Audit Trails:Convergence of distributed ledger technology with document versioning creates tamper-evident compliance records for life sciences quality systems.
- Embedded AI Document Extraction:Natural language processing integration with EDMS workflows enables automated metadata tagging for legal discovery and contract analysis applications.
Industry Challenges
- Information Governance Skill Scarcity:Organizations lack personnel capable of designing retention schedules that satisfy simultaneous litigation hold requirements and privacy deletion mandates.
- Interoperability Certification Burden:Achieving HL7 FHIR connectivity for healthcare EDMS requires 12-18 month validation cycles against multiple electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Document Management System (EDMS) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Remote End User: Healthcare, Legal, Education, Manufacturing Solution: Document Capture, Workflow Management, Records Management, Collaboration Tools Application: Compliance Management, Report Generation, Information Retrieval, Audit Trails |
| Companies Covered | DocuWare, OpenText, Microsoft SharePoint, Revver, Box, Adobe Document Cloud, Laserfiche, EisenVault, M-Files, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Document Management System (EDMS) Market Emerging Trajectories
Artificial intelligence is compressing document processing timelines from hours to seconds, while regulatory pressure accelerates platform consolidation among vendors capable of multi-jurisdiction compliance.
Containerized microservices architecture is virtualizing EDMS deployment models. Healthcare providers in the United States are adopting Kubernetes-orchestrated document services to achieve elastic scaling during patient intake surges. This shift is virtualizing the traditional boundary between content management and application infrastructure, enabling embedded document capabilities within clinical workflow tools.
The EU AI Act's risk-based classification system imposes documentation burdens on automated decision systems. Financial institutions deploying AI-powered contract analysis must maintain human-readable audit trails for algorithmic determinations. German banking regulators are requiring explainability features in document classification tools used for credit risk assessment.
Subscription consumption models are displacing perpetual licensing in enterprise procurement. Legal departments now prioritize usage-based pricing for e-discovery and matter management platforms. This pattern is most visible in London and New York financial services firms, where seasonal litigation volumes create demand for elastic document repository scaling.
Electronic Document Management System (EDMS) Market Segmentation
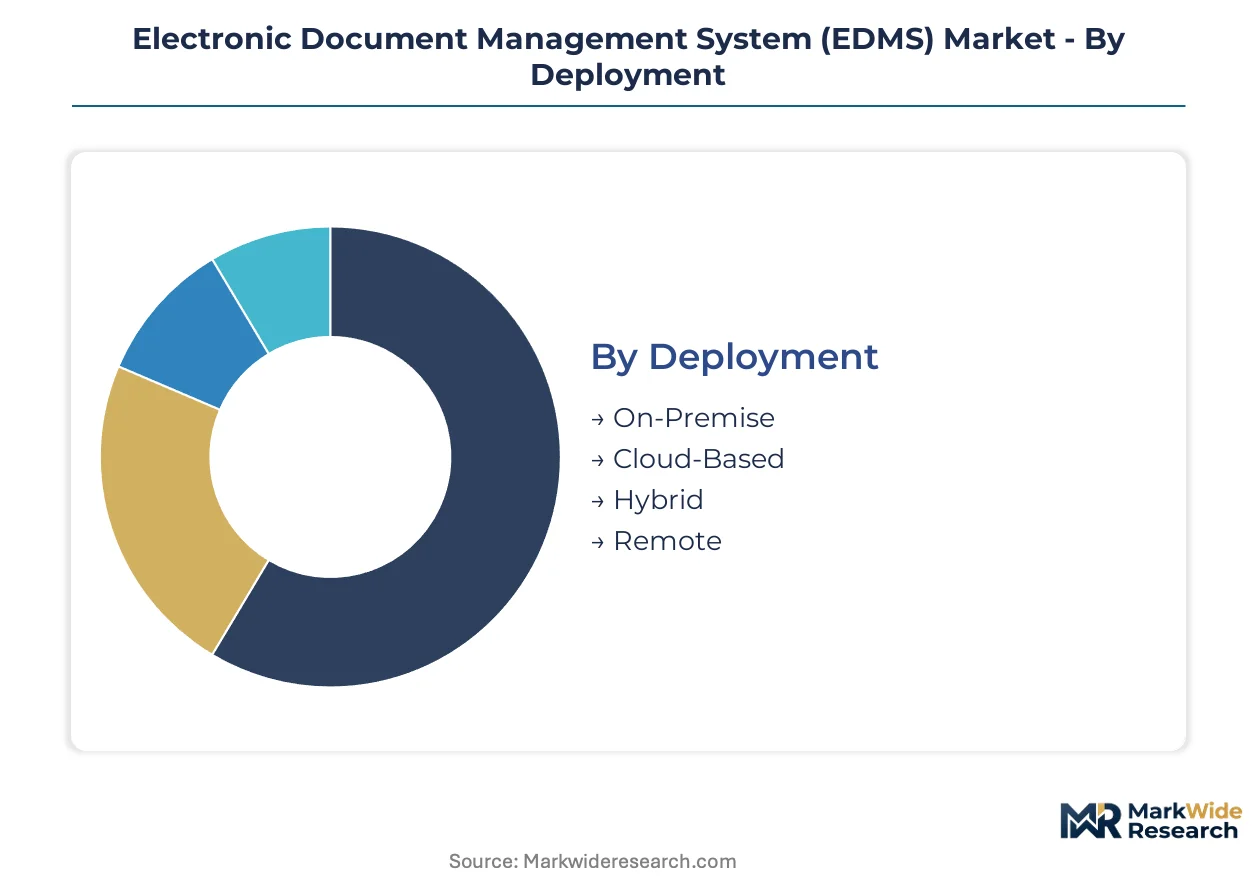
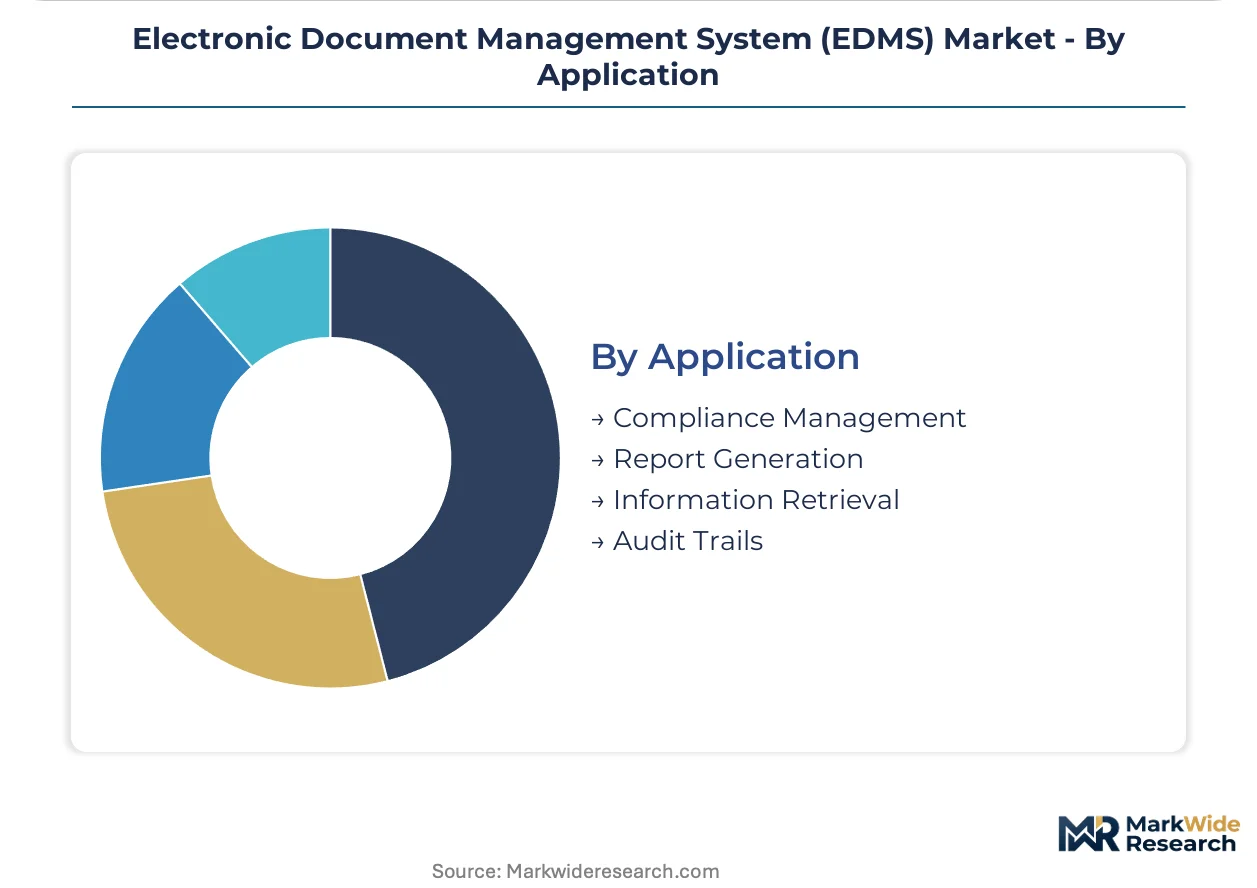
EDMS procurement patterns diverge sharply across deployment models, end-user industries, and functional applications. Understanding these fault lines reveals where vendors must architect specialized capabilities versus scalable platforms.
Deployment:
Use-case spectrum spans tightly controlled sovereign data environments to elastic consumption models serving distributed workforces.
- Cloud-Based:Multi-tenant SaaS architectures with API-first integration layers. US healthcare providers in Texas and Florida are migrating patient records to AWS GovCloud and Azure Government regions to satisfy HIPAA technical safeguards while eliminating capital expenditure cycles.
- On-Premise:Dedicated hardware installations with air-gapped network segmentation. German automotive suppliers in Stuttgart maintain on-premise document vaults to satisfy OEM contractual data residency clauses and TISAX certification requirements.
- Hybrid:Federated storage with policy-driven data placement across cloud and local repositories.
- Remote:Edge-deployed nodes synchronizing with central repositories over intermittent connectivity.
The dominant share belongs to Cloud-Based deployment, while Hybrid configurations are closing the gap fastest as regulated industries architect selective cloud migration paths.
End User:
Customer type determines compliance burden depth and workflow complexity tolerance.
- Healthcare:Clinical document lifecycle management with EHR interoperability mandates. Hospital systems in California and New York are consolidating radiology PACS, pathology reports, and discharge summaries into unified repositories to satisfy Joint Commission survey readiness.
- Legal:Matter-centric organization with litigation hold and privilege log automation. UK Magic Circle firms in London are deploying AI-powered contract analysis integrated with document management to accelerate due diligence timelines.
- Manufacturing:Quality system documentation with ISO 9001 traceability requirements.
- Education:Student record archives with FERPA privacy protections and alumni transcript services.
Healthcare commands the largest installed base, though Legal segment spending is expanding most quickly as e-discovery volumes and regulatory investigation activity intensify.
Solution:
Functional module selection maps directly to operational pain point severity and automation maturity.
- Workflow Management:Business process orchestration with conditional routing and SLA monitoring. Financial services firms in Singapore are implementing straight-through processing for loan documentation to compress approval cycles from weeks to hours.
- Document Capture:Intelligent ingestion with OCR, barcode recognition, and AI classification. Indian pharmaceutical manufacturers in Hyderabad are digitizing batch manufacturing records to qualify for PLI scheme incentives.
- Records Management:Retention schedule enforcement with legal hold and disposition automation.
- Collaboration Tools:Co-authoring, annotation, and external sharing with version control.
Workflow Management generates the highest margin contribution, while Document Capture is gaining share fastest as paper-to-digital transformation accelerates in developing markets.
Application:
Business outcome orientation separates compliance-driven procurement from efficiency-driven adoption.
- Compliance Management:Regulatory template libraries with audit trail generation and evidence packaging. Life sciences companies in Switzerland are deploying EDMS with pre-built FDA 21 CFR Part 11 validation documentation to accelerate system qualification.
- Audit Trails:Immutable activity logging with cryptographic integrity verification. French banking regulators through ACPR are mandating tamper-evident document histories for credit decision documentation.
- Information Retrieval:Federated search across siloed repositories with semantic relevance ranking.
- Report Generation:Automated assembly of regulatory submissions and management dashboards.
Compliance Management absorbs the deepest R&D investment, yet Audit Trails is climbing the fastest as EU AI Act explainability requirements propagate across financial services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers export digitized quality documentation to OEM assembly plants across the United States and China, establishing document interoperability standards that cascade through tiered supply chains worldwide.
United States
Hospital systems in Texas and Florida are migrating patient records to AWS GovCloud and Azure Government regions to satisfy HIPAA technical safeguards. The FDA enforces 21 CFR Part 11 requirements for electronic signatures in pharmaceutical manufacturing. Clinical document repositories in California consolidate radiology PACS, pathology reports, and discharge summaries to satisfy Joint Commission survey readiness.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria digitize quality assurance workflows to satisfy automotive OEM supply chain requirements. The EU AI Act mandates explainable audit trails for automated document classification systems. Stuttgart-based automotive suppliers maintain on-premise document vaults to satisfy TISAX certification and contractual data residency clauses.
India
Pharmaceutical manufacturers in Hyderabad and Ahmedabad clusters deploy EDMS to digitize batch manufacturing records for PLI scheme qualification. CDSCO aligns with international GMP standards for electronic documentation in drug production. Contract research organizations in Bangalore integrate document management with clinical trial management systems to accelerate regulatory submissions.
Switzerland
Life sciences companies deploy EDMS with pre-built FDA 21 CFR Part 11 validation documentation to accelerate system qualification. Swissmedic enforces stringent documentation requirements for pharmaceutical quality systems. Basel-area biotech firms anchor centralized document repositories to manage multi-jurisdiction regulatory submissions across FDA and EMA jurisdictions.
Singapore
Financial services firms implement straight-through processing for loan documentation to compress approval cycles from weeks to hours. The Monetary Authority of Singapore mandates tamper-evident record-keeping for digital banking operations. Marina Bay financial institutions deploy AI-powered contract analysis integrated with document management to accelerate due diligence timelines.
Electronic Document Management System (EDMS) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deployment models and compliance verticals. The vendor base organizes around three strategic archetypes: enterprise platform consolidators, vertical workflow specialists, and modular mid-market configurators. Dominant competitive moves include M&A activity targeting AI-powered document extraction capabilities and strategic partnerships with cloud infrastructure providers to accelerate containerized deployment.
Within the enterprise platform tier, OpenText and Microsoft exemplify channel-controlling positions through extensive partner ecosystems and native integration with productivity suites. DocuWare occupies a specialist position in European mid-market manufacturing with modular, industry-specific configurations. Laserfiche anchors the vertical workflow specialist archetype through deep automation specialization in government and education sectors.
| Leading Market Players |
|---|
| DocuWare |
| OpenText |
| Microsoft SharePoint |
| Revver |
| Box |
| Adobe Document Cloud |
| Laserfiche |
| EisenVault |
| M-Files |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States anchors margin distribution across the Electronic Document Management System value chain, with hyperscaler data center capacity in Virginia and Oregon determining where subscription revenue pools accumulate downstream.
Pricing Analysis
Legacy perpetual-license EDMS installations trade at steep discounts against cloud-native SaaS tiers, while AI-augmented document extraction modules command premium positioning above standard workflow configurations. Three-tier pricing structure across enterprise, professional, and entry-level segments separates HIPAA-validated healthcare deployments from basic departmental file sharing. Cost compression in mid-market SaaS tiers is intensifying because cybersecurity insurance requirements are forcing vendors to absorb compliance overhead. Healthcare provider networks exhibit the highest price sensitivity due to capital budget constraints, whereas legal services firms demonstrate elasticity tolerance for e-discovery acceleration features.
Supply Chain Analysis
Contract manufacturing for EDMS hardware appliances concentrates with Taiwanese EMS providers and Chinese server assembly facilities, though Indian software development centers are capturing implementation services volume. The supply chain draws from semiconductor components out of Taiwan and South Korea, enterprise storage systems from Ireland and Singapore, and specialized OCR scanning hardware from Japan and Germany. Single-source vulnerability in GPU acceleration chips for AI document classification creates procurement risk for vendors building automated extraction features. Distribution runs through direct enterprise sales forces for Fortune 500 accounts, while channel partners and systems integrators serve mid-market manufacturing and healthcare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic Document Management System adoption sits in early-cycle expansion, with cloud migration mandates from enterprise IT departments creating durable tailwinds for subscription revenue models across regulated industries.
For Market Incumbents: Entrench platform stickiness by embedding EDMS capabilities within electronic health record workflows through HL7 FHIR interoperability investments, insulating against best-of-breed workflow automation entrants. Deepen upstream control over AI document extraction training data pools to defend margin position against horizontal platform competitors.
For New Entrants and Emerging Players: Pursue white-space opportunity in Indian pharmaceutical manufacturing clusters, where PLI scheme compliance requirements are forcing batch record digitization ahead of established vendor penetration. Target Hyderabad and Ahmedabad contract manufacturers with modular, validation-ready configurations priced below enterprise SaaS tiers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical workflow specialists holding concentrated government and education sector positions. Five-to-ten year viability hinges on successful cloud architecture migration and AI capability integration. Watch FDA 21 CFR Part 11 enforcement intensity as inflection signal for life sciences EDMS upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Document Extraction Integration | Natural language processing compression reduces legal discovery timelines from weeks to hours. |
| Healthcare EHR Interoperability Partnership | HL7 FHIR connectivity satisfies Joint Commission survey readiness for hospital systems. |
| Blockchain-Anchored Audit Trail Development | Tamper-evident versioning meets EU AI Act explainability mandates for financial services. |
| India PLI Scheme Compliance Packaging | Pre-built CDSCO-aligned validation documentation accelerates pharmaceutical manufacturer adoption. |
| Containerized Microservices Architecture Migration | Kubernetes orchestration enables elastic scaling during patient intake surges for Texas health systems. |
Methodological Framework
Operator-level perspectives from hospital CIOs, legal department operations directors, pharmaceutical quality assurance managers, and manufacturing IT procurement leads anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EU AI Act regulatory texts, CDSCO GMP circulars, and hyperscaler cloud infrastructure disclosures. Bottom-up deployment modeling across cloud, on-premise, and hybrid configurations triangulated against top-down enterprise software spending pattern analysis.
Scenario-bracketing framed projections across conservative, baseline, and accelerated cloud migration pathways over the analysis window. Segmentation dimensions modeled include deployment architecture, end-user industry vertical, solution functional module, and application outcome orientation. CAGRs derived from fitted adoption curves incorporating HIPAA enforcement intensity, EU AI Act implementation timelines, and India PLI scheme qualification deadlines. Pricing elasticity assumptions calibrated against healthcare capital expenditure cycles and legal services litigation volume seasonality.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting healthcare capital budgets or cybersecurity insurance premium trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cloud infrastructure availability. Quarterly review of FDA inspection observation trends, EU AI Act delegated act publications, and Indian pharmaceutical export growth rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Clothing Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Australia ICT Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Utility App Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
Location As a Service Market
Digital Solutions
United States Contract Manufacturing Services Market