
 North America Data Center Rack Market | 2026-2036
North America Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Rack Market Insights
Aftermarket service revenue is reconfiguring margin capture across the North America data center rack value chain. Schneider Electric leverages its integrated power and cooling portfolio to anchor recurring service contracts alongside hardware shipments. Vertiv Group sustains engineering-intensive customization capabilities for hyperscale deployments. Eaton competes through electrical protection integration that extends rack-level value per unit.
Data center racks are standardized structural enclosures engineered to house, organize, and protect IT equipment, typically constructed from cold-rolled steel with load ratings between 1,500 and 3,000 pounds and conforming to EIA-310-D dimensional specifications for universal equipment mounting. Enclosed racks command premium positioning where thermal containment and physical security requirements dominate enterprise and financial services deployments. Open frame configurations lead volume shipments among cloud providers optimizing airflow density and cable management at scale. Wall-mounted and relay rack segments occupy narrower but defensible niches in edge computing and telecommunications closet environments where floor space constraints dictate form factor selection.
The U.S. Environmental Protection Agency administers ENERGY STAR certification frameworks that shape thermal efficiency benchmarks for rack-integrated equipment, while the National Electrical Code through the National Fire Protection Association governs grounding and power distribution safety standards that manufacturers must satisfy for market access. The Federal Communications Commission maintains electromagnetic interference thresholds that constrain rack-level shielding and cable routing designs. Stakeholders must monitor how state-level renewable energy mandates in Virginia, Texas, and Arizona reshape power density requirements and rack thermal specifications as data center operators pursue carbon-neutral operations commitments.
Market Dynamics
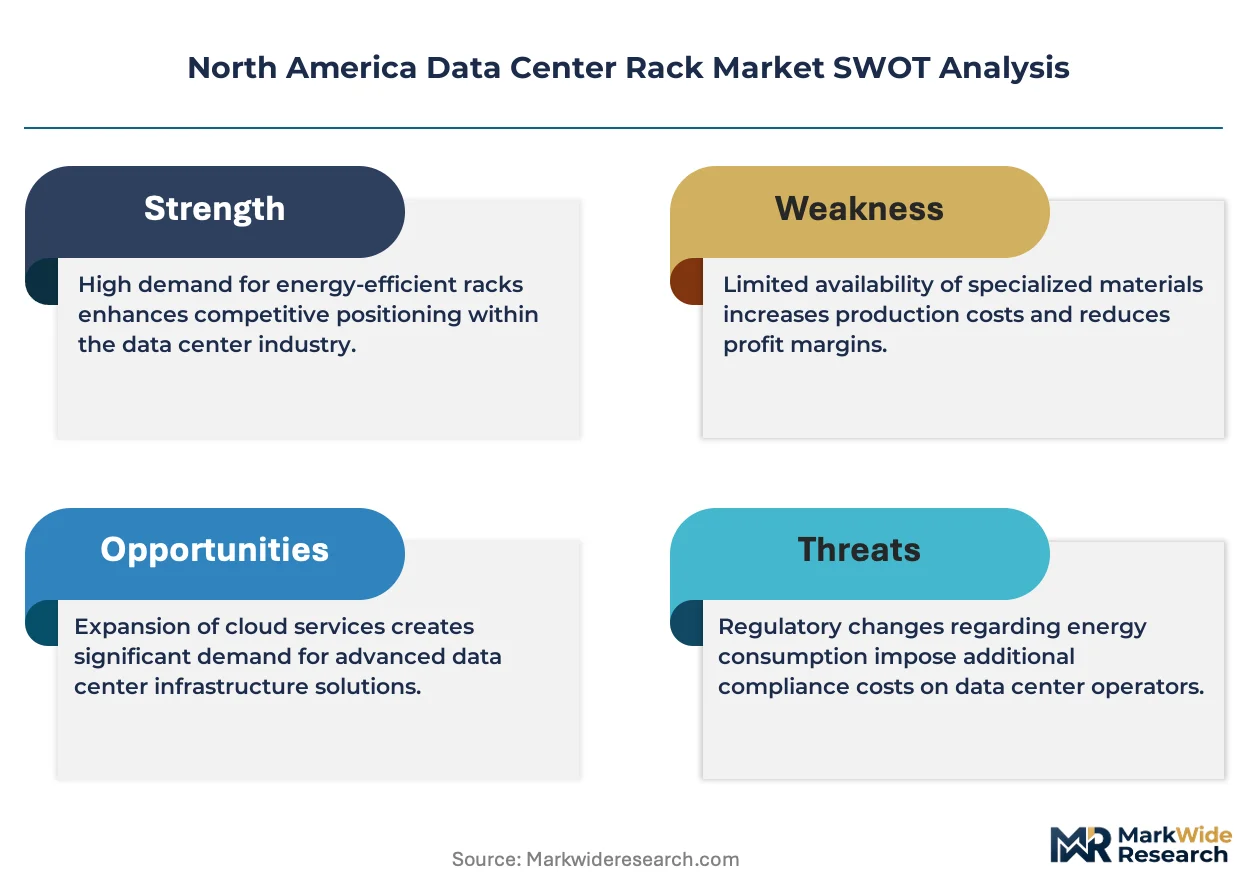
Hyperscale cloud providers are consolidating procurement power and dictating thermal density specifications that rack manufacturers must engineer around, compressing margins for standardized products while rewarding customized, high-performance enclosures.
Growth Catalysts
- ENERGY STAR Certification:The EPA's thermal efficiency benchmarks are compelling rack manufacturers to redesign airflow management and power distribution architectures to qualify for federal procurement eligibility.
- Hyperscale Facility Expansion:Northern Virginia's Data Center Alley now hosts utility-scale power commitments exceeding several U.S. states combined, driving concentrated demand for high-load-rated enclosures.
- Liquid Cooling Integration:Direct-to-chip and immersion cooling systems are requiring rack structures with integrated coolant distribution manifolds and sealed containment designs.
Market Restraints
- Steel Price Volatility:Cold-rolled steel input costs fluctuate with global commodity markets, squeezing fabrication margins for rack producers serving price-sensitive enterprise segments.
- Supply Concentration:Critical power distribution components and precision sheet metal fabrication capacity cluster in Mexico and select U.S. Midwest manufacturing corridors, creating geographic vulnerability.
- Physical Dimensional Constraints:EIA-310-D mounting standards limit structural innovation for non-standard equipment form factors emerging in specialized AI accelerator deployments.
Strategic Opportunities
- Edge Computing Infrastructure:Wall-mounted and relay rack configurations address space-constrained deployments in Texas and Arizona distributed computing nodes where traditional floor-standing enclosures prove impractical.
- State Renewable Mandates:Virginia's clean energy procurement requirements are creating demand for rack-integrated power monitoring and thermal optimization systems that demonstrate carbon footprint reduction.
- Modular Assembly Convergence:Prefabricated data center modules combining racks with power and cooling are enabling faster deployment cycles for cloud providers seeking rapid capacity scaling.
Industry Challenges
- Thermal Engineering Talent Scarcity:Rack manufacturers face acute shortages of computational fluid dynamics specialists capable of optimizing airflow for 50kW+ per-rack densities.
- Multi-Certification Timelines:Simultaneous UL, FCC, and state electrical code compliance processes extend product launch cycles by six to twelve months for new enclosure designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Rack Market |
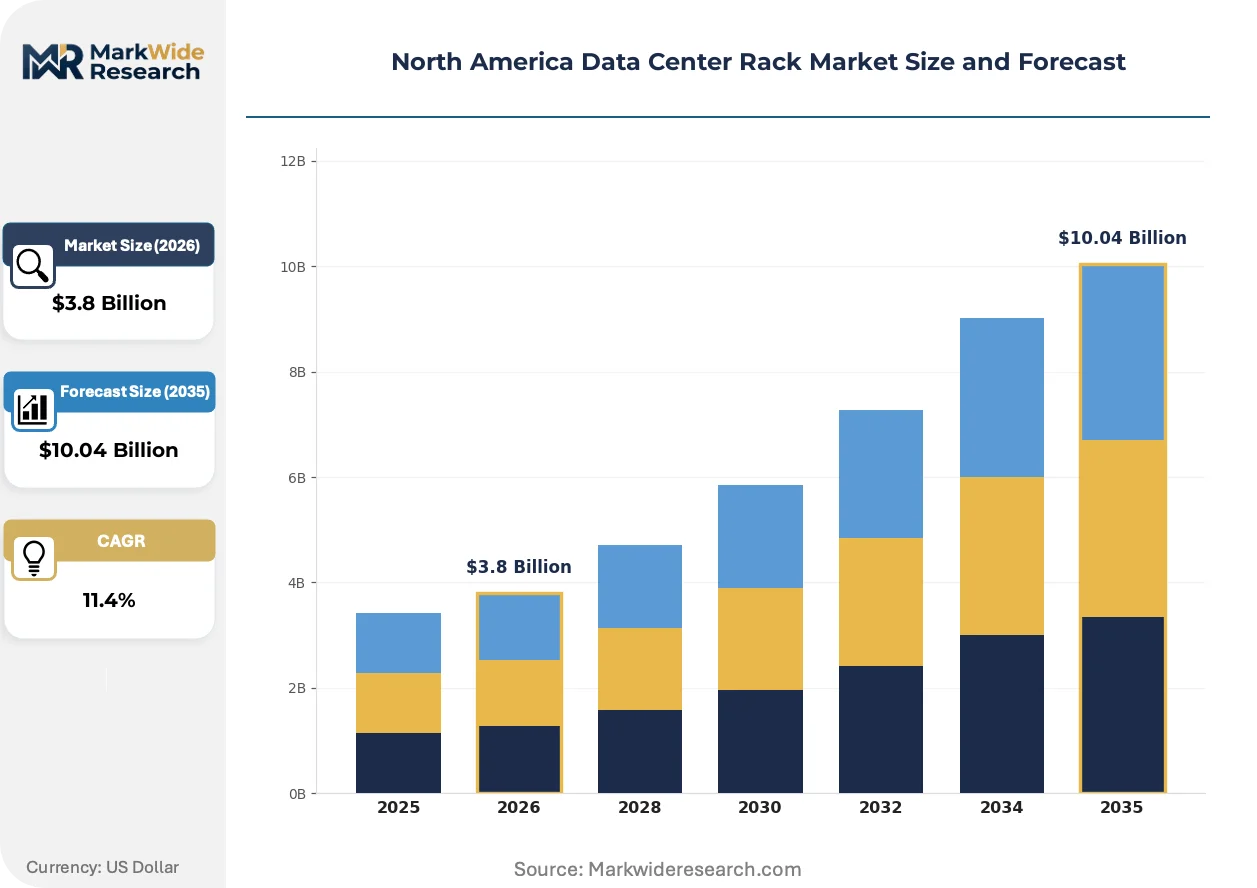
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Racks, Wall-Mounted Racks, Relay Racks Size: 42U, 45U, 48U, 24U Material: Steel, Aluminum, Wood, Plastic End User: Telecom, IT Service Providers, Enterprises, Cloud Providers |
| Companies Covered | Schneider Electric, Vertiv Group, Rittal, Eaton, Dell, Hewlett Packard Enterprise, Legrand, Chatsworth Products, nVent Electric, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Rack Market Trends and Innovations
Thermal management architectures and procurement specifications are diverging sharply between hyperscale cloud operators and traditional enterprise buyers, fragmenting product development priorities across the supply base.
Immersion-ready rack designs with sealed containment vessels and dielectric fluid compatibility are rendering obsolete conventional air-cooled enclosures for high-performance computing clusters. Cloud providers in Northern Virginia and Texas are specifying these systems for AI training workloads. The technology is rendering obsolete legacy raised-floor cooling paradigms that dominated data center construction for three decades.
The EPA's evolving ENERGY STAR server specification criteria are cascading into rack-level efficiency requirements that manufacturers must document through third-party testing. This regulatory pressure is accelerating adoption of blanking panels, brush-sealed cable entries, and hot-aisle containment systems. Financial services deployments in Illinois and New York are most affected, with procurement teams now mandating certified thermal performance documentation prior to vendor selection.
Hyperscale buyers are consolidating direct procurement relationships with rack fabricators, bypassing traditional distribution channels and systems integrators. This disintermediation compresses channel margins while rewarding manufacturers with in-house thermal engineering and rapid customization capabilities. The pattern is most visible in Northern Virginia, where cloud operators negotiate frame-level specifications directly with production facilities.
North America Data Center Rack Market Segmentation
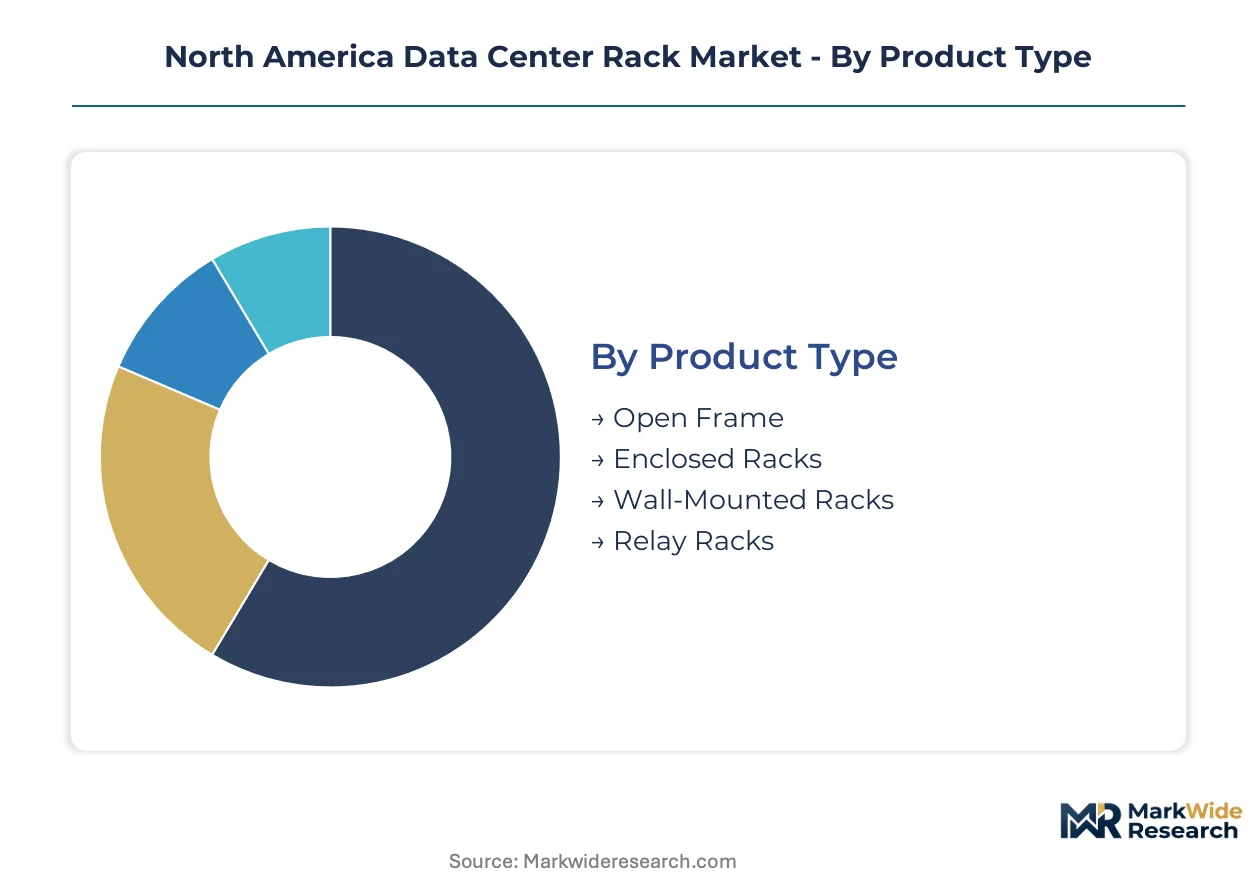
Data center rack segmentation in North America reflects divergent engineering priorities between hyperscale cloud infrastructure and legacy enterprise deployments. Rack manufacturers must balance thermal density specifications against structural cost constraints across four distinct product architectures. Material selection and unit height configurations further stratify procurement patterns between high-volume cloud contracts and specialized edge computing installations.
Product Type:
Mature configurations dominate volume shipments while emerging form factors capture specialized edge computing demand.
- Open Frame:Structural steel frames without side panels maximize airflow density for hyperscale cooling architectures. Cloud providers in Northern Virginia's Data Center Alley specify these units for AI training clusters where thermal optimization outweighs physical security requirements.
- Enclosed Racks:Cold-rolled steel cabinets with lockable doors and side panels integrate thermal containment systems for financial services deployments. Illinois and New York procurement teams mandate EPA ENERGY STAR thermal performance documentation prior to vendor selection.
- Wall-Mounted Racks:Compact enclosures address floor space constraints in Texas and Arizona edge computing nodes.
- Relay Racks:Two-post configurations serve telecommunications closet environments with reduced load requirements.
Open Frame handles the majority of throughput; Wall-Mounted Racks is the fastest mover on share.
Size:
Height configurations segment procurement patterns by power density tier and facility ceiling clearance constraints.
- 42U:The established height standard accommodates mainstream server form factors within standard data center ceiling plenums. Enterprise buyers in established facilities favor this configuration for equipment refresh cycles without infrastructure modification.
- 48U:Extended-height enclosures maximize vertical space utilization in new hyperscale construction. Cloud providers specify these units for greenfield Northern Virginia deployments where 15-foot ceiling heights support increased rack density.
- 45U:Intermediate sizing bridges legacy and high-density requirements.
- 24U:Reduced-height units fit constrained telecommunications and edge environments.
42U maintains dominant procurement volume; 48U is climbing the fastest as hyperscale construction accelerates.
Material:
Structural composition choices trade load-bearing capacity against weight reduction and corrosion resistance.
- Steel:Cold-rolled carbon steel delivers 1,500-3,000 pound load ratings required for high-density compute enclosures. Northern Virginia hyperscale contracts specify steel construction for structural integrity at 50kW+ thermal densities.
- Aluminum:Lightweight alloy construction reduces shipping costs and floor loading for multi-story facilities. Arizona edge computing deployments favor aluminum for seismic resilience and rapid installation.
- Wood:Limited specialty applications in acoustic dampening environments.
- Plastic:Non-conductive housings for electromagnetic-sensitive telecommunications equipment.
Steel commands procurement volume leadership; Aluminum is expanding most quickly in edge infrastructure.
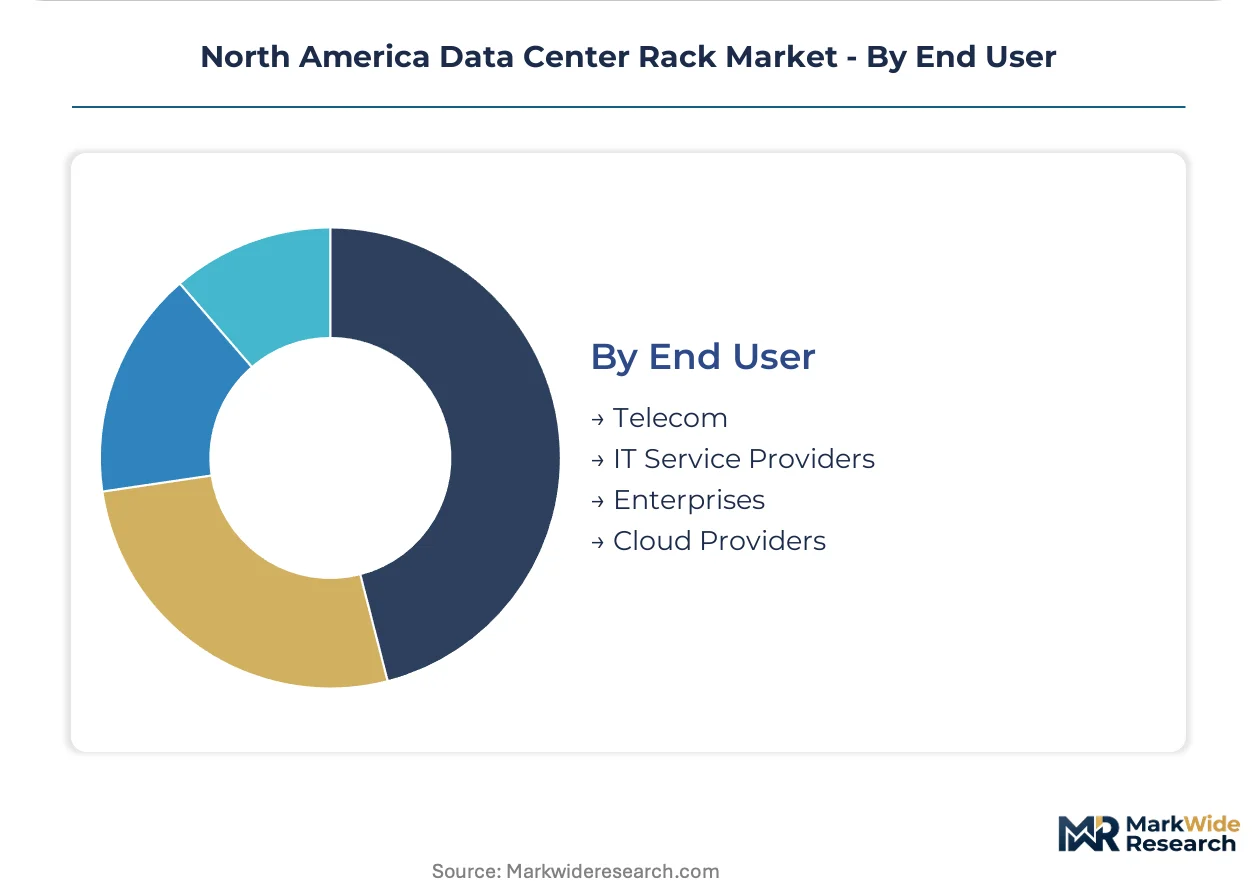
End User:
Customer type segmentation reveals divergent specification authority between consolidated cloud procurement and fragmented enterprise buying.
- Cloud Providers:Hyperscale operators consolidate direct fabrication relationships bypassing distribution channels. These buyers dictate custom thermal and cable management specifications for Northern Virginia and Texas facility expansions.
- Enterprises:Financial services and healthcare organizations prioritize ENERGY STAR certification and physical security integration. Illinois and New York procurement teams require documented thermal efficiency compliance.
- IT Service Providers:Colocation operators balance multi-tenant flexibility with standardized infrastructure.
- Telecom:Carrier networks specify relay and wall-mounted configurations for central office and cell site deployments.
Cloud Providers drive the steepest expansion trajectory; Enterprises maintain steady replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North America. Hyperscale cloud buyers in Northern Virginia negotiate frame-level specifications directly with fabricators, while enterprise procurement in secondary markets tolerates higher per-unit costs for certified thermal performance and local service coverage.
United States
Northern Virginia's Data Center Alley now hosts utility-scale power commitments exceeding several U.S. states combined, driving concentrated demand for 48U steel enclosures rated above 3,000 pounds. The EPA's ENERGY STAR certification requirements for data center equipment are pushing rack manufacturers toward thermal-optimized designs with documented airflow efficiency. Cloud providers in Ashburn and Manassas specify open-frame configurations for AI training clusters where cooling density outweighs physical security.
Texas
Austin and Dallas-Fort Worth hyperscale campuses are absorbing 48U extended-height enclosures for greenfield construction with 15-foot ceiling clearances. The state's independent grid operator ERCOT shapes power density planning as operators pursue renewable energy procurement under Texas renewable portfolio standards. Edge computing nodes in Houston and San Antonio favor wall-mounted aluminum racks where floor space constraints and seismic resilience requirements dominate specification.
Canada
Toronto and Montreal data center developments emphasize thermal containment for financial services and healthcare compliance with federal privacy regulations. Natural cooling advantages from northern latitudes reduce active cooling loads, allowing enclosed rack configurations with lower power usage effectiveness targets. Provincial renewable energy mandates in Ontario and Quebec are creating procurement preferences for rack-integrated power monitoring systems that demonstrate carbon footprint documentation.
North America Data Center Rack Market Competitive Landscape
Integrated power-cooling specialists and precision fabrication houses split the market between recurring service revenue models and hyperscale customization contracts. Schneider Electric leverages its integrated portfolio to anchor long-term service agreements alongside hardware shipments. Vertiv Group sustains engineering-intensive customization capabilities for direct cloud provider relationships. Eaton competes through electrical protection integration that extends per-unit value capture. Consolidation pressure is intensifying as hyperscale buyers bypass distribution channels, while regional fabricators invest in precision sheet metal capacity to serve edge computing demand.
Within the integrated systems tier, Schneider Electric, Vertiv Group, and Eaton exemplify divergent strategic positioning. Schneider Electric's French multinational structure supports global procurement leverage for thermal management components. Vertiv Group's U.S.-based engineering footprint aligns with hyperscale facility expansion timelines in Northern Virginia and Texas. Eaton's electrical protection heritage extends into rack-level power distribution integration. These three anchors represent the dominant competitive archetypes: full-stack integrated infrastructure, hyperscale customization specialists, and electrical-centric value extension.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group |
| Rittal |
| Eaton |
| Dell |
| Hewlett Packard Enterprise |
| Legrand |
| Chatsworth Products |
| nVent Electric |
| Others |
Pricing and Supply Chain Analysis
Cold-rolled steel fabrication capacity clusters in Mexico and the U.S. Midwest, anchoring margin capture for rack manufacturers who control precision sheet metal sourcing while hyperscale buyers squeeze hardware margins through direct procurement relationships.
Pricing Analysis
Aftermarket service contracts generate lifetime value multiples exceeding initial hardware sales. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels segments procurement by ENERGY STAR documentation requirements. Cost compression in standardized open-frame segments is intensifying because hyperscale buyers negotiate frame-level specifications directly with fabricators. Cloud providers in Northern Virginia exhibit lowest price sensitivity; enterprise financial services buyers in Illinois and New York tolerate premium pricing for thermal certification documentation.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Flex holding precision sheet metal capacity for rack fabrication. Mexico, the U.S. Midwest, and China supply cold-rolled steel inputs, power distribution components, and dielectric cooling manifolds. Single-source vulnerability runs through specialized coolant distribution hardware for immersion-ready designs. Distribution runs through direct manufacturer relationships with hyperscale operators, bypassing traditional systems integrators and channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through EPA ENERGY STAR certification and UL electrical compliance creates switching costs that protect incumbent positions against commoditization pressure.
For Market Incumbents: Harden certification moats by accelerating ENERGY STAR documentation capabilities and UL listing breadth to defend against emerging low-cost fabricators from Asia. Vertical integration into precision sheet metal capacity in Mexico insulates margin pools from steel price volatility. Channel control through direct service contracting with hyperscale operators locks out competitor access to Northern Virginia and Texas expansion timelines.
For New Entrants and Emerging Players: Establish a beachhead in wall-mounted aluminum rack configurations for Arizona and Texas edge computing nodes where hyperscale procurement concentration is weakest. White-space opportunity sits with modular prefabricated data center modules combining racks with integrated power and cooling for rapid deployment cycles. Go-to-market angle targets regional colocation operators seeking differentiated thermal monitoring documentation for state renewable energy mandate compliance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fabrication specialists holding Mexico-based capacity and hyperscale direct relationships. Long-term viability across a decade horizon favors targets with captive thermal engineering talent and ENERGY STAR testing infrastructure. Monitor hyperscale capital expenditure disclosure patterns as the inflection signal for rack procurement volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Immersive Cooling Integration | Sealed containment vessel designs for Northern Virginia AI training clusters displace legacy air-cooled infrastructure. |
| Precision Sheet Metal Capacity Expansion | Mexico-based fabrication footprint captures hyperscale direct procurement relationships bypassing distribution channels. |
| ENERGY STAR Certification Acceleration | Third-party thermal testing documentation satisfies Illinois and New York financial services procurement mandates. |
| Aftermarket Service Contract Anchoring | Recurring revenue streams from thermal optimization monitoring extend customer lifetime value beyond hardware shipment. |
| Modular Prefabricated Data Center Modules | Converged rack-power-cooling units enable Texas and Arizona cloud providers to compress deployment timelines. |
Research Methodology
The analysis maps open-frame, enclosed, wall-mounted, and relay rack configurations, each validated through data center facility engineers, procurement officers at hyperscale operators, thermal management specialists, and electrical contractors. Primary interviews with rack manufacturers, precision sheet metal fabricators, and cooling system integrators combined with secondary validation through EPA ENERGY STAR certification databases, UL listing directories, and hyperscaler capital expenditure disclosures. Bottom-up unit shipment estimates triangulate against top-down infrastructure investment forecasts.
Assumptions held fixed include EPA thermal efficiency benchmark continuity and EIA-310-D mounting standard persistence, while steel price volatility and hyperscale construction timelines varied across sensitivity scenarios. Segmentation dimensions modeled encompass product architecture, height configuration, material composition, and end-user procurement authority across the projection horizon. CAGRs derive from installed base replacement cycles and greenfield facility expansion patterns, with liquid cooling adoption curves and state renewable mandate enforcement intensity as key forecast inputs.
Sensitivities concentrate around steel commodity price spikes, hyperscale procurement consolidation acceleration, and EPA specification revisions. Forecasts reflect documented assumptions regarding thermal density trajectories and regulatory compliance timeline stability. Quarterly review of hyperscale capital expenditure announcements, ENERGY STAR specification updates, and Mexico-U.S. trade flow indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Poland Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Germany Data Center Construction Market